
 Asia-Pacific Primary Angle-Closure Glaucoma Market | 2026-2036
Asia-Pacific Primary Angle-Closure Glaucoma Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Primary Angle-Closure Glaucoma Market Outlook
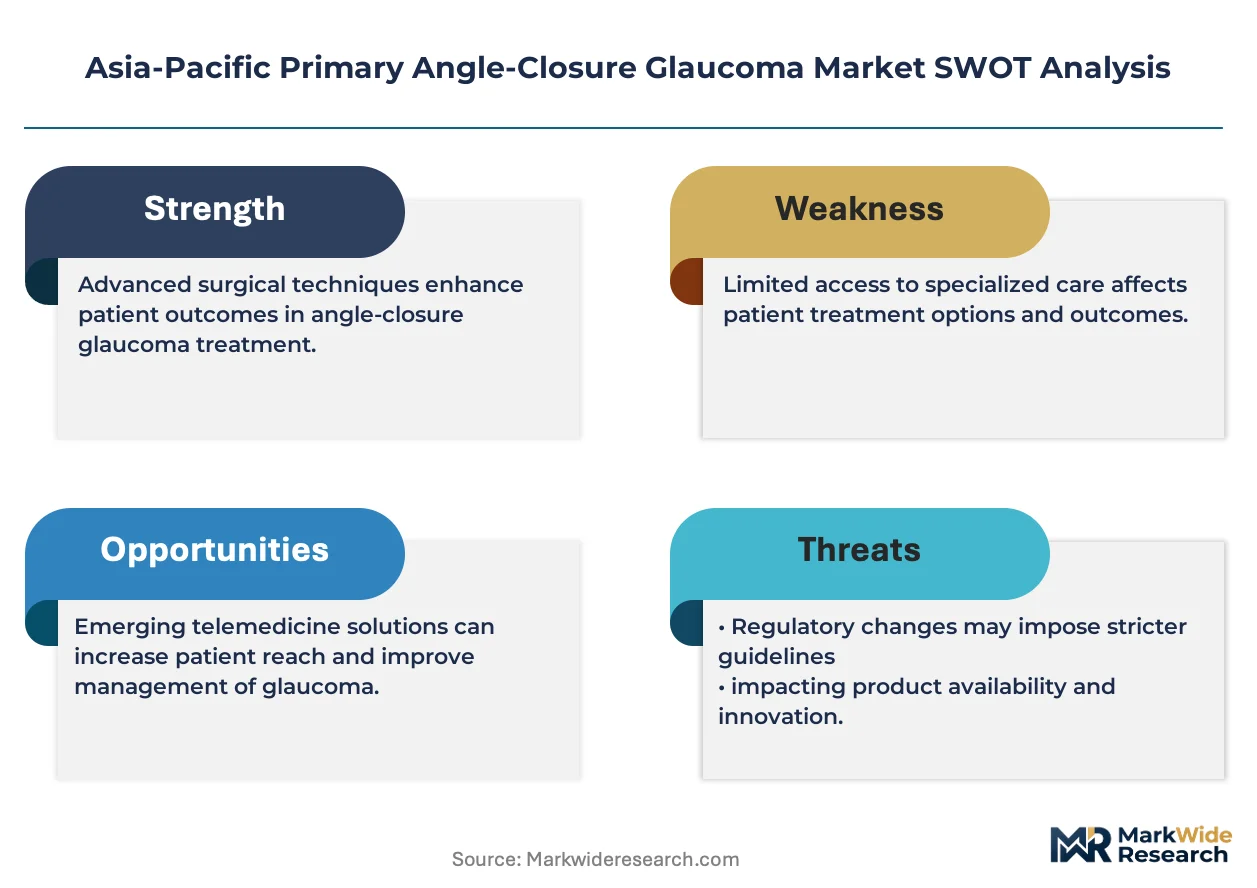
The EU Green Deal's influence on sustainable healthcare procurement is pivoting Asia-Pacific ophthalmology supply chains toward greener manufacturing audits. Novartis AG leverages its integrated R&D footprint across Singapore and Japan to sustain regional product registration leadership. Santen Pharmaceutical Co., Ltd. anchors its position through specialized distribution in East Asian hospital networks, while Alcon competes on diagnostic imaging technology depth.
Primary angle-closure glaucoma denotes an ocular condition where iris-cornea contact blocks aqueous humor outflow through the trabecular meshwork, elevating intraocular pressure above 21 mmHg and risking optic nerve damage; its clinical purpose centers on preventing irreversible vision loss through pressure modulation. Medication remains the dominant first-line intervention, though laser therapy segments are capturing expanded margin pools as clinics adopt selective laser trabeculoplasty protocols. Among end users, ophthalmology clinics lead procedural volume, while ambulatory surgical centers represent the fastest-growing site-of-care shift driven by reimbursement alignment and same-day discharge protocols.
Japan's PMDA, China's NMPA, and India's CDSCO collectively shape product standards through divergent clinical trial requirements and post-market surveillance obligations that extend registration timelines for multinational device manufacturers. Australia's TGA and South Korea's MFDS add further complexity through distinct biocompatibility testing mandates that filter market entry. Stakeholders must monitor regulatory harmonization negotiations between ASEAN member states to anticipate whether unified device approval pathways will emerge or fragment further.
Market Dynamics
Japan's PMDA accelerated approval pathways for novel intraocular pressure-lowering devices are compressing registration timelines and redistributing competitive advantage toward firms with integrated regional R&D footprints.
Growth Catalysts
- China's NMPA streamlined device review:Tertiary hospital networks in Shanghai and Beijing are expanding glaucoma screening capacity through faster regulatory clearance of diagnostic platforms.
- Minimally invasive glaucoma surgery (MIGS) protocols:Ophthalmology clinics across South Korea and Taiwan are adopting selective laser trabeculoplasty as first-line intervention, displacing conventional medication-only pathways.
- Aging demographics in East Asia:China's sixty-five-plus population concentration in coastal provinces is generating sustained procedural volume for angle-closure detection and management.
Market Restraints
- Input cost volatility in optical components:Precision-manufactured intraocular lenses and diagnostic sensors face supply concentration from German and Japanese specialty glass suppliers, exposing margin pressure.
- Regulatory friction from divergent ASEAN standards:The absence of unified medical device approval pathways forces redundant clinical trials across Thailand, Indonesia, and Vietnam, extending commercialization timelines.
- Technical limitation in early-stage detection:Anterior segment optical coherence tomography equipment remains concentrated in urban tertiary centers, restricting rural screening penetration.
Strategic Opportunities
- Underpenetrated India market:CDSCO regulatory harmonization discussions with ASEAN frameworks could unlock streamlined market entry for multinational device manufacturers targeting tier-two cities.
- Technology convergence of AI-assisted imaging:Machine learning integration with fundus photography systems is enabling automated angle-closure risk stratification in high-volume screening programs.
- Distribution innovation through ambulatory surgical centers:Australia's TGA reimbursement alignment with same-day discharge protocols is accelerating site-of-care migration from inpatient settings.
Industry Challenges
- Specialized surgical skill scarcity:Trained glaucoma specialists capable of performing MIGS procedures remain concentrated in Tokyo, Seoul, and Sydney metropolitan clusters, constraining procedure expansion.
- Certification timeline compression:Australia's TGA biocompatibility testing mandates for novel intraocular materials impose eighteen-to-twenty-four-month validation cycles that outpace product development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Primary Angle-Closure Glaucoma Market |
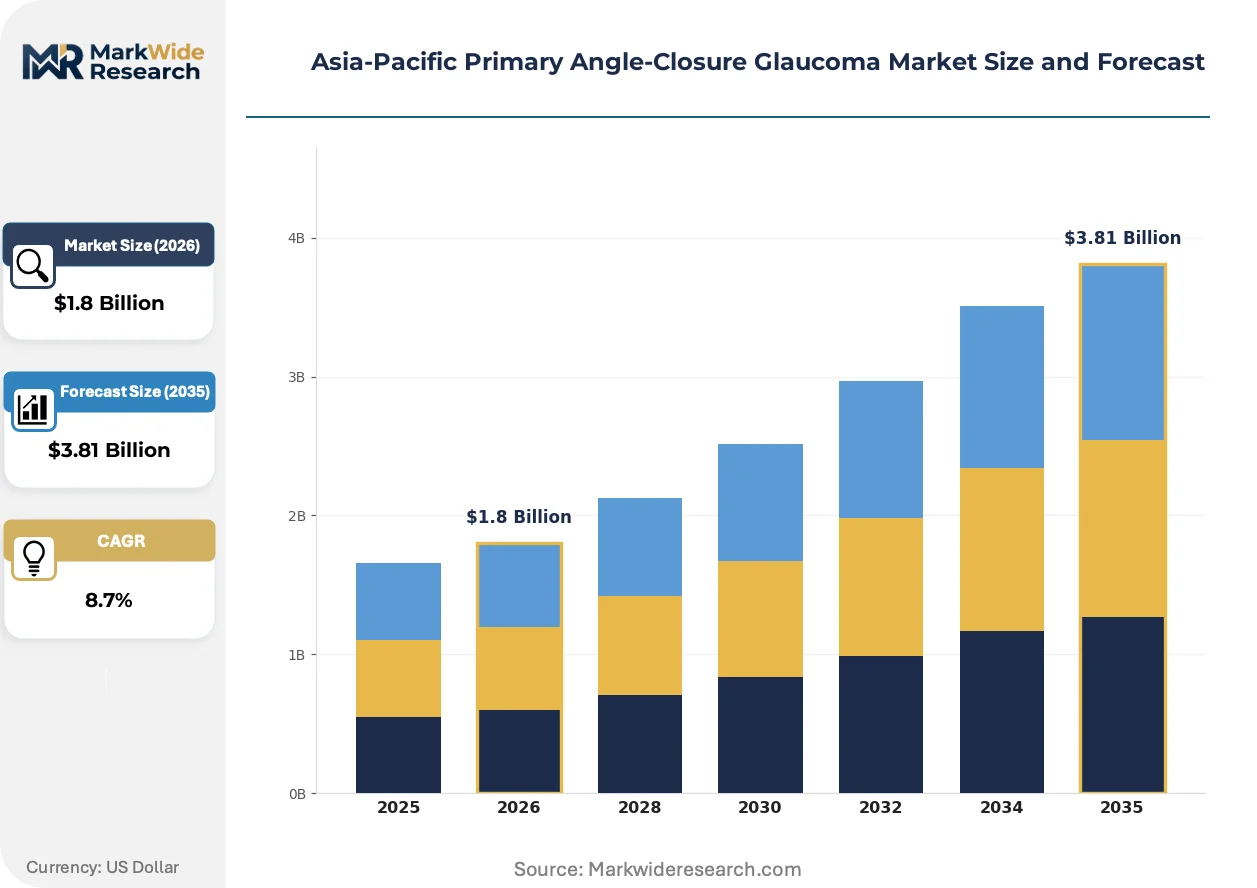
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Laser Therapy, Surgical Procedure, Monitoring Device End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Home Care Distribution Channel: Direct Sales, Online Pharmacies, Retail Pharmacies, Distributors Technology: Laser-Assisted, Microsurgical Tools, Diagnostic Imaging, Telemedicine |
| Companies Covered | Novartis AG, Allergan, Aerie Pharmaceuticals, Santen Pharmaceutical Co., Ltd., Bausch & Lomb Incorporated, Alcon, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Laboratoires Théa, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Primary Angle-Closure Glaucoma Market Strategic Shifts
Asia-Pacific ophthalmology is experiencing active restructuring around device miniaturization, regulatory pathway acceleration, and procurement model evolution that favors integrated diagnostic-therapeutic platforms over standalone equipment.
Micro-invasive glaucoma surgery (MIGS) stent technology is consolidating procedural workflows across Japan and South Korea. Tertiary hospital ophthalmology departments in Osaka and Busan are replacing conventional trabeculectomy with ab-interno canaloplasty at accelerating rates. This technology shift is consolidating manufacturer margins around disposable single-use devices while compressing capital equipment sales cycles.
Japan's PMDA Sakigake designation system is accelerating pre-market review timelines for breakthrough ophthalmic devices. The framework compresses regulatory lag from thirty-six months to twelve months for qualifying intraocular pressure sensors. Domestic manufacturers with established quality management systems are capturing first-mover positioning in reimbursed device categories ahead of multinational entrants.
Hospital procurement committees are unbundling diagnostic imaging service contracts from capital equipment purchases. Ophthalmology clinics in Singapore and Hong Kong are migrating toward per-procedure leasing arrangements for anterior segment analyzers. This purchasing behavior shift is most visible in private hospital networks where capital expenditure constraints intersect with high patient throughput requirements.
Asia-Pacific Primary Angle-Closure Glaucoma Market Segmentation
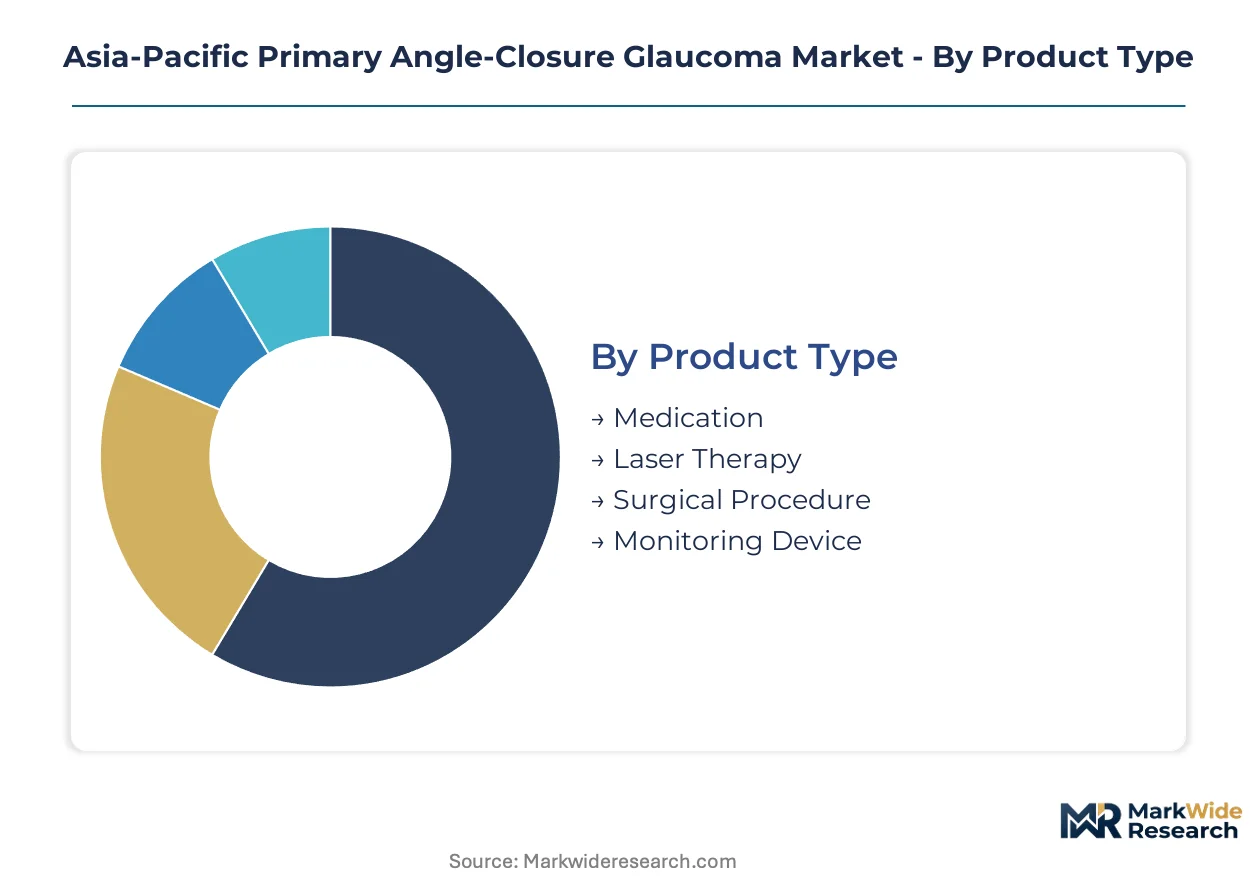
Segmentation in the Asia-Pacific Primary Angle-Closure Glaucoma Market reveals divergent capital requirements across intervention modalities. Treatment pathway economics vary sharply between pharmaceutical maintenance and surgical capital equipment, reshaping manufacturer portfolio priorities across the region's heterogeneous healthcare systems.
Product Type:
Capital intensity concentrates in surgical and monitoring segments, where precision manufacturing and regulatory validation impose steep upfront investment barriers.
- Surgical Procedure:Minimally invasive glaucoma surgery (MIGS) stents and ab-interno canaloplasty systems demand micron-scale manufacturing tolerances and biocompatibility testing cycles exceeding eighteen months. Tertiary hospital networks in Shanghai and Osaka are consolidating procurement around disposable single-use devices that command premium pricing over reusable alternatives.
- Monitoring Device:Anterior segment optical coherence tomography (AS-OCT) platforms and intraocular pressure sensors require integrated optical engineering and software validation. China's NMPA streamlined review pathways are accelerating domestic manufacturer market entry against multinational incumbents.
- Medication:Prostaglandin analogs and carbonic anhydrase inhibitors dominate first-line therapy with lower capital barriers but compressed margin pools under centralized procurement in China's hospital tier-one cities.
- Laser Therapy:Selective laser trabeculoplasty (SLT) equipment occupies mid-tier capital intensity, with South Korean clinics displacing medication-only pathways through faster reimbursement alignment.
Most installed capacity flows through Medication. Expansion is steepest in Surgical Procedure.
End User:
Site-of-care economics are pivoting toward outpatient settings as reimbursement frameworks reward same-day discharge protocols.
- Ophthalmology Clinics:Specialized diagnostic throughput and procedure volume concentrate in urban clusters where glaucoma specialists maintain dedicated surgical suites. Japan's metropolitan networks in Tokyo and Osaka anchor regional procedural density.
- Ambulatory Surgical Centers:Australia's TGA reimbursement alignment with MIGS protocols is accelerating migration from inpatient settings. Same-day discharge economics favor streamlined capital equipment footprints over full hospital infrastructure.
- Hospitals:Tertiary centers retain complex trabeculectomy and combined cataract-glaucoma procedures requiring overnight observation capabilities.
- Home Care:Self-tonometry devices and telemedicine integration are emerging in Singapore's private insurance networks, though penetration remains constrained by diagnostic accuracy requirements.
Revenue concentration sits with Ophthalmology Clinics. Patient volume is climbing fastest in Ambulatory Surgical Centers.
Distribution Channel:
Channel strategy diverges between capital equipment requiring technical service integration and consumables suited to high-velocity logistics.
- Direct Sales:AS-OCT platforms and surgical lasers demand field engineering support and training contracts. Manufacturers maintain captive sales forces in Beijing, Seoul, and Sydney to service high-value installations.
- Distributors:Regional logistics networks cover Indonesia, Vietnam, and Thailand where fragmented hospital procurement favors local inventory and credit terms. ASEAN regulatory fragmentation forces distributor-led market development ahead of direct investment.
- Retail Pharmacies:Preserved formulations and combination drops move through established pharmaceutical wholesale channels with limited manufacturer control.
- Online Pharmacies:India's CDSCO is tightening oversight of prescription eye drop e-commerce, constraining channel expansion despite consumer convenience demand.
Equipment revenue flows predominantly through Direct Sales. Distributors are gaining share fastest in emerging ASEAN markets.
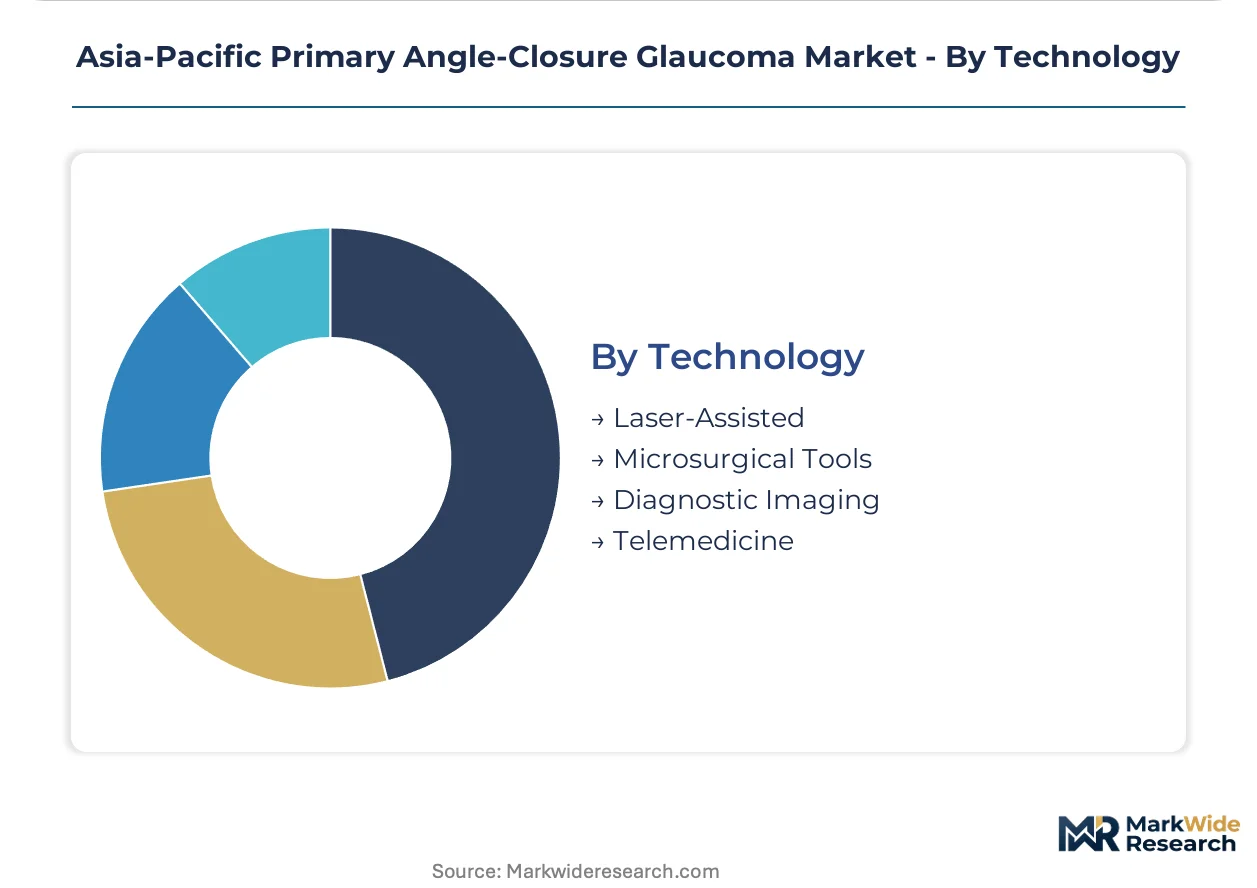
Technology:
Technology platform selection determines reimbursement tier and specialist training requirements across national health systems.
- Diagnostic Imaging:AS-OCT and fundus photography systems with AI-assisted angle-closure risk stratification are consolidating screening workflows. China's coastal province hospitals are deploying at scale ahead of rural network penetration.
- Laser-Assisted:SLT platforms are displacing medication-first protocols in South Korea and Taiwan where procedure reimbursement exceeds pharmaceutical maintenance economics.
- Microsurgical Tools:MIGS stent delivery systems and precision cannulas require surgeon certification programs that limit addressable specialist pools.
- Telemedicine:Remote consultation platforms are piloting in Australia's rural outreach programs, though diagnostic limitation in anterior segment examination constrains clinical utility.
Deployment concentration centers on Diagnostic Imaging. Adoption curves are steepest for Laser-Assisted platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary angle-closure glaucoma management first achieved systematic scale in Japan's post-war ophthalmology infrastructure, later diffusing through East Asian hospital networks as diagnostic imaging technology commoditized. Today's regional landscape reflects divergent regulatory maturities and urban-rural care gaps.
China
Coastal tertiary hospitals in Shanghai and Beijing drive screening volumes through expanded NMPA fast-track approvals for anterior segment analyzers. The national regulator's streamlined device review compresses registration timelines from thirty-six to eighteen months for qualifying diagnostic platforms. Guangdong province's Pearl River Delta cluster anchors domestic manufacturing of intraocular pressure sensors, with Shenzhen-based firms capturing rising share in reimbursed device categories.
Japan
Aging demographics in the Kanto region sustain procedural density for MIGS interventions among the world's highest per-capita glaucoma specialist concentrations. PMDA's Sakigake designation system accelerates pre-market review to twelve months for breakthrough ophthalmic devices, redistributing competitive advantage toward domestic manufacturers with established quality systems. Osaka's Kansai medical device corridor hosts integrated R&D facilities serving East Asian registration requirements.
South Korea
Seoul Capital Area clinics displace medication-first pathways through MFDS reimbursement alignment with selective laser trabeculoplasty protocols. The national regulator's procedure coding updates favor same-day discharge economics, accelerating ambulatory surgical center migration. Busan's ophthalmology clusters specialize in micro-invasive stent delivery systems requiring surgeon certification programs that limit addressable specialist pools.
Australia
TGA biocompatibility testing mandates for novel intraocular materials impose eighteen-to-twenty-four-month validation cycles that filter multinational device entry. Sydney and Melbourne metropolitan networks concentrate trained glaucoma specialists capable of complex trabeculectomy procedures. Rural outreach programs pilot telemedicine integration for anterior segment examination, though diagnostic accuracy constraints limit clinical utility.
India
Tier-two cities in Maharashtra and Tamil Nadu represent underpenetrated volume opportunities as CDSCO engages ASEAN regulatory harmonization discussions. The national pharmaceutical regulator's evolving oversight of prescription eye drop e-commerce constrains channel expansion despite consumer convenience demand. Hyderabad's medical technology corridor attracts contract manufacturing for multinational device firms seeking cost-advantaged production.
Asia-Pacific Primary Angle-Closure Glaucoma Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory sophistication and integrated R&D footprint, with surgical device manufacturers commanding pricing power over pharmaceutical maintenance therapies. The vendor base stratifies into three tiers: multinational ophthalmology conglomerates with captive distribution, regional pharmaceutical specialists with hospital formulary relationships, and domestic device startups leveraging accelerated approval pathways. Consolidation pressures concentrate among diagnostic imaging platforms where capital equipment sales cycles compress toward per-procedure leasing arrangements. Competitive moves center on regulatory first-mover positioning in reimbursed device categories and backward integration into precision optical component manufacturing.
Within the multinational conglomerate tier, Novartis AG and Alcon occupy positions defined by integrated R&D footprints across Singapore and Japanese regulatory jurisdictions. Santen Pharmaceutical Co., Ltd. anchors specialized distribution capabilities in East Asian hospital networks. These three exemplify divergent strategic archetypes: the Swiss-headquartered player leverages global registration scale, the US-based competitor competes on diagnostic imaging technology depth, and the Japanese limited company sustains regional product registration leadership through domestic regulatory intimacy.
| Leading Market Players |
|---|
| Novartis AG |
| Allergan |
| Aerie Pharmaceuticals |
| Santen Pharmaceutical Co., Ltd. |
| Bausch & Lomb Incorporated |
| Alcon |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Laboratoires Théa |
| Others |
Value Chain & Pricing Dynamics
Tertiary hospital procurement committees in China's coastal provinces anchor pricing power through consolidated volume contracting for MIGS devices. This buyer concentration forces manufacturers toward per-procedure leasing arrangements that compress upfront capital premiums while extending revenue recognition timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the Asia-Pacific market. Premium tiers command positioning through PMDA Sakigake designation and MFDS breakthrough device status, while standard tiers compete on NMPA streamlined clearance speed. Price differentiation hinges on biocompatibility certification grade and bundled surgeon training programs. Cost compression in economy-tier medication segments is intensifying because China's centralized hospital procurement pools generic prostaglandin analogs. Ambulatory surgical centers exhibit highest price sensitivity; tertiary ophthalmology departments show lowest.
Supply Chain Analysis
Biocompatibility certification gates upstream access, with ISO 10993 and TGA material validation requirements filtering component suppliers. Precision optical engineering draws from Japan, Germany, and South Korea for specialty glass and sensor substrates. Raw material dependencies center on high-purity silica substrates, biocompatible polymers, and precision-machined titanium alloys. Single-source vulnerability concentrates in German specialty glass suppliers for anterior segment analyzers. Distribution runs through captive field engineering teams for capital equipment and regional logistics networks for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through MIGS device premiumization and disposable single-use conversion away from reusable alternatives. Cost-down drivers include domestic manufacturing migration to Shenzhen and Hyderabad corridors.
For Market Incumbents: Anticipate regulatory timeline compression by securing PMDA Sakigake designation ahead of multinational rivals. Deepen backward integration into precision optical component manufacturing to defend margin position against German and Japanese supplier concentration. Prioritize certification investment in China's NMPA fast-track pathways to maintain formulary access as domestic manufacturers accelerate. For New Entrants and Emerging Players: Begin with India's tier-two cities where CDSCO regulatory harmonization discussions with ASEAN frameworks could unlock streamlined market entry. Target ambulatory surgical centers in Australia and South Korea where reimbursement alignment with same-day discharge protocols creates white-space demand. Pursue AI-assisted imaging integration as the go-to-market angle for automated angle-closure risk stratification. For Investors and Strategic Acquirers: Ophthalmology conglomerates with integrated R&D footprints across Singapore and Japan are the most active acquirer in this space, seeking diagnostic-therapeutic platform consolidation. Long-term viability favors targets with captive regulatory registration capabilities and surgeon certification program infrastructure. Watch for PMDA-NMPA mutual recognition agreement progress as the inflection signal for cross-border commercialization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Sakigake Designation Pursuit | Compresses pre-market review from thirty-six months to twelve for qualifying devices. |
| AI-Assisted Imaging Integration | Enables automated angle-closure risk stratification in high-volume Chinese screening programs. |
| Ambulatory Surgical Center Partnership | Captures site-of-care migration driven by Australia's TGA same-day discharge reimbursement. |
| Domestic Manufacturing Footprint | Reduces cost position through Shenzhen and Hyderabad precision component production. |
| Surgeon Certification Program Development | Limits addressable specialist pools and locks in proprietary MIGS stent delivery system adoption. |
Study Parameters
Coverage spans East Asia, Southeast Asia, and Oceania, with primary inputs from each regional cluster. The analysis combines structured interviews with glaucoma specialists, hospital procurement managers, biomedical engineers, and regulatory affairs leads at national health agencies with secondary validation. Secondary sources include PMDA approval databases, NMPA medical device registration filings, MFDS reimbursement coding updates, and hospital procurement contract repositories. Bottom-up procedure volume modeling and top-down healthcare expenditure triangulation anchor market size estimation.
Granularity-level modeling disaggregates projections across product type, end user site-of-care, distribution channel, and technology platform dimensions. CAGRs derive from segmented procedure volume trajectories and price evolution assumptions across the projection horizon. Industry-specific forecast inputs incorporate regulatory approval timeline distributions and reimbursement policy shift probabilities.
Several conditions sit outside the modeled scope, including raw material supply disruptions, geopolitical trade restriction escalations, and novel therapeutic modality breakthroughs. Forecasts reflect documented assumptions about specialist training pipeline expansion and diagnostic equipment rural penetration rates. Deviation in PMDA-NMPA regulatory harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Malabsorption Syndrome Market