
 Diabetes Care Devices and Drugs Market | 2026-2036
Diabetes Care Devices and Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Care Devices and Drugs Market Intelligence
Expanded manufacturing capacity in India and Brazil is narrowing the supply gap for affordable insulin analogues and blood glucose meters. Novo Nordisk leverages its extensive R&D pipeline in GLP-1 receptor agonists to maintain a strong market position. Abbott Laboratories dominates the continuous glucose monitoring (CGM) segment with its sensor-based technology. Medtronic competes through its portfolio of integrated insulin pumps and smart pens, focusing on closed-loop system development.
Diabetes care devices and drugs encompass a range of technologies and pharmaceuticals designed for glycemic control in individuals with diabetes. These include monitoring devices that measure blood glucose with specific accuracy parameters, such as Mean Absolute Relative Difference (MARD) for CGMs, and therapeutic agents like insulin formulations or oral hypoglycemics. The primary purpose is to help patients maintain blood glucose levels within a target range to prevent long-term complications. Continuous Glucose Monitors and Injectable GLP-1 Receptor Agonists represent high-growth product categories. This reflects a transition from reactive monitoring with Blood Glucose Meters to proactive, data-driven management for Type 2 Diabetes.
Regulatory frameworks from the US FDA, the European Medicines Agency (EMA), and China's NMPA govern market entry and product claims. These agencies enforce rigorous clinical trial requirements for new drugs and stringent pre-market approval processes for high-risk devices like insulin pumps. Successful long-term patient adherence depends on the ability of manufacturers to integrate device data into seamless digital health ecosystems while ensuring affordability and accessibility.
Market Dynamics
The convergence of medical devices with digital health ecosystems is the central force shaping the diabetes care market. This integration is driven by demand for real-time data analytics and personalized feedback loops for improved glycemic control.
Growth Catalysts
- Value-Based Reimbursement:Policies in North America and Europe rewarding improved outcomes are accelerating adoption of CGMs and integrated pumps.
- Sensor Miniaturization:Advances in microelectronics enable smaller, more comfortable, and longer-lasting on-body devices, improving user adherence.
- Emerging Market Demand:Rising incomes and public health initiatives in China and Brazil are expanding access to modern diabetes care.
Market Restraints
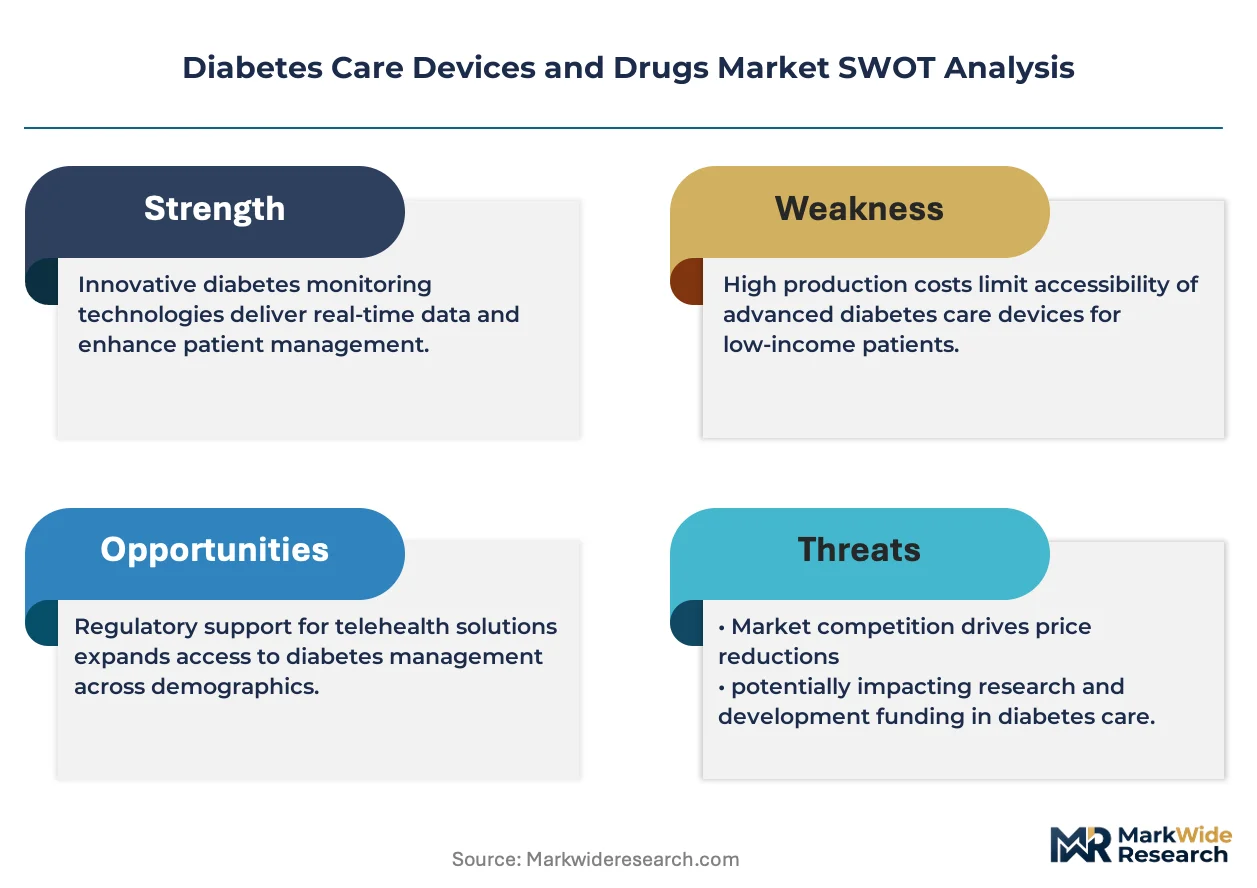
- Cost and Reimbursement Gaps:High upfront costs and inconsistent insurance for advanced systems like closed-loop pumps create significant access barriers.
- Stringent Regulatory Hurdles:The EU's Medical Device Regulation (MDR) imposes extensive data requirements and post-market surveillance, lengthening development timelines.
- Access to Biologics:Patent expirations and complex manufacturing for insulin analogues can lead to supply constraints and price volatility.
Strategic Opportunities
- Underpenetrated Geographies:Markets in Southeast Asia and Latin America present expansion potential due to rising diabetes prevalence and nascent adoption of advanced technologies.
- AI-Powered Predictive Analytics:Integrating AI into management platforms to forecast glycemic events offers a major opportunity for product differentiation.
- Direct-to-Consumer Channels:Subscription models for CGM sensors and supplies provide a pathway to bypass traditional distribution and enhance customer relationships.
Industry Challenges
- Data Interoperability:Achieving secure, seamless data exchange between devices from different manufacturers and with electronic health records remains a significant technical challenge.
- Patient Adherence and Training:Manufacturers face difficulty ensuring long-term patient engagement with complex devices, which require extensive training and ongoing support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Care Devices and Drugs Market |
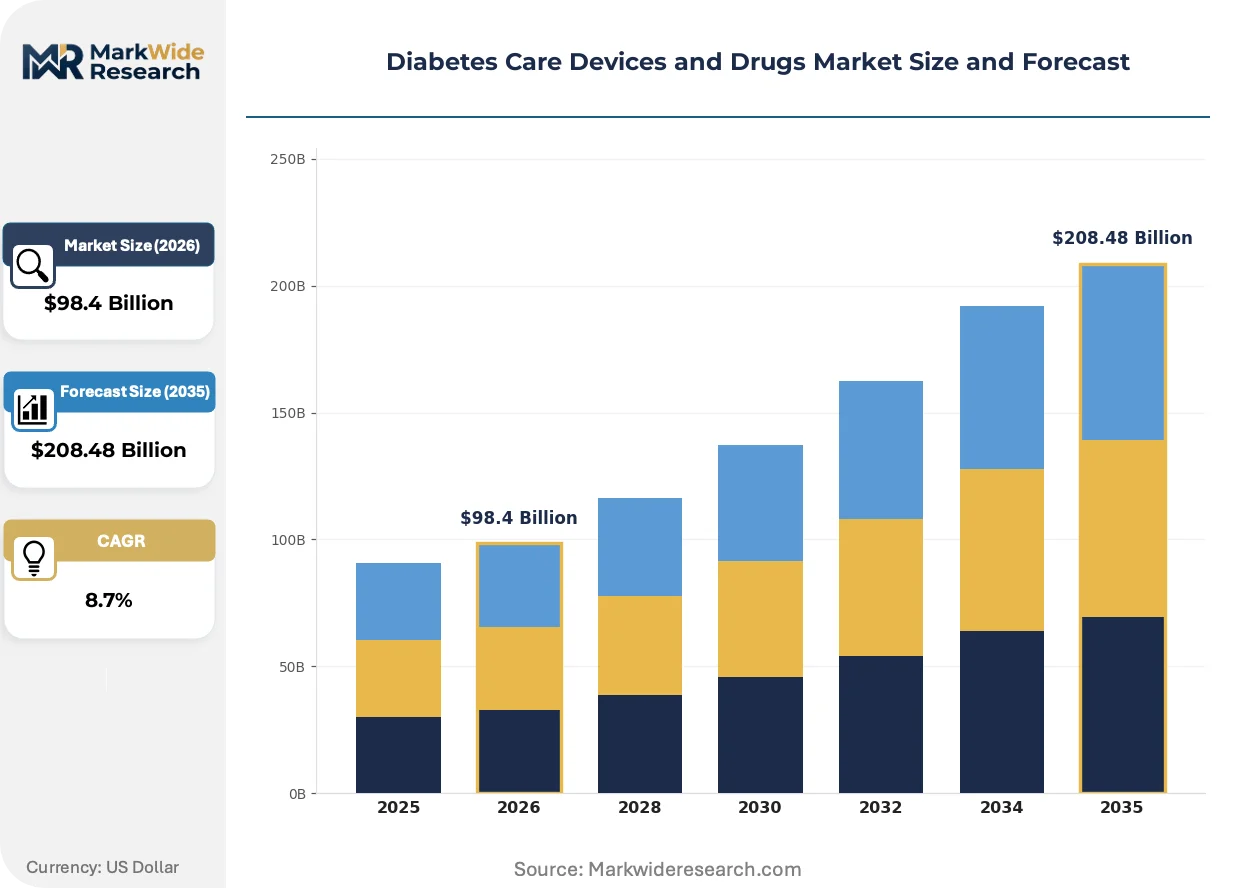
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $208.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Blood Glucose Meters, Continuous Glucose Monitors, Oral Hypoglycemics, Injectable GLP-1 Receptor Agonists Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes, Diabetic Ketoacidosis End User: Hospitals, Specialized Clinics, Diagnostic Laboratories, Home Care Patients, Pharmacies Delivery Mode: Injections, Oral Tablets, Transdermal Patches, Inhalation Devices, Implantable Pumps |
| Companies Covered | Novo Nordisk, Abbott Laboratories, Medtronic, F. Hoffmann-La Roche Ltd., Sanofi, Dexcom, Insulet Corporation, Eli Lilly and Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Care Devices and Drugs Market Strategic Shifts & Innovations
Connectivity is reconfiguring the diabetes care model from reactive treatment to proactive, personalized management. This shift prioritizes continuous data streams and analytical insights over intermittent measurements to guide therapeutic decisions.
Minimally invasive continuous glucose monitoring (CGM) provides real-time glucose readings through a small, on-body sensor. Patients with Type 1 and increasingly Type 2 diabetes adopt these systems for greater glycemic visibility. This evolution is rendering obsolete the reliance on frequent, painful fingerstick tests from traditional blood glucose meters.
The US FDA's interoperable automated glycemic controller (iAGC) designation standardizes communication protocols. This pathway allows components like CGMs and pumps from different vendors to form a single automated insulin delivery system. The iAGC classification pushes the industry toward open-architecture, patient-customizable closed-loop systems.
A prominent behavioral shift involves patients demanding direct control over their personal glycemic data. This consumerization of health data disrupts the clinician-gated information model, as patients use third-party apps to analyze their own trends. The demand for data portability is most visible in North America, influencing device design.
Diabetes Care Devices and Drugs Market Segmentation
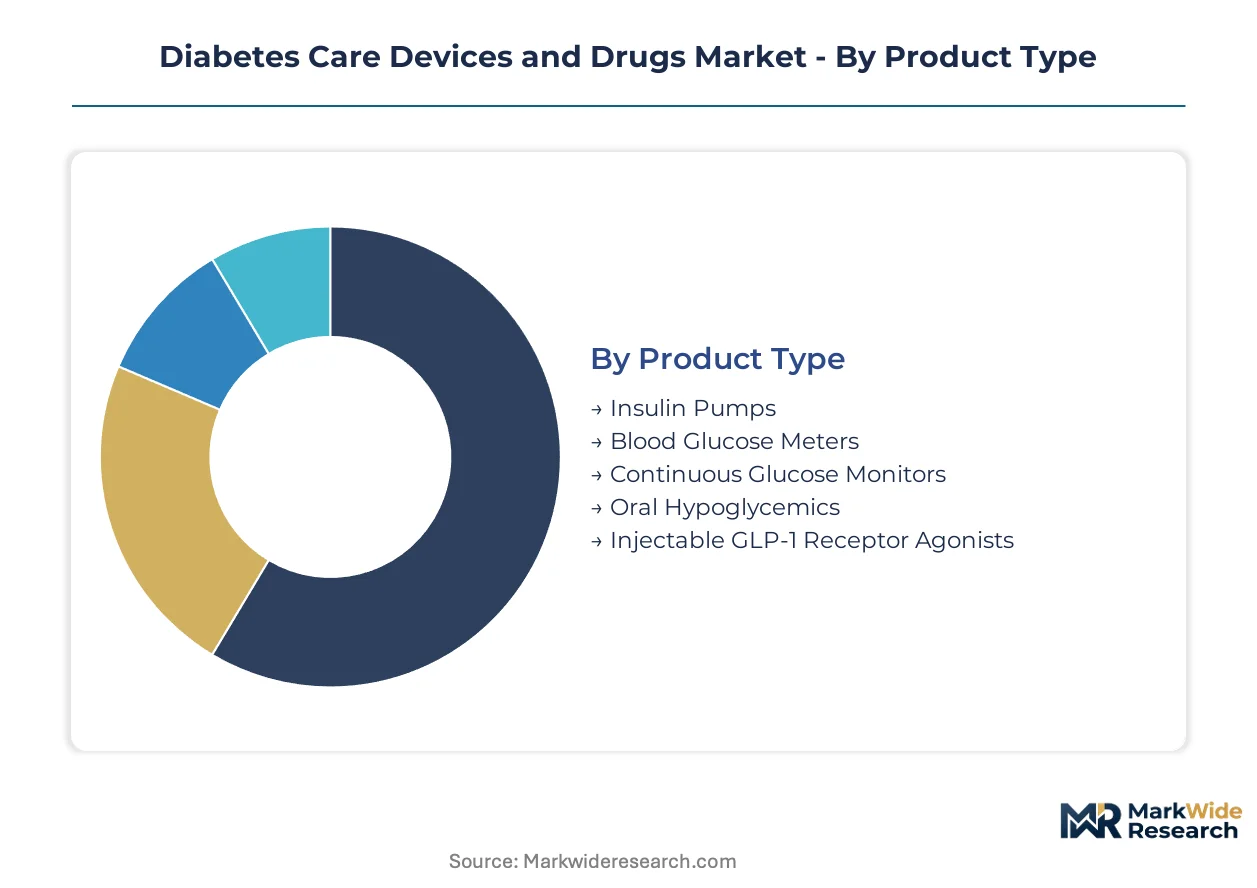
Segmentation analysis reveals distinct dynamics across the diabetes care devices and drugs market, reflecting diverse patient needs and technological advancements. Understanding these segments helps manufacturers tailor product development and market entry strategies. This granular view highlights areas of concentrated demand and emerging growth trajectories for glycemic management.
Product Type:
The product type segmentation highlights varying adoption cycles, from established monitoring tools to rapidly evolving therapeutic agents.
- Continuous Glucose Monitors:Sensor-based devices provide real-time glucose readings, reducing fingerstick reliance for proactive management. Demand concentrates in North America and Europe, driven by value-based reimbursement and patient preference for data-driven insights.
- Injectable GLP-1 Receptor Agonists:These pharmaceutical agents mimic natural hormones to improve glycemic control and often aid weight management. Expansion concentrates in markets with rising Type 2 diabetes prevalence, such as China and Brazil, due to their efficacy and cardiovascular benefits.
- Insulin Pumps:Automated devices deliver insulin continuously, offering precise glycemic management for Type 1 diabetes patients.
- Blood Glucose Meters:Traditional handheld devices measure blood glucose from a fingerstick sample, providing intermittent readings for glycemic status.
- Oral Hypoglycemics:Pills lower blood glucose through various mechanisms, serving as a primary treatment for many Type 2 diabetes patients.
Blood Glucose Meters dominate the installed base. Continuous Glucose Monitors are where expansion concentrates.
Application:
The application segment reflects the varying patient volumes and disease progression stages addressed by diabetes care solutions.
- Type 2 Diabetes:This segment represents the largest patient population, often managed with oral medications, GLP-1 agonists, and increasingly CGMs. Demand for integrated care solutions is significant in countries with aging populations and rising incomes, like China.
- Type 1 Diabetes:Autoimmune condition requiring lifelong insulin therapy, primarily managed through insulin pumps and continuous glucose monitoring systems. Regulatory frameworks from the US FDA and EMA ensure strict device performance for this critical patient group.
- Gestational Diabetes:Temporary condition during pregnancy, managed through diet, exercise, and sometimes insulin, with a focus on maternal and fetal health outcomes.
- Prediabetes:Characterized by elevated blood glucose levels not yet meeting diabetes diagnostic criteria, often addressed through lifestyle modifications to prevent progression.
- Diabetic Ketoacidosis:A severe, acute complication of diabetes requiring immediate medical intervention, primarily treated in hospital settings.
Type 2 Diabetes applications drive the largest market volume. Prediabetes management shows the steepest expansion trajectory.
End User:
End-user categories delineate where diabetes care products are consumed, highlighting shifts in care delivery models.
- Home Care Patients:Individuals managing their diabetes independently, utilizing portable devices like CGMs and smart pens for daily glycemic control. This segment is growing in North America and Europe, driven by demand for greater autonomy and digital health integration.
- Hospitals:Critical for initial diagnosis, acute complication management, and specialized treatment initiation for complex diabetes cases. Regulatory bodies like the US FDA and EMA influence device procurement in these institutional settings.
- Specialized Clinics:Outpatient facilities offering comprehensive diabetes management, including endocrinology consultations, education, and device training.
- Diagnostic Laboratories:Facilities conducting blood tests for diabetes diagnosis and monitoring, such as HbA1c and glucose tolerance tests.
- Pharmacies:Key distribution channels for oral hypoglycemics, insulin, and blood glucose meters, providing patient access and counseling.
Hospitals remain central for acute care. Home Care Patients represent a significant shift in long-term management.
Delivery Mode:
The delivery mode segmentation reflects the maturity and invasiveness of various therapeutic administration methods.
- Injections:Predominantly subcutaneous delivery of insulin and GLP-1 receptor agonists using pens or syringes. This traditional method remains widespread due to its efficacy and established patient familiarity across all geographies.
- Oral Tablets:Non-invasive delivery of various oral hypoglycemic agents, offering convenience for Type 2 diabetes patients. This mode dominates in terms of patient preference in early-stage Type 2 diabetes management.
- Transdermal Patches:Non-invasive delivery systems for certain drugs, offering continuous, controlled release, though less common for primary diabetes therapeutics.
- Inhalation Devices:Alternative delivery method for insulin, providing a needle-free option for some patients, regulated by agencies such as the US FDA.
- Implantable Pumps:Surgically placed devices delivering insulin directly into the peritoneal cavity, offering advanced, long-term glycemic control for select patients.
Injections maintain the broadest patient reach. Oral Tablets show strong growth in primary care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side expansion in key manufacturing hubs is influencing global distribution for diabetes care devices and drugs. This expansion helps narrow the affordability gap for essential therapeutics and monitoring technologies. Strategic investments in local production capabilities are shifting regional market dynamics.
United States
Demand for advanced diabetes management technologies, such as continuous glucose monitors, drives market expansion in the United States. The US FDA's interoperable automated glycemic controller (iAGC) designation standardizes communication protocols for integrated systems. Innovation clusters in Boston and the San Francisco Bay Area attract significant venture capital for digital health solutions.
Germany
Germany's aging population and robust healthcare infrastructure stimulate demand for integrated care solutions and advanced insulin delivery systems. The European Medicines Agency (EMA) and the EU's Medical Device Regulation (MDR) enforce stringent quality and safety standards. Research and development in medical technology centers around Bavaria and North Rhine-Westphalia focus on personalized glycemic control.
China
Rising incomes and a large Type 2 diabetes patient population propel demand for injectable GLP-1 receptor agonists and advanced monitoring devices in China. The National Medical Products Administration (NMPA) regulates market entry and product claims for both domestic and imported diabetes treatments. Major pharmaceutical and medical device manufacturing hubs in the Yangtze River Delta are expanding capacity for diabetes care products.
India
Expanded manufacturing capacity for affordable insulin analogues and blood glucose meters addresses a significant supply gap in India. The Central Drugs Standard Control Organization (CDSCO) oversees the approval and regulation of new drugs and medical devices. Cities like Hyderabad and Bengaluru are developing as centers for pharmaceutical R&D and medical technology production.
Brazil
Public health initiatives and an increasing prevalence of Type 2 diabetes are expanding access to modern diabetes care solutions across Brazil. ANVISA, Brazil's national health surveillance agency, regulates the market entry of diabetes devices and drugs. São Paulo serves as a central hub for healthcare infrastructure and medical device distribution throughout Latin America.
Diabetes Care Devices and Drugs Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the diabetes care devices and drugs market. The competitive landscape features a mix of large pharmaceutical companies, specialized medical device manufacturers, and emerging digital health innovators. Dominant competitive moves include expanding R&D pipelines for novel therapeutics and developing integrated device solutions.
Specialists in device innovation, Abbott Laboratories and Medtronic PLC, exemplify leadership in continuous glucose monitoring and integrated insulin pump systems, respectively. Abbott Laboratories, a US-based entity, maintains a strong position in sensor-based glucose monitoring technology. Medtronic PLC, an Ireland-domiciled medical technology company, focuses on closed-loop system development through its portfolio of smart pens and insulin pumps. Novo Nordisk A/S, a Danish pharmaceutical company, represents a major force in the GLP-1 receptor agonist segment, leveraging its extensive R&D capabilities.
| Leading Market Players |
|---|
| Novo Nordisk |
| Abbott Laboratories |
| Medtronic |
| F. Hoffmann-La Roche Ltd. |
| Sanofi |
| Dexcom |
| Insulet Corporation |
| Eli Lilly and Company |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta's expanding manufacturing capacity for diabetes care products directly influences global pricing. This increased production volume in China contributes to greater affordability for essential therapeutics and monitoring technologies.
Pricing Analysis
The EU's Medical Device Regulation (MDR) dictates the pricing tier structure for advanced diabetes devices in Europe. Hybrid pricing models combining value-based reimbursement with subscription services characterize the market, driven by device accuracy parameters and regulatory certifications. Pricing softness stems from expanded manufacturing capacity in India and Brazil for affordable insulin analogues and blood glucose meters. Home care patients exhibit high price sensitivity for advanced closed-loop systems, while institutional buyers prioritize performance and interoperability.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the complex global network for diabetes care products. Geographic supply concentration for insulin analogues and GLP-1 receptor agonists centers in India, China, and Europe. Raw material dependencies include specialized sensor components and biologics, where complex manufacturing creates a structural supply chain risk. Distribution runs through multi-channel networks, including pharmacies, specialized clinics, and emerging direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diabetes care market presents a significant fragmentation opportunity driven by the demand for personalized, data-driven management. This shift creates distinct niches for specialized devices and integrated digital health solutions.
For Market Incumbents: Entrench core market positions by expanding R&D pipelines for novel therapeutics like GLP-1 receptor agonists and developing integrated closed-loop insulin delivery systems. This defends against emerging digital health innovators and mitigates stringent regulatory hurdles. Deepen control over digital health ecosystems to ensure device data interoperability and patient adherence. Investment in advanced sensor miniaturization further strengthens product differentiation.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated geographies like Southeast Asia and Latin America, where diabetes prevalence is rising. Target the prediabetes management segment with AI-powered predictive analytics for early intervention. A direct-to-consumer subscription model for CGM sensors offers a viable go-to-market angle. Focus on seamless digital health ecosystem integration to differentiate offerings for home care patients.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with proven interoperability and AI-driven predictive analytics capabilities. Long-term viability rests on integrated, data-driven solutions for chronic disease management. Target acquisition profiles include innovative sensor technology firms and digital health platform providers with strong patient engagement. Regulatory approvals for open-architecture closed-loop systems, such as iAGC designations, serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Predictive Analytics Product Launch | Offers product differentiation by forecasting glycemic events for Type 2 Diabetes patients. |
| Digital Health Ecosystem Platform Integration | Ensures seamless data exchange between devices and electronic health records for improved patient care. |
| Strategic Partnerships for Interoperability | Facilitates communication protocols between diverse device manufacturers, enhancing system flexibility. |
| Geographic Expansion into Southeast Asia | Addresses rising diabetes prevalence and nascent technology adoption in underpenetrated markets. |
| iAGC Regulatory Approval Pathway | Standardizes communication protocols for automated insulin delivery systems, accelerating market entry. |
Research Approach
Operator-level perspectives from clinicians, hospital purchasing committees, medical device engineers, and regulatory affairs leads anchored the qualitative base for this study. Primary interviews were triangulated with extensive secondary research, including US FDA filings, EMA submissions, NMPA guidelines, and industry association reports. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down data validation.
Scenario-bracketing informed the quantitative analytical framework, providing a range of outcomes across the analysis window. The market was segmented and modeled by product type, application, end-user, delivery mode, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical data, market drivers, and expert projections. Diabetes prevalence rates and healthcare expenditure trends served as key forecast inputs.
Stress conditions across reimbursement policies and new device interoperability standards were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning technological advancements and patient adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Global Type 2 Diabetes Treatment Market