
 Ophthalmic Femtosecond Lasers Market | 2026-2036
Ophthalmic Femtosecond Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Femtosecond Lasers Market Intelligence
Buyer concentration among hospital-affiliated ambulatory surgical centers is hardening across major metropolitan markets. Alcon Inc. leverages its integrated cataract-refractive portfolio to sustain recurring consumable revenue streams. Carl Zeiss Meditec AG anchors premium positioning through proprietary optical coherence tomography-guided laser platforms. Johnson & Johnson Surgical Vision Inc. competes on global service density and surgeon training infrastructure.
Ophthalmic femtosecond lasers generate ultrashort pulses typically below 500 femtoseconds duration, enabling photodisruption of ocular tissue with minimal thermal collateral damage through nonlinear optical absorption. These systems execute precise corneal flap creation, lens fragmentation, and arcuate incisions to reduce surgical variability and improve visual outcomes. The application dimension shows cataract surgery and LASIK commanding current installed bases while corneal surgery applications expand fastest among subspecialty practices. Product segmentation reveals laser cataract surgery systems capturing premium pricing relative to standalone refractive platforms, with surgical laser configurations gaining traction in academic medical centers for resident training protocols.
FDA 510(k) clearance and EU MDR conformity assessment govern commercial access, with FDA requiring clinical validation of incision precision metrics and MDR mandating post-market surveillance for active implantable derivatives. ISO 13485 quality management and IEC 60601-1 electrical safety standards frame manufacturing baseline requirements for all marketed devices. Stakeholders must monitor evolving reimbursement thresholds for femtosecond-assisted procedures against standard manual techniques across public and private payer systems.
Market Dynamics
Surgeon training protocols and reimbursement thresholds for femtosecond-assisted cataract procedures are tightening the link between capital equipment procurement and sustained consumable revenue capture across ambulatory surgical networks.
Growth Catalysts
- LASIK volume recovery:Post-pandemic elective procedure backlogs are clearing in the United States and Germany, driving replacement cycles for aging excimer laser platforms.
- EU MDR compliance deadlines:The 2024-2026 transition window is accelerating hospital system procurement of CE-marked femtosecond systems ahead of legacy device retirements.
- Corneal cross-linking integration:Combined femtosecond and UV-A platforms for keratoconus treatment are expanding addressable procedure volumes in tertiary ophthalmology centers.
Market Restraints
- Capital intensity barriers:Single-platform acquisition costs exceeding $500,000 restrict independent practice adoption outside hospital-affiliated networks.
- Reimbursement compression:CMS and private payers in the United States are narrowing fee differentials between manual and femtosecond-assisted cataract extraction.
- Service technician scarcity:Concentrated manufacturer service footprints create 72-hour+ downtime risks for non-urban surgical centers.
Strategic Opportunities
- India outpatient expansion:Corporate hospital chains in Mumbai and Delhi are deploying femtosecond platforms for premium refractive packages targeting medical tourism.
- Glaucoma angle procedures:Femtosecond laser trabeculotomy is emerging as a MIGS-adjacent application with limited competitive device saturation.
- Subscription financing models:Per-procedure leasing structures are lowering entry barriers for mid-sized ophthalmology groups in Japan.
Industry Challenges
- Biomedical engineer recruitment:Servicing femtosecond laser cavities requires specialized photonics expertise concentrated in Germany and the United States.
- ISO 13485 audit backlogs:Notified body capacity constraints are extending conformity assessment timelines for new platform submissions.
- EHR integration complexity:Proprietary OCT data formats from femtosecond systems resist seamless interoperability with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Femtosecond Lasers Market |
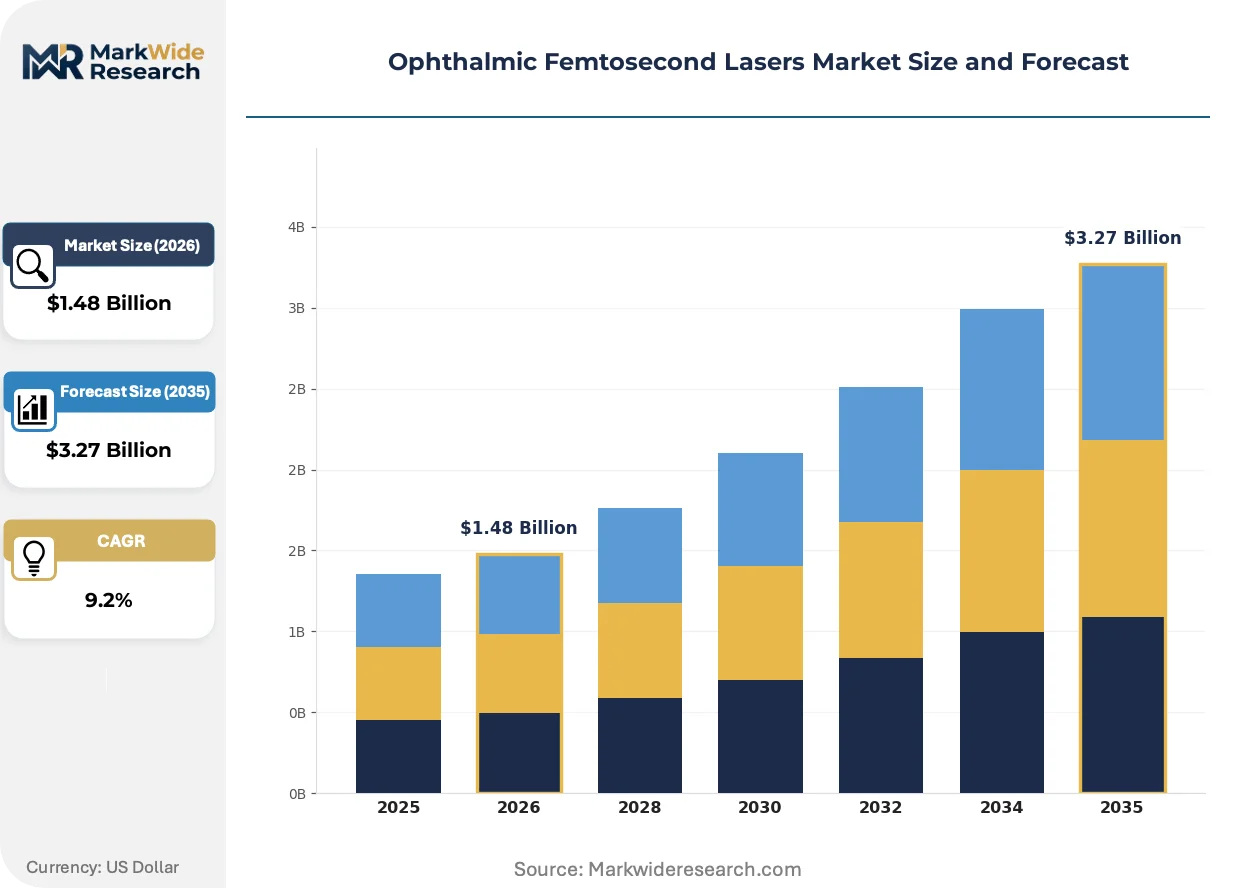
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser System, Laser Cataract Surgery, Refractive Laser, Surgical Laser End User: Hospitals, Eye Clinics, Academic Institutions, Research Laboratories Technology: Ultrafast Laser, Picosecond Laser, Nanosecond Laser, Solid-State Laser Application: Cataract Surgery, LASIK, Corneal Surgery, Glaucoma Treatment |
| Companies Covered | Bausch & Lomb Incorporated, Ziemer Ophthalmic Systems AG, Johnson & Johnson Surgical Vision Inc., IMRA America, Inc., Abbott Medical Optics, Alcon Inc., LENSAR Inc., SCHWIND eye-tech-solutions GmbH, Carl Zeiss Meditec AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Femtosecond Lasers Market Strategic Shifts & Innovations
Real-time intraoperative guidance systems and cloud-connected maintenance platforms are compressing the feedback loop between surgical outcomes and equipment calibration protocols.
Intraoperative OCT integration is decentralizing surgical decision-making from preoperative planning to real-time flap thickness verification and lens fragmentation monitoring. Academic medical centers in Boston and Heidelberg are deploying these systems for resident training standardization. The technology is decentralizing quality assurance functions previously concentrated in postoperative follow-up protocols.
The EU MDR's post-market surveillance requirements for active implantable medical devices are extending conformity obligations to femtosecond laser manufacturers with cataract refractive suites. European notified bodies are demanding annual clinical follow-up data on incision healing metrics. Manufacturers serving Germany and France are restructuring quality management systems to capture longitudinal patient outcome registries.
Service contract unbundling is fragmenting traditional full-service agreements into laser head maintenance, software licensing, and consumable supply tiers. Ambulatory surgical centers in Texas and California are negotiating à la carte service modules to match utilization patterns. This restructuring is most visible among high-volume cataract networks seeking to insource preventive maintenance on mature platform generations.
Ophthalmic Femtosecond Lasers Market Segmentation
Segmentation in ophthalmic femtosecond lasers reveals how procurement decisions bifurcate between high-volume cataract networks and specialized refractive practices. Equipment configurations, user settings, and application protocols each impose distinct technical requirements that shape vendor R&D priorities and service contract structures.
Product Type:
Supply concentration among German and Japanese photonics manufacturers determines which platform configurations dominate hospital procurement tenders.
- Laser System:General-purpose femtosecond platforms deliver pulse durations below 500 femtoseconds through solid-state resonator architectures. Demand clusters in United States metropolitan surgical centers upgrading from mechanical microkeratome systems for LASIK flap creation.
- Laser Cataract Surgery:Integrated platforms combine femtosecond anterior capsulotomy with phacoemulsification handpieces through docking interfaces. Procurement concentrates in hospital-affiliated ambulatory networks in Germany seeking premium reimbursement differentials for bladeless procedures.
- Refractive Laser:Compact tabletop configurations prioritize corneal flap precision and astigmatic keratotomy for standalone LASIK practices.
- Surgical Laser:Multi-application systems support resident training protocols through modular docking adapters for corneal, lenticular, and glaucoma procedures.
Laser cataract surgery systems absorb the bulk of installed capacity; refractive laser configurations are expanding most quickly among independent practices in Japan.
End User:
Capital commitment thresholds and procedure volume economics determine which user categories drive replacement cycles versus greenfield adoption.
- Hospitals:Integrated health systems in Texas and California deploy femtosecond suites across multiple operating rooms to maximize equipment utilization rates. These networks negotiate enterprise service agreements with manufacturers to standardize maintenance protocols.
- Eye Clinics:Independent specialty practices in Mumbai and Delhi target medical tourism segments with premium femtosecond-assisted refractive packages. Leasing structures and per-procedure financing lower entry barriers for mid-sized groups.
- Academic Institutions:Heidelberg and Boston medical centers deploy intraoperative OCT-guided systems for resident competency standardization.
- Research Laboratories:Photonics research facilities in Germany develop next-generation pulse compression architectures for clinical translation.
Hospitals absorb the bulk of installed capacity; eye clinics are gaining share fastest in outpatient expansion markets.
Technology:
Intellectual property concentration in solid-state and ultrafast architectures shapes competitive differentiation and licensing revenue streams.
- Ultrafast Laser:Titanium-sapphire and ytterbium-doped fiber oscillators generate sub-500 femtosecond pulses through chirped pulse amplification. Japanese manufacturers lead commercialization of compact fiber architectures for ophthalmic integration.
- Picosecond Laser:Extended pulse durations between 1-10 picoseconds target tattoo removal and dermatological applications with limited ophthalmic penetration.
- Nanosecond Laser:Q-switched solid-state systems deliver microjoule-level energies for posterior capsulotomy with higher thermal collateral than femtosecond alternatives.
- Solid-State Laser:Diode-pumped Nd:YAG and Er:YAG configurations provide wavelength flexibility for corneal and lenticular procedures through optical parametric amplification.
Ultrafast laser technology commands the dominant installed base; solid-state architectures are climbing fastest in multi-wavelength platform development.
Application:
Reimbursement differentials and clinical outcome data determine which procedures justify capital equipment investment against manual technique alternatives.
- Cataract Surgery:Femtosecond-assisted anterior capsulotomy and lens fragmentation reduce effective phacoemulsification time. United States hospital networks face CMS reimbursement compression narrowing fee differentials versus manual techniques.
- LASIK:Corneal flap creation represents the most mature femtosecond application with established visual outcome superiority over mechanical microkeratomes. Post-pandemic elective procedure backlogs in Germany are clearing replacement cycles for aging platforms.
- Corneal Surgery:Femtosecond arcuate incisions and intrastromal ring channel creation address keratoconus and astigmatism in tertiary referral centers.
- Glaucoma Treatment:Laser trabeculotomy and sclerotomy applications are emerging as micro-invasive glaucoma surgery alternatives with limited competitive device saturation.
Cataract surgery absorbs the bulk of installed capacity; glaucoma treatment is expanding most quickly among subspecialty practices seeking procedure diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-affiliated ambulatory surgical centers in the United States, Germany, and Japan concentrate installed femtosecond laser capacity, while corporate hospital chains in India and medical tourism hubs in the UAE accelerate greenfield adoption.
United States
Integrated health systems in Texas and California deploy femtosecond suites across multiple operating rooms to maximize utilization rates. FDA 510(k) clearance pathways require clinical validation of incision precision metrics before commercial access. Metropolitan surgical centers in Dallas and Houston negotiate enterprise service agreements with manufacturers to standardize maintenance protocols across high-volume cataract networks.
Germany
Hospital-affiliated networks in Bavaria and North Rhine-Westphalia seek premium reimbursement differentials for bladeless cataract procedures. EU MDR conformity assessment deadlines through 2026 accelerate procurement of CE-marked systems ahead of legacy device retirements. Heidelberg University Hospital deploys intraoperative OCT-guided platforms for resident competency standardization in corneal and refractive surgery training.
Japan
Mid-sized ophthalmology groups in Tokyo and Osaka adopt per-procedure leasing structures to lower capital entry barriers. METI industrial standards govern photonics equipment quality assurance for clinical laser systems. Academic medical centers in Nagoya integrate femtosecond platforms with UV-A cross-linking modules for keratoconus treatment protocols.
India
Corporate hospital chains in Mumbai and Delhi deploy femtosecond platforms for premium refractive packages targeting medical tourism segments. CDSCO medical device regulations require import licensing and local clinical trial data for laser cataract systems. Outpatient expansion in Bangalore and Chennai drives demand for compact tabletop configurations suited to independent specialty practices.
United Arab Emirates
Private ophthalmology networks in Dubai and Abu Dhabi invest in femtosecond-assisted LASIK and cataract suites for premium expatriate and medical tourism markets. MOHAP facility licensing mandates equipment calibration protocols and technician certification for laser surgery centers. Healthcare free zones in Dubai Healthcare City attract multinational manufacturers establishing regional service hubs for Gulf Cooperation Council markets.
Ophthalmic Femtosecond Lasers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated diagnostic-laser platforms and subscription financing models. The vendor base stratifies across three maturity tiers: diversified medical technology conglomerates with integrated cataract-refractive portfolios, specialized ophthalmic laser manufacturers with proprietary photonics architectures, and regional equipment distributors with localized service capabilities. Dominant competitive moves include strategic partnerships between laser manufacturers and diagnostic imaging developers, plus geographic expansion through distributor networks in Asia-Pacific outpatient markets.
Within the diversified medical technology tier, Alcon Inc., Johnson & Johnson Surgical Vision Inc., and Carl Zeiss Meditec AG exemplify contrasting strategic positions. Alcon Inc. anchors recurring revenue capture through consumable-integrated platform ecosystems. Johnson & Johnson Surgical Vision Inc. occupies a position emphasizing global service density and surgeon training infrastructure. Carl Zeiss Meditec AG represents premium-tier differentiation through proprietary optical coherence tomography-guided laser platforms. Specialized manufacturers including Ziemer Ophthalmic Systems AG and LENSAR Inc. sit within the mid-tier, while SCHWIND eye-tech-solutions GmbH exemplifies German photonics engineering concentration in compact refractive system design.
| Leading Market Players |
|---|
| Bausch & Lomb Incorporated |
| Ziemer Ophthalmic Systems AG |
| Johnson & Johnson Surgical Vision Inc. |
| IMRA America, Inc. |
| Abbott Medical Optics |
| Alcon Inc. |
| LENSAR Inc. |
| SCHWIND eye-tech-solutions GmbH |
| Carl Zeiss Meditec AG |
| Others |
Cost & Logistics Intelligence
EU MDR post-market surveillance mandates for active implantable medical devices gate qualified supply access and premium-tier pricing for femtosecond laser manufacturers serving European hospital networks. Compliance investment requirements stratify vendor tiers, with CE-marked systems commanding service contract premiums against non-compliant legacy platforms facing accelerated retirement.
Pricing Analysis
High-volume cataract networks absorb capital equipment at compressed margins while standalone refractive practices sustain premium pricing for compact tabletop configurations. Three-tier pricing structure across premium OCT-integrated, standard femtosecond-only, and economy refurbished platforms reflects certification grade and after-sales bundling intensity. Pricing pressure stems from CMS reimbursement compression narrowing fee differentials for femtosecond-assisted versus manual cataract extraction in United States hospital systems. Independent eye clinics in India exhibit highest price sensitivity; academic medical centers in Germany demonstrate lowest sensitivity due to training protocol standardization requirements.
Supply Chain Analysis
Biomedical engineer scarcity in photonics-specialized labor markets constrains manufacturing scale-up across German and Japanese production hubs. Solid-state resonator architectures and ytterbium-doped fiber oscillators draw from concentrated precision optics suppliers in Jena and Hamamatsu. Single-source vulnerability for titanium-sapphire crystal substrates creates procurement risk during geopolitical trade disruptions. Distribution runs through manufacturer-direct service contracts for hospital-affiliated networks, with regional distributors covering independent specialty practices in Asia-Pacific outpatient markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ophthalmic femtosecond laser market operates as a vertical-integration race where control over consumable disposables and proprietary OCT data formats determines recurring revenue capture against capital-sale competitors.
For Market Incumbents: Cement platform ecosystem lock-in through proprietary docking interfaces that block third-party consumable substitution. Expand backward integration into ytterbium fiber oscillator production to insulate against Hamamatsu supplier concentration. Alcon and Carl Zeiss Meditec anchor defensive positions through integrated cataract-refractive portfolios that raise switching costs for ambulatory surgical center networks.
For New Entrants and Emerging Players: Launch via subscription financing models targeting mid-sized ophthalmology groups in Japan and corporate hospital chains in India seeking per-procedure cost structures without capital commitment. White-space concentration sits in glaucoma angle procedures and corneal cross-linking integration where competitive device saturation remains limited. Prioritize regulatory fast-follower positioning behind FDA-cleared platforms to compress time-to-revenue.
For Investors and Strategic Acquirers: EU MDR notified body capacity constraints extending conformity assessment timelines is the leading indicator that regulatory execution capability will separate viable platforms from stranded assets. Acquisition targets should display ISO 13485 quality management maturity and established clinical follow-up data infrastructure for post-market surveillance compliance. Monitor FDA 510(k) clearance velocity for femtosecond-assisted glaucoma applications as inflection signal for procedure expansion beyond cataract and LASIK saturation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment acceleration captures hospital procurement ahead of legacy device retirements in Germany. |
| Hospital System Partnership | Enterprise service agreements with Texas and California integrated networks standardize maintenance protocols across multiple operating rooms. |
| Software Companion Development | Cloud-connected maintenance platforms compress feedback loops between surgical outcomes and equipment calibration in academic medical centers. |
| Reimbursement Strategy | CMS fee schedule advocacy defends margin structures for femtosecond-assisted cataract against manual technique compression. |
| Backward Integration | In-house production of ytterbium-doped fiber oscillators reduces dependency on Japanese photonics suppliers for pulse generation architectures. |
Research Approach
Multi-period observation of femtosecond laser installed base migrations, service contract restructuring patterns, and reimbursement threshold shifts anchored the trend analysis, supplemented by interviews with cataract network procurement directors, biomedical engineering leads at academic medical centers, ophthalmic laser service technicians, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, hospital procurement databases, and CMS Medicare fee schedule filings. Bottom-up equipment shipment tracking and top-down ambulatory surgical center capacity modeling were triangulated against manufacturer-reported service contract values.
Segment-weighting across product type, application, end user, and technology dimensions shaped volume and value projections throughout the forecast period. CAGRs were derived from replacement cycle analysis for aging excimer platforms, EU MDR transition procurement acceleration curves, and outpatient expansion rates in Asia-Pacific medical tourism hubs. Industry-specific inputs incorporated phacoemulsification handpiece attach rates, per-procedure leasing adoption velocity, and intraoperative OCT integration penetration in resident training protocols.
Regulatory timeline delays, reimbursement compression acceleration, and photonics component supply disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding EU MDR transition completion, CMS fee schedule stability, and Japanese METI standards harmonization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Tonometry Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Ophthalmic Photocoagulator Market