
 India Ophthalmic Clinical Trials Market | 2026-2036
India Ophthalmic Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
India Ophthalmic Clinical Trials Market Insights
Contract research organizations serving biopharma sponsors is expanding as domestic and multinational drug developers intensify ophthalmology pipelines. Veeda Clinical Research leverages its Bengaluru-Goa operational network to anchor Phase II-III glaucoma studies. IQVIA Holdings Inc competes through integrated real-world evidence platforms that extend trial design capabilities. Catalyst Clinical Services Pvt. Ltd. specializes in investigator-initiated studies across South Indian hospital networks.
Ophthalmic clinical trials comprise structured investigations of drugs, devices, and biological therapies targeting ocular diseases, typically requiring visual acuity endpoints, optical coherence tomography biomarkers, and slit-lamp examination protocols under Good Clinical Practice standards. Phase III studies command the largest value share due to multi-site recruitment complexity and regulatory submission requirements for novel anti-VEGF agents and sustained-release implants. Diabetic retinopathy indication trials represent the fastest-expanding segment as India's diabetes prevalence drives sponsor investment in retinal vascular disease therapies.
CDSCO governs trial approvals through the New Drugs and Clinical Trials Rules while ICMR ethical guidelines mandate institutional review board oversight and informed consent protocols for vulnerable populations. BIS standards for ophthalmic device testing and state-level pharmacy councils shape investigational product handling requirements across Maharashtra, Gujarat, and Karnataka. Stakeholders must monitor CDSCO's evolving digital trial submission portal and state-specific clinical establishment regulations to secure site activation timelines.
Market Dynamics
CDSCO's 2019 New Drugs and Clinical Trials Rules eliminated local clinical trial requirements for drugs approved in regulated markets, compressing sponsor timelines and redirecting investment toward Phase II-III replication studies across Maharashtra and Telangana hospital networks.
Growth Catalysts
- PLI Scheme for Pharmaceuticals:Production-linked incentives for active pharmaceutical ingredients and drug intermediates reduce import dependency for anti-VEGF compounds used in retinal trials.
- Diabetes Epidemiology:India's diabetic population concentration creates natural recruitment pools for diabetic retinopathy studies, cutting per-patient acquisition costs versus Western sites.
- Tele-ophthalmology Infrastructure:State-funded rural screening programs in Karnataka and Tamil Nadu generate referral pipelines that CROs tap for site activation.
Market Restraints
- Import Duty Structure:DGFT tariff classifications for optical coherence tomography devices inflate capital expenditure for investigative sites in tier-two cities.
- Ethics Committee Backlog:Institutional review board capacity constraints at medical colleges in Gujarat and Rajasthan extend protocol approval timelines.
- Comparator Drug Sourcing:Domestic manufacturing gaps for reference biologics force sponsors to import ranibizumab and aflibercept, exposing trials to currency volatility.
Strategic Opportunities
- East India Expansion:West Bengal and Odisha ophthalmology departments at medical colleges remain undercontracted relative to South Indian site density.
- Gene Therapy Pipelines:Leber congenital amaurosis and inherited retinal dystrophy programs require specialized vitreoretinal surgical capabilities that few Asian sites possess.
- Digital Trial Submission Portal:CDSCO's SUGAM platform enables electronic protocol amendments, reducing administrative site burden for multi-center studies.
Industry Challenges
- Principal Investigator Bandwidth:Senior vitreoretinal specialists at Aravind Eye Hospital and Sankara Nethralaya face competing demands between clinical service, surgery, and trial oversight.
- Good Clinical Practice Certification:Site staff training gaps in ICH-GCP standards require sponsor-funded remediation programs before regulatory inspection readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Ophthalmic Clinical Trials Market |
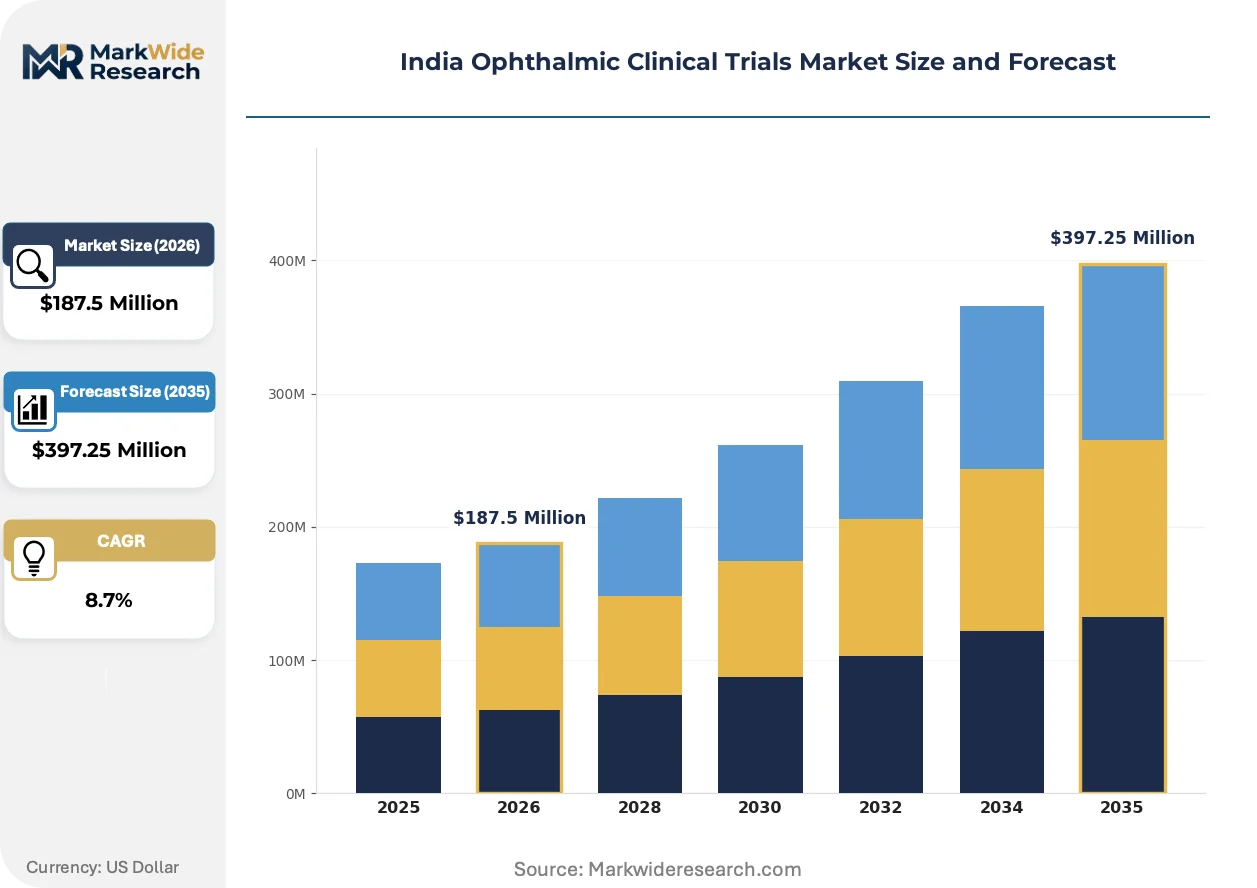
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $397.25 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Phase: Phase I, Phase II, Phase III, Phase IV Indication: Glaucoma, Cataract, Diabetic Retinopathy, Age-related Macular Degeneration Study Design: Randomized, Open-label, Double-blind, Cross-sectional Participant Demographics: Adults, Seniors, Pediatrics, Women |
| Companies Covered | ProRelix Services LLP, Abiogenesis Clinpharm Pvt Ltd., Veeda Clinical Research, IQVIA Holdings Inc, Charles River Laboratories International Inc, Icon PLC, Catalyst Clinical Services Pvt. Ltd., Navitas Life Sciences, Vimta Labs Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Ophthalmic Clinical Trials Market Trends and Innovations
Adaptive trial designs and decentralized data capture are compressing traditional ophthalmology study timelines while raising the technical bar for site infrastructure across Indian metropolitan hospital networks.
Artificial intelligence-based image analysis for diabetic retinopathy grading is rewriting endpoint adjudication workflows. Contract research organizations deploy machine learning algorithms to automate optical coherence tomography thickness measurements, reducing central reading center backlogs. Biopharma sponsors adopting these tools compress database lock timelines by eliminating manual segmentation bottlenecks.
CDSCO's 2023 guidance on post-trial access mandates sponsors provide continued therapy to participants after study completion. This obligation alters budget modeling for anti-VEGF trials requiring monthly injections over two-year follow-up periods. Maharashtra and Karnataka sites now negotiate extended supply agreements during contract execution rather than protocol amendment stages.
Hospital-based principal investigators increasingly prefer risk-sharing fee structures over per-patient payments. This procurement evolution transfers budget variance risk to CROs while aligning site activation incentives with enrollment velocity. Bengaluru's ophthalmology CRO corridor exhibits the most pronounced shift, with sponsors accepting milestone-based contracts to secure preferred investigator access.
India Ophthalmic Clinical Trials Market Segmentation
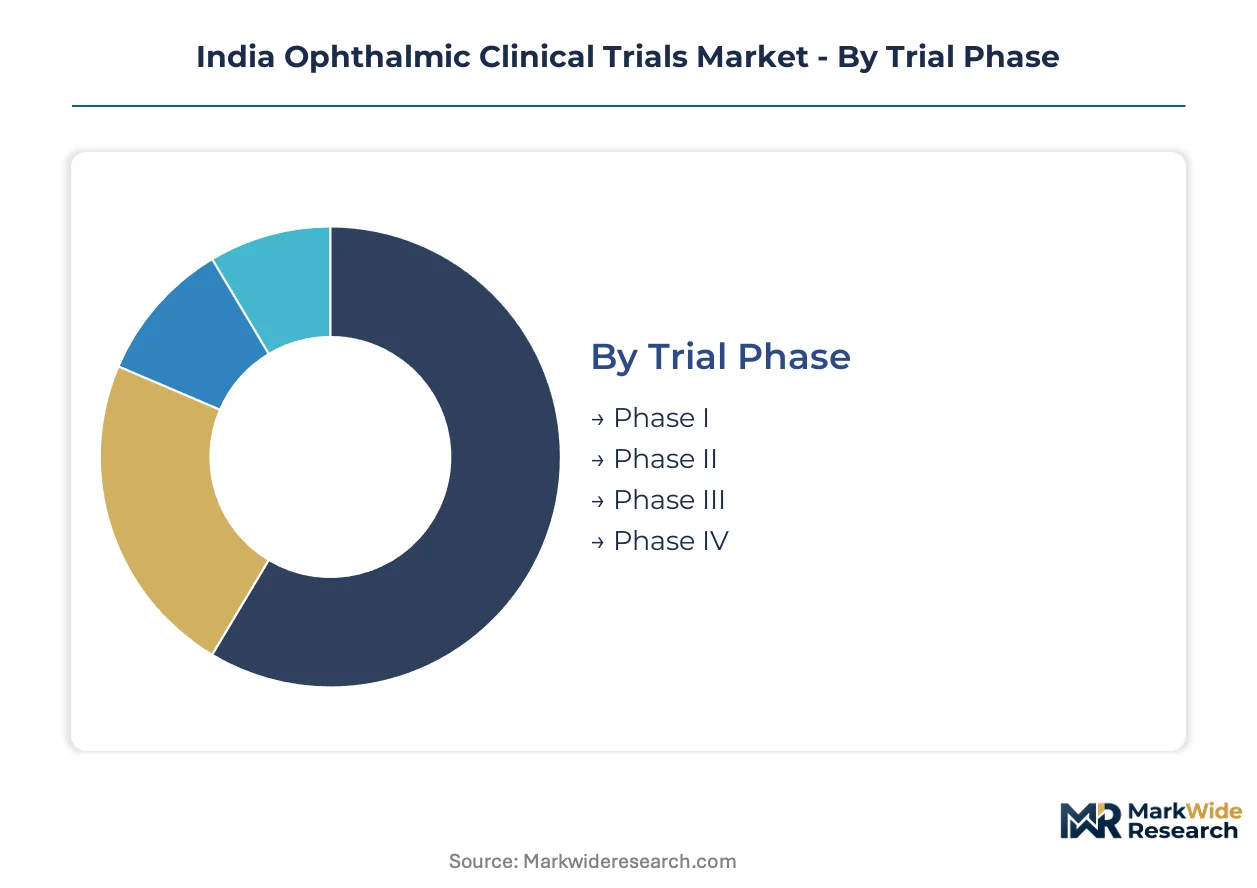
Ophthalmic clinical trials in India fragment across trial phases, disease indications, methodological designs, and participant cohorts. Each dimension shapes site selection, regulatory pathways, and sponsor investment allocation across Maharashtra, Telangana, and Karnataka hospital networks.
Trial Phase:
Phase distribution determines whether trials operate as standalone first-in-human studies or embed within larger multi-phase development programs.
- Phase I:First-in-human safety and pharmacokinetic studies for novel anti-VEGF compounds and sustained-release implants. Demand concentrates at specialized units within Bengaluru's ophthalmology CRO corridor where CDSCO fast-track approvals accelerate dose-escalation timelines.
- Phase II:Efficacy signal detection and dose-ranging investigations across moderate patient populations. Maharashtra and Telangana hospital networks attract sponsor investment due to established diabetic retinopathy patient registries that streamline recruitment for vascular endpoint studies.
- Phase III:Pivotal registration trials requiring multi-site coordination and statistical powering for regulatory submission.
- Phase IV:Post-marketing surveillance and comparative effectiveness studies conducted under real-world conditions.
Phase III commands the largest sponsor budgets today; Phase II is climbing the fastest as biopharma pipelines mature.
Indication:
Disease focus shapes endpoint selection, imaging infrastructure requirements, and investigator specialization needs across Indian sites.
- Diabetic Retinopathy:Retinal vascular disease studies leveraging India's diabetes epidemiology for natural recruitment pools. Karnataka and Tamil Nadu tele-ophthalmology screening programs generate referral pipelines that cut per-patient acquisition costs versus Western comparator sites.
- Glaucoma:Intraocular pressure reduction and visual field progression trials requiring automated perimetry and optical coherence tomography retinal nerve fiber layer analysis. Bengaluru-Goa operational networks anchor specialized Phase II-III studies for novel prostaglandin analogues and sustained-release implants.
- Cataract:Intraocular lens safety and visual performance investigations following phacoemulsification procedures.
- Age-related Macular Degeneration:Geographic atrophy and neovascular AMD studies requiring fluorescein angiography and anti-VEGF comparator arms.
Diabetic retinopathy leads trial volumes today; gene therapy pipelines for inherited retinal dystrophies are expanding most quickly.
Study Design:
Methodological rigor tiers separate registration-grade trials from exploratory investigations across Indian investigative sites.
- Double-blind:Masked randomized controlled trials with sham injection or placebo device arms for anti-VEGF and sustained-release implant registration. CDSCO's SUGAM platform enables electronic protocol amendments that reduce administrative burden for complex masking procedures across multi-center studies.
- Randomized:Controlled allocation studies comparing active treatment against standard-of-care or approved comparators.
- Open-label:Unmasked safety and pharmacokinetic investigations where blinding is impractical for surgical interventions or device implantations.
- Cross-sectional:Single-timepoint observational studies capturing disease prevalence, biomarker correlations, or diagnostic accuracy metrics.
Double-blind designs dominate Phase III budgets today; adaptive and decentralized methodologies are gaining sponsor preference fastest.
Participant Demographics:
Population targeting shapes inclusion criteria complexity, informed consent protocols, and site accessibility requirements across India's heterogeneous patient base.
- Seniors:Age-related disease studies for cataract, glaucoma, and macular degeneration requiring modified consent procedures and caregiver involvement. Ethics committee capacity constraints at Gujarat and Rajasthan medical colleges extend approval timelines for vulnerable population protections.
- Adults:Working-age cohorts for diabetic retinopathy and occupational eye disease investigations with standard informed consent frameworks.
- Pediatrics:Childhood strabismus, amblyopia, and inherited retinal dystrophy studies mandating parental consent and assent protocols under ICMR ethical guidelines.
- Women:Sex-specific subgroup analyses and pregnancy registry studies for teratogenicity surveillance.
Adult recruitment fills most trial slots today; pediatric gene therapy investigations for Leber congenital amaurosis are expanding enrollment fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's streamlined approval framework creates cost-of-compliance arbitrage that redirects sponsor investment from Western regulatory jurisdictions toward Indian investigative sites. Maharashtra and Karnataka hospital networks capture the bulk of Phase III ophthalmology studies as domestic CROs build specialized capabilities faster than competitors in regulated markets.
Maharashtra
Aravind Eye Hospital's Mumbai satellite and state medical college networks drive diabetic retinopathy recruitment through established diabetes patient registries. CDSCO's New Drugs and Clinical Trials Rules enable faster protocol amendments for multi-center anti-VEGF studies. Mumbai-Pune corridor concentrates CRO operations serving both domestic biopharma and multinational sponsors.
Karnataka
Bengaluru's ophthalmology CRO corridor anchors Phase II-III glaucoma and sustained-release implant trials leveraging tele-ophthalmology referral pipelines. State-funded rural screening programs in Karnataka and Tamil Nadu generate patient flows that cut per-patient acquisition costs. Veeda Clinical Research operates across Bengaluru-Goa networks to capture site activation demand.
Telangana
Hyderabad's biopharma manufacturing base creates sponsor proximity for ophthalmic drug development programs targeting retinal vascular diseases. CDSCO's SUGAM platform enables electronic submissions that compress site activation timelines relative to paper-based systems. State medical colleges attract investigator-initiated studies through streamlined ethics committee frameworks.
Gujarat
Ahmedabad and Surat ophthalmology departments face ethics committee capacity constraints that extend protocol approval timelines for vulnerable population protections. DGFT tariff classifications for optical coherence tomography devices inflate capital expenditure for investigative sites in tier-two cities. Gujarat sites specialize in cataract intraocular lens safety studies following phacoemulsification procedures.
Tamil Nadu
Sankara Nethralaya's Chennai headquarters competes for principal investigator bandwidth between clinical service and trial oversight obligations. State tele-ophthalmology infrastructure generates referral pipelines for diabetic retinopathy studies across rural screening catchments. Tamil Nadu sites negotiate risk-sharing fee structures that transfer budget variance risk to sponsoring CROs.
India Ophthalmic Clinical Trials Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service CROs commanding Phase III budgets while niche investigators capture early-phase signal detection work. The vendor base organizes around three archetypes: integrated global networks, domestic mid-cap specialists, and hospital-affiliated academic research organizations. Consolidation pressure operates through strategic partnerships rather than outright acquisition as sponsors prioritize investigator relationships over scale. Geographic expansion into East India and gene therapy capability building represent the dominant competitive moves.
Among domestic mid-cap specialists, Veeda Clinical Research, Catalyst Clinical Services Pvt. Ltd., and ProRelix Services LLP occupy positions shaped by regional site density and therapeutic focus. Veeda exemplifies the Bengaluru-Goa operational model that anchors South Indian glaucoma studies. Catalyst represents the investigator-initiated study specialist archetype embedded within hospital networks. ProRelix sits within the emerging tier of Mumbai-Pune corridor operators competing for Maharashtra sponsor contracts.
| Leading Market Players |
|---|
| ProRelix Services LLP |
| Abiogenesis Clinpharm Pvt Ltd. |
| Veeda Clinical Research |
| IQVIA Holdings Inc |
| Charles River Laboratories International Inc |
| Icon PLC |
| Catalyst Clinical Services Pvt. Ltd. |
| Navitas Life Sciences |
| Vimta Labs Ltd. |
| Others |
Pricing and Supply Chain Analysis
A three-tier pricing structure across premium, standard, and economy levels governs India ophthalmic clinical trials, with CDSCO fast-track certification and ICH-GCP compliance status determining which tier sponsors occupy and which investigative sites they can access. Premium-tier CROs command risk-sharing contracts at Aravind Eye Hospital and Sankara Nethralaya, while economy operators compete on per-patient fees at state medical colleges with extended ethics committee timelines.
Pricing Analysis
Distributor margins for comparator drug sourcing compress sponsor budgets, as reference biologics like ranibizumab and aflibercept flow through import-dependent channels with currency exposure. Project-based pricing dominates Phase II-III studies, with price differentiation driven by principal investigator reputation and optical coherence tomography infrastructure grade. Cost compression in economy-tier site activation is intensifying because ethics committee backlogs at Gujarat and Rajasthan medical colleges force sponsors to pay premium expedite fees. Domestic biopharma sponsors exhibit highest price sensitivity; multinational sponsors prioritize speed over per-patient economics.
Supply Chain Analysis
Refurbished optical coherence tomography devices from Germany and Japan circulate through secondary markets, extending equipment lifecycles for tier-two city investigative sites that cannot absorb new capital expenditure. Active pharmaceutical ingredients for anti-VEGF compounds draw from India and China manufacturing bases under PLI scheme incentives, while sustained-release implant components rest on US and European specialty polymer suppliers. Single-source vulnerability concentrates in reference biologic comparators, exposing trials to DGFT tariff reclassification risk. Distribution runs through Mumbai-Pune and Bengaluru-Goa CRO corridors to hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India ophthalmic clinical trials function as a regulatory compounder where CDSCO's 2019 New Drugs and Clinical Trials Rules elimination of local trial requirements created sustained sponsor inflow.
For Market Incumbents: Deploy investigator relationship lock-in through exclusive site access agreements at Aravind Eye Hospital and Sankara Nethralaya. Incumbents should deepen backward integration into tele-ophthalmology screening infrastructure, capturing patient referral pipelines that emerging CROs cannot replicate. Gene therapy pipeline sponsors pose substitution threat to anti-VEGF service lines. For New Entrants and Emerging Players: Tier-two city ophthalmology departments at Gujarat and Rajasthan state medical colleges represent the most penetrable site archetype. New entrants should anchor East India expansion into West Bengal and Odisha, where principal investigator bandwidth exceeds South Indian saturation. Go-to-market positioning as ethics committee navigation specialists addresses the dominant site activation bottleneck. For Investors and Strategic Acquirers: Consolidation pressure builds where gene therapy capabilities concentrate in fewer than five Asian sites. Investors should frame long-term viability around CDSCO digital trial infrastructure adoption curves, targeting acquisition profiles of Bengaluru-Goa corridor CROs with sustained-release implant surgical capabilities. The signal to watch is CDSCO SUGAM platform utilization rates as site efficiency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Capability Buildout | Leber congenital amaurosis pipelines require vitreoretinal surgical infrastructure that few Indian sites possess. |
| Tele-Ophthalmology Integration | Karnataka state-funded rural screening programs generate patient flows that compress per-patient acquisition costs. |
| CDSCO Digital Submission Adoption | SUGAM platform utilization reduces administrative burden for multi-center protocol amendments. |
| East India Site Network Expansion | West Bengal and Odisha medical colleges remain undercontracted relative to South Indian density. |
| Risk-Sharing Contract Structuring | Milestone-based agreements align CRO incentives with enrollment velocity at Tamil Nadu sites. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Telangana, Gujarat, and Tamil Nadu, with primary inputs from each region's ophthalmology CRO corridor. The analysis combines primary interviews with drug development executives, regulatory affairs leads at CDSCO, hospital procurement managers, and principal investigators at Aravind Eye Hospital and Sankara Nethralaya with secondary validation from ClinicalTrials.gov, CDSCO SUGAM platform disclosures, ICMR ethical guidelines, and state medical college procurement records. Bottom-up site capacity modeling and top-down sponsor pipeline analysis triangulate market sizing.
Rate-of-change decomposition separates trial phase maturation effects from regulatory framework shifts and sponsor geographic reallocation decisions across the analysis window. Segmentation dimensions include trial phase, disease indication, study design methodology, and participant demographic cohort. CAGRs derive from sponsor pipeline tracking and site activation velocity modeling, with diabetic retinopathy epidemiology and PLI scheme API manufacturing incentives as sector-specific forecast inputs.
Underlying measurement precision varies by segment; Phase III multi-site trials carry tighter precision than Phase I first-in-human studies due to public disclosure requirements. Forecasts reflect assumptions about CDSCO approval velocity, ethics committee capacity expansion, and comparator drug import tariff stability. Practitioners should monitor CDSCO guidance on post-trial access obligations and DGFT optical coherence tomography device classifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Astigmatism Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Ophthalmic Eye Drops Market