
 Ophthalmic Clinical Trials Market | 2026-2036
Ophthalmic Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Clinical Trials Market Analytics
Good Clinical Practice certification under ICH E6(R2) is bifurcating the ophthalmic CRO landscape into audit-ready global operators and regional specialists struggling with investigator-site qualification. IQVIA Holdings Inc. leverages its Real-World Evidence platform to anchor recruitment for retina disorder studies across its site network. Parexel International Corporation sustains competitive position through therapeutic depth in glaucoma and corneal disease protocols. Charles River Laboratories International Inc. differentiates via preclinical-to-clinical continuity in ocular toxicology and Phase I bridging studies.
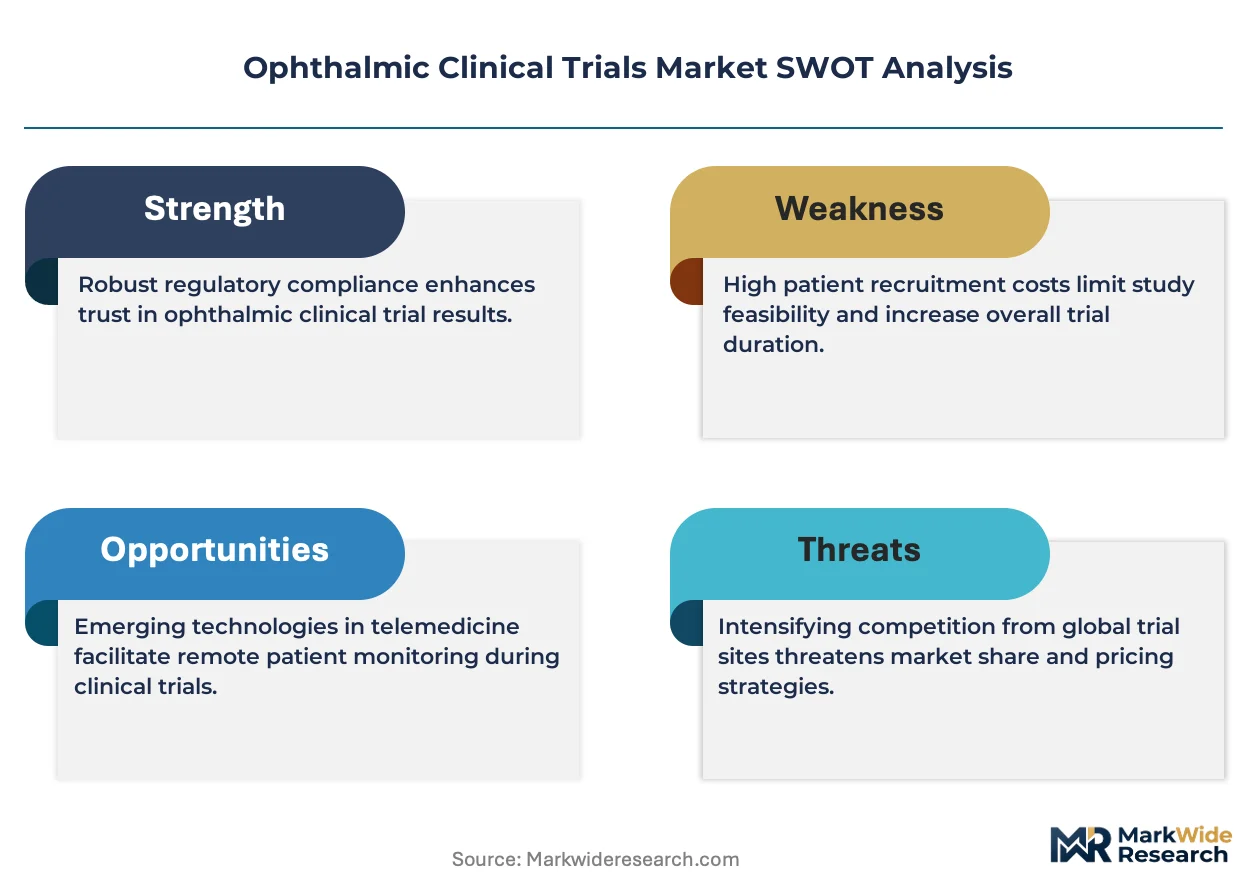
Ophthalmic clinical trials constitute regulated research programs evaluating safety, efficacy, and pharmacokinetics of interventions for vision-threatening diseases, typically requiring specialized endpoints such as best-corrected visual acuity, optical coherence tomography metrics, and microperimetry thresholds to satisfy regulatory scrutiny. Phase III protocols dominate value capture given their multi-center scale and pivotal regulatory weight, while gene therapy trials represent the fastest-expanding product category as adeno-associated viral vectors advance through pipelines for inherited retinal dystrophies. Device trials for sustained-release drug delivery implants occupy a mature, margin-defended niche with established predicate pathways.
FDA ophthalmology division reviews and EMA's Committee for Medicinal Products for Human Use jointly shape trial design through guidance on acceptable endpoints for geographic atrophy and diabetic macular edema, directly influencing protocol complexity and duration. ICH E6(R3) revisions will force sponsors to revalidate quality management systems across decentralized and hybrid trial modalities. Stakeholders must monitor how FDA's Project Optimus dose-optimization mandate propagates into ophthalmic oncology and gene therapy protocols.
Market Dynamics
Adaptive trial designs for retinal gene therapies are compressing protocol timelines and forcing contract research organizations to restructure investigator-site qualification workflows around decentralized data capture capabilities.
Growth Catalysts
- FDA Expanded Access Pathways:These regulatory mechanisms accelerate patient enrollment for orphan ophthalmology programs, reducing recruitment bottlenecks in inherited retinal dystrophy studies.
- Optical Coherence Tomography Biomarkers:Quantitative imaging endpoints enable smaller sample sizes in pivotal trials, lowering development costs for geographic atrophy interventions.
- Japan's PMDA Sakigake Designation:Priority review status for regenerative medicines draws biopharmaceutical sponsors to Tokyo-Osaka site clusters for first-in-human ocular gene therapy protocols.
Market Restraints
- Adeno-Associated Viral Vector Manufacturing:Viral payload production concentrates at three contract manufacturing organizations worldwide, creating supply vulnerability for Phase III gene therapy programs.
- ICH E6(R3) Compliance Costs:Revised quality management standards force sponsors to revalidate electronic data capture systems, adding twelve to eighteen months to protocol startup timelines.
- Retinal Specialist Scarcity:Fellowship-trained investigators cluster in Boston, Basel, and Singapore, limiting site expansion into Eastern Europe and Latin America.
Strategic Opportunities
- EMA PRIME Designation:Priority medicines status offers accelerated assessment and enhanced regulatory dialogue for pediatric retinal disease therapies, attracting sponsor investment to European site networks.
- Microperimetry-Functional Vision Endpoints:Convergence of retinal imaging with patient-reported outcome measures enables novel primary endpoints for geographic atrophy trials, differentiating protocols from legacy visual acuity designs.
- Decentralized Ocular Assessment:Home-based visual function testing via smartphone applications expands recruitment beyond traditional academic medical centers into community ophthalmology practices across Germany.
Industry Challenges
- Gene Therapy Vector Immunogenicity:Pre-existing neutralizing antibodies against AAV serotypes exclude thirty to fifty percent of screening candidates, forcing sponsors to maintain larger screening pools.
- Real-World Evidence Integration:Merging electronic health record data with clinical trial databases requires reconciliation of disparate ophthalmic imaging formats across vendor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Clinical Trials Market |
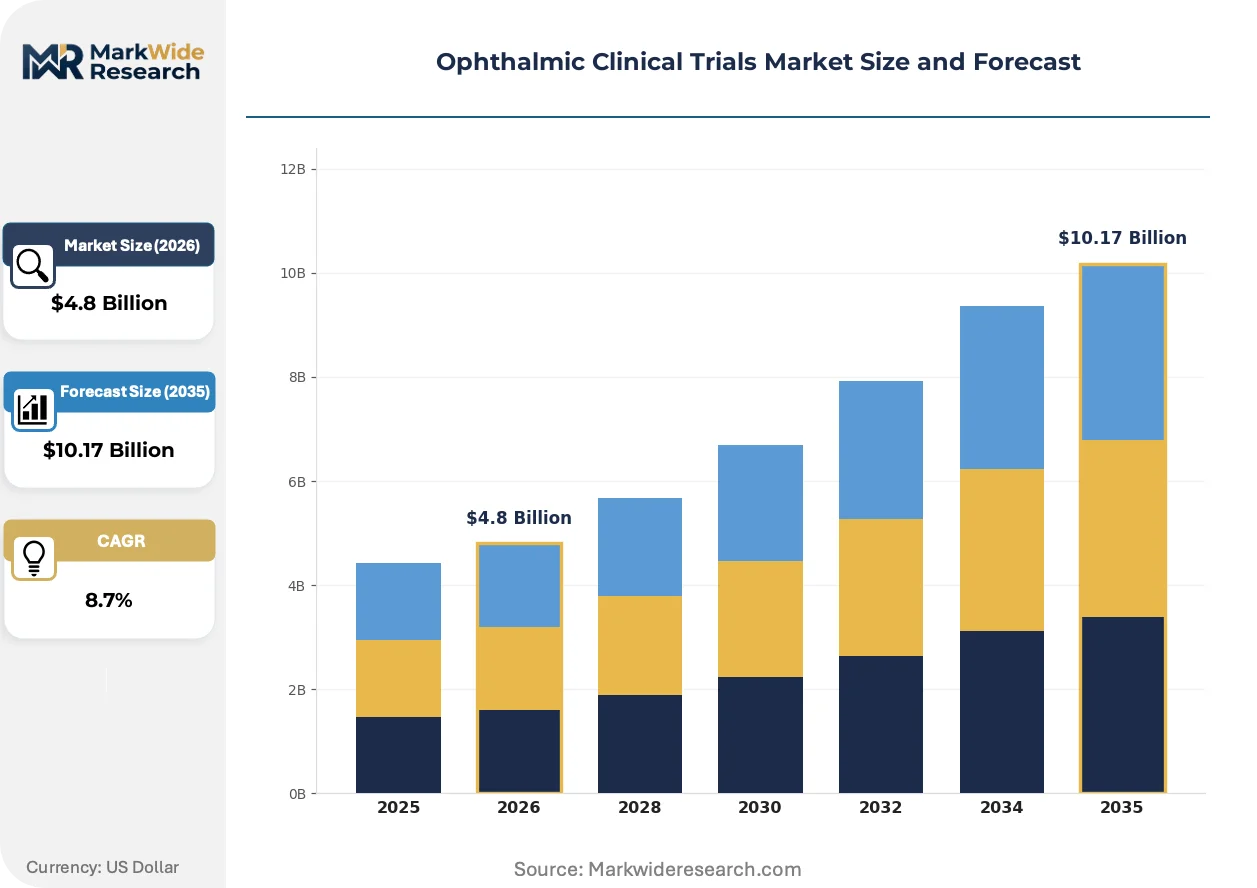
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Type: Phase I, Phase II, Phase III, Phase IV Product Type: Drugs, Devices, Diagnostics, Gene Therapy Indication: Glaucoma, Cataract, Retina Disorders, Corneal Diseases Recruitment Method: Volunteer-based, Patient Referral, Online Advertising, Direct Outreach |
| Companies Covered | Parexel International Corporation, ICON plc, IQVIA Holdings Inc., Medpace, PPD (Thermo Fisher Scientific), Syneos Health, Iris Pharma, Laboratory Corporation of America Holdings, Charles River Laboratories International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Clinical Trials Market Evolving Landscape
Digital biomarker acquisition and decentralized trial modalities are restructuring how ocular efficacy data is captured, validated, and submitted to regulatory authorities across the development lifecycle.
Artificial intelligence-enabled image analysis is bifurcating endpoint adjudication workflows in retina disorder trials. Large ophthalmology CROs deploy machine learning algorithms for automated optical coherence tomography segmentation, compressing central reading center timelines from weeks to days. Mid-tier regional operators lacking computational infrastructure face margin compression as sponsors mandate AI-validated endpoint packages for FDA submissions.
EMA's PRIME designation scheme is accelerating regulatory dialogue timelines for advanced therapy medicinal products in ophthalmology. Sponsors receive scientific advice at Day 150 of development, enabling earlier protocol optimization for inherited retinal disease gene therapies. German and Dutch regulatory agencies report forty percent faster assessment completion for PRIME-eligible ocular programs versus standard pathways.
Site selection criteria now prioritize integrated electronic health record networks over standalone investigator experience. Biopharmaceutical sponsors in the United States contract with health system alliances spanning multiple states, replacing single academic center dependencies. Kaiser Permanente and Intermountain Healthcare site networks capture geographic atrophy progression data from routine clinical care, blurring boundaries between interventional trials and observational registries.
Ophthalmic Clinical Trials Market Segmentation
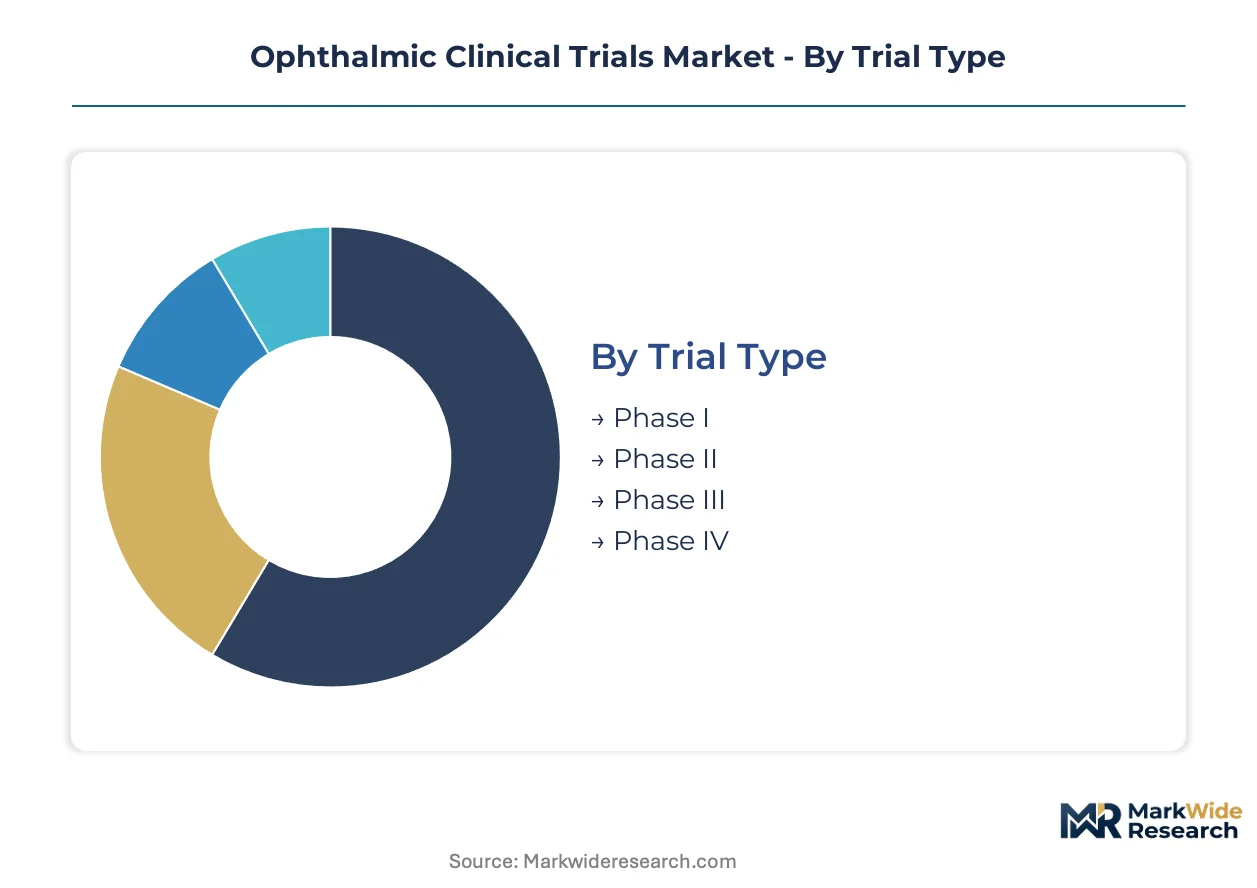
Ophthalmic clinical trial segmentation reveals how protocol complexity, therapeutic modality, and patient access strategies reshape competitive positioning across the development lifecycle. Trial sponsors deploy differentiated segment strategies to align regulatory pathways with site capabilities and recruitment economics.
Trial Type:
Phase III protocols face intensifying substitution pressure from adaptive Phase II designs that compress timelines for retinal gene therapies, forcing traditional pivotal studies to defend their value proposition through regulatory weight.
- Phase I:First-in-human ocular studies concentrate in Basel, Singapore, and Boston where specialized surgical suites support subretinal injection protocols. PMDA Sakigake designation in Japan accelerates sponsor migration to Tokyo-Osaka clusters for regenerative medicine safety assessments.
- Phase II:Adaptive designs with Bayesian endpoints now dominate retina disorder development, enabling dose-ranging decisions without separate studies. FDA Project Optimus mandates propagate dose-optimization requirements into ophthalmic oncology protocols.
- Phase III:Multi-center pivotal trials anchor value capture through geographic atrophy and diabetic macular edema programs requiring 500-plus participants.
- Phase IV:Post-market surveillance concentrates on sustained-release implant safety databases and real-world gene therapy durability tracking.
Phase III anchors the volume base while Phase II gains share at the steepest rate.
Product Type:
Cost tier stratification separates capital-intensive gene therapy manufacturing from commoditized diagnostic validation, with device trials occupying a margin-defended middle layer.
- Drugs:Small-molecule and biologic protocols for glaucoma and diabetic macular edema leverage established endpoints and predicate pathways. Demand clusters in Germany and the United States where payer clarity supports reimbursement-linked trial designs.
- Gene Therapy:Adeno-associated viral vector programs for inherited retinal dystrophies command premium development costs due to vector manufacturing concentration at three contract manufacturing organizations worldwide. EMA PRIME designation accelerates European site investment for pediatric retinal disease therapies.
- Devices:Sustained-release drug delivery implants follow established 510(k) and CE marking pathways with predictable regulatory timelines.
- Diagnostics:Optical coherence tomography biomarker validation studies support smaller sample sizes for geographic atrophy interventions.
Drugs retain the largest revenue footprint while gene therapy climbs the fastest.
Indication:
Application-specific endpoint requirements fragment trial design expertise, with retina disorder protocols demanding imaging-intensive infrastructure that excludes generalist sites.
- Retina Disorders:Geographic atrophy and diabetic macular edema trials require microperimetry-functional vision endpoints and AI-enabled OCT segmentation. Kaiser Permanente and Intermountain Healthcare networks capture progression data from routine clinical care.
- Glaucoma:Visual field progression endpoints and intraocular pressure monitoring concentrate in specialized academic centers with longitudinal patient registries.
- Corneal Diseases:Stem cell and artificial cornea protocols cluster in Basel and Singapore where surgical innovation supports complex keratoplasty studies.
- Cataract:Premium intraocular lens trials follow standardized visual acuity endpoints with broad site eligibility.
Retina Disorders command the steepest site qualification requirements while Glaucoma provides the broadest accessible patient base.
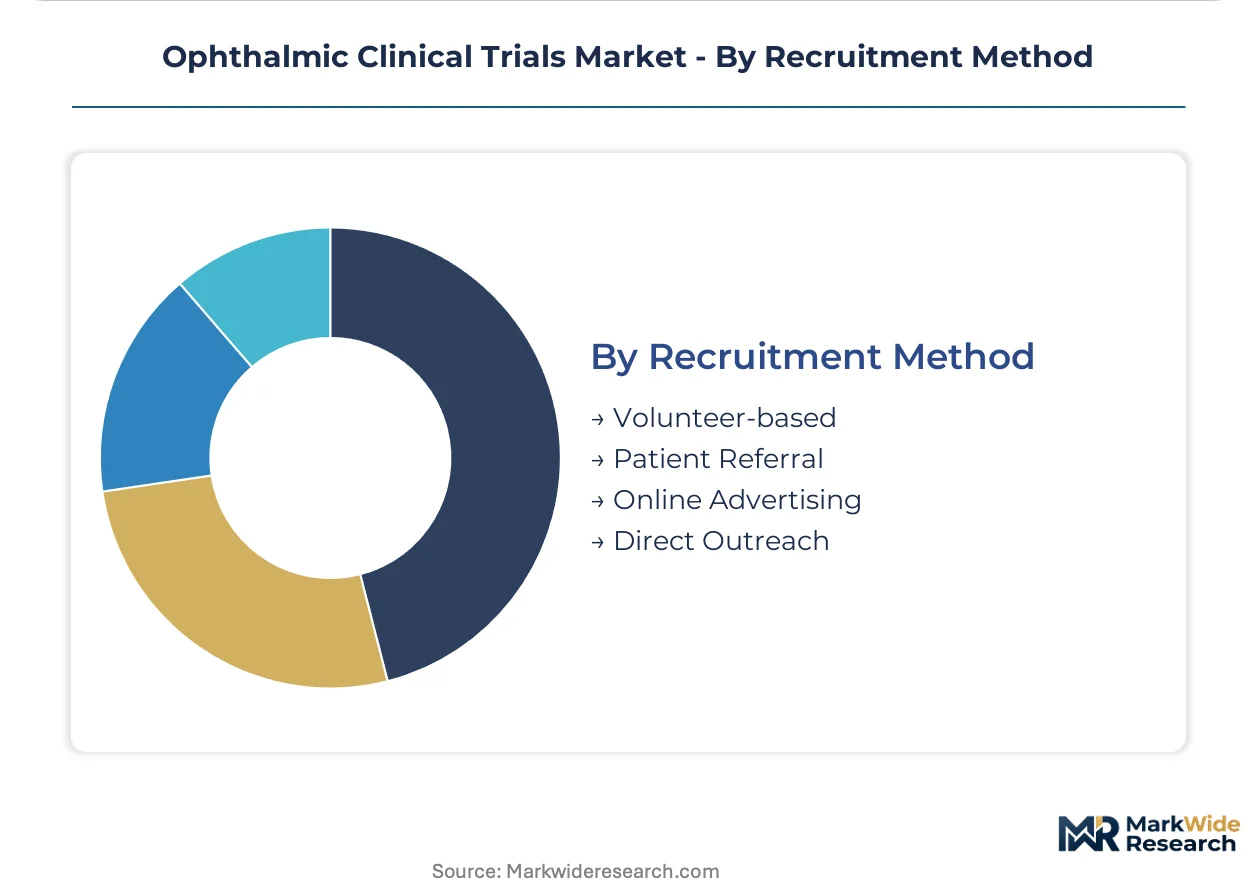
Recruitment Method:
Customer-type stratification separates health system alliance contracting from direct-to-patient digital outreach, with hybrid models gaining traction in decentralized trial modalities.
- Patient Referral:Retinal specialist networks in Boston, Basel, and Singapore generate pre-qualified candidates for gene therapy screening pools. Pre-existing AAV neutralizing antibodies exclude thirty to fifty percent of referred candidates.
- Direct Outreach:Integrated electronic health record networks enable protocol-matching algorithms across multi-state health system alliances.
- Online Advertising:Social media and search-based recruitment expands geographic atrophy trial access beyond traditional academic centers.
- Volunteer-based:Healthy participant databases support Phase I ocular tolerability studies with rapid enrollment timelines.
Patient Referral sustains the highest conversion rates while Direct Outreach scales most quickly through health system digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical sponsors concentrate ophthalmic trial investment where specialized site networks, regulatory clarity, and payer infrastructure align. FDA, EMA, and PMDA pathways now determine geographic deployment decisions for gene therapy protocols.
United States
Academic medical centers in Boston and the San Francisco Bay Area generate pre-qualified candidates for inherited retinal dystrophy screening pools. FDA expanded access pathways accelerate enrollment timelines for orphan ophthalmology programs. Kaiser Permanente and Intermountain Healthcare networks capture geographic atrophy progression data across multi-state alliances.
Germany
EMA PRIME designation draws sponsor investment to European site networks for pediatric retinal disease therapies. The Paul-Ehrlich-Institut coordinates accelerated assessment pathways with forty percent faster completion for priority ocular programs. Heidelberg and Tübingen clusters specialize in microperimetry-functional vision endpoint validation.
Japan
PMDA Sakigake designation prioritizes regenerative medicine review, attracting first-in-human ocular gene therapy protocols to Tokyo-Osaka site clusters. Domestic sponsors leverage streamlined assessment for adeno-associated viral vector safety studies. Osaka University Hospital anchors subretinal injection surgical expertise.
United Kingdom
NHS integrated care systems enable protocol-matching algorithms across regional ophthalmology networks. MHRA alignment with FDA endpoints for diabetic macular edema reduces regulatory friction for transatlantic trials. Moorfields Eye Hospital and Oxford site clusters concentrate retinal imaging infrastructure.
Switzerland
Swissmedic coordinates with EMA on advanced therapy medicinal product assessments for Basel-based pharmaceutical sponsors. The country's specialized surgical suites support complex keratoplasty and stem cell protocol execution. University Hospital Basel anchors corneal disease innovation alongside Novartis and Roche development pipelines.
Ophthalmic Clinical Trials Market Competitive Landscape
Player mix skews toward full-service contract research organizations with therapeutic depth and mid-tier specialists with regional site access. Three tiers structure competitive positioning: global operators with Real-World Evidence platforms, therapeutic specialists with ocular protocol expertise, and regional players with investigator-network relationships. Consolidation pressure intensifies as adaptive trial designs demand decentralized data capture capabilities. Strategic partnerships between CROs and academic medical centers now outpace standalone site qualification investments.
Among full-service operators, IQVIA Holdings Inc., Parexel International Corporation, and Charles River Laboratories International Inc. exemplify divergent archetype strategies. IQVIA occupies a position anchored by Real-World Evidence platform integration across site networks. Parexel represents therapeutic specialization depth in glaucoma and corneal disease protocols. Charles River Laboratories sits within preclinical-to-clinical continuity, bridging ocular toxicology with Phase I safety assessments.
| Leading Market Players |
|---|
| Parexel International Corporation |
| ICON plc |
| IQVIA Holdings Inc. |
| Medpace |
| PPD (Thermo Fisher Scientific) |
| Syneos Health |
| Iris Pharma |
| Laboratory Corporation of America Holdings |
| Charles River Laboratories International Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day vector manufacturing lead times concentrate pricing power at three contract manufacturing organizations worldwide, compressing sponsor margins while amplifying cost pass-through for adeno-associated viral payload production. Phase III gene therapy protocols absorb this supply rigidty through cost-plus contracts indexed to bioreactor utilization rates, with sponsors locking capacity eighteen months ahead of first-patient-in dates.
Pricing Analysis
Cost-plus contracts with bioreactor-utilization indexation dominate gene therapy trial procurement, separating premium-tier sponsors with locked capacity from standard-tier competitors exposed to spot-market volatility. Price differentiation rests on vector serotype rarity and GMP certification tier, with triple-plasmid systems commanding premiums over helper-dependent platforms. Cost compression in mid-tier CRO services is intensifying because AI-enabled endpoint adjudication commoditizes traditional central reading center offerings. Academic medical centers exhibit the lowest price sensitivity due to grant-funded infrastructure, while emerging biotech sponsors face acute budget constraints on vector manufacturing deposits.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled viral vector shipments from Baltimore, Leipzig, and Osaka bioreactor facilities expose sponsors to container-availability volatility on transatlantic and transpacific trade lanes. Supply concentrates in the United States, Germany, and Japan where specialized fill-finish capabilities anchor global AAV production. Raw material dependencies encompass plasmid DNA, helper virus stocks, and serum-free media formulations. Single-source vulnerability at the plasmid synthesis tier creates systemic risk for Phase III programs. Distribution runs through qualified cold-chain logistics providers with continuous temperature monitoring from manufacturing suite to clinical site.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as adaptive trial designs splinter protocol expertise across decentralized data capture, AI-enabled endpoint validation, and real-world evidence integration. Gene therapy specialization creates defendable niches for operators with vector manufacturing relationships and retinal surgical expertise.
For Market Incumbents: Shield market position by acquiring regional CROs with investigator-network depth in Basel, Boston, and Singapore to preempt competitor site access. Prioritize backward integration into electronic health record networks, mirroring Kaiser Permanente alliance structures that blur trial-registry boundaries. Regulatory shift toward ICH E6(R3) compliance threatens margin structures for audit-unready operators.
For New Entrants and Emerging Players: Anchor in decentralized ocular assessment technology, specifically home-based visual function testing platforms that expand recruitment beyond academic medical centers into community ophthalmology practices across Germany. Target geographic atrophy indication protocols where microperimetry-functional vision endpoint expertise remains scarce. Pursue strategic partnerships with smartphone application developers for patient-reported outcome capture.
For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical parent companies divesting non-core clinical development capabilities in ophthalmology. Five-to-ten-year viability hinges on adaptive trial infrastructure and real-world evidence platform integration. Mid-tier CROs with therapeutic depth in retina disorders represent prime acquisition archetypes. Monitor FDA Project Optimus implementation pace as inflection indicator for dose-optimization service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Implementation | Bayesian endpoint integration compresses Phase II timelines for retinal gene therapies. |
| Real-World Evidence Platform Development | EHR-network integration anchors recruitment for geographic atrophy progression studies. |
| Vector Manufacturing Capacity Lock | Long-term offtake agreements with Baltimore and Leipzig bioreactor facilities secure supply. |
| AI-Enabled Endpoint Adjudication | Automated OCT segmentation compresses central reading center timelines from weeks to days. |
| Decentralized Ocular Assessment Deployment | Home-based visual function testing expands patient access beyond academic medical centers. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with clinical development executives, regulatory affairs leads at ophthalmic sponsors, retinal specialist investigators, and payer access specialists informed trial design evolution and site selection criteria. Secondary sources encompass FDA ophthalmology division guidance documents, EMA PRIME designation assessments, ClinicalTrials.gov protocol registries, and PMDA Sakigake review summaries. Bottom-up enrollment velocity modeling and top-down market size triangulation reconcile segment-level demand with aggregate value capture.
Sensitivity analysis around vector manufacturing capacity constraints and regulatory pathway acceleration informs the projection framework across the analysis window. Segmentation dimensions encompass trial phase, therapeutic modality, indication category, and recruitment methodology, with gene therapy manufacturing tier modeled as an industry-specific supply-side dimension. CAGRs derive from enrollment trajectory analysis and protocol complexity indexing. Forecast inputs incorporate investigator-site density by metropolitan cluster and adaptive design adoption curves.
Material uncertainties — AAV vector immunogenicity exclusion rates, ICH E6(R3) compliance timeline delays, and retinal specialist investigator availability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway continuity and manufacturing capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Astigmatism Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Retinal Vasculitis Treatment Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
US Ophthalmic Sutures Market