
 Usher Syndrome Market | 2026-2036
Usher Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Usher Syndrome Market Analysis
AAV-based delivery vectors are pivoting toward synthetic capsid variants that improve retinal transduction efficiency and reduce immunogenicity costs. Atsena Therapeutics leverages proprietary dual AAV technology for large-gene transfer in inherited retinal diseases. GenSight Biologics anchors its portfolio on optogenetic approaches combined with engineered adeno-associated viral platforms. Cochlear Limited dominates auditory implant solutions that complement emerging ocular gene therapies in Usher patient management.
Usher syndrome encompasses a group of autosomal recessive disorders characterized by congenital sensorineural hearing loss and progressive retinitis pigmentosa, with three clinical subtypes distinguished by severity, progression rate, and vestibular involvement; its primary purpose is to identify therapeutic interventions that halt photoreceptor degeneration and preserve auditory function. Gene therapy commands the deepest R&D investment pools due to the monogenic nature of most Usher subtypes and the accessibility of the eye for localized vector delivery. Diagnostic kits represent a maturing segment where clinical adoption hinges on cascade screening protocols in pediatric audiology programs. Intravitreal injectables lead delivery mode preference because the vitreous chamber permits direct subretinal or intravitreal vector administration with lower systemic exposure.
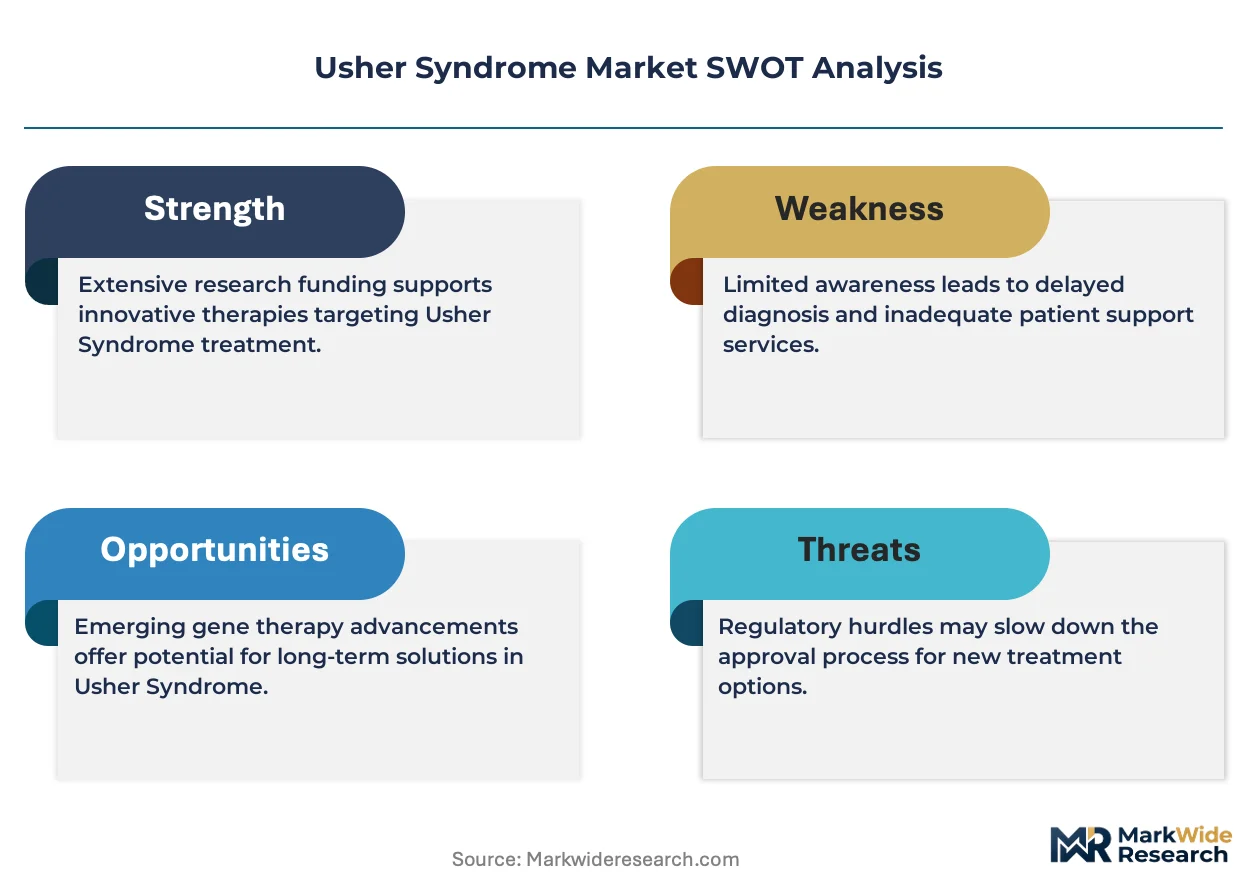
FDA orphan drug incentives and EMA PRIME designation pathways accelerate development timelines for Usher syndrome therapies by granting protocol assistance and fee waivers. The EU Medical Device Regulation and ISO 14155 clinical investigation standards govern diagnostic kit performance claims and trial conduct across European markets. Stakeholders must monitor regulatory precedent for combination product classifications where gene therapy and surgical delivery devices converge.
Market Dynamics
Gene therapy vector engineering is compressing development timelines for inherited retinal diseases, with synthetic AAV capsids now enabling dual-vector large-gene delivery that was previously unattainable for Usher syndrome subtypes.
Growth Catalysts
- FDA Orphan Drug Designation:Protocol assistance and fee waivers accelerate clinical trial initiation for monogenic retinal therapies, reducing regulatory friction for developers targeting small patient populations.
- Intravitreal delivery platforms:Surgical device convergence with gene therapy vectors enables subretinal administration with reduced systemic immunogenicity, expanding treatable patient pools.
- Pediatric audiology cascade screening:Early genetic identification in Germany, Japan, and the United States drives diagnostic kit demand and presymptomatic intervention windows.
Market Restraints
- AAV manufacturing capacity concentration:Viral vector production bottlenecks in contract development organizations limit batch consistency and scale-up for late-stage trials.
- Pre-existing neutralizing antibodies:Seroprevalence rates exclude substantial patient subsets from first-generation AAV therapies, requiring exclusion criteria that shrink addressable populations.
- EMA MDR compliance costs:EU Medical Device Regulation certification requirements for combination products extend timelines and inflate quality management system expenditures.
Strategic Opportunities
- Optogenetic platform expansion:Light-sensing protein engineering combined with engineered AAV variants creates intervention pathways independent of specific gene mutation, broadening indication scope.
- Cochlear implant-gene therapy bundling:Auditory device manufacturers can capture longitudinal patient relationships through integrated hearing preservation and restoration protocols.
- EMA PRIME designation pathway:Accelerated assessment eligibility for breakthrough therapies reduces time-to-market for first-in-class retinal interventions.
Industry Challenges
- Retinal surgeon training deficits:Subretinal injection technique specialization remains concentrated in tertiary academic centers, limiting site activation for multicenter trials.
- Biomarker validation timelines:surrogate endpoints for photoreceptor preservation lack standardized regulatory acceptance across FDA and EMA review divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Usher Syndrome Market |
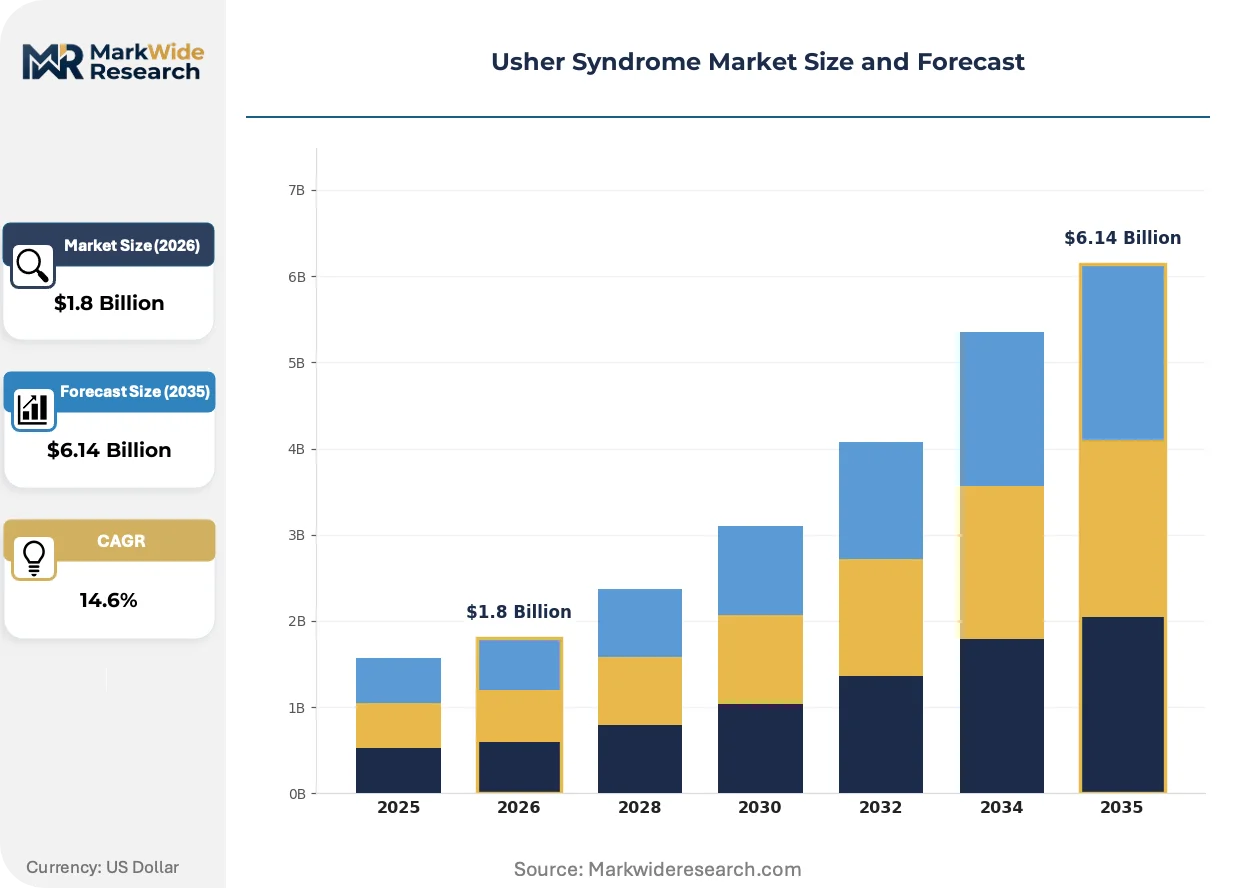
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Pharmaceutical, Diagnostic Kits, Clinical Trials Therapy Area: Ocular Disorders, Hearing Loss, Neurodegenerative Conditions, Genetic Disorders End User: Hospitals, Research Institutes, Clinics, Pharma Companies Delivery Mode: Intravitreal Injectables, Oral Administration, Topical Formulations, Infusions |
| Companies Covered | Laboratoires Théa, Atsena Therapeutics, AAVantgarde Bio, Nacuity Pharmaceuticals, Nanoscope Therapeutics, GenSight Biologics, Odylia Therapeutics, Cochlear Limited, MED-EL Medical Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Usher Syndrome Market Emerging Trajectories
Vector engineering and surgical delivery convergence is dismantling previous technical barriers to large-gene transfer, while regulatory frameworks adapt to combination product complexity.
Synthetic AAV capsid libraries are rewriting the efficiency benchmarks for retinal transduction. Academic medical centers in the United States and Germany are prioritizing variants with reduced immunogenicity profiles for first-in-human protocols. This capsid diversification is compressing the competitive moat around legacy serotype patents and enabling modular platform licensing.
EMA PRIME designation and FDA Breakthrough Therapy pathways are synchronizing protocol development across Atlantic regulatory regimes. Sponsors now front-load quality-of-life endpoint validation to satisfy both agencies' evolving evidentiary standards. Retinal gene therapy submissions are absorbing the greatest compliance scrutiny, with combination product classification disputes consuming pre-submission resources.
Hospital procurement committees are consolidating gene therapy acquisition decisions under centralized pharmacy and therapeutics committees. Academic medical centers are displacing decentralized ophthalmology department purchasing with enterprise-level contract negotiation for high-cost biologals. This concentration is most visible in the United States, where integrated delivery networks are extracting performance guarantees and outcome-based rebate structures from developers.
Usher Syndrome Market Segmentation
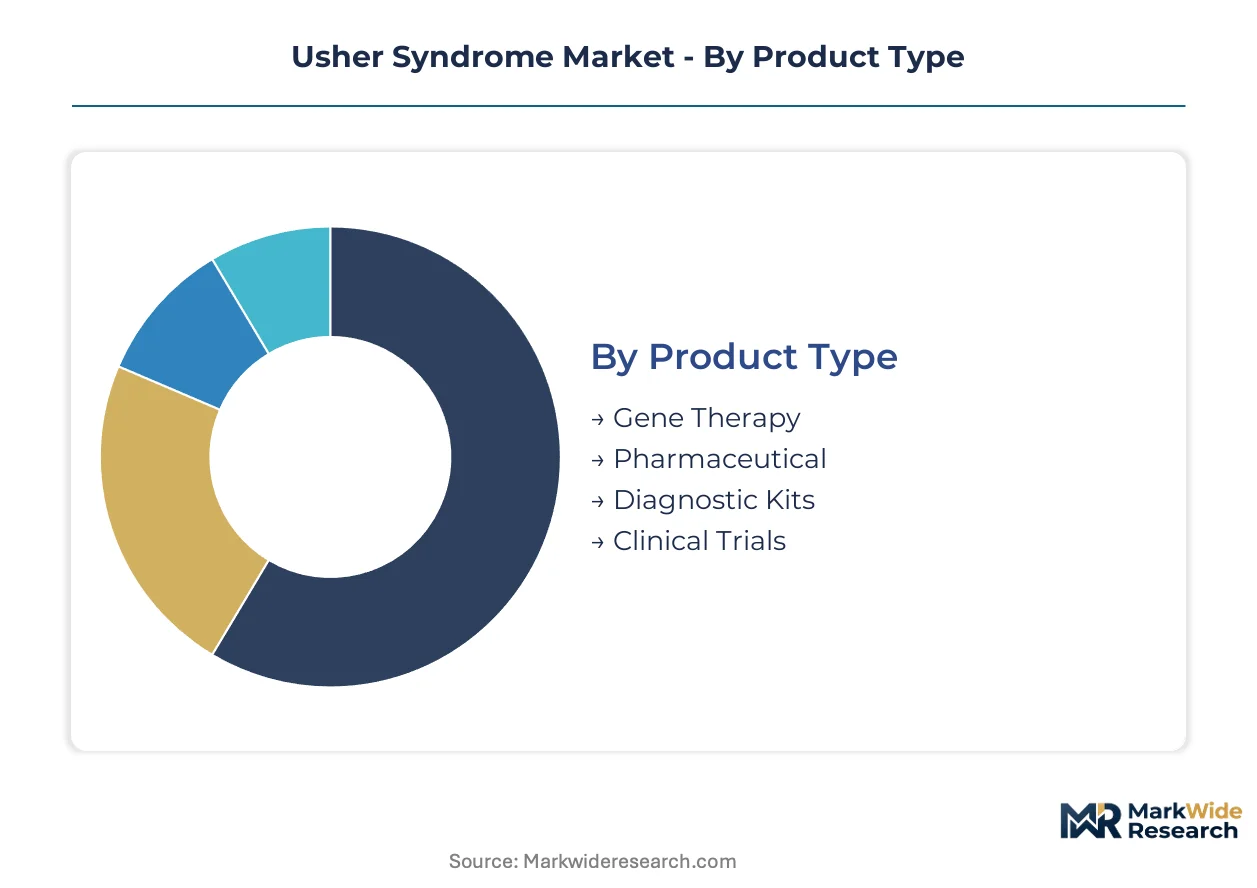
Usher syndrome's dual sensory pathology demands parallel therapeutic tracks—ocular gene therapy and auditory intervention—each carrying distinct regulatory burdens and manufacturing complexities. Segmentation reveals where R&D capital concentrates and which approval pathways determine commercial viability.
Product Type:
FDA gene therapy guidelines impose IND-enabling toxicology burdens on viral vectors that diagnostic kits escape through 510(k) pathways, while pharmaceutical candidates navigate NDA requirements with distinct CMC validation thresholds.
- Gene Therapy:AAV-based platforms targeting MYO7A, USH1C, and USH2A mutations dominate pipeline investment. Subretinal delivery demands surgical device co-development, triggering FDA combination product classification reviews that extend pre-market timelines. Demand concentrates in United States academic medical centers with established vitreoretinal surgery programs.
- Diagnostic Kits:Next-generation sequencing panels and single-gene assays for cascade screening in pediatric audiology programs. German statutory health insurance reimbursement for early genetic identification drives European kit volumes, while Japanese newborn hearing screening expansion creates secondary demand.
- Pharmaceutical:Small-molecule neuroprotective agents and antioxidant formulations targeting photoreceptor preservation. Oral bioavailability challenges limit efficacy in retinal applications, constraining addressable populations to early-stage patients.
- Clinical Trials:Protocol design services, patient registry management, and biomarker validation for natural history studies. EMA PRIME designation eligibility accelerates European trial initiation, reducing sponsor recruitment burdens.
Leading the category by volume: Diagnostic Kits. Growing fastest: Gene Therapy.
Therapy Area:
Clinical endpoints vary sharply across sensory systems—retinal imaging biomarkers versus audiometric thresholds—forcing parallel development tracks with non-overlapping specialist investigator networks.
- Ocular Disorders:Retinitis pigmentosa progression halting through photoreceptor-targeted gene replacement. FDA breakthrough therapy designation for optogenetic approaches validates surrogate endpoints, compressing Phase III duration.
- Hearing Loss:Cochlear gene therapy and hair cell regeneration protocols. Cochlear Limited's implant installed base creates captive channels for adjunct pharmaceutical delivery, bundling surgical and therapeutic revenues.
- Neurodegenerative Conditions:Vestibular dysfunction management in Usher Type 1. Balance rehabilitation device integration with pharmacological intervention represents emerging combination therapy models.
- Genetic Disorders:Pan-Usher syndrome approaches leveraging mutation-agnostic platforms. Synthetic AAV capsid engineering enables large-gene delivery previously excluded by packaging limits.
Dominating revenue concentration: Ocular Disorders. Expanding most quickly: Genetic Disorders.
End User:
Procurement authority fragmentation separates research-funded academic centers from commercially reimbursed hospital systems, with divergent budget cycles and contracting mechanisms.
- Hospitals:Integrated delivery networks in the United States consolidate gene therapy acquisition under centralized pharmacy committees. Outcome-based rebate structures and performance guarantees now standard in high-cost biologic procurement.
- Research Institutes:Natural history study sponsorship and investigator-initiated trials. German Max Planck Institute and American National Eye Institute funding streams support preclinical vector optimization.
- Clinics:Community ophthalmology and audiology practices referring to tertiary centers. Diagnostic kit sampling and genetic counseling services generate service revenue without therapeutic dispensing.
- Pharma Companies:In-licensing and partnership origination for platform technologies. GenSight Biologics and Atsena Therapeutics anchor partnership activity in optogenetic and dual-AAV modalities.
Capturing largest procurement volume: Hospitals. Gaining share fastest: Research Institutes.
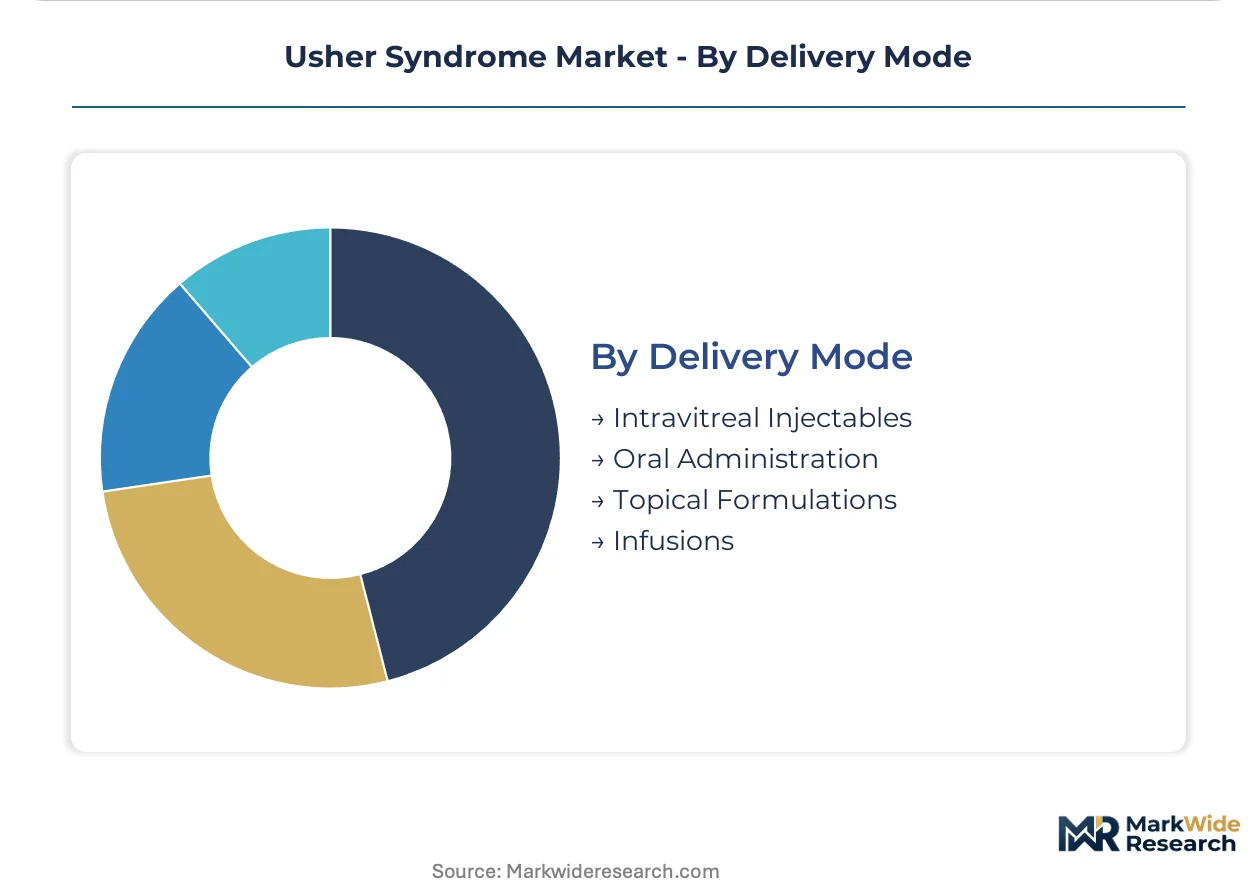
Delivery Mode:
Surgical technique requirements stratify addressable sites, with subretinal injection specialization concentrated in tertiary academic centers limiting multicenter trial activation.
- Intravitreal Injectables:Direct vitreous chamber administration of viral vectors with reduced systemic immunogenicity. Subretinal injection precision demands surgeon training programs that FDA mandates as risk mitigation measures.
- Oral Administration:Systemic neuroprotective agents with blood-retinal barrier penetration limitations. Convenience advantage offset by retinal bioavailability constraints in advanced disease stages.
- Topical Formulations:Corneal and anterior segment applications with minimal Usher syndrome relevance. Limited to adjunctive lubrication and surface management.
- Infusions:Systemic gene delivery approaches under investigation for auditory and vestibular targets. Preclinical toxicity profiles complicate IND-enabling study design.
Holding dominant clinical position: Intravitreal Injectables. Steepest expansion trajectory: Infusions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Usher syndrome interventions concentrates in the United States, Germany, and Japan, where tertiary ophthalmology networks and statutory screening programs create aligned reimbursement and early identification pathways.
United States
FDA orphan drug designations and breakthrough therapy pathways compress clinical trial timelines for gene therapy developers. The National Eye Institute funds natural history studies at academic medical centers. Boston and Philadelphia anchor vitreoretinal surgery training programs that activate multicenter trial sites.
Germany
Statutory health insurance reimburses cascade genetic screening in pediatric audiology, expanding diagnostic kit volumes. EMA PRIME designation eligibility accelerates European trial initiation for sponsors. Heidelberg and Tübingen concentrate retinal gene therapy research through Max Planck Institute partnerships.
Japan
Newborn hearing screening expansion drives presymptomatic genetic identification demand. PMDA's Sakigake designation system grants priority review for regenerative medicine products. Tokyo and Osaka academic hospitals lead subretinal injection technique standardization for Asian patient populations.
United Kingdom
NHS specialized commissioning frameworks concentrate gene therapy delivery in designated supraregional centers. MHRA innovative licensing pathways align with EMA accelerated assessment timelines. London and Manchester host inherited retinal disease natural history registries that support trial recruitment.
France
ANSM early access programs enable named-patient provision for investigational retinal therapies prior to marketing authorization. National rare disease plans coordinate multidisciplinary Usher patient management across ophthalmology and audiology services. Paris and Lyon academic centers pioneer optogenetic surgical protocols.
Usher Syndrome Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with gene therapy developers retaining proprietary vector platforms while diagnostic kit producers rely on outsourced manufacturing. The market structure tilts toward consolidation in ocular gene therapy, where dual-AAV and optogenetic platform licensing creates defensive moats, while hearing intervention remains anchored by established auditory implant manufacturers. Strategic archetypes include platform technology licensors, surgical device-therapy integrators, and cascade screening diagnostic providers. Dominant competitive moves encompass vector engineering partnerships with academic medical centers and co-development agreements that bundle surgical delivery systems with therapeutic payloads.
Among biopharmaceutical developers, Atsena Therapeutics and GenSight Biologics occupy positions within the retinal gene therapy archetype, representing divergent technical approaches to inherited ocular disease intervention. Atsena's designation as a United States-based entity situates it within the North American concentration of AAV platform innovation, while GenSight Biologics exemplifies European optogenetic strategy development. Cochlear Limited anchors the auditory intervention tier, its Australian corporate structure reflecting the geographic distribution of implantable hearing technology leadership. These three entities collectively illustrate how the competitive landscape stratifies across therapeutic modality rather than geographic origin.
| Leading Market Players |
|---|
| Laboratoires Théa |
| Atsena Therapeutics |
| AAVantgarde Bio |
| Nacuity Pharmaceuticals |
| Nanoscope Therapeutics |
| GenSight Biologics |
| Odylia Therapeutics |
| Cochlear Limited |
| MED-EL Medical Electronics |
| Others |
Supply Flow & Price Mechanics
Captive vector manufacturing by Atsena Therapeutics and GenSight Biologics anchors supply security and pricing power in retinal gene therapy, insulating developers from contract development organization bottlenecks that inflate batch costs for outsourced AAV production. This vertical integration choice compresses per-dose manufacturing variance while enabling outcome-based contracting with United States integrated delivery networks.
Pricing Analysis
Volume versus margin splits sharply between diagnostic kits and gene therapies, with cascade screening panels in Germany and Japan capturing high-volume, low-unit-price economics while subretinal AAV therapies command premium positioning tied to surgical delivery bundling. Price differentiation rests on FDA breakthrough therapy designation tiering and EMA PRIME eligibility, with certified academic medical centers extracting performance guarantees that standard community clinics cannot match. Pricing pressure stems from AAV manufacturing capacity constraints that extend wait times for non-integrated developers. Hospital procurement committees demonstrate lowest price sensitivity for first-in-class optogenetic platforms, while community audiology clinics prioritize diagnostic kit cost minimization.
Supply Chain Analysis
Cold-chain logistics costs for AAV vectors concentrate supply chain investment in the United States, Germany, and Japan, where tertiary academic medical centers maintain validated storage infrastructure. Raw material dependencies center on plasmid DNA, HEK293 cell lines, and synthetic capsid libraries sourced from specialized bioreactor facilities. Single-source vulnerability characterizes serotype-specific capsid patent estates held by legacy platform licensors. Distribution runs through hospital centralized pharmacy committees rather than decentralized ophthalmology department purchasing, consolidating negotiation leverage in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into AAV manufacturing represents the decisive competitive race, with control over capsid engineering and bioreactor capacity determining which developers can meet outcome-based rebate terms demanded by United States hospital procurement committees.
For Market Incumbents: Deploy dual-AAV platform licensing as the primary defensive lever. Secure exclusive surgical device co-development agreements with retinal instrument manufacturers to lock out non-integrated competitors. Cochlear Limited's implant installed base threatens auditory gene therapy bundling; counter by anchoring longitudinal patient relationships through vestibular rehabilitation device integration. Expand bioreactor capacity in Boston and Philadelphia corridor to compress per-dose manufacturing variance. For New Entrants and Emerging Players: Enter via mutation-agnostic optogenetic platforms that bypass serotype-specific patent thickets. Target Japanese newborn hearing screening expansion as the most penetrable geography, where PMDA Sakigake designation accelerates regulatory timelines. Pursue white-space in pan-Usher syndrome approaches using synthetic capsid libraries that enable large-gene delivery previously excluded by packaging limits. Go-to-market angle: academic medical center investigator-initiated trial sponsorship with natural history registry integration. For Investors and Strategic Acquirers: Exit pathways concentrate in platform technology licensing to major ophthalmology franchises, with acquisition premiums attaching to validated retinal transduction efficiency data. Long-term viability favors developers with demonstrated surgical device-therapy integration and EMA PRIME designation eligibility. Target acquisition archetype: dual-AAV specialists with proprietary capsid libraries and established United States academic medical center relationships. Signal to watch: FDA combination product classification precedents for subretinal delivery systems, which will clarify regulatory capital requirements for integrated versus modular platform strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-AAV Platform Licensing | Enables large-gene transfer for MYO7A and USH2A mutations previously excluded by packaging limits. |
| EMA PRIME Designation Pathway | Accelerates European trial initiation through protocol assistance and accelerated assessment eligibility. |
| Surgical Device Co-Development | Triggers FDA combination product reviews that extend timelines but lock in delivery system control. |
| Pediatric Audiology Cascade Screening | Drives diagnostic kit volumes through German statutory health insurance reimbursement expansion. |
| Optogenetic Platform Expansion | Creates mutation-agnostic intervention pathways independent of specific gene defects. |
Methodological Framework
FDA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone, supplemented by formulary and reimbursement databases tracking United States integrated delivery network procurement patterns. Primary interviews with retinal surgeon-investigators, regulatory affairs leads at gene therapy developers, hospital pharmacy and therapeutics committee chairs, and payer access specialists validated demand assumptions. Bottom-up and top-down triangulation reconciled patient population estimates with manufacturing capacity projections.
Bottom-up modeling anchored volume forecasts to diagnosed prevalence by Usher subtype and treatable patient eligibility criteria excluding seropositive individuals, while top-down analysis cross-checked revenue projections against hospital procurement committee budget cycles. Segmentation dimensions spanned product type, therapy area, end user, and delivery mode, with regional regulatory clusters modeled separately. CAGRs derived from natural history study enrollment trajectories and FDA breakthrough therapy designation timelines. Industry-specific inputs incorporated AAV manufacturing batch success rates and subretinal injection site activation capacity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under AAV immunogenicity breakthroughs or EMA MDR compliance delays that extend combination product timelines. Forecasts reflect assumptions about surgical training program expansion and biomarker validation standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
United States Dry Eye Syndrome Market