
 Global Hemianopsia Market | 2026-2036
Global Hemianopsia Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemianopsia Market Foresight
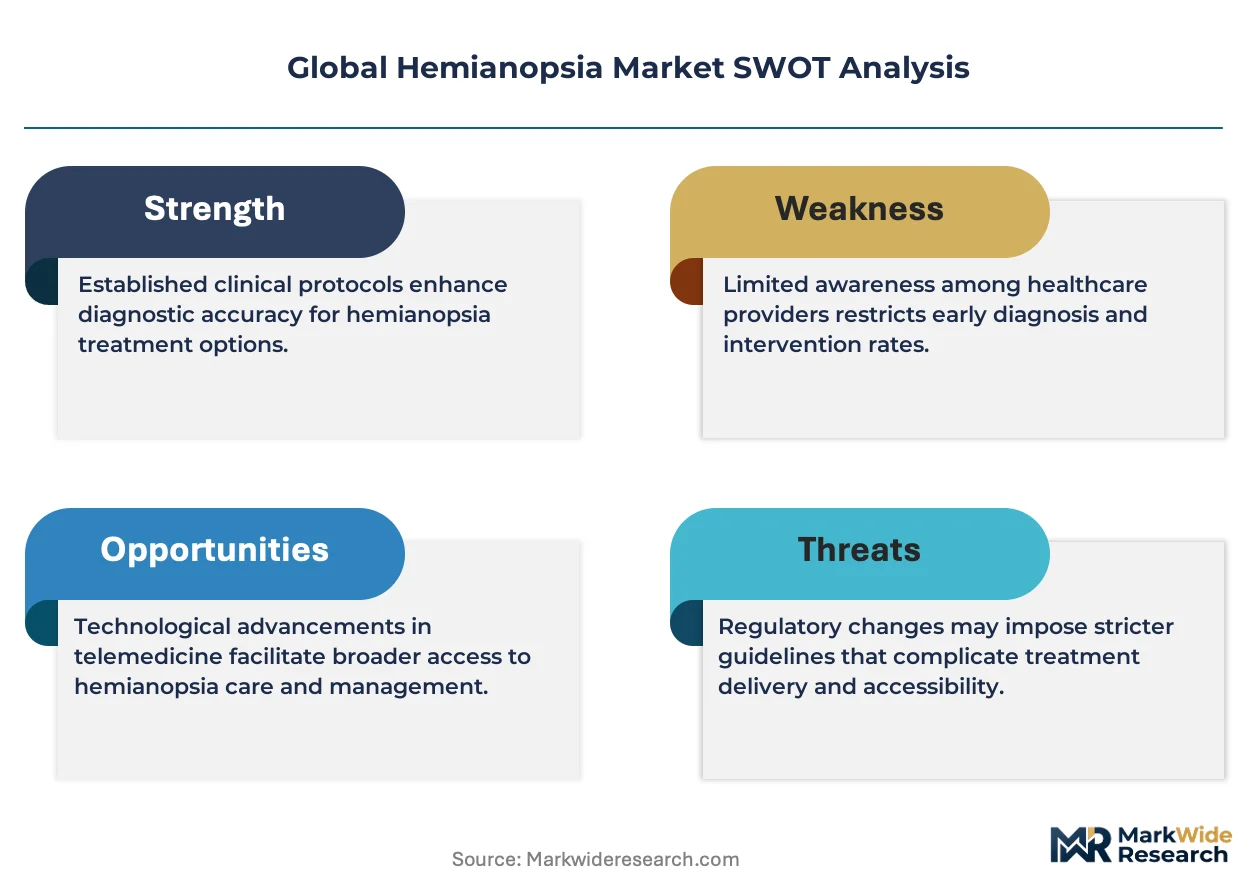
Class IIb device certification is collapsing as the baseline threshold for commercial entry in hemianopsia therapeutics. Carl Zeiss Meditec AG leverages its surgical microscopy heritage to anchor premium positioning in diagnostic imaging for post-stroke visual field assessment. Novartis AG competes through pharmaceutical management protocols that integrate with rehabilitation workflows. EssilorLuxottica dominates the compensatory lens segment, controlling distribution through optometric channels across Europe and North America.
Hemianopsia denotes partial blindness affecting half of the visual field, typically resulting from optic pathway lesions, stroke, or traumatic brain injury, with homonymous patterns representing the predominant clinical presentation requiring structured rehabilitation protocols. The condition's primary purpose in medical commerce lies in restoring functional independence through neuroplasticity-driven interventions or adaptive compensation. Homonymous hemianopsia leads therapy area demand due to its high post-stroke incidence, while assistive technology segments sustain margin pools through recurring lens and software subscriptions. Telemedicine delivery is accelerating fastest among delivery modes, though in-person treatment still occupies the majority of reimbursed care pathways.
FDA 510(k) clearance requirements shape device commercialization timelines for US manufacturers, while the EU MDR and CE marking framework impose stricter clinical evidence standards than preceding directives. Japan's PMDA enforces additional quality system regulations for ophthalmic rehabilitation devices entering its national health reimbursement catalog. Stakeholders must monitor regulatory divergence between FDA breakthrough device designations and EU MDR notified body capacity constraints when prioritizing geographic launch sequencing.
Market Dynamics
Neuroplasticity-driven rehabilitation protocols are compressing treatment timelines and forcing device manufacturers to demonstrate measurable functional outcomes rather than mere visual field mapping accuracy.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter CE marking requirements for Class IIb neuro-ophthalmic devices are filtering out marginal competitors and consolidating demand around validated therapeutic platforms.
- Post-stroke rehabilitation protocols:Germany's university hospital clusters in Heidelberg and Tübingen are establishing standardized visual restoration pathways that export clinical credibility across European markets.
- Telemedicine delivery infrastructure:Remote visual field assessment and therapy monitoring is expanding addressable patient populations beyond urban specialized centers.
Market Restraints
- Specialized neuro-ophthalmologist scarcity:Limited fellowship-trained clinicians constrain patient throughput regardless of device availability or reimbursement coverage.
- Optical component supply concentration:Precision wavefront sensors and microdisplay modules cluster with East Asian contract manufacturers, creating single-source vulnerability.
- Compensatory lens substitution:Prismatic correction devices from established optical laboratories satisfy immediate functional needs without requiring prescription therapy commitment.
Strategic Opportunities
- Japan's PMDA quality system pathway:National health reimbursement catalog inclusion for ophthalmic rehabilitation devices offers premium pricing access in an aging demographic market.
- AI-guided saccadic training convergence:Machine learning algorithms paired with eye-tracking hardware enable personalized therapy intensity adjustment previously requiring continuous specialist supervision.
- Home-based therapy channels:Direct-to-patient subscription models bypass clinic capacity constraints and capture recurring revenue from software-enabled device ecosystems.
Industry Challenges
- FDA 510(k) predicate device matching:Novel neuroplasticity interventions struggle to identify appropriate comparison devices, extending regulatory timelines and pre-revenue burn.
- Legacy electronic health record integration:Visual field data formats lack standardization across Epic, Cerner, and specialized ophthalmology platforms, complicating outcome documentation for reimbursement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemianopsia Market |
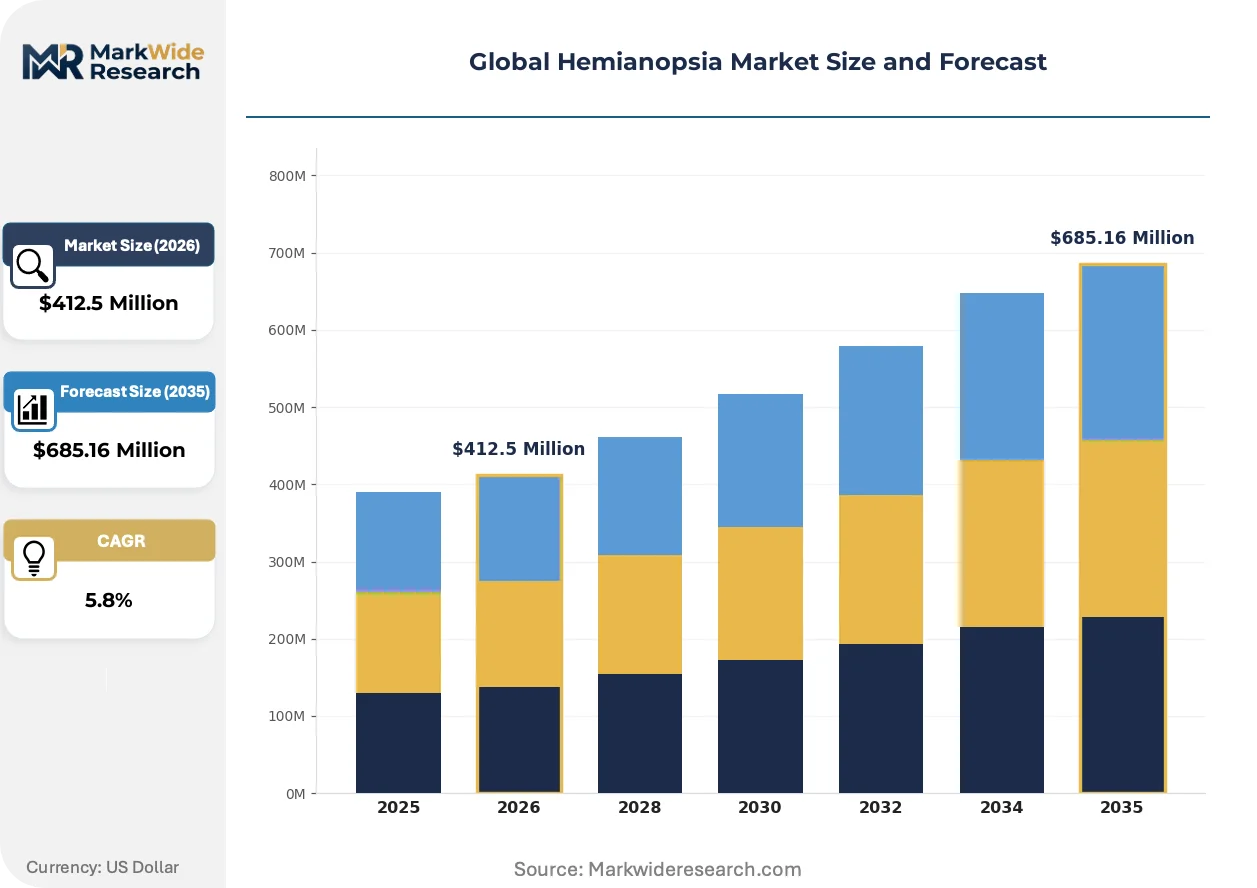
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Homonymous Hemianopsia, Binasal Hemianopsia, Bitemporal Hemianopsia, Quadrantanopia Therapy Area: Neuro-Rehabilitation, Visual Restoration Therapy, Compensatory Training, Pharmaceutical Management, Assistive Technology End User: Neurological Clinics, Rehabilitation Centers, Vision Therapy Facilities, Research Institutes Delivery Mode: In-person Treatment, Telemedicine, Home-based Programs, Mobile Applications |
| Companies Covered | Vycor Medical Inc., RetroSense Therapeutics LLC, Chadwick Optical, Carl Zeiss Meditec AG, AbbVie Inc., Novartis AG, F. Hoffmann-La Roche Ltd., EssilorLuxottica, Haag-Streit Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemianopsia Market Shifts & Advancements
Digital therapeutics with embedded biofeedback are replacing passive optical compensation as the dominant intervention modality, restructuring how providers measure and monetize patient progress.
Non-invasive transcranial direct current stimulation paired with visual training is displacing conventional prism therapy in post-stroke rehabilitation centers. University hospitals in Germany and the Netherlands are adopting these combined protocols within six-month pilot-to-scale timelines. The technology is displacing high-margin custom lens fabrication by demonstrating superior functional independence metrics in standardized activities of daily living assessments.
The EU MDR's clinical evidence requirements for neuro-ophthalmic devices are extending notified body review cycles and forcing manufacturers to maintain larger post-market surveillance cohorts. Device sponsors now face mandatory PMCF study commitments that add eighteen to twenty-four months to commercialization timelines. Small-cap developers are responding by prioritizing FDA breakthrough device designation for US market entry before addressing European regulatory complexity.
Hospital procurement departments are unbundling visual rehabilitation services from bundled stroke care contracts and negotiating standalone device and software subscriptions. This purchasing pattern shift pressures manufacturers to demonstrate discrete cost-per-functional-outcome metrics rather than capital equipment ROI. The transformation is most visible in US academic medical centers where value-based care contracts with Medicare Advantage plans dominate reimbursement structures.
Global Hemianopsia Market Segmentation
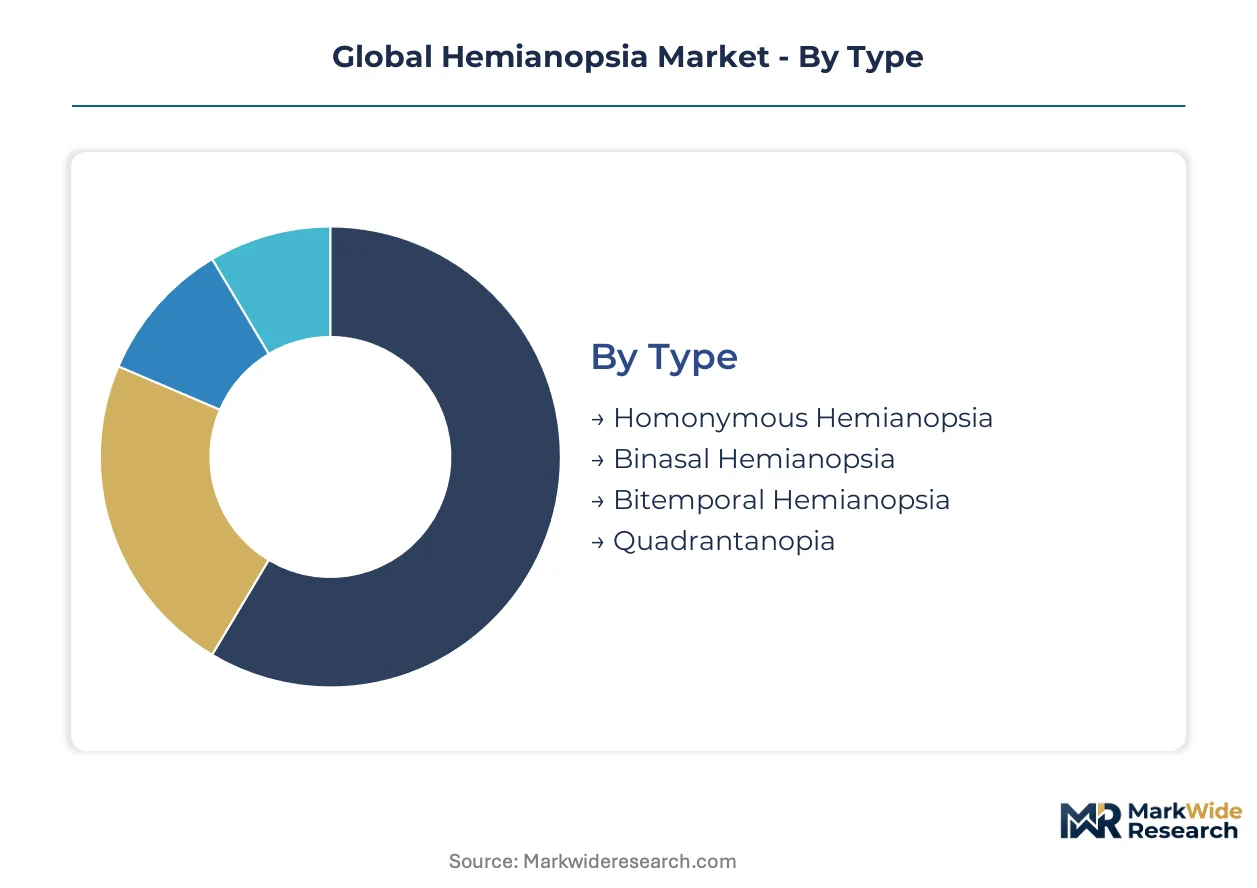
Segmentation in hemianopsia therapeutics reveals how substitution pressures reshape competitive boundaries. Optical compensation competes directly with neuroplasticity protocols, forcing manufacturers to defend discrete value propositions within each category.
Type:
Homonymous patterns face the strongest substitution threat from prismatic lenses, while rarer variants command premium diagnostic investment due to specialized etiology requirements.
- Homonymous Hemianopsia:Post-stroke lesions affecting the optic radiations or occipital cortex produce congruent visual field defects in both eyes. Demand clusters in Germany's university hospital networks around Heidelberg and Tübingen, where standardized restoration protocols filter clinical credibility across European reimbursement systems.
- Binasal Hemianopsia:Bilateral nasal field loss typically signals chiasmal compression from pituitary pathology. Surgical intervention timelines compress the addressable window for visual rehabilitation, limiting device manufacturers to pre-operative assessment tools rather than sustained therapy platforms.
- Bitemporal Hemianopsia:Chiasmal lesions from craniopharyngioma or pituitary adenoma drive neurosurgical priority over rehabilitation.
- Quadrantanopia:Partial field defects from temporal or parietal lobe involvement retain greater functional independence, reducing compensatory device penetration.
Homonymous Hemianopsia anchors the volume base while Quadrantanopia gains share at the steepest rate through targeted stroke rehabilitation protocols.
Therapy Area:
Cost tier stratification separates capital-intensive device platforms from recurring pharmaceutical and assistive revenue streams.
- Neuro-Rehabilitation:Structured protocols leveraging repetitive visual stimulation to drive cortical reorganization. Germany's specialized vision rehabilitation centers cluster around university hospitals, establishing clinical credibility that exports across EU member states.
- Visual Restoration Therapy:Computer-based border detection training delivered through perimeter devices. FDA 510(k) clearance timelines constrain US commercialization while EU MDR clinical evidence mandates extend European entry by eighteen to twenty-four months.
- Compensatory Training:Saccadic eye movement instruction to maximize remaining field utilization.
- Pharmaceutical Management:Protocols integrating neuroplasticity-enhancing compounds with rehabilitation workflows.
- Assistive Technology:Prismatic lenses, scanning mirrors, and head-mounted displays satisfying immediate functional needs without prescription therapy commitment.
Assistive Technology captures the highest patient throughput while Visual Restoration Therapy expands most quickly through telemedicine delivery infrastructure.
End User:
Customer type concentration determines procurement authority and reimbursement pathway complexity.
- Neurological Clinics:Fellowship-trained neuro-ophthalmologists drive adoption of neuroplasticity-driven interventions. Capacity constraints limit patient throughput regardless of device availability or coverage generosity.
- Rehabilitation Centers:Post-acute stroke facilities integrating visual restoration into bundled care contracts. US academic medical centers unbundle services from stroke contracts, demanding discrete cost-per-functional-outcome metrics.
- Vision Therapy Facilities:Optometric channels dominated by EssilorLuxottica's compensatory lens distribution.
- Research Institutes:Pilot-to-scale timelines in Germany and the Netherlands validate combined tDCS and visual training protocols.
Neurological Clinics concentrate the highest-margin procedures while Rehabilitation Centers drive volume expansion through standardized stroke pathways.
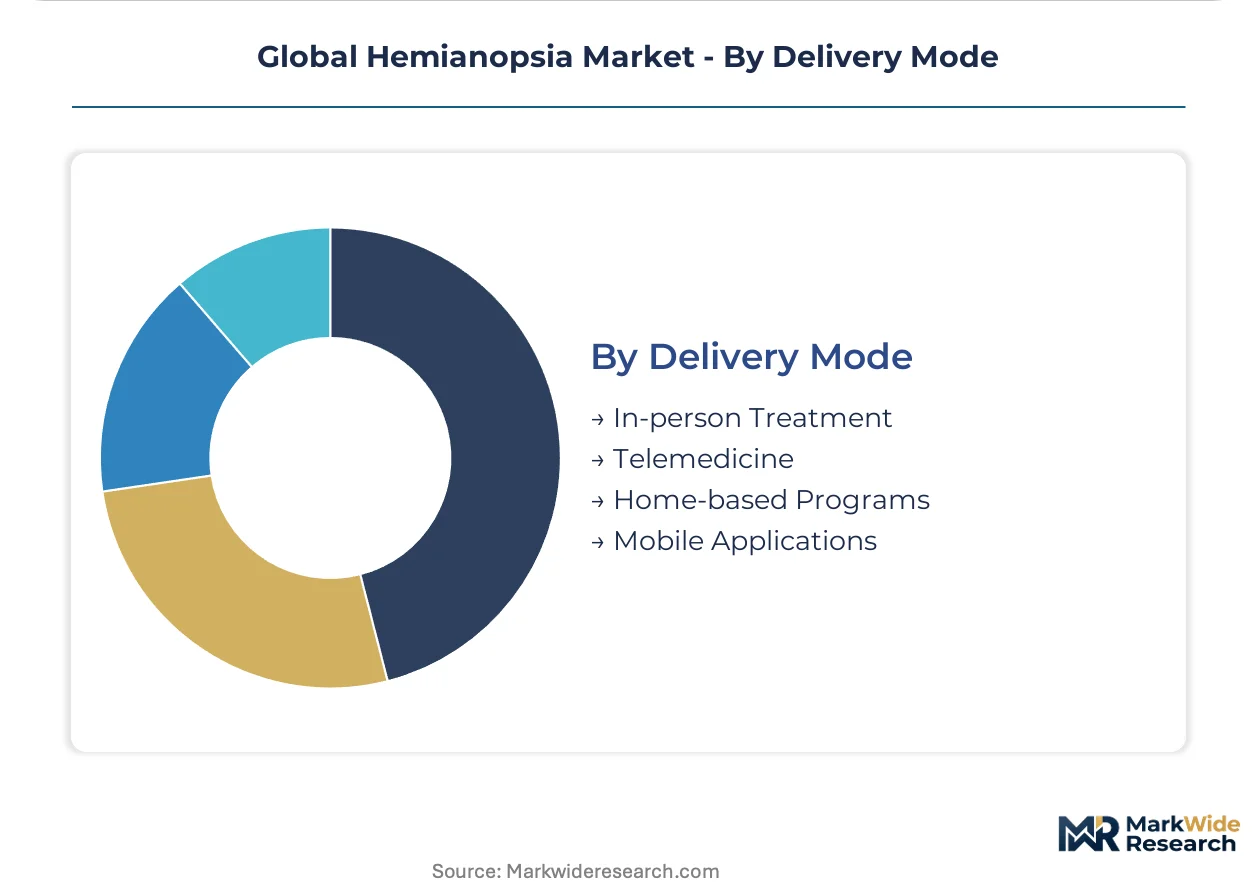
Delivery Mode:
Maturity gradients separate established in-person reimbursement from emerging direct-to-patient channels.
- In-person Treatment:Specialist-supervised therapy occupying the majority of reimbursed care pathways. Scarcity of fellowship-trained clinicians creates throughput ceilings independent of device innovation.
- Telemedicine:Remote visual field assessment and therapy monitoring expanding addressable populations beyond urban specialized centers. AI-guided saccadic training enables personalized intensity adjustment without continuous specialist presence.
- Home-based Programs:Subscription models bypassing clinic capacity constraints through software-enabled device ecosystems.
- Mobile Applications:Consumer-grade visual training with limited clinical validation for reimbursement.
In-person Treatment retains reimbursement dominance while Home-based Programs climb the fastest through direct-to-patient subscription economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian contract manufacturers dominate optical component supply for hemianopsia devices, concentrating precision wavefront sensors and microdisplay modules in single-source arrangements that create geographic vulnerability for device sponsors.
United States
Academic medical centers in Boston and Baltimore unbundle visual rehabilitation from bundled stroke care contracts, demanding discrete cost-per-functional-outcome metrics from device manufacturers. FDA 510(k) clearance timelines constrain commercialization for novel neuroplasticity interventions lacking appropriate predicate devices. The Cleveland Clinic and Johns Hopkins clusters drive protocol standardization that exports clinical credibility to regional hospital networks.
Germany
University hospital clusters in Heidelberg and Tübingen establish standardized visual restoration pathways that filter across European reimbursement systems. The EU MDR notified body capacity constraints extend device review cycles by eighteen to twenty-four months, filtering marginal competitors from commercial entry. Specialized vision rehabilitation centers concentrate around these academic nodes, creating referral density that accelerates therapy adoption.
Japan
PMDA quality system regulations govern ophthalmic rehabilitation device entry into the national health reimbursement catalog, offering premium pricing access in an aging demographic market. METI industrial policy supports domestic manufacturing of precision optical components, reducing import dependency for wavefront sensor modules. Tokyo and Osaka medical device clusters concentrate regulatory expertise that accelerates dossier preparation for foreign sponsors.
Netherlands
Research institutes in Utrecht and Rotterdam validate combined transcranial direct current stimulation and visual training protocols within six-month pilot-to-scale timelines. EMA-aligned regulatory frameworks enable parallel scientific advice pathways that compress development timelines for EU-wide market entry. Dutch rehabilitation centers serve as early adopters for telemedicine delivery infrastructure that expands patient access beyond urban specialized centers.
Switzerland
Swissmedic maintains stringent clinical evidence requirements for neuro-ophthalmic devices that exceed baseline EU MDR thresholds, creating a premium market tier for validated therapeutic platforms. Basel and Zurich host pharmaceutical-device convergence research that integrates neuroplasticity-enhancing compounds with rehabilitation workflows. The country's precision manufacturing heritage supports domestic production of scanning mirror assemblies for compensatory lens systems.
Global Hemianopsia Market Competitive Landscape
Concentration sits with diversified medtech conglomerates and specialized optical manufacturers that span diagnostic imaging, compensatory lenses, and pharmaceutical management protocols. The market structure tiers across premium diagnostic platforms, mid-market rehabilitation devices, and high-volume assistive technology. Three archetypes dominate: surgical microscopy heritage players, optical laboratory networks, and pharmaceutical-device integrators. Strategic moves center on M&A for neuroplasticity technology access and backward integration into precision optical component supply.
Among the diversified medtech tier, Carl Zeiss Meditec AG and EssilorLuxottica occupy distinct positioning vectors that exemplify competitive divergence. Carl Zeiss Meditec AG represents the surgical microscopy heritage archetype, leveraging diagnostic imaging credibility for post-stroke visual field assessment. EssilorLuxottica anchors the optical laboratory network model, controlling compensatory lens distribution through established optometric channels. Novartis AG sits within the pharmaceutical-device integrator tier, competing through management protocols that embed within rehabilitation workflows rather than capital equipment placement.
| Leading Market Players |
|---|
| Vycor Medical Inc. |
| RetroSense Therapeutics LLC |
| Chadwick Optical |
| Carl Zeiss Meditec AG |
| AbbVie Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| EssilorLuxottica |
| Haag-Streit Holding |
| Others |
Supply & Pricing Matrix
Digital therapeutics substitution for passive optical compensation simultaneously shifts supply geography toward East Asian electronics manufacturing clusters and compresses pricing power in legacy lens fabrication. This substitution dynamic restructures procurement authority as hospital systems unbundle visual rehabilitation services and negotiate discrete cost-per-outcome metrics rather than capital equipment ROI.
Pricing Analysis
EU MDR clinical evidence mandates dictate the pricing tier structure across neuro-ophthalmic device categories. Three-tier pricing separates FDA breakthrough-designated platforms from CE-marked mid-market devices and unvalidated economy alternatives. Price differentiation hinges on notified body certification depth and post-market surveillance commitment scale. Pricing pressure stems from hospital procurement departments demanding discrete functional outcome documentation for reimbursement. Academic medical centers exhibit lowest price sensitivity due to value-based care contract structures, while community rehabilitation centers face acute budget constraints.
Supply Chain Analysis
Just-in-time inventory strategies dominate device assembly while strategic stockpiling concentrates in precision optical component procurement. East Asian contract manufacturers in Taiwan, South Korea, and Japan anchor supply for wavefront sensors and microdisplay modules. Component sourcing draws from specialized semiconductor foundries and precision optics fabricators. Single-source vulnerability in microdisplay supply creates structural risk for device sponsors dependent on consumer electronics allocation priorities. Distribution runs through hospital procurement departments and specialized vision rehabilitation center networks rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained neuro-ophthalmologist scarcity constrains patient throughput regardless of device innovation pace, creating a capability bottleneck that shapes competitive strategy across all stakeholder archetypes.
For Market Incumbents: Consolidate diagnostic imaging credibility through backward integration into precision optical component supply and deepen clinical evidence portfolios ahead of EU MDR post-market surveillance mandates. Carl Zeiss Meditec AG's surgical microscopy heritage exemplifies defensible positioning against emerging AI-guided saccadic training entrants. Priority investment rests on captive supply of wavefront sensor modules from East Asian contract manufacturers. For New Entrants and Emerging Players: Telemedicine infrastructure gaps in rural stroke rehabilitation networks offer white-space access beyond established university hospital clusters. Home-based therapy channels present the most penetrable segment given clinic capacity constraints and direct-to-patient subscription economics. Go-to-market execution should anchor on AI-enabled personalization that reduces specialist supervision requirements. For Investors and Strategic Acquirers: FDA breakthrough device designation reshapes the acquisition landscape by compressing US commercialization timelines relative to EU MDR pathways. Long-term viability favors platforms with demonstrated neuroplasticity outcome metrics and software-enabled recurring revenue architectures. Acquisition target archetypes include digital therapeutic developers with validated saccadic training algorithms. The signal to watch is hospital procurement unbundling velocity from bundled stroke care contracts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Buildout | Notified body capacity constraints filter marginal competitors from CE marking pathways. |
| Backward Integration into Optical Components | Captive supply of wavefront sensors mitigates East Asian single-source vulnerability. |
| AI-Guided Saccadic Training Development | Machine learning personalization reduces specialist supervision bottlenecks in therapy delivery. |
| Telemedicine Infrastructure Partnership | Remote assessment expands addressable populations beyond urban specialized centers. |
| Home-Based Subscription Model Launch | Direct-to-patient economics bypass clinic capacity constraints and capture recurring revenue. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with neuro-ophthalmologists, hospital procurement managers, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up patient population estimates and top-down device shipment triangulation anchored market sizing.
Across the analysis window, forecasts model therapy area segmentation, delivery mode adoption patterns, and regional regulatory cluster differentiation. CAGRs derive from neuroplasticity protocol penetration curves and telemedicine infrastructure deployment rates. Industry-specific inputs include post-stroke incidence projections and EU MDR notified body review cycle timelines.
Underlying assumptions cover reimbursement stability for visual restoration interventions, with deviation risk concentrated in FDA predicate device matching complexity for novel neuroplasticity platforms. Revision becomes warranted when hospital procurement unbundling velocity crosses thresholds that restructure device manufacturer pricing power.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market