
 Head Band Ophthalmoscopes Market | 2026-2036
Head Band Ophthalmoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Head Band Ophthalmoscopes Market Foresight
Hospital outpatient departments is recalibrating procurement priorities toward portable head band ophthalmoscopes that enable bedside and mobile screening. Heine USA Ltd. leverages its German engineering heritage to sustain premium positioning in fiber optic illumination systems. Keeler Ltd. anchors its competitive stance through specialized optics manufacturing in the United Kingdom. Welch Allyn competes on channel control, extending its distribution reach across North American clinic networks.
A head band ophthalmoscope is a wearable diagnostic instrument that mounts on the examiner's head via an adjustable band, typically employing LED or halogen illumination with adjustable lenses ranging from 0 to 20 diopters for direct visualization of the retina, optic disc, and posterior pole; its primary purpose is enabling hands-free fundus examination in settings where table-mounted equipment proves impractical. The portable and handheld product categories capture expanding margin pools as point-of-care diagnostics shift beyond traditional hospital walls, while rechargeable battery configurations are displacing cord-dependent units in ambulatory settings. LED technology leads installed base volumes due to energy efficiency and color temperature stability, though fluorescence-enabled devices command premium positioning in retinal pathology screening.
The FDA oversees 510(k) clearance pathways for ophthalmic diagnostic devices in the United States, while the EU MDR framework imposes stricter clinical evidence requirements for CE marking across European markets, collectively elevating compliance costs but filtering substandard entrants. ISO 13485 quality management standards shape manufacturing protocols for device makers serving multiple regulatory jurisdictions. Stakeholders must monitor how evolving battery safety standards and electromagnetic compatibility directives reshape design requirements for rechargeable wireless configurations.
Market Dynamics
Portable diagnostic instruments are recalibrating competitive positioning across ophthalmic device supply chains as hospital outpatient departments prioritize bedside mobility over fixed infrastructure investments.
Growth Catalysts
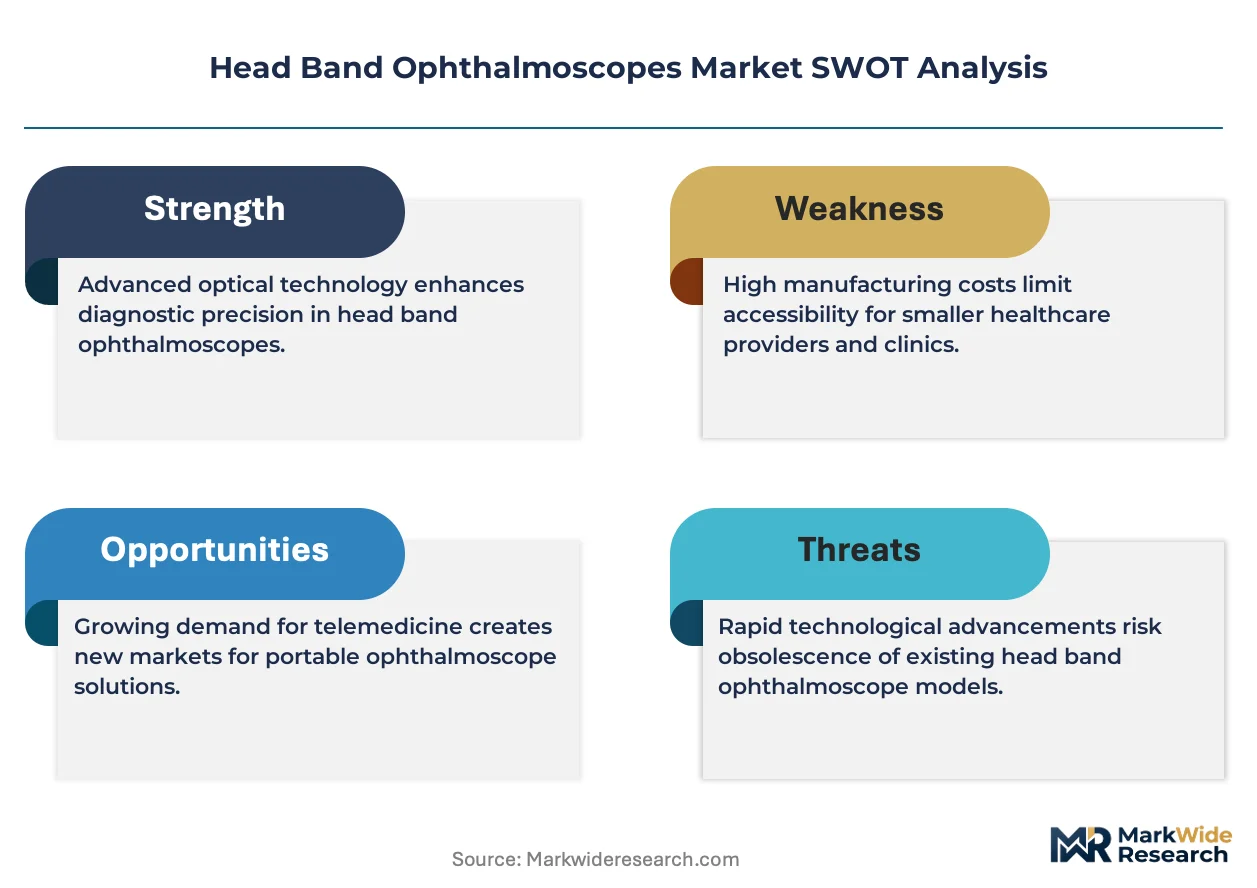
- EU MDR framework:Stricter clinical evidence requirements for CE marking elevate quality thresholds, filtering substandard entrants and rewarding manufacturers with robust quality management systems.
- Ambulatory surgical centers:These facilities are expanding procurement of rechargeable battery configurations that eliminate cord dependency during mobile screening workflows.
- Fiber optic illumination:German engineering heritage in precision optics manufacturing sustains premium positioning for high-performance illumination systems in tertiary care settings.
Market Restraints
- Input cost volatility:Rare earth elements in LED phosphors expose manufacturers to price swings from concentrated Chinese mining operations.
- Technical limitation:Halogen illumination's shorter operational lifespan and heat generation constrain deployment in high-throughput screening environments.
- Regulatory friction:FDA 510(k) clearance pathways impose documentation burdens that extend time-to-market for iterative design improvements.
Strategic Opportunities
- Underpenetrated rural India:Primary health centers lack fundus examination capacity, creating whitespace for battery-operated, training-light devices.
- Telemedicine convergence:Integration of head band ophthalmoscopes with smartphone-based image capture and cloud transmission enables remote specialist consultation.
- Japan's aging demographics:Home healthcare expansion under METI-supported initiatives drives demand for examiner-wearable diagnostics outside institutional walls.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits create 12-18 month gaps between design completion and commercial launch across multiple jurisdictions.
- Skill gap in fundus interpretation:Primary care physicians require structured training to achieve diagnostic competency with direct ophthalmoscopy techniques.
- Legacy system integration:Electronic health record compatibility varies across hospital networks, complicating seamless documentation of examination findings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head Band Ophthalmoscopes Market |
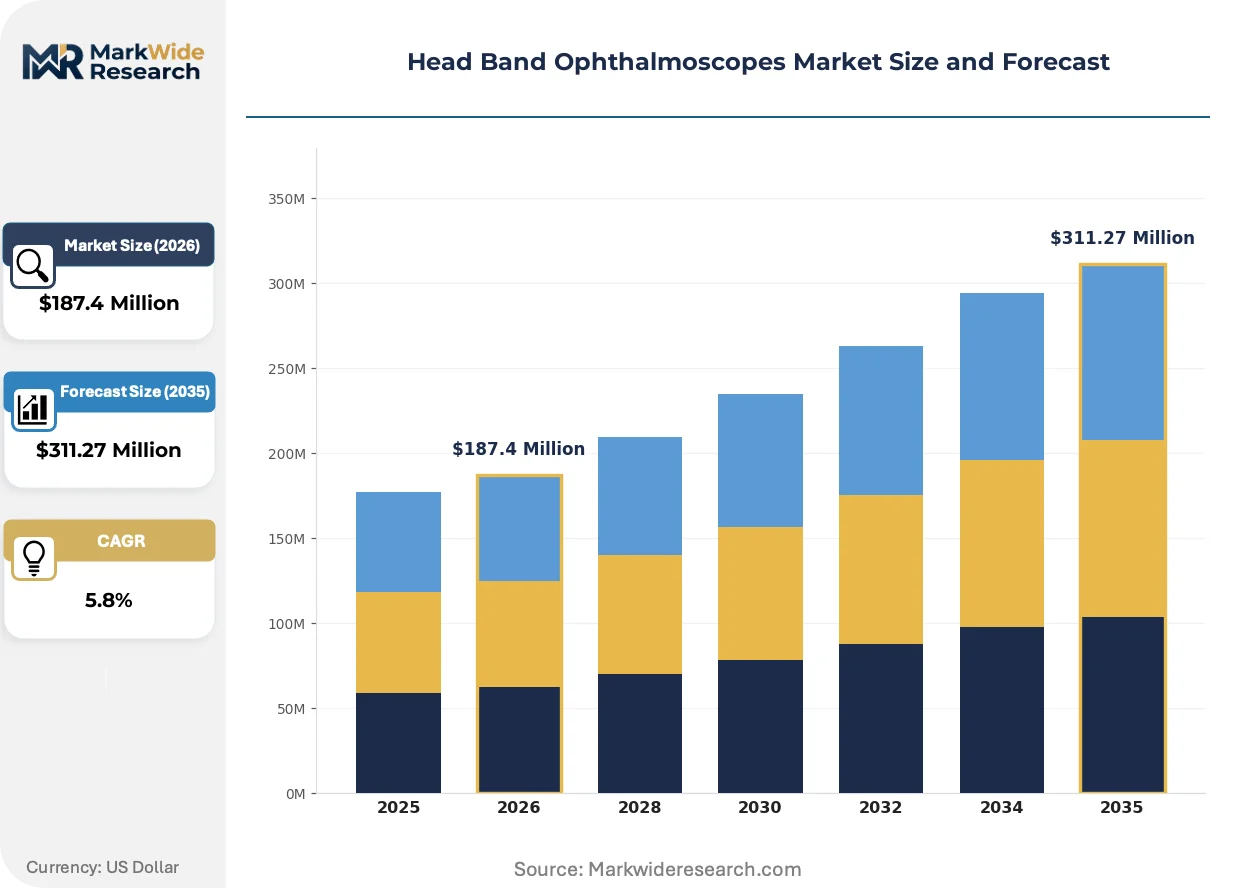
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Handheld, Rechargeable, Digital Technology: LED, Halogen, Fiber Optic, Fluorescence End User: Hospitals, Clinics, Eye Care Professionals, Research Institutes Application: Diagnostic Imaging, Vision Examination, Fundus Inspection, Education |
| Companies Covered | US Ophthalmic, Heine USA Ltd., Keeler Ltd., Welch Allyn, Carl Zeiss Meditec AG, Iridex Corporation, Alltion (Wuzhou) Co., Ltd., Propper Manufacturing, Oak Tree Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head Band Ophthalmoscopes Market Shifts & Advancements
Illumination technology, regulatory evidence standards, and procurement centralization are actively restructuring how head band ophthalmoscopes are designed, approved, and acquired across healthcare systems.
LED illumination is overtaking halogen as the dominant light source in new device installations due to superior energy efficiency and stable color temperature during extended examinations. Hospital outpatient departments in Germany and the United States are prioritizing LED-equipped units for high-volume diabetic retinopathy screening programs. This transition is compressing margins for manufacturers still maintaining halogen product lines while rewarding suppliers with mature LED optical engineering capabilities.
EU MDR's tightened clinical evidence requirements are extending CE marking timelines and elevating post-market surveillance obligations for ophthalmic diagnostic devices. Manufacturers must now generate prospective clinical data rather than relying on predicate device equivalence, increasing regulatory affairs staffing and external trial costs. Medium-scale device makers serving European markets are responding by consolidating product portfolios to focus resources on highest-margin configurations.
Buying committees in North American health systems are consolidating vendor relationships through multi-year enterprise agreements that bundle devices, disposables, and service contracts. Independent ophthalmology practices and smaller clinic networks face exclusion from preferred pricing tiers, compressing their supplier options. This concentration is most visible in integrated delivery networks across the United States, where standardization mandates reduce device variety in favor of simplified training and maintenance protocols.
Head Band Ophthalmoscopes Market Segmentation
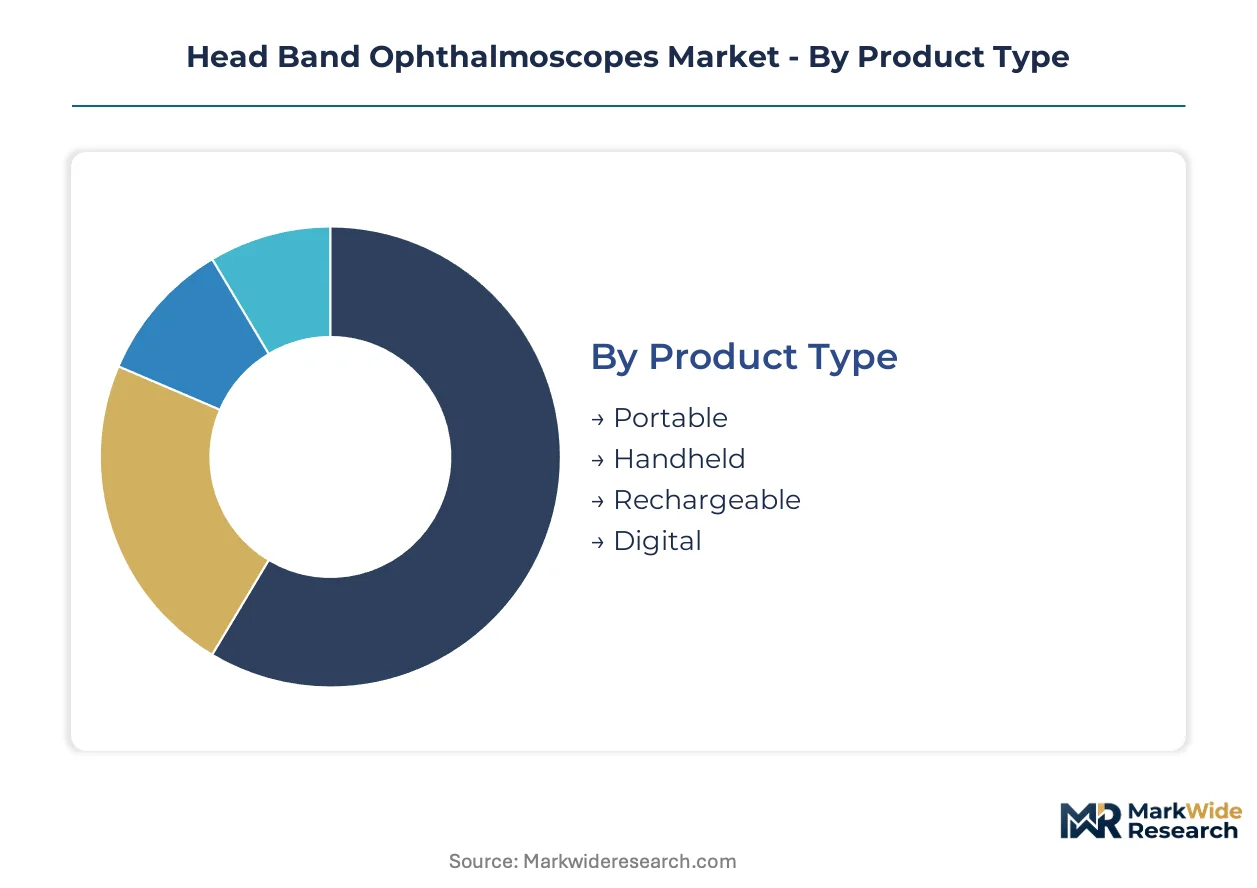
Segmentation in head band ophthalmoscopes reflects divergent clinical workflows across institutional and ambulatory settings. Procurement patterns vary sharply between high-throughput hospital screening programs and resource-constrained primary care deployments. Understanding these splits enables targeted positioning across reimbursement environments and regulatory jurisdictions.
Product Type:
Customization intensity spans from standardized handheld units to configurable rechargeable systems with modular battery packs and illumination sources.
- Portable:These units balance optical performance with transportability, typically weighing under 500 grams with detachable headbands. Demand concentrates in German hospital outpatient departments where bedside diabetic retinopathy screening requires mobility between wards. EU MDR compliance costs favor manufacturers with established quality management systems.
- Handheld:Compact single-piece designs dominate high-volume clinic deployments in the United States. Procurement committees in integrated delivery networks prioritize standardized training protocols and simplified maintenance contracts over feature depth.
- Rechargeable:Lithium-ion configurations eliminate cord dependency during mobile examinations. Indian primary health centers drive adoption where unreliable grid power constrains corded device utility.
- Digital:Integrated image capture and wireless transmission capabilities support telemedicine workflows. Japanese home healthcare expansion under METI initiatives creates demand for examiner-wearable diagnostics with seamless documentation.
Most installed capacity flows through Handheld configurations. Expansion is steepest in Rechargeable systems.
Technology:
Cost tiers separate premium fiber optic and fluorescence systems from mass-market LED and legacy halogen alternatives.
- LED:Solid-state illumination delivers stable color temperature and 50,000-hour operational lifespan. Hospital outpatient departments in the United States and Germany prioritize LED-equipped units for extended screening sessions. Energy efficiency reduces total cost of ownership in high-utilization environments.
- Halogen:Tungsten-filament sources provide warm color rendering valued by experienced examiners. Replacement bulb costs and heat generation constrain deployment in Japan's expanding home healthcare sector where device longevity matters.
- Fiber Optic:Precision light guides enable uniform illumination across wide field angles. German medical device manufacturing corridors sustain premium positioning through engineering heritage in optical component fabrication.
- Fluorescence:Excitation-emission capabilities support retinal pathology screening with contrast-enhanced visualization. Research institutes in Switzerland and academic medical centers command specialized procurement budgets for advanced diagnostic modalities.
Volume concentrates in LED technology. Fiber Optic commands the steepest margin expansion trajectory.
End User:
Customer type determines specification requirements, with hospitals demanding integration capabilities and eye care professionals prioritizing optical precision.
- Hospitals:Enterprise procurement mandates standardized device fleets with electronic health record compatibility. FDA 510(k) clearance and ISO 13485 certification filter supplier pools in the United States.
- Clinics:Independent practice economics favor durable mid-tier configurations with extended warranty coverage. Reimbursement pressure constrains capital equipment budgets.
- Eye Care Professionals:Optometrists and ophthalmologists in private practice demand adjustable diopter ranges and superior optical clarity. Premium positioning rewards manufacturers with specialized optics expertise.
- Research Institutes:Academic medical centers require fluorescence-enabled devices and documentation capabilities for clinical trial protocols. Funding cycles create lumpy procurement patterns.
Procurement volume concentrates in Hospitals. Eye Care Professionals represent the steepest expansion trajectory as scope-of-practice expansion enables independent diagnostic authority.
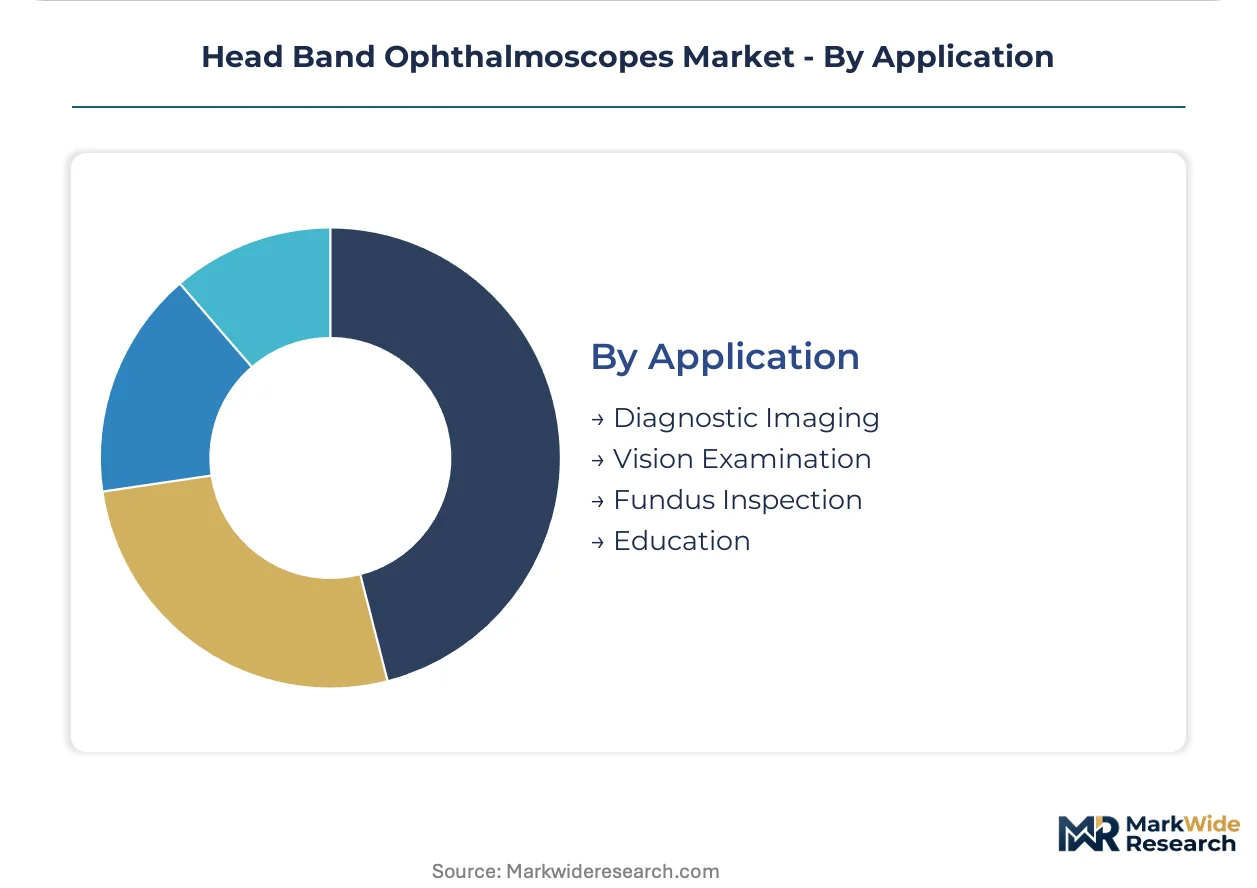
Application:
Maturity gradients separate established diagnostic imaging from emerging telemedicine-integrated workflows.
- Diagnostic Imaging:Standard fundus photography and documentation for disease monitoring. Reimbursement codes in the United States and Germany support routine screening program economics.
- Vision Examination:Refractive assessment and visual acuity testing integration. Primary care clinics in India leverage portable devices for outreach programs.
- Fundus Inspection:Direct visualization of retina, optic disc, and posterior pole structures. Skill requirements limit deployment to trained examiners.
- Education:Training devices with augmented reality overlays and simulation capabilities. Medical schools in Japan and Switzerland invest in competency-based curricula.
Diagnostic Imaging captures most procedure volume. Education represents the steepest expansion trajectory as simulation-based training displaces traditional apprenticeship models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate toward jurisdictions with streamlined quality management certification. Cost-of-compliance gaps between FDA 510(k) pathways and EU MDR frameworks are accelerating facility relocation decisions.
United States
Hospital outpatient departments in the United States drive procurement of LED-equipped units for diabetic retinopathy screening programs. FDA 510(k) clearance pathways filter supplier pools while elevating documentation burdens for iterative design improvements. The Greater Boston medical device cluster anchors innovation in fiber optic illumination systems.
Germany
German hospital networks prioritize portable configurations enabling bedside mobility between wards. EU MDR framework imposes stricter clinical evidence requirements for CE marking, extending timelines for medium-scale device makers. The medical device manufacturing corridor in Baden-Württemberg sustains premium positioning through precision optics engineering heritage.
Japan
Home healthcare expansion under METI-supported initiatives drives demand for examiner-wearable diagnostics outside institutional walls. PMDA regulatory alignment with international standards streamlines approval for rechargeable wireless configurations. The Kanto region around Tokyo concentrates distribution infrastructure for ambulatory surgical center supply chains.
India
Primary health centers in rural India lack fundus examination capacity, creating whitespace for battery-operated, training-light devices. CDSCO oversight of medical device imports shapes procurement patterns for public health programs. Manufacturing activity concentrates in Maharashtra and Gujarat for cost-competitive component assembly.
Switzerland
Research institutes and academic medical centers command specialized procurement budgets for fluorescence-enabled diagnostic modalities. Swissmedic maintains rigorous post-market surveillance obligations that parallel EU MDR stringency. The Basel pharmaceutical-industrial complex generates adjacent demand for clinical trial documentation capabilities.
Head Band Ophthalmoscopes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium illumination systems concentrating around German engineering heritage while volume production migrates toward Asian assembly bases. The vendor base organizes into three tiers: multinational device conglomerates with enterprise distribution reach, mid-scale specialists with optical component expertise, and regional assemblers serving price-sensitive procurement channels. Strategic archetypes include fiber optic engineering specialists, rechargeable battery integrators, and telemedicine platform partners. Competitive moves center on M&A consolidation of optical component suppliers and geographic expansion through distributor acquisition.
Among German-origin precision manufacturers, Heine USA Ltd. and Carl Zeiss Meditec AG occupy positions anchored by engineering heritage in illumination systems. Keeler Ltd. represents the United Kingdom-based specialist archetype with concentrated optics manufacturing capabilities. Welch Allyn exemplifies the North American channel control model through clinic network distribution reach. These three entities illustrate how geographic origin and organizational structure map to distinct competitive positioning vectors.
| Leading Market Players |
|---|
| US Ophthalmic |
| Heine USA Ltd. |
| Keeler Ltd. |
| Welch Allyn |
| Carl Zeiss Meditec AG |
| Iridex Corporation |
| Alltion (Wuzhou) Co., Ltd. |
| Propper Manufacturing |
| Oak Tree Group |
| Others |
Supply & Pricing Matrix
Precision optics engineers in Baden-Württemberg command wage premiums that propagate through three-tier pricing structures separating fiber optic systems from LED configurations and halogen economy units. Labor-cost differentials between German engineering corridors and Asian assembly bases sustain margin spreads exceeding certification-grade differentials alone.
Pricing Analysis
Distributor margins absorb 15-25 points before hospital procurement committees, compressing manufacturer net pricing power at the OEM tier. Pricing stratifies across premium, standard, and economy tiers anchored by ISO 13485 certification grade and fiber optic illumination performance. Cost compression in halogen configurations is intensifying because LED energy efficiency reduces total cost of ownership claims. Ambulatory surgical centers exhibit highest price sensitivity; research institutes command lowest sensitivity due to grant-funded procurement.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Chicago, and Tokyo orchestrate hub-and-spoke patterns reaching hospital networks and clinic chains. Manufacturing concentrates in Germany for precision optical components, China for LED module assembly, and India for battery pack integration. Rare earth phosphors, lithium-ion cells, and precision-molded housings anchor input dependencies. Single-source vulnerability in Chinese rare earth processing exposes margin stability to export restriction risk. Distribution runs through authorized medical device distributors with ISO 13485-certified warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance cost differentials between established German manufacturers and Asian assemblers create geographic-arbitrage opportunities for quality-certified production relocation. FDA 510(k) documentation burdens versus PMDA streamlined pathways reward dual-track regulatory strategies.
For Market Incumbents: Lock in fiber optic illumination supply through backward integration into Baden-Württemberg optical component suppliers. Expand rechargeable battery certification investment to preempt emerging entrants from Indian manufacturing bases. Defend against telemedicine-integrated digital ophthalmoscope substitutes by embedding software documentation capabilities in core product lines. For New Entrants and Emerging Players: Launch via direct-to-clinic distribution models bypassing consolidated hospital buying committees in United States integrated delivery networks. Target rural Indian primary health centers with training-light, battery-operated configurations. Exploit whitespace in Japanese home healthcare expansion under METI-supported initiatives through examiner-wearable diagnostic positioning. For Investors and Strategic Acquirers: Mid-scale optical specialists with ISO 13485 certification and established CE marking track records represent the most active acquirer target category in this space. Long-term viability over the next decade hinges on telemedicine platform integration capabilities and fluorescence-enabled device portfolios. Monitor PMDA approval velocity for rechargeable wireless configurations as inflection indicator for Japanese market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter substandard competitors from European hospital procurement pools. |
| Hospital System Partnership | Enterprise agreements with United States integrated delivery networks secure multi-year device fleet standardization mandates. |
| Software Companion Development | Smartphone-based image capture integration enables telemedicine workflows for Japanese home healthcare expansion. |
| Reimbursement Strategy | Diabetic retinopathy screening code alignment supports clinic economics for portable device adoption in Germany. |
| FDA Submission | 510(k) clearance pathway access determines supplier pool eligibility for United States hospital outpatient departments. |
Research Methodology
Direct dialogue with ophthalmology department heads, biomedical engineering procurement leads, GPO contracts managers, and optical component suppliers grounded qualitative assessment. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up installation base estimates and top-down healthcare capital expenditure flows were triangulated for convergence.
Segment-level projections across the analysis window reflect modeled splits by product type, illumination technology, end-user institution class, and geographic regulatory cluster. CAGRs were derived from weighted-average growth contributions across portable, handheld, rechargeable, and digital configuration trajectories. Forecast inputs incorporated EU MDR implementation timelines, METI home healthcare subsidy schedules, and Indian primary health center infrastructure buildout assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under battery safety standard revisions and rare earth export restriction scenarios. Outputs reflect documented assumptions regarding regulatory clearance timelines and reimbursement code stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market