
 Astigmatism Market | 2026-2036
Astigmatism Market Size, Share, and Industry Trends Forecast 2026-2036
Astigmatism Market Analysis
Premium toric lens specifications is bifurcating the competitive landscape into precision-manufactured and value-tier suppliers. Johnson & Johnson Services, Inc. leverages its silicone hydrogel portfolio to dominate North American specialty channels. EssilorLuxottica anchors European distribution through its integrated lens-retail network. CooperVision differentiates via extended-parameter toric designs for high-astigmatism prescriptions.
Astigmatism denotes a refractive error caused by an irregularly curved cornea or lens, typically measured in diopters of cylinder power and axis orientation from 0 to 180 degrees, requiring cylindrical correction rather than spherical optics alone. Its primary commercial purpose centers on restoring visual acuity through customized optical or surgical intervention. Toric lenses and laser surgery command the largest margin pools, while wavefront technology represents the fastest-advancing segment due to personalized ablation profiles. Corrective lenses remain the volume backbone across optometrist and ophthalmologist channels, though surgical procedures capture premium pricing in hospital settings.
The FDA oversees contact lens safety and laser device approvals in the United States, while the EU Medical Device Regulation mandates clinical evidence for toric and implantable lens categories in Europe. India's CDSCO aligns with ISO 13485 for ophthalmic device manufacturing, tightening quality thresholds for imported lenses. Stakeholders must weigh regulatory compliance costs against premium positioning in wavefront-guided surgical platforms and next-generation silicone hydrogel materials.
Market Dynamics
The astigmatism market pivots on tightening EU Medical Device Regulation requirements for toric lenses, which is forcing manufacturers to restructure clinical evidence portfolios and redirect R&D spending toward precision-manufacturing capabilities.
Growth Catalysts
- EU MDR compliance mandates:Clinical evidence requirements for toric and implantable lens categories are accelerating consolidation among manufacturers with robust quality management systems.
- LASIK adoption in urban ophthalmology centers:India's metropolitan clusters demonstrate concentrated demand for laser vision correction among younger demographics seeking spectacle independence.
- Extended-parameter toric designs:High-astigmatism prescriptions previously underserved by standard offerings now access customized optical solutions through advanced silicone hydrogel materials.
Market Restraints
- Silicone hydrogel raw material concentration:Supply of specialized polymers for premium toric lenses concentrates among a limited base of chemical suppliers, creating input cost volatility.
- Wavefront technology capex barriers:Personalized ablation platforms require substantial capital deployment for femtosecond laser systems and diagnostic equipment.
- CDSCO alignment with ISO 13485:India's tightened quality thresholds for imported lenses extend certification timelines and elevate compliance costs for foreign manufacturers.
Strategic Opportunities
- Underpenetrated rural India:Tier-2 and Tier-3 cities present white space for spectacle-based correction as awareness campaigns and optometrist networks expand beyond metropolitan boundaries.
- Integrated lens-retail distribution:Direct-to-consumer channels and tele-optometry platforms are emerging as alternative pathways bypassing traditional wholesale intermediaries.
- PLI scheme alignment:India's production-linked incentive framework for medical devices offers tariff advantages and capital subsidies for domestic manufacturing of ophthalmic lenses.
Industry Challenges
- Specialized optometrist training gaps:Wavefront-guided surgical platforms and advanced toric fitting protocols require practitioners with expertise in corneal topography interpretation and customized lens design.
- Legacy practice management integration:Electronic health record systems and diagnostic device connectivity create friction during technology transitions in established ophthalmology clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Astigmatism Market |
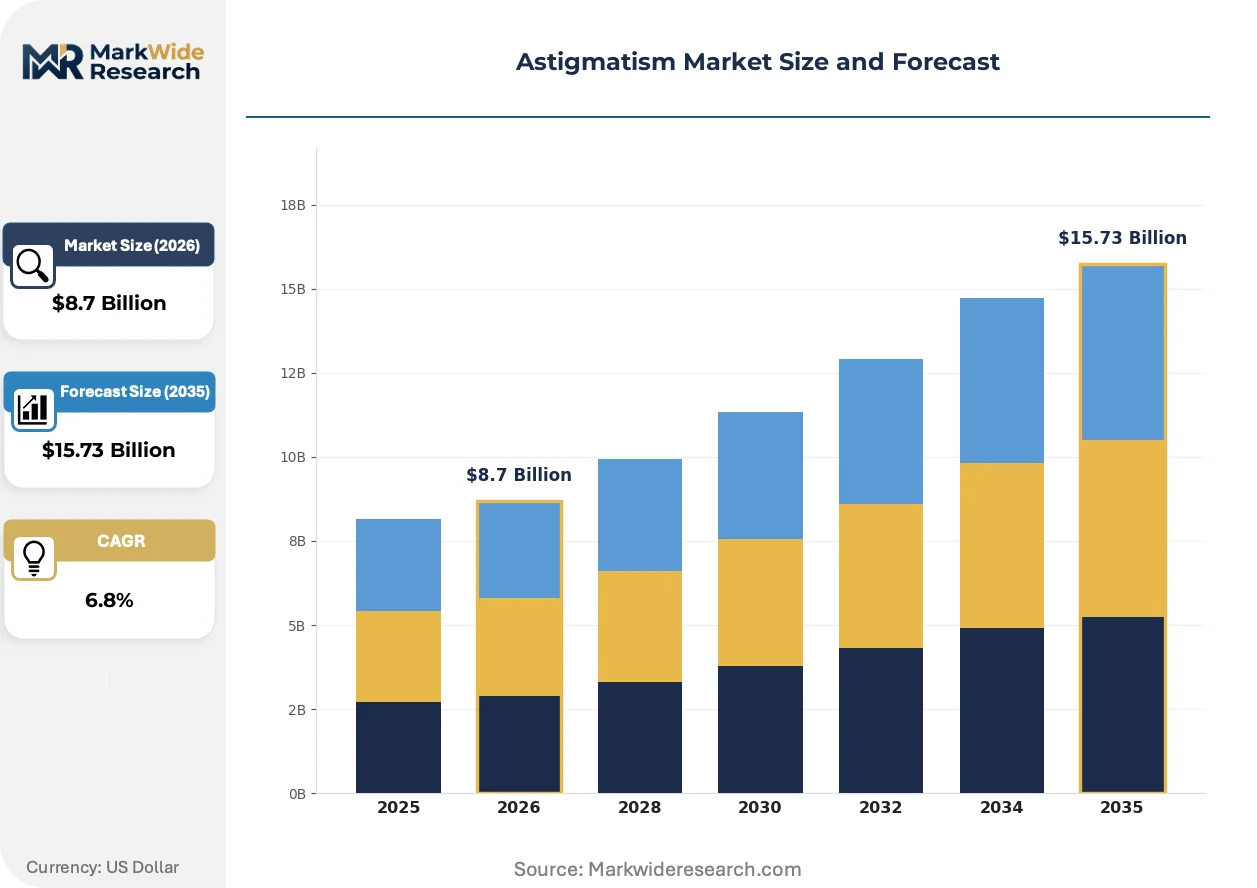
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrective Lenses, Toric Lenses, Eye Drops, Surgical Procedures Application: Vision Correction, Specialty Care, Preventive Care, Diagnostics End User: Optometrists, Ophthalmologists, Clinics, Hospitals Technology: Laser Surgery, Photorefractive Keratectomy, Implantable Lenses, Wavefront Technology |
| Companies Covered | Novartis AG, Johnson & Johnson Services, Inc., Bausch + Lomb, Alcon, CooperVision, Carl Zeiss Meditec AG, EssilorLuxottica, SEA VISION S.r.l., HOYA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Astigmatism Market Emerging Trajectories
Wavefront-guided ablation technology is reshaping surgical correction protocols, while regulatory harmonization efforts and shifting patient acquisition channels are restructuring how astigmatism solutions reach end-users.
Femtosecond laser platforms for astigmatism correction is bifurcating the surgical segment into premium wavefront-guided procedures and standard LASIK offerings. Refractive surgery centers in Germany and the United States are adopting these systems at differentiated paces based on reimbursement structures. This technology is compressing margins for conventional microkeratome-based procedures while enabling premium pricing for customized ablation profiles.
The EU Medical Device Regulation mandates clinical evidence for toric lens categories, elevating documentation requirements beyond previous CE-marking thresholds. Manufacturers must now submit post-market surveillance data and biocompatibility studies for extended-parameter designs. Specialty care clinics in Germany and France are responding by consolidating supplier relationships toward vendors with established MDR-compliant portfolios.
Patient acquisition is migrating toward digital consultation platforms and direct-to-consumer vision testing applications. Traditional optometrist channels face disintermediation as younger demographics in India's urban centers research LASIK providers through online comparison tools before booking procedures. This behavioral shift concentrates marketing spend toward search-optimized platforms and telemedicine-enabled pre-screening services.
Astigmatism Market Segmentation
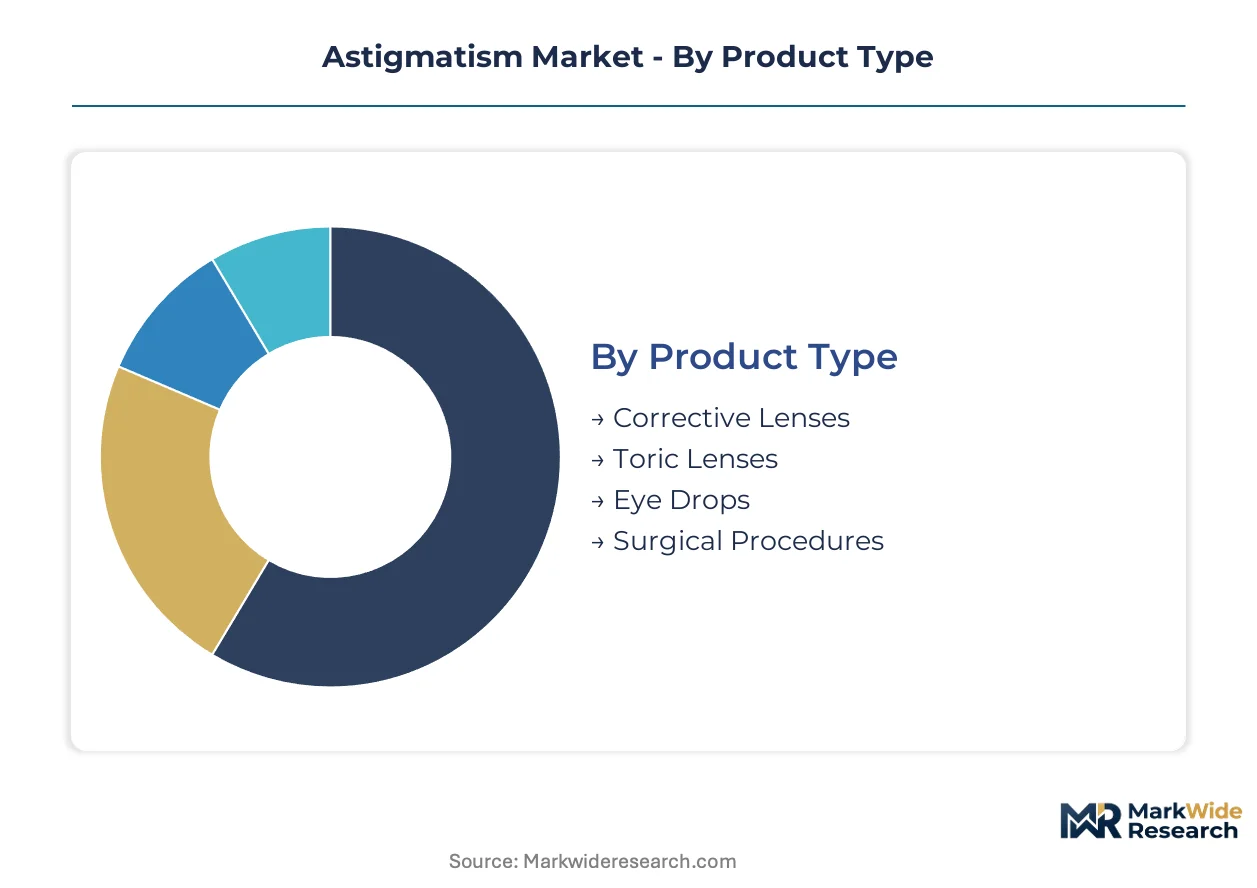
Astigmatism correction spans optical, pharmaceutical, and surgical modalities, each governed by distinct regulatory pathways and reimbursement structures. Segmentation reveals where margin concentration aligns with clinical complexity versus where volume scale dominates through standardized distribution.
Product Type:
FDA 510(k) clearances and EU MDR clinical evidence requirements create divergent compliance burdens across optical versus pharmaceutical categories.
- Corrective Lenses:Spherical-cylindrical spectacles address low-to-moderate astigmatism through standardized prescription fulfillment. Volume concentrates in India's urban optometry chains and Germany's statutory health insurance reimbursement channels, constrained by margin compression in commoditized lens finishing.
- Toric Lenses:Silicone hydrogel contact lenses incorporate cylindrical power and axis stabilization through prism ballast or thin-zone designs. Demand clusters in North American specialty care clinics seeking extended-parameter fittings for high-astigmatism prescriptions previously excluded from soft lens correction.
- Eye Drops:Topical formulations target symptomatic relief from astigmatism-related visual fatigue rather than refractive correction. CDSCO registration requirements in India and FDA ophthalmic drug approvals govern market access.
- Surgical Procedures:Corneal reshaping through excimer laser or femtosecond platforms commands premium pricing in hospital settings. Reimbursement variability across German statutory funds and US commercial payers segments adoption.
Established volume favors corrective lenses; emerging adoption favors toric lenses.
Application:
Clinical purpose determines whether procurement flows through retail optical channels or institutional purchasing frameworks.
- Vision Correction:Primary refractive intervention through lenses or surgery to restore visual acuity. Volume concentrates in India's metropolitan ophthalmology centers where LASIK adoption accelerates among younger demographics.
- Specialty Care:Complex astigmatism management including post-keratoplasty or irregular cornea cases requiring customized solutions. German specialty clinics now source exclusively MDR-compliant toric portfolios, consolidating supplier relationships.
- Preventive Care:Early screening and progression monitoring in pediatric and young adult populations. School-based vision programs in India and employer wellness initiatives in the United States drive demand.
- Diagnostics:Corneal topography, wavefront aberrometry, and biometry for treatment planning. Capital equipment procurement concentrates in hospital ophthalmology departments and high-volume refractive surgery centers.
Volume scale anchors vision correction; margin expansion concentrates in specialty care.
End User:
Channel structure fragments between retail-accessible optometry and gated specialist referral pathways.
- Optometrists:Primary vision care providers managing routine astigmatism diagnosis and lens-based correction. India's expanding optometrist networks in Tier-2 and Tier-3 cities present white space for spectacle-based volume growth.
- Ophthalmologists:Medical and surgical specialists handling complex cases and refractive procedures. Femtosecond laser platform adoption concentrates in urban ophthalmology centers seeking premium surgical positioning.
- Clinics:Dedicated refractive surgery or contact lens specialty facilities. German specialty care clinics demonstrate concentrated demand for MDR-documented toric lens portfolios.
- Hospitals:Institutional settings capturing surgical volume and complex pathology referrals. Reimbursement structures in the United States and Germany determine capital equipment deployment for wavefront-guided platforms.
Patient acquisition is migrating toward clinic-based specialty care; hospitals retain complex surgical volume.
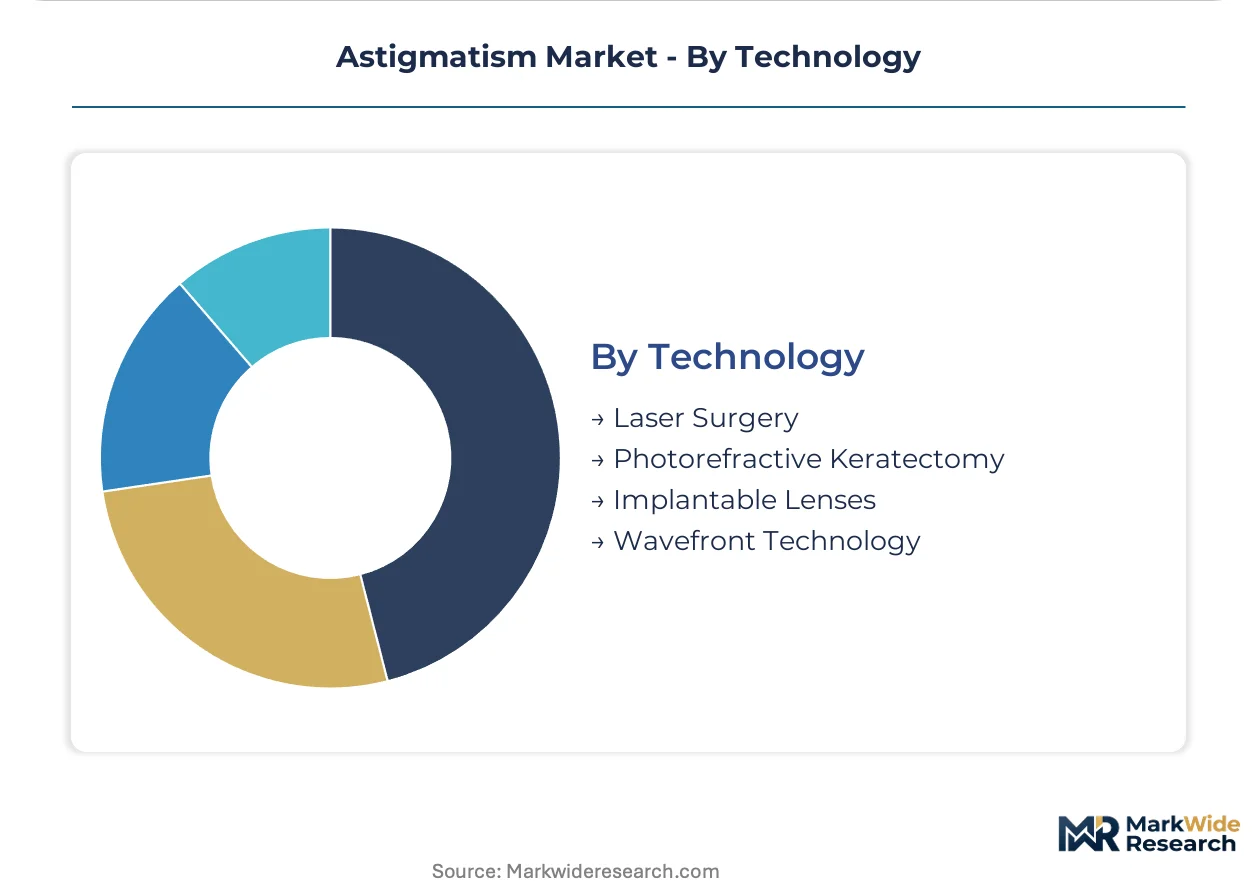
Technology:
Capital intensity and regulatory classification separate surgical platforms from implantable and diagnostic categories.
- Laser Surgery:LASIK and PRK procedures using excimer laser ablation for corneal reshaping. India's urban centers demonstrate fastest expansion among younger demographics seeking spectacle independence.
- Photorefractive Keratectomy:Surface ablation technique preserving corneal biomechanical integrity. Demand concentrates in military and aviation screening populations where flap-related complications carry occupational consequences.
- Implantable Lenses:Phakic intraocular lenses and toric IOLs for high astigmatism beyond laser correction range. EU MDR clinical evidence requirements elevate documentation thresholds for extended-parameter designs.
- Wavefront Technology:Customized ablation profiles based on individual optical aberration mapping. Steepest expansion trajectory among premium refractive platforms, constrained by femtosecond laser system capex barriers.
Standard LASIK commands current surgical volume; wavefront-guided platforms capture premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-manufactured toric lenses to specialty clinics across France and the Netherlands under tightened EU Medical Device Regulation documentation requirements. Trade corridors from the United States supply wavefront-guided surgical platforms to hospital systems in Canada and Mexico.
United States
FDA 510(k) clearances for silicone hydrogel toric lenses and excimer laser platforms concentrate procurement in metropolitan ophthalmology centers. Commercial payer reimbursement variability segments adoption of femtosecond systems across hospital networks. Refractive surgery volume clusters in California and Texas urban corridors where younger demographics seek spectacle independence.
Germany
EU MDR clinical evidence mandates for implantable and toric lens categories consolidate supplier relationships toward MDR-documented portfolios. Statutory health insurance reimbursement channels anchor corrective lens volume in optometry chains. Specialty care clinics in Bavaria and North Rhine-Westphalia now source exclusively from manufacturers with established quality management systems.
India
CDSCO alignment with ISO 13485 tightens quality thresholds for imported lenses while extending certification timelines. PLI scheme capital subsidies attract domestic manufacturing investment for ophthalmic devices. LASIK adoption accelerates in Maharashtra and Karnataka urban centers where metropolitan ophthalmology clusters serve younger patient demographics.
Japan
PMDA oversight of contact lens safety and laser device approvals governs market access for imported toric and surgical platforms. Aging demographics sustain demand for presbyopia-correcting toric designs in Tokyo and Osaka metropolitan areas. Domestic manufacturers leverage JIS standards compliance to defend positioning in premium silicone hydrogel segments.
China
NMPA registration requirements for ophthalmic devices elevate documentation burdens for foreign toric lens manufacturers seeking market entry. MIIT industrial policy supports domestic production of femtosecond laser systems for refractive surgery centers. Demand concentrates in Yangtze River Delta and Pearl River Delta urban clusters where private hospital chains deploy capital equipment.
Astigmatism Market Vendor Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and precision-manufacturing scale. The vendor base stratifies into three tiers: multinational conglomerates with integrated lens-retail networks, mid-cap specialists in extended-parameter toric designs, and regional fabricators serving price-sensitive spectacle markets. Dominant competitive moves include M&A to secure silicone hydrogel material supply and strategic partnerships with refractive surgery centers for wavefront platform placement.
Within the multinational tier, Johnson & Johnson Services, Inc. and EssilorLuxottica occupy positions anchored by distribution breadth and regulatory dossier depth. CooperVision exemplifies the specialist archetype through its focus on high-astigmatism prescription segments. Carl Zeiss Meditec AG represents the precision-surgical equipment vector, with its German origin signaling engineering-intensive platform development. These three named entities collectively illustrate how competitive positioning depends on vertical control over either material supply, retail channel access, or capital equipment technology.
| Leading Market Players |
|---|
| Novartis AG |
| Johnson & Johnson Services, Inc. |
| Bausch + Lomb |
| Alcon |
| CooperVision |
| Carl Zeiss Meditec AG |
| EssilorLuxottica |
| SEA VISION S.r.l. |
| HOYA Corporation |
| Others |
Supply Flow & Price Mechanics
Silicone hydrogel material substitution for conventional hydrogel polymers is redrawing procurement geography toward German and US chemical suppliers while compressing margin structures for toric lens manufacturers absorbing input cost volatility.
Pricing Analysis
Wavefront-guided femtosecond platforms versus standard LASIK versus legacy microkeratome procedures define a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA 510(k) clearance tier and customization depth for aberration correction. Pricing pressure stems from EU MDR documentation burdens elevating compliance overhead. Price-sensitive volume concentrates in India's urban spectacle chains; least sensitivity appears in German specialty clinics sourcing MDR-compliant extended-parameter toric portfolios.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for silicone hydrogel raw materials sourced from South Korean and Japanese chemical suppliers. Manufacturing concentrates in Germany, the United States, and Ireland for precision toric lens finishing. Supply chains rest on specialized polymer feedstocks, precision molding equipment, and biocompatibility certification documentation. Single-source vulnerability concentrates in silicone hydrogel resin supply. Distribution runs through optometrist chains, ophthalmology clinic networks, and hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EU MDR clinical evidence requirements create multi-year barriers to supplier qualification that protect incumbent positions.
For Market Incumbents: Shield market position through backward integration into silicone hydrogel material supply and accelerated MDR dossier expansion for extended-parameter toric designs. Emerging Asian manufacturers with ISO 13485 alignment threaten mid-tier positioning. Channel control via exclusive refractive surgery center partnerships represents the critical defensive lever. For New Entrants and Emerging Players: Post-operative care service gaps in wavefront-guided surgery follow-up present white space where incumbents under-serve patient retention and outcome monitoring. India's Tier-2 and Tier-3 cities offer the most penetrable geography for spectacle-based volume entry. Tele-optometry-enabled pre-screening services provide a differentiated go-to-market angle bypassing traditional wholesale intermediaries. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-manufacturing specialists with established regulatory dossiers. Long-term viability over a multi-year horizon rests on EU MDR compliance depth rather than commodity scale. Acquisition targets should demonstrate quality management system maturity and extended-parameter toric design capabilities. The signal to watch is CDSCO certification timeline compression for imported lens categories.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Portfolio Expansion | MDR-compliant dossiers unlock German specialty clinic procurement and consolidate supplier relationships. |
| Silicone Hydrogel Material Backward Integration | In-house polymer production insulates margin structures from chemical supplier concentration risk. |
| Refractive Surgery Center Partnership Network | Exclusive platform placement agreements secure femtosecond laser system utilization and patient flow. |
| Tele-Optometry Pre-Screening Platform Launch | Digital patient acquisition channels capture younger demographics researching LASIK through online comparison tools. |
| Extended-Parameter Toric Design R&D Investment | High-astigmatism prescription solutions access underserved segments previously excluded from soft lens correction. |
Methodological Framework
Cross-validation between ophthalmologist interviews and optical industry trade data anchors the qualitative findings for this analysis. Primary research incorporated discussions with refractive surgeons, optometrist network managers, hospital purchasing committee members, and silicone hydrogel material procurement specialists. Secondary sources included FDA 510(k) clearance databases, EU MDR notified body documentation, CDSCO import registration records, and hospital capital equipment procurement disclosures. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation refined segment-level estimates.
Sensitivity analysis around LASIK adoption trajectories and toric lens replacement rates shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, application purpose, end-user channel, and technology platform. CAGRs derived from fitted growth curves applied to base-year estimates. Industry-specific forecast inputs included EU MDR transition timelines, PLI scheme subsidy disbursement patterns, and femtosecond laser system placement rates.
Forecasts assume regulatory continuity in FDA, EU MDR, and CDSCO regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Vision Care Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Tonometry Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Retina Health Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Europe Dry Eye Syndrome Market