
 Ophthalmic Lasers Market | 2026-2036
Ophthalmic Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Lasers Market Intelligence
Ophthalmic laser engineering talent is bifurcating between legacy photocoagulation specialists and next-generation femtosecond platform developers. Carl Zeiss Meditec leverages its Stuttgart engineering base to sustain dominance in corneal diagnostic-laser integration. Lumenis Be Ltd. competes through diversified energy platforms spanning retina and glaucoma workflows. NIDEK Co., Ltd. anchors its position in the Asia-Pacific corridor through cost-calibrated excimer and diagnostic systems.
Ophthalmic lasers are precision photonic instruments that deliver focused coherent light at specific wavelengths—typically 193 nm for excimer corneal ablation, 1053 nm for Nd:YAG posterior capsulotomy, and 800 nm femtosecond pulses for intrastromal incisions—to achieve tissue photodisruption, photoablation, or photocoagulation without thermal collateral damage. Femtosecond platforms command premium positioning in refractive and cataract applications due to bladeless precision and reduced endothelial cell loss. Photocoagulation technology retains the largest installed base across retinal disorder management, while optical coherence-guided laser systems represent the fastest-growing margin pool through real-time tomographic feedback integration.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements that reshape product development timelines and market access costs for laser manufacturers. ISO 13485 quality management certification and IEC 60601-1-2 electromagnetic compatibility standards function as baseline commercial prerequisites across all target jurisdictions. Stakeholders must monitor reimbursement volatility for femtosecond-assisted cataract procedures versus conventional phacoemulsification, as payer decisions will determine capital equipment replacement cycles and technology upgrade trajectories.
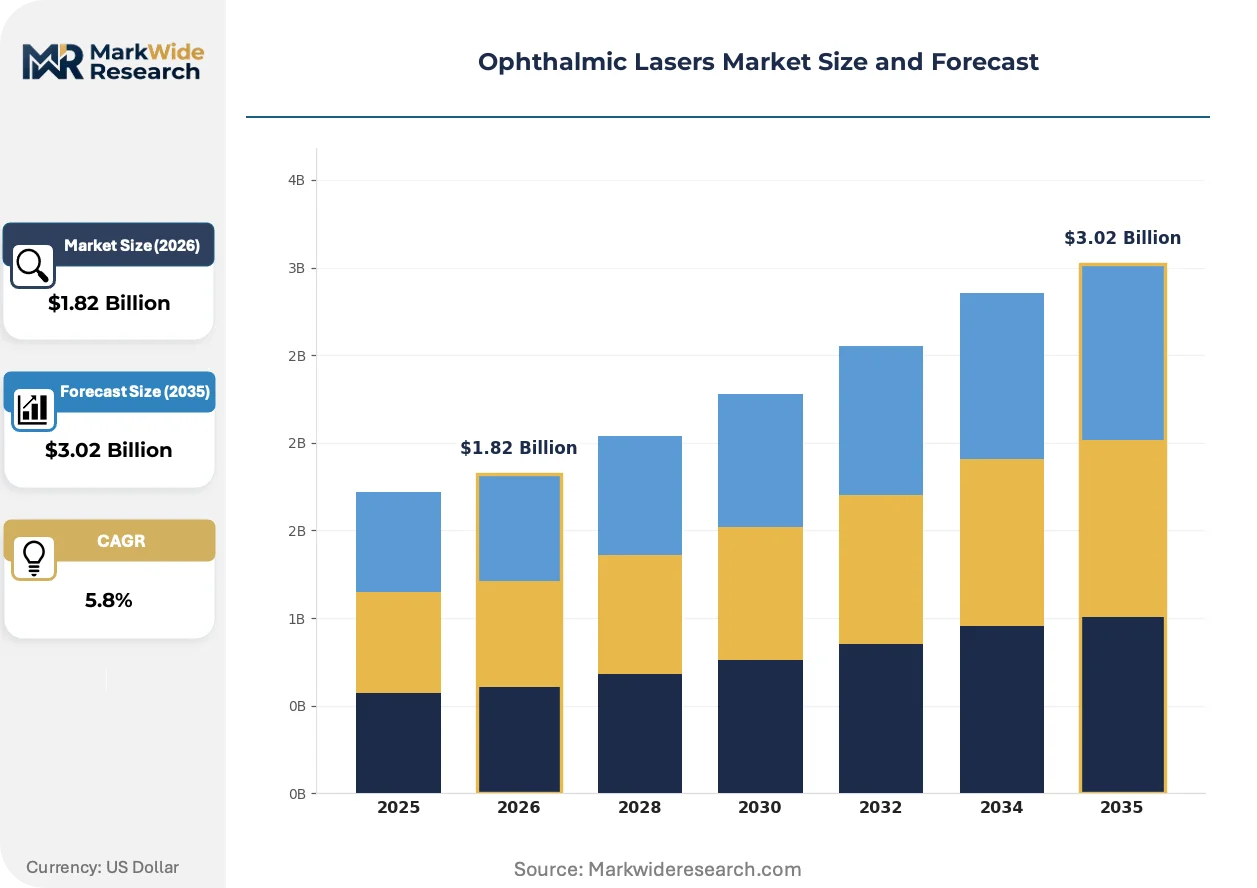
Market Dynamics
Femtosecond laser platforms are compressing procedural variance in cataract and refractive surgery, forcing capital equipment cycles to synchronize with optical coherence tomography integration roadmaps rather than standalone replacement schedules.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:Streamlined conformity assessment for laser-integrated diagnostic systems accelerates multi-country commercial deployment across Germany, France, and Italy.
- Bladeless cataract workflows:Femtosecond capsulotomy and lens fragmentation reduce endothelial cell trauma, driving hospital procurement of integrated laser-phaco platforms.
- Stuttgart precision manufacturing cluster:Concentrated optomechanical engineering talent enables rapid prototyping of next-generation scanning optics for corneal applications.
Market Restraints
- Excimer gas supply volatility:Krypton fluoride and argon fluoride gas procurement costs fluctuate with semiconductor industry demand, compressing margins on 193 nm laser maintenance contracts.
- Single-source femtosecond oscillator dependency:German and US suppliers control titanium-sapphire and ytterbium fiber seed laser production, creating vulnerability for Asian OEMs.
- Thermal damage threshold limitations:Photocoagulation wavelengths above 800 nm risk collateral retinal tissue effects, restricting power scaling in diabetic retinopathy protocols.
Strategic Opportunities
- India's tier-2 city ophthalmology expansion:Cost-calibrated excimer and Nd:YAG platforms address cataract backlog in Nagpur, Indore, and Coimbatore where surgical density remains below metropolitan benchmarks.
- Optical coherence-guided laser convergence:Real-time tomographic feedback integration enables sub-10-micron precision in stromal dissection, opening corneal inlay and intrastromal ring segment applications.
- US Medicare Advantage femtosecond carve-outs:Selective reimbursement riders for laser-assisted cataract procedures create channel for premium platform placement in ambulatory surgery centers.
Industry Challenges
- Fiber laser engineering scarcity:Femtosecond pulse compression and chirped pulse amplification expertise concentrates in Stuttgart, Rochester, and Tokyo, constraining platform development timelines.
- ISO 13485 certification latency:Design history file and risk management documentation requirements extend quality system implementation by 14-18 months for novel wavelength platforms.
- Legacy photocoagulator integration friction:Retinal surgeons face workflow disruption when retrofitting slit-lamp delivery systems with OCT-navigated targeting modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Lasers Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.02 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excimer, Femtosecond, Argon, Nd:YAG, Diode Application: Glaucoma Treatment, Retinal Disorders, Cataract Surgery, Refractive Surgery, Corneal Repair End User: Specialty Clinics, Eye Care Centers, Outpatient Facilities, Diagnostic Laboratories, Research Institutes Technology: Photodisruption, Photoablation, Photocoagulation, Optical Coherence, Scanning Laser |
| Companies Covered | Alcon Laboratories, Inc., Carl Zeiss Meditec AG, Lumenis Be Ltd., NIDEK Co., Ltd., Bausch & Lomb Incorporated, Ellex Medical Lasers Limited, IRIDEX Corporation, Topcon Corporation, Ziemer Ophthalmic Systems AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Lasers Market Strategic Shifts & Innovations
Photonic integration is collapsing the boundary between diagnostic imaging and therapeutic delivery, redefining how surgical precision is validated in real time.
Femtosecond laser sources are miniaturizing through ytterbium fiber amplification architectures that replace bulk titanium-sapphire oscillators. Ambulatory surgery centers in Germany and Japan are adopting these compact platforms for office-based refractive procedures. The footprint reduction is miniaturizing capital allocation decisions, enabling satellite clinic deployment without dedicated laser suite construction.
EU Medical Device Regulation (MDR) Article 10 clinical evidence requirements are extending post-market surveillance obligations for laser-integrated systems. Manufacturers must now maintain periodic safety update reports across all member states where devices are marketed. Corneal diagnostic-laser combination products face the steepest compliance burden, with notified body review timelines stretching certification cycles.
Surgeon training models are pivoting toward virtual reality simulation prior to live femtosecond platform certification. Academic medical centers in the United States and South Korea are replacing proctored case accumulation with validated competency metrics. This behavioral shift compresses technology transfer timelines while reducing early-adopter complication rates in teaching hospital settings.
Ophthalmic Lasers Market Segmentation
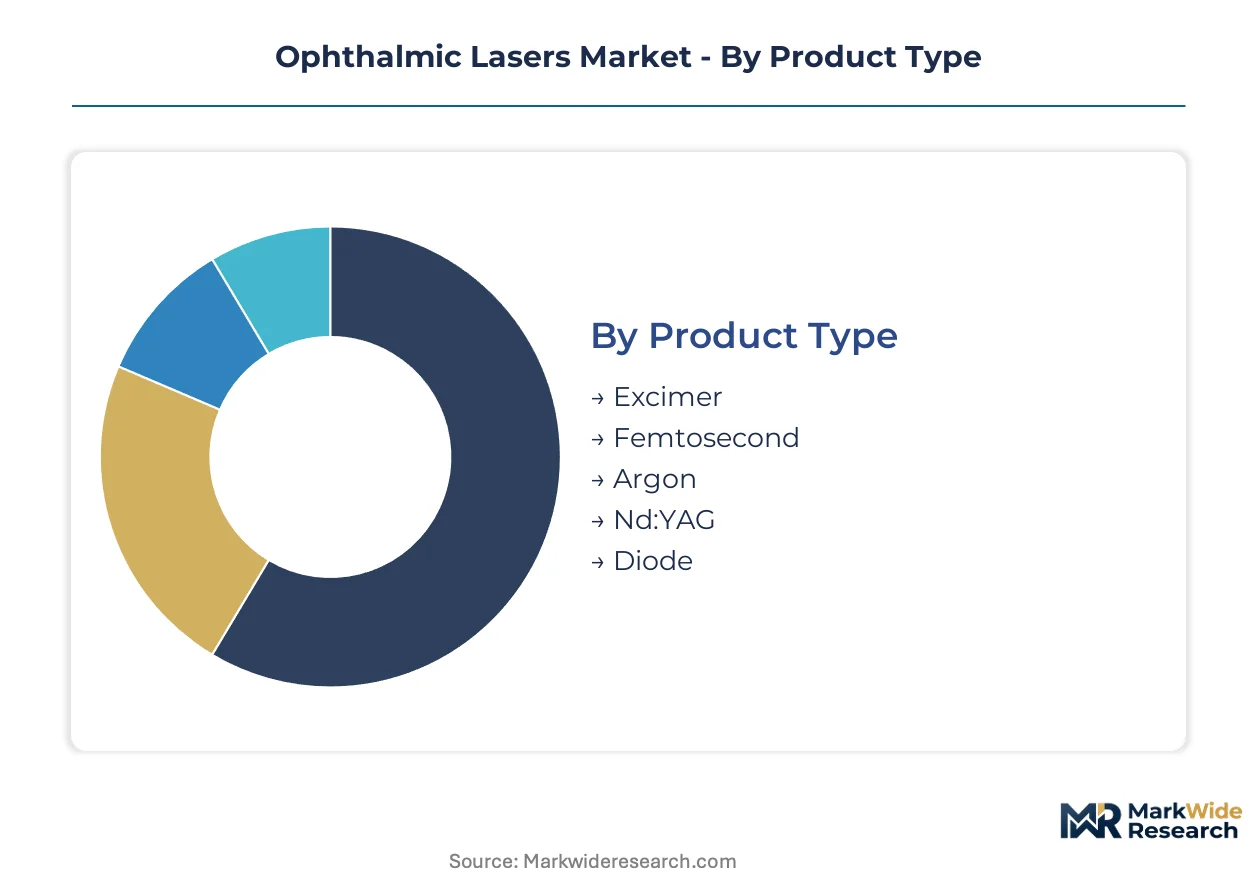
Segmentation in ophthalmic lasers reveals how technology substitution pressures reshape procurement patterns across surgical workflows. Understanding where femtosecond platforms displace legacy systems versus where photocoagulators retain installed base dominance informs capital allocation and R&D prioritization.
Product Type:
Femtosecond platforms face the strongest substitution pressure from compact fiber-laser architectures, while excimer systems confront gas supply volatility that threatens maintenance contract economics.
- Excimer:These 193 nm ultraviolet lasers employ krypton fluoride or argon fluoride gas mixtures for precise corneal photoablation in LASIK and PRK procedures. Demand concentrates in Germany and Japan where regulatory frameworks favor established refractive protocols, though gas procurement cost spikes from semiconductor industry competition compress service margins.
- Femtosecond:Ultrashort pulse systems at 800 nm enable bladeless capsulotomy and intrastromal lenticule extraction with reduced endothelial trauma. Hospital procurement in South Korea and the United States accelerates for cataract applications as optical coherence integration becomes standard, displacing manual phacoemulsification in premium surgical tiers.
- Argon:Continuous-wave blue-green lasers at 488-514 nm retain utility in retinal photocoagulation for diabetic macular edema.
- Nd:YAG:1064 nm Q-switched systems address posterior capsulotomy and peripheral iridotomy with established reimbursement pathways.
- Diode:Compact 810 nm semiconductor lasers serve transscleral cyclophotocoagulation and portable retinal applications.
Excimer platforms anchor the volume base in established refractive markets while femtosecond systems gain share at the steepest rate through cataract workflow integration.
Application:
Cost tier differentiation separates emergency retinal intervention from elective refractive procedures, with capital intensity and reimbursement rates diverging sharply across surgical categories.
- Cataract Surgery:Femtosecond laser-assisted capsulotomy and lens fragmentation reduce ultrasonic energy requirements and endothelial cell loss. Procurement concentrates in ambulatory surgery centers across Germany and the United States where Medicare Advantage carve-outs and private payer riders create differential reimbursement for laser-assisted workflows.
- Refractive Surgery:Corneal reshaping through excimer ablation or femtosecond lenticule extraction serves myopia, hyperopia, and astigmatism correction. Demand clusters in Seoul, Tokyo, and Stuttgart where high surgical density and consumer willingness to pay for spectacle independence sustain premium pricing.
- Glaucoma Treatment:Selective laser trabeculoplasty and cyclophotocoagulation address intraocular pressure management.
- Retinal Disorders:Panretinal photocoagulation and focal laser therapy target diabetic retinopathy and retinal vein occlusion.
- Corneal Repair:Phototherapeutic keratectomy and collagen cross-linking address dystrophies and ectatic disorders.
Cataract applications command the largest installed equipment base while refractive surgery delivers the highest margin per procedure.
End User:
Customer type determines purchasing authority complexity, with hospital procurement committees imposing longer sales cycles but larger contract values than independent specialty practices.
- Eye Care Centers:Dedicated ophthalmology facilities combine diagnostic and surgical capabilities under single ownership, enabling streamlined femtosecond platform adoption. These centers in Nagpur, Indore, and Coimbatore drive tier-2 city expansion in India with cost-calibrated excimer and Nd:YAG configurations.
- Specialty Clinics:Single-specialty practices focus on high-volume refractive or retinal procedures with rapid technology upgrade cycles.
- Outpatient Facilities:Ambulatory surgery centers prioritize capital efficiency and procedure throughput over research capabilities.
- Diagnostic Laboratories:Imaging-focused sites require laser-integrated optical coherence systems for preoperative planning.
- Research Institutes:Academic medical centers in Stuttgart, Rochester, and Tokyo prototype next-generation scanning optics and validate virtual reality training protocols.
Eye care centers represent the dominant volume channel while specialty clinics exhibit the shortest equipment replacement cycles.
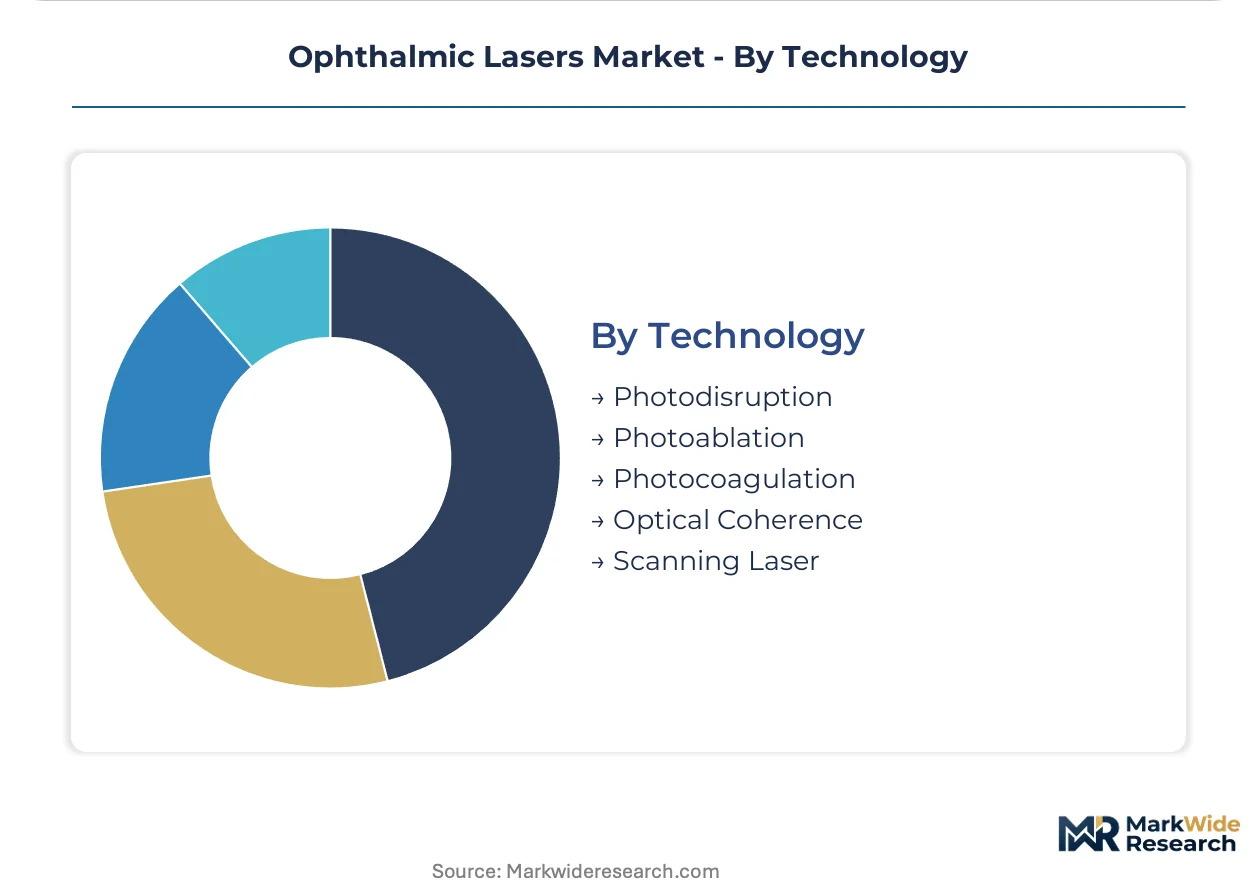
Technology:
Supply concentration in femtosecond oscillator manufacturing creates vulnerability for platform developers dependent on German and US seed laser sources.
- Photocoagulation:Thermal laser-tissue interaction at 400-700 nm wavelengths induces protein denaturation for retinal vessel sealing. This technology retains the largest installed base across diabetic retinopathy management in the United States and Europe, though thermal damage thresholds above 800 nm restrict power scaling protocols.
- Photodisruption:Plasma-mediated optical breakdown creates precise tissue cutting without thermal collateral. Femtosecond platforms in Japan and Germany exploit this mechanism for corneal and lenticular applications, with ytterbium fiber amplification architectures enabling footprint reduction for office-based deployment.
- Photoablation:UV photon absorption breaks molecular bonds for corneal surface reshaping.
- Optical Coherence:Tomographic guidance integrates real-time feedback into laser delivery systems.
- Scanning Laser:Rapid beam deflection enables uniform tissue treatment patterns.
Photocoagulation technology dominates current installed base while optical coherence integration expands most quickly as a mandatory feature in new platform procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium femtosecond platforms command pricing power in Stuttgart and Seoul that cost-calibrated Nd:YAG systems in tier-2 Indian cities cannot replicate. This asymmetry fragments procurement patterns across surgical tiers.
United States
Medicare Advantage carve-outs for laser-assisted cataract procedures drive ambulatory surgery center procurement in Florida and Texas. FDA 510(k) clearance pathways accelerate commercial entry for integrated diagnostic-laser platforms. Rochester, New York anchors femtosecond oscillator engineering talent for next-generation fiber amplification architectures.
Germany
Carl Zeiss Meditec's Stuttgart engineering base sustains dominance in corneal diagnostic-laser integration for premium refractive workflows. EU Medical Device Regulation harmonization streamlines multi-country deployment across France and Italy. Baden-Württemberg's precision manufacturing cluster enables rapid prototyping of scanning optics for femtosecond platforms.
Japan
High surgical density in Tokyo and Osaka sustains demand for spectacle independence through excimer and femtosecond lenticule extraction. PMDA regulatory frameworks favor established refractive protocols with robust clinical evidence requirements. Nagoya's Chubu region concentrates ytterbium fiber laser engineering for compact platform miniaturization.
India
Cataract backlogs in Nagpur, Indore, and Coimbatore drive cost-calibrated excimer and Nd:YAG platform adoption in tier-2 eye care centers. CDSCO medical device regulations impose quality system requirements that extend market entry timelines for novel wavelength platforms. Maharashtra and Karnataka host expanding surgical capacity with procurement focused on capital efficiency over premium feature integration.
South Korea
Seoul's high-volume refractive market accelerates femtosecond platform replacement cycles through consumer willingness to pay for advanced technology. MFDS certification requirements align with EU MDR standards for laser-integrated diagnostic systems. The Seoul Capital Area concentrates virtual reality surgeon training protocol validation for competency-based femtosecond certification.
Ophthalmic Lasers Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the ophthalmic laser market. The vendor base separates into three tiers: integrated diagnostic-laser platform developers, diversified energy system manufacturers, and regional cost-optimized suppliers. German and Japanese engineering clusters anchor premium positioning while Asian OEMs compete on procurement cost. Dominant competitive moves include optical coherence integration partnerships and footprint-reducing fiber laser architecture licensing.
Within the integrated platform tier, Carl Zeiss Meditec AG and Ziemer Ophthalmic Systems AG represent Stuttgart-based precision engineering archetypes. Lumenis Be Ltd. occupies a position exemplifying diversified energy platform strategy across retina and glaucoma workflows. NIDEK Co., Ltd. anchors the Asia-Pacific cost-calibrated supplier archetype through excimer and diagnostic system positioning.
| Leading Market Players |
|---|
| Alcon Laboratories, Inc. |
| Carl Zeiss Meditec AG |
| Lumenis Be Ltd. |
| NIDEK Co., Ltd. |
| Bausch & Lomb Incorporated |
| Ellex Medical Lasers Limited |
| IRIDEX Corporation |
| Topcon Corporation |
| Ziemer Ophthalmic Systems AG |
| Others |
Cost & Logistics Intelligence
Femtosecond oscillator manufacturing scale economies in Stuttgart and Rochester concentrate supply-side leverage among titanium-sapphire and ytterbium fiber seed laser producers, compressing margin floors for Asian OEMs while elevating price premiums for integrated diagnostic-laser platforms in German and US hospital procurement.
Pricing Analysis
The customization-premium spread between configured-to-order femtosecond platforms and standard excimer systems spans three-tier pricing structure across premium, standard, and economy levels, with ISO 13485 certification tier and optical coherence integration depth as primary differentiation drivers. Price erosion runs through economy-tier Nd:YAG maintenance contracts as gas procurement cost spikes from semiconductor industry competition compress service margins. Ambulatory surgery centers in Florida and Texas exhibit highest price sensitivity due to Medicare Advantage reimbursement volatility, while Seoul's refractive clinics show lowest sensitivity given consumer willingness to pay for spectacle independence.
Supply Chain Analysis
Strategic stockpiling of krypton fluoride and argon fluoride excimer gases contrasts with just-in-time procurement preferences for ytterbium fiber amplification components in compact platform miniaturization. Supply concentration centers on Germany, the United States, and Japan for femtosecond oscillator production, with rare earth fiber and precision scanning optics as critical input dependencies. Single-source vulnerability in titanium-sapphire seed laser sourcing creates structural risk for platform developers outside Stuttgart and Rochester engineering clusters. Distribution runs through hospital procurement committees and ambulatory surgery center GPO contracts in the United States, direct sales to eye care centers in India, and academic medical center partnerships in Germany and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ophthalmic laser platform adoption sits in early-cycle expansion as femtosecond-assisted cataract workflows displace manual phacoemulsification in premium surgical tiers, with optical coherence integration becoming standard procurement specification rather than optional upgrade.
For Market Incumbents: Shield installed base revenue through backward integration into ytterbium fiber oscillator production, reducing dependency on German and US seed laser suppliers while locking in service contract renewals. Accelerate ISO 13485 certification timelines for novel wavelength platforms to preempt EU MDR Article 10 compliance delays that threaten multi-country deployment schedules. Channel control through exclusive eye care center partnerships in Nagpur, Indore, and Coimbatore defends against cost-calibrated Asian OEM encroachment in India's tier-2 expansion corridor. For New Entrants and Emerging Players: Post-sales training and virtual reality surgeon certification gaps present white-space opportunities where incumbents under-serve with standardized competency protocols. India's tier-2 eye care centers represent the most penetrable geography given capital efficiency priorities over premium feature integration. A go-to-market angle anchored on compact fiber-laser architectures with reduced footprint enables satellite clinic deployment without dedicated laser suite construction, bypassing incumbent dominance in metropolitan hospital procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors optical coherence-guided laser convergence specialists with real-time tomographic feedback integration capabilities. Long-term viability over the next decade rests on platforms that collapse diagnostic-therapeutic boundaries rather than standalone laser delivery systems. Acquisition target archetypes include femtosecond fiber amplification developers in Nagoya's Chubu region and virtual reality training protocol validators in Seoul. The signal to watch is Medicare Advantage carve-out expansion rates for laser-assisted cataract procedures, which determine capital equipment replacement cycles and technology upgrade trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Coherence Integration Partnership | Real-time tomographic feedback enables sub-10-micron precision in stromal dissection applications. |
| Fiber Laser Architecture Licensing | Ytterbium fiber amplification replaces bulk titanium-sapphire oscillators for compact platform miniaturization. |
| Hospital System Partnership | Medicare Advantage carve-outs in Florida and Texas ambulatory surgery centers drive premium platform placement. |
| CE Marking Pathway Investment | EU MDR Article 10 clinical evidence requirements extend certification cycles for laser-integrated systems. |
| Reimbursement Strategy Development | Selective payer riders for femtosecond-assisted cataract procedures determine capital allocation decisions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with femtosecond platform engineers, hospital purchasing committee members, biomedical equipment specialists, and eye care center procurement managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, CMS Medicare reimbursement schedules, and GPO contract disclosure filings. Bottom-up equipment installation tracking and top-down market sizing triangulated volume and value estimates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type tier, application workflow, end-user facility scale, and regional regulatory cluster complexity. CAGRs were derived from procedural volume trajectories, capital equipment replacement cycles, and technology substitution elasticity coefficients. Forecast inputs incorporated excimer gas procurement cost indices, femtosecond oscillator supply concentration metrics, and reimbursement policy shift probabilities.
Underlying assumptions cover stable EU MDR enforcement timelines and continued Medicare Advantage carve-out expansion, with deviation risk concentrated in excimer gas supply volatility from semiconductor industry demand spikes and single-source femtosecond oscillator supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Eye Melanoma Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Global Therapeutic Lenses Market