
 Ophthalmic Eye Shield Market | 2026-2036
Ophthalmic Eye Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Eye Shield Market Analytics
Ambulatory surgery centers is bifurcating demand away from traditional hospital purchasing, as same-day ophthalmic procedures multiply and inventory models shift toward just-in-time disposable consumption. Gulden Ophthalmics dominates the rigid shield segment through specialized optical-grade polycarbonate manufacturing. Hilco Vision leverages extensive distribution networks across North American eye care practices. Innovative Optics differentiates through laser-protective specialty shields for surgical suites.
Ophthalmic eye shields are medical devices engineered to protect the cornea, sclera, and periorbital tissue from mechanical trauma, photic injury, or post-surgical contamination, typically fabricated from optical-grade polycarbonate with light transmission below 0.1% in the ultraviolet spectrum and impact resistance exceeding 45 joules. Their primary commercial purpose spans post-operative recovery management, intraoperative laser safety compliance, and traumatic injury immobilization across ophthalmology, optometry, and emergency medicine settings. Rigid shields sustain the largest revenue pool due to reusable sterilization protocols favored in hospital central supply departments, while disposable shields represent the fastest-expanding category as infection control protocols tighten and ambulatory centers eliminate reprocessing overhead. Specialty laser-protective shields command premium positioning driven by surgical diode and excimer laser proliferation in refractive and retinal procedures.
FDA 510(k) premarket notification requirements govern device clearance for U.S. manufacturers, while EU MDR and CE marking obligations enforce biocompatibility testing and clinical evidence standards for European market access. ISO 10993 biological evaluation protocols and ISO 13485 quality management systems shape material selection and manufacturing process validation across all major supply jurisdictions. Stakeholders must monitor evolving laser safety standards from IEC and ANSI alongside reimbursement policy shifts for outpatient ophthalmic procedures that directly influence end-user procurement budgets and product specification requirements.
Market Dynamics
Ambulatory surgery centers are restructuring procurement patterns toward single-use disposable shields, eliminating reprocessing overhead while tightening infection control protocols across outpatient ophthalmic networks.
Growth Catalysts
- EU MDR conformity assessments:Biocompatibility testing mandates under the 2017/745 regulation are accelerating material upgrades, forcing manufacturers toward medical-grade polymers that command premium positioning in European markets.
- Laser surgery proliferation:Excimer and femtosecond laser adoption in refractive procedures is expanding addressable demand for specialty protective shields with specific optical density ratings.
- Japan's aging demographic:Cataract surgical volume expansion among patients over 65 is sustaining steady consumption of post-operative recovery shields across Tokyo and Osaka metropolitan clinical networks.
Market Restraints
- Optical-grade polycarbonate supply concentration:Raw material sourcing depends heavily on specialized polymer producers in Germany and the United States, exposing converters to input cost volatility and allocation constraints.
- FDA 510(k) clearance timelines:Premarket notification review periods for novel shield designs create 12-18 month commercialization delays that compress first-mover advantages.
- Reusable shield substitution:Hospital central supply departments with established sterilization infrastructure continue favoring rigid polycarbonate shields over disposable alternatives in budget-constrained environments.
Strategic Opportunities
- Pediatric ophthalmology expansion:Underserved demand for anatomically scaled shields in pediatric cataract and strabismus procedures offers white space beyond adult-centric product portfolios.
- India's surgical infrastructure buildout:Government-funded vision centers under the National Programme for Control of Blindness are creating procurement channels for cost-optimized disposable shields.
- Telemedicine-integrated post-operative monitoring:Remote patient compliance tracking is enabling subscription-based shield replenishment models linked to recovery protocol adherence.
Industry Challenges
- ISO 13485 quality management implementation:Small and mid-sized shield manufacturers face capex-intensive cleanroom and documentation infrastructure requirements to maintain certification currency.
- Laser safety standard harmonization:Divergent IEC 60825 and ANSI Z136.1 testing protocols force dual certification investments for products targeting both European and North American surgical laser suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Eye Shield Market |
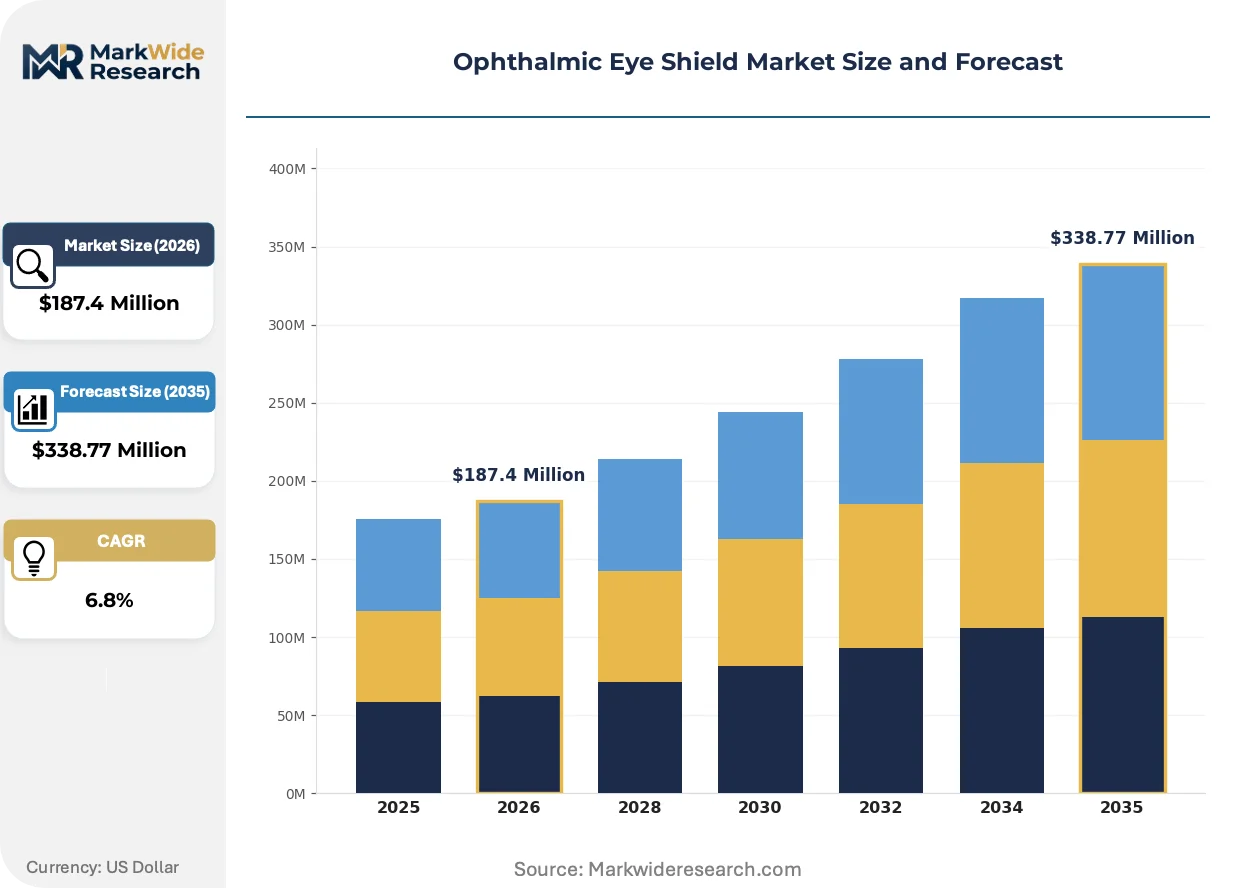
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Shields, Soft Shields, Specialty Shields, Disposable Shields Material: Polycarbonate, Acrylic, PVC, Foam Application: Post-operative Care, Injury Protection, Medical Procedures, Sports End User: Hospitals, Clinics, Ambulatory Surgery Centers, Homecare |
| Companies Covered | Innovative Optics, Ambler Surgical, Gulden Ophthalmics, Oculo-Plastik, Inc., Hilco Vision, Surtex Instruments, Univet, NoIR, PROTECT-Laserschutz GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Eye Shield Market Evolving Landscape
Material science advances and regulatory harmonization pressures are compressing product development cycles while elevating performance thresholds for optical protection and biocompatibility assurance.
Antimicrobial-impregnated polycarbonate formulations are displacing standard optical-grade resins in premium shield segments. Ambulatory surgery centers in the United States are adopting these surfaces at accelerated rates to mitigate surgical site infection liability. The displacement is compressing margins for commodity-grade shield producers unable to source certified antimicrobial additives.
EU MDR technical documentation requirements are mandating expanded clinical evidence for legacy shield designs previously grandfathered under the Medical Devices Directive. Manufacturers with established European notified body relationships are accelerating dossier preparation. Rigid reusable shields with decades of clinical history face the steepest compliance cost escalation.
Same-day surgical discharge protocols are collapsing traditional 7-14 day shield supply models toward 24-48 hour disposable kits bundled with post-operative medication. United States Medicare reimbursement shifts toward episodic payment are reinforcing this compression. Distributors with direct-to-practice logistics capabilities are capturing margin previously held by hospital purchasing consortia.
Ophthalmic Eye Shield Market Segmentation
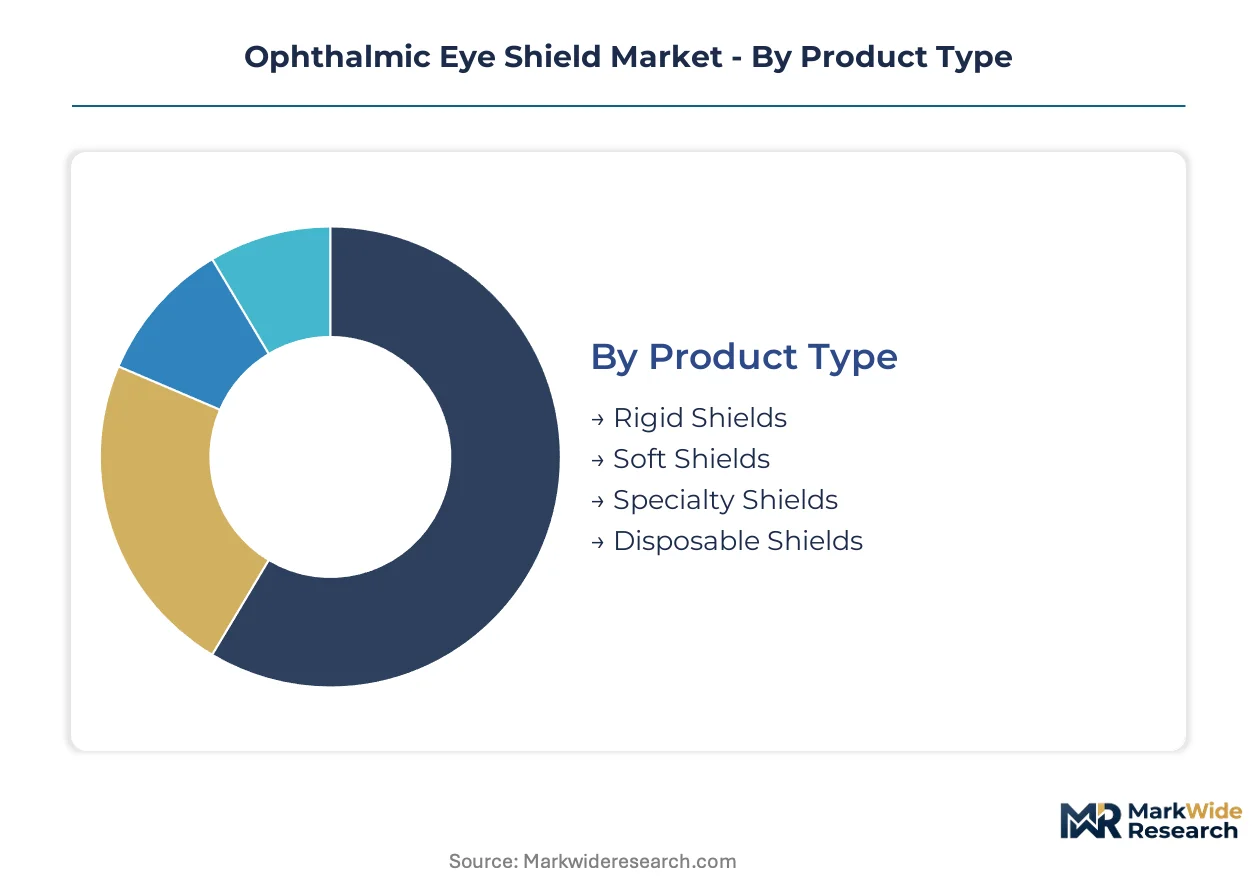
Segmentation in the ophthalmic eye shield market reveals distinct margin architectures across product architectures, material grades, and procurement channels. Each dimension carries divergent regulatory burdens and sterilization economics that reshape vendor positioning.
Product Type:
Margin pools concentrate in specialty shields commanding optical density premiums, while volume throughput favors disposables in ambulatory networks.
- Rigid Shields:Optical-grade polycarbonate shells withstand autoclave cycles exceeding 100 iterations. Hospital central supply departments in Germany and the United States favor these for cataract recovery protocols due to established sterilization infrastructure.
- Specialty Shields:Laser-protective variants incorporate specific optical density ratings for excimer and femtosecond surgical suites. Demand clusters in Tokyo metropolitan clinics where refractive procedure volume sustains premium positioning.
- Soft Shields:Foam-composite constructions for pediatric and trauma applications where anatomical conformity exceeds rigidity requirements.
- Disposable Shields:Single-use polycarbonate or PVC formats eliminating reprocessing overhead in outpatient networks.
The dominant share belongs to rigid shields, while disposable shields are closing the gap fastest.
Material:
Cost tiers stratify sharply around optical transmission specifications and biocompatibility certification depth.
- Polycarbonate:Medical-grade optical formulations with UV transmission below 0.1% and impact resistance exceeding 45 joules. FDA 510(k) clearance pathways favor established polycarbonate dossiers, entrenching incumbent suppliers in United States hospital networks.
- Acrylic:Lower-density alternative for non-laser applications where impact requirements moderate. Ambulatory surgery centers in Japan specify acrylic for cost-optimized post-operative kits.
- PVC:Disposable shield substrate offering thermoforming flexibility at commodity price points.
- Foam:Soft shield cores and peripheral padding for pressure-sensitive applications.
Polycarbonate commands the value pool, though acrylic is gaining fastest in cost-sensitive procurement channels.
Application:
Volume throughput centers on post-surgical recovery, while injury protection carries episodic demand spikes.
- Post-operative Care:Corneal protection following cataract, refractive, and retinal procedures. Aging surgical demographics in Japan and Germany sustain steady consumption through metropolitan clinical networks.
- Medical Procedures:Intraoperative laser safety compliance in excimer and femtosecond suites. EU MDR biocompatibility mandates are accelerating material upgrades for European surgical shield specifications.
- Injury Protection:Trauma immobilization in emergency medicine settings with irregular demand patterns tied to seasonal activity.
- Sports:Protective eyewear for high-impact athletic applications outside core medical markets.
Post-operative care holds the volume base, with medical procedure applications expanding most quickly on laser surgery proliferation.
End User:
Procurement authority is fragmenting as ambulatory networks bypass traditional hospital purchasing consortia.
- Hospitals:Central supply departments with sterilization infrastructure favoring reusable rigid shields. Budget constraints in United States health systems reinforce this preference despite infection control pressures.
- Ambulatory Surgery Centers:Same-day discharge protocols driving just-in-time disposable consumption. Medicare reimbursement shifts toward episodic payment in the United States accelerate this transition.
- Clinics:Independent ophthalmology and optometry practices with mixed procurement patterns.
- Homecare:Direct-to-patient distribution for extended post-operative recovery protocols.
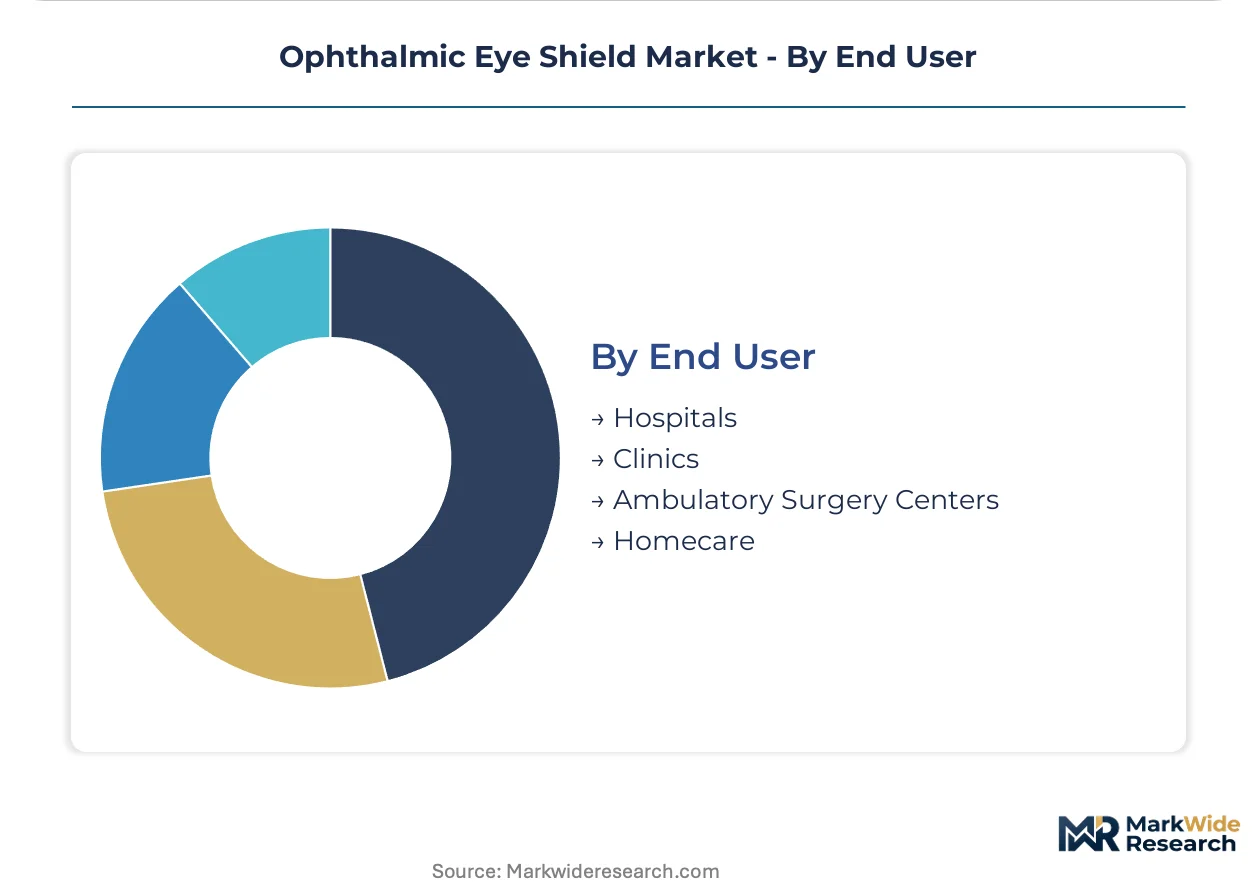
Hospitals retain the largest procurement volume, yet ambulatory surgery centers are climbing the fastest on network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for optical-grade polycarbonate resin, while the Port of Long Beach handles Pacific Rim medical device consolidation. These maritime gateways sustain ophthalmic shield supply chains across three continents.
United States
Medicare episodic reimbursement shifts accelerate ambulatory surgery center procurement of disposable shields. FDA 510(k) clearance timelines create 12-18 month commercialization delays for novel designs. The Dallas-Fort Worth metroplex concentrates distribution hubs serving Southwest ophthalmology networks.
Germany
EU MDR conformity assessments under 2017/745 mandate biocompatibility upgrades for polycarbonate formulations. REACH chemical registration requirements constrain additive selection for antimicrobial-impregnated surfaces. The Rhine-Main region around Frankfurt hosts notified body operations shaping European market access.
Japan
Cataract surgical volume among patients over 65 sustains steady post-operative shield consumption. PMDA pharmaceutical and medical device agency oversight governs material safety certifications. Tokyo metropolitan clinical networks anchor refractive procedure demand for specialty laser-protective variants.
India
The National Programme for Control of Blindness funds vision center infrastructure creating procurement channels for cost-optimized disposables. CDSCO medical device regulations tighten import documentation for foreign-manufactured shields. Maharashtra state government tenders dominate public sector ophthalmic device acquisition.
United Kingdom
NHS procurement frameworks favor reusable rigid shields in hospital central supply departments despite infection control pressures. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards. London and Southeast England concentrate private ophthalmology clinic networks driving premium disposable adoption.
Ophthalmic Eye Shield Market Competitive Landscape
Listed leaders compete with private specialists across material certification and distribution reach. The vendor base splits between optical-grade polycarbonate converters and disposable shield assemblers. Three archetypes dominate: rigid reusable specialists, disposable mass producers, and laser-protective niche players. Competitive moves center on EU MDR dossier preparation and ambulatory surgery center direct contracting.
Among North American fabricators, Gulden Ophthalmics and Hilco Vision exemplify the rigid-disposable split, while Innovative Optics occupies the specialty laser-protection tier. PROTECT-Laserschutz GmbH anchors European laser safety positioning. These four represent distinct strategic postures without implying specific market share or operational scale.
| Leading Market Players |
|---|
| Innovative Optics |
| Ambler Surgical |
| Gulden Ophthalmics |
| Oculo-Plastik, Inc. |
| Hilco Vision |
| Surtex Instruments |
| Univet |
| NoIR |
| PROTECT-Laserschutz GmbH |
| Others |
Value Network & Pricing Analysis
Antimicrobial-impregnated polycarbonate displacement of standard optical-grade resins is simultaneously concentrating supply geography around German and United States polymer producers and compressing margins for converters unable to source certified additive formulations, creating a bifurcated cost structure between premium-certified and commodity-grade shield tiers.
Pricing Analysis
Volume-discount tiering structures separate hospital central supply departments purchasing reusable rigid shields in bulk from ambulatory surgery centers acquiring single-use disposable kits on just-in-time contracts. Three-tier pricing structure across premium, standard, and economy levels reflects optical density certification depth and antimicrobial surface treatment. Cost compression in the economy tier is intensifying because acrylic substitution in Japanese post-operative kits reduces polycarbonate offtake. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare episodic reimbursement constraints, while Tokyo metropolitan refractive clinics show lowest sensitivity for laser-protective specialty variants.
Supply Chain Analysis
Inventory lead times for optical-grade polycarbonate resin stretch 8-12 weeks from German and United States specialized polymer producers, exposing shield converters to allocation constraints during demand surges. Raw material sourcing draws from Bayer Covestro and SABIC medical-grade formulations, with PVC and acrylic alternatives feeding cost-optimized disposable segments. Single-source vulnerability concentrates in optical-grade polycarbonate supply, where REACH registration requirements limit qualified European additive suppliers. Distribution runs through Port of Hamburg for European clinical networks and Port of Long Beach for Pacific Rim consolidation, with Dallas-Fort Worth distribution hubs serving Southwest United States ophthalmology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR biocompatibility mandates and antimicrobial surface proliferation constitute a dual regulatory-technological inflection compressing development cycles while elevating certification barriers, positioning the market for high-growth disruption among prepared incumbents and specialized entrants.
For Market Incumbents: Fortify EU MDR dossier preparation through notified body relationships in the Rhine-Main region, accelerating technical documentation for legacy rigid shield designs facing grandfathered status expiration. Deepen backward integration into optical-grade polycarbonate compounding to secure antimicrobial additive supply chains against REACH-constrained sourcing. Channel control through direct ambulatory surgery center contracting mitigates distributor margin capture under Medicare episodic payment shifts.
For New Entrants and Emerging Players: Anchor in India's National Programme for Control of Blindness vision center infrastructure, where CDSCO import documentation barriers favor domestic assembly partnerships over foreign-manufactured shield imports. Pediatric ophthalmology presents the most penetrable white space, with anatomically scaled shield demand underserved by adult-centric portfolios. A go-to-market angle bundling disposable shields with telemedicine-integrated compliance tracking captures subscription-based replenishment revenue.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier shield assemblers with established ISO 13485 certification and ambulatory surgery center distribution relationships, positioned for acquisition by optical-grade polycarbonate converters seeking downstream integration. Long-term viability over a 5-10 year window hinges on laser-protective specialty positioning as excimer and femtosecond surgical volume expands. The signal to watch is FDA 510(k) clearance timeline compression for novel antimicrobial-impregnated designs, indicating regulatory pathway efficiency for prepared filers.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Acceleration | Notified body relationships in Frankfurt determine European market access timelines for legacy shield designs. |
| Antimicrobial Surface Certification Investment | FDA 510(k) dossiers incorporating ISO 10993 biocompatibility data command premium positioning in United States hospital networks. |
| Ambulatory Surgery Center Direct Contracting | Medicare episodic reimbursement shifts procurement authority away from hospital purchasing consortia toward outpatient networks. |
| Pediatric Shield Portfolio Development | Anatomically scaled designs for strabismus and cataract procedures address underserved demand beyond adult-centric offerings. |
| Indian Domestic Assembly Partnership | CDSCO regulatory alignment under National Programme for Control of Blindness tenders creates cost-optimized procurement channels. |
Research Methodology
Initial hypotheses were tested against primary input from ophthalmic surgeons, hospital purchasing committee members, ambulatory surgery center administrators, and biomedical engineers, and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and GPO contract repositories. Bottom-up demand modeling across product type, material grade, application, and end-user segments was triangulated with top-down market sizing from trade flow analysis through Port of Hamburg and Port of Long Beach.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within rigid, specialty, soft, and disposable shield categories. Segmentation dimensions modeled include product architecture, optical density certification tier, sterilization protocol compatibility, and regional regulatory cluster. CAGRs were derived from surgical volume elasticity analysis and material substitution rate projections, with forecast inputs incorporating PMDA cataract procedure data from Tokyo metropolitan networks and CDSCO import registration trends for Indian vision center infrastructure.
Material uncertainties — polycarbonate supply allocation constraints, EU MDR notified body capacity bottlenecks, and Medicare reimbursement rule finalization — sit outside the modeled envelope and could compress or extend realized growth trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Global Retinal Detachment Treatment Market