
 North America Computed Tomography (CT) Market | 2026-2036
North America Computed Tomography (CT) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Computed Tomography (CT) Market Analytics
The North America CT equipment landscape is pivoting on a widening gap between premium multi-slice systems and commodity portable units. GE HealthCare leverages its installed base of high-end scanners to sustain recurring service revenue across integrated delivery networks. Siemens Healthineers anchors its position through R&D intensity in photon-counting detector technology. Canon Medical Systems differentiates by competing aggressively on total cost-of-ownership contracts for mid-tier hospitals.
Computed Tomography (CT) is a medical imaging modality that uses rotating X-ray tubes and detector arrays to reconstruct cross-sectional anatomical images, with modern multi-slice systems achieving sub-millimeter spatial resolution and sub-second temporal resolution for cardiac gating. Its primary commercial purpose is non-invasive diagnostic visualization for disease detection, treatment planning, and interventional guidance across acute and ambulatory settings. Spiral CT dominates current installed capacity due to its speed and workflow efficiency, while dual-energy CT represents the fastest-growing technology segment as radiology departments seek material decomposition capabilities for tissue characterization. Portable CT scanners command concentrated demand from neuro-intensive care units and intraoperative suites where patient transport risks outweigh image quality trade-offs.
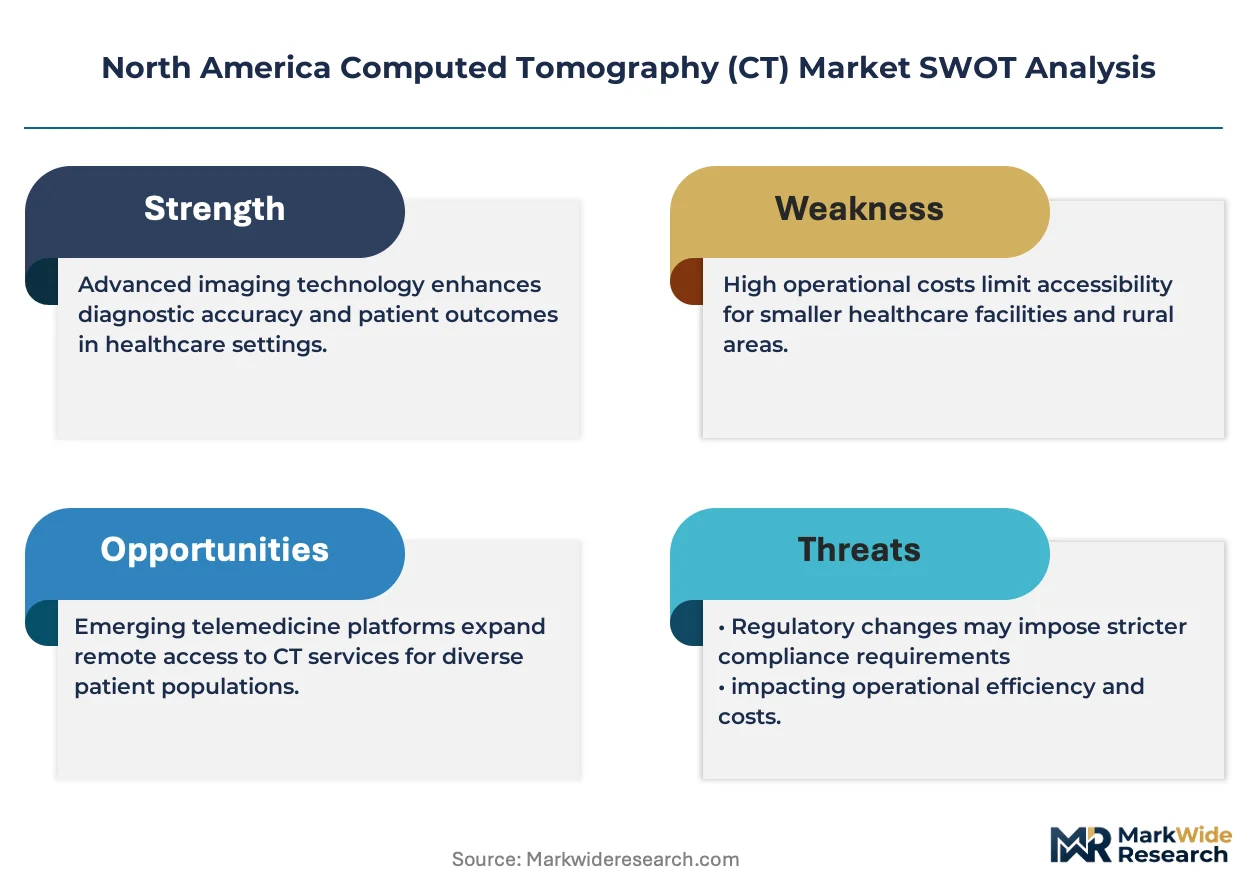
FDA 510(k) premarket notification requirements govern CT system clearance, while the EPA's radiation protection standards constrain X-ray tube output specifications and shielding design. The NRC and Agreement States administer radioactive material licensing for CT-based theranostic applications, creating compliance cost layers that favor vendors with established regulatory affairs infrastructure. Stakeholders must monitor how CMS reimbursement adjustments for hospital outpatient departments versus freestanding imaging centers reshape site-of-service economics for CT utilization.
Market Dynamics
Health system consolidation across the United States is compressing procurement cycles and favoring vendors capable of delivering enterprise-wide service contracts spanning multi-state networks. Integrated delivery networks now negotiate centralized CT fleet standardization, displacing hospital-by-hospital purchasing autonomy.
Growth Catalysts
- Outpatient clinic expansion:Same-day diagnostic workflows drive CT installation in ambulatory surgical centers across Texas and Florida, bypassing hospital-based imaging queues.
- FDA 510(k) pathway acceleration:Streamlined clearance for iterative reconstruction algorithms shortens upgrade cycles from seven years toward four.
- Photocounting detector maturation:Research hospitals in Massachusetts and California deploy next-generation spectral imaging for material decomposition protocols.
Market Restraints
- Helium supply concentration:Superconducting magnet cooling depends on Qatar and Russia extraction, exposing CT manufacturers to price volatility and export restriction risk.
- Radiologist workforce scarcity:The American College of Radiology documents insufficient fellowship-trained specialists to interpret rising scan volumes, creating interpretation bottlenecks.
- Shielding compliance escalation:State-level radiation protection offices enforce stricter lead-equivalent requirements for retrofit installations, adding construction cost layers.
Strategic Opportunities
- Neuro-intensive care penetration:Portable CT deployment in Canadian and US stroke centers eliminates patient transport risks during acute intervention windows.
- CMS site-of-service parity:Reimbursement rate convergence between hospital outpatient departments and freestanding imaging centers incentivizes ambulatory investment.
- AI reconstruction integration:Deep learning algorithms reduce radiation dose while maintaining diagnostic confidence, opening pediatric and repeat-scan applications previously constrained by cumulative exposure limits.
Industry Challenges
- Service engineer specialization:Photon-counting detector maintenance requires training pipelines that OEMs and third-party servicers have not yet scaled.
- Legacy PACS interoperability:New acquisition protocols strain DICOM routing infrastructure in mid-tier hospitals running decade-old archive systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Computed Tomography (CT) Market |
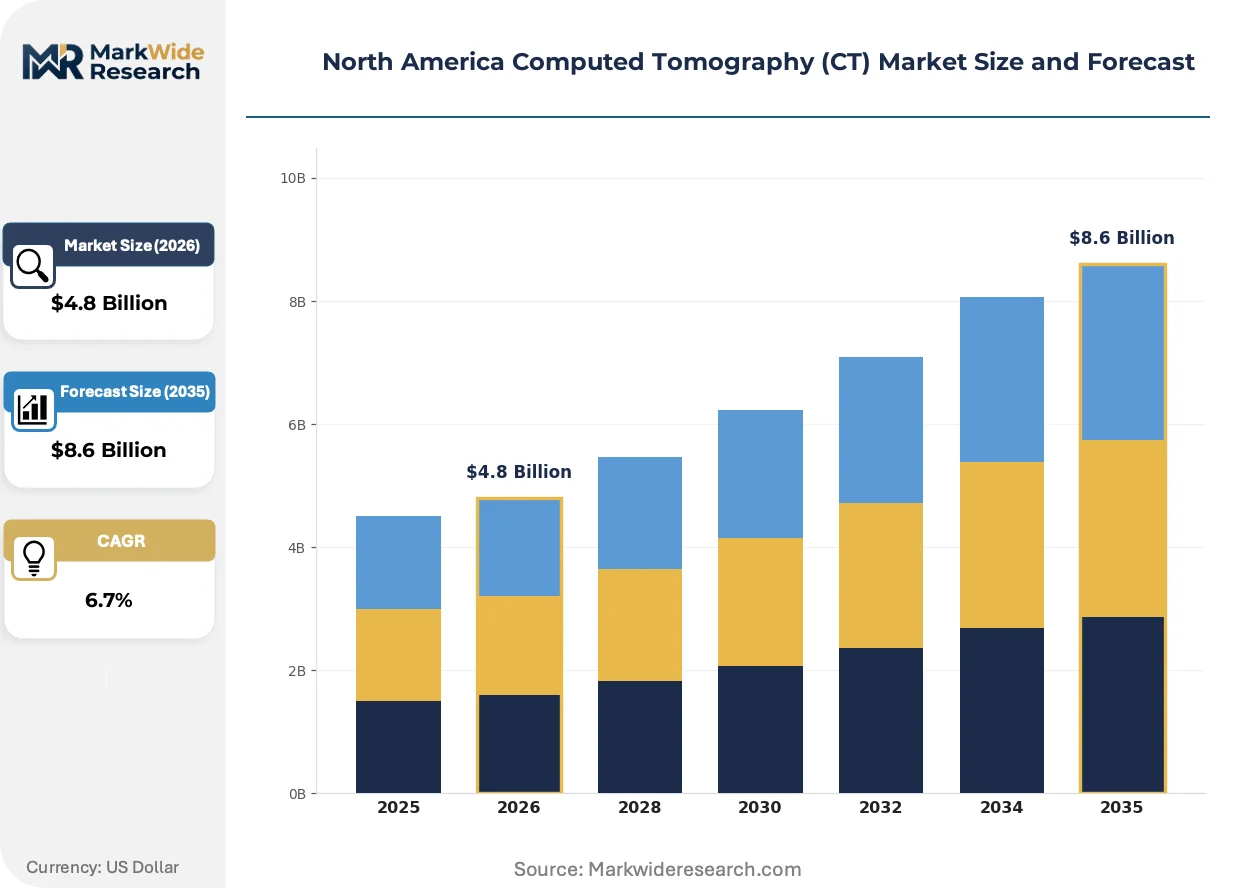
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary CT Scanners, Portable CT Scanners, Cone Beam CT, Multi-slice CT End User: Hospitals, Diagnostic Imaging Centers, Research Institutes, Outpatient Clinics Technology: Spiral CT, High-Resolution CT, Dual-Energy CT, Iterative Reconstruction CT Application: Oncology, Neurology, Cardiovascular, Orthopedics |
| Companies Covered | GE HealthCare, Siemens Healthineers, Canon Medical Systems, Koninklijke Philips, FUJIFILM Holdings, NeuroLogica, Carestream Health, Hitachi Healthcare Systems, United Imaging Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Computed Tomography (CT) Market Evolving Landscape
Computed tomography is undergoing hardware-software decoupling, with reconstruction algorithms and detector materials evolving faster than gantry mechanical platforms. Vendors now compete on computational imaging stacks rather than slice-count specifications alone.
Photon-counting detector technology is converging with cadmium zinc telluride semiconductor layers to enable energy-resolved imaging at the photon level. Academic medical centers in the United States and Canada pilot these systems for coronary plaque characterization and renal stone composition analysis. The technology is converging with spectral imaging workflows to compress the timeline for material-specific diagnosis from research protocol to clinical standard.
The FDA's 510(k) premarket notification framework for software-as-a-medical-device is forcing reconstruction algorithm developers to demonstrate substantial equivalence through clinical validation studies. This regulatory expansion extends to iterative reconstruction and deep learning denoising modules sold as aftermarket upgrades. CT manufacturers with established quality management systems capture compliance cost advantages over pure-play AI vendors lacking predicate device portfolios.
Hospital procurement departments unbundle service contracts from equipment financing, negotiating multi-vendor maintenance agreements and third-party parts sourcing. This purchasing behavior shift pressures OEM service margins while creating openings for independent service organizations specializing in detector replacement and tube refurbishment. The trend is most visible in the United States Midwest, where Catholic health systems and municipal hospital districts lead contract restructuring efforts.
North America Computed Tomography (CT) Market Segmentation
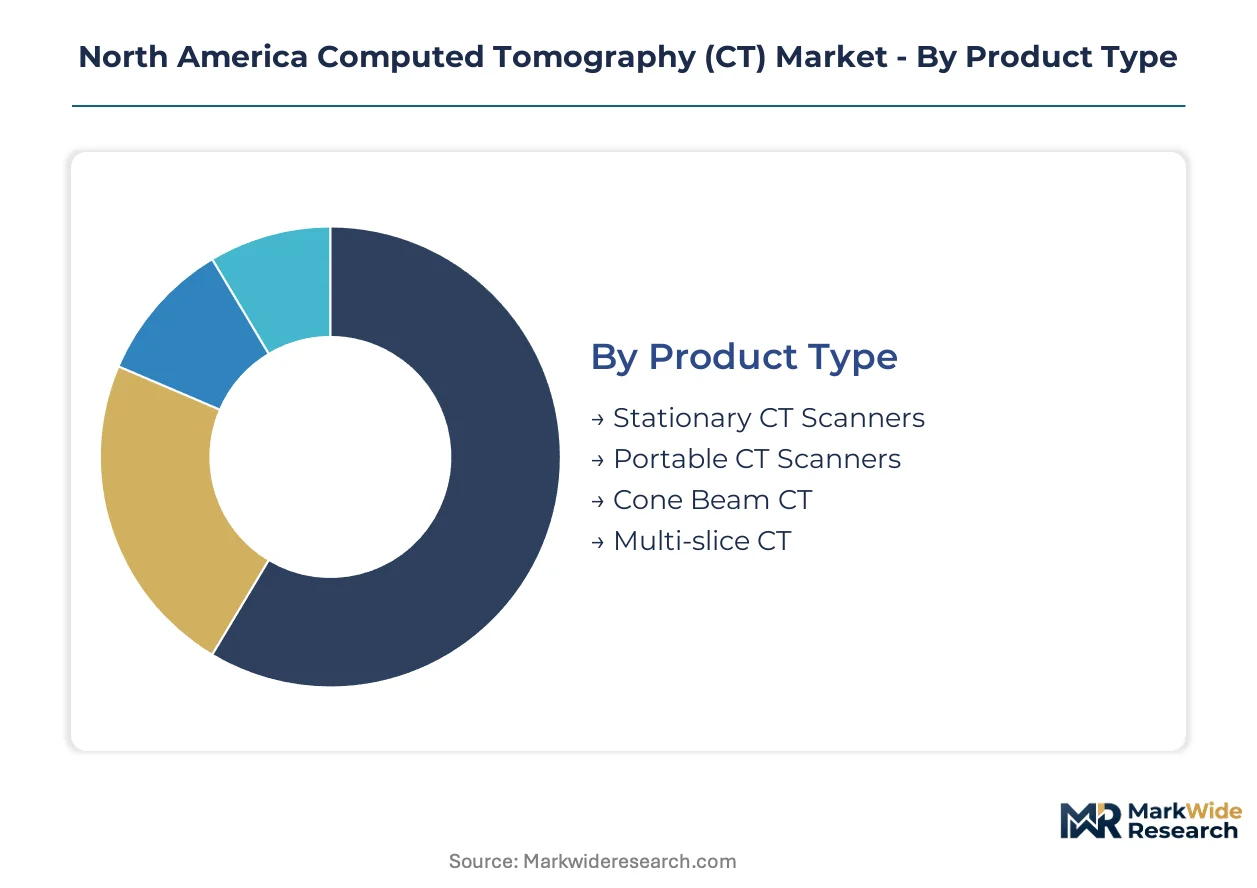
CT procurement in North America fragments across clinical settings with divergent throughput requirements, reimbursement structures, and regulatory exposure. Understanding these segment boundaries clarifies why vendors pursue divergent go-to-market strategies rather than uniform product positioning.
Product Type:
FDA 510(k) clearance pathways vary substantially by scanner mobility and detector architecture, with stationary systems facing longer validation timelines due to higher radiation output classifications. Portable and point-of-care configurations qualify under abbreviated review tracks when manufacturers demonstrate equivalence to predicate devices with comparable beam filtration.
- Stationary CT Scanners:Fixed-installation systems with gantry rotation speeds exceeding 0.35 seconds per revolution and detector arrays spanning 64 to 320 slices. Demand concentrates in Level I trauma centers across Texas and California where 24/7 throughput requirements justify capital intensity. Shielding compliance costs and lead-lined room construction create switching friction that locks in vendor relationships across decade-long depreciation cycles.
- Portable CT Scanners:Self-contained units on motorized bases with battery-backed power systems enabling deployment at bedside. Neuro-intensive care units in Massachusetts and Pennsylvania deploy these systems to eliminate patient transport risks during acute stroke intervention windows. The segment climbs fastest as ambulatory surgical centers seek same-day diagnostic capabilities without construction-intensive fixed installations.
- Cone Beam CT:Flat-panel detector systems optimized for maxillofacial and dental applications with reduced radiation dose profiles compared to conventional fan-beam geometry. Oral surgery groups in Florida and Arizona drive replacement demand.
- Multi-slice CT:Detector configurations enabling simultaneous acquisition of 16 to 640 slices per rotation. Integrated delivery networks standardize fleet procurement around 128-slice platforms for cardiac and vascular protocols.
Leading the category by volume: Multi-slice CT. Expanding most quickly: Portable CT Scanners.
End User:
Reimbursement rate differentials between hospital outpatient departments and freestanding imaging centers reshape capital allocation priorities across customer segments. CMS site-of-service adjustments create margin compression for hospital-based radiology while expanding returns for ambulatory investors.
- Hospitals:Acute care facilities with emergency departments, inpatient capacity, and surgical suites requiring 24/7 imaging availability. Health system consolidation across the Midwest drives centralized procurement of enterprise-wide service contracts spanning multi-state networks. Capital budgeting cycles extend 7 to 10 years with replacement triggered by obsolescence rather than mechanical failure.
- Diagnostic Imaging Centers:Freestanding facilities specializing in outpatient radiology with volume-based operational models. Texas and Florida permit physician ownership under Stark Law exceptions, concentrating investment in high-throughput metropolitan corridors. The segment gains share fastest as reimbursement parity with hospital outpatient departments improves unit economics.
- Research Institutes:Academic medical centers and university hospitals pursuing protocol development and clinical trial imaging. NIH-funded institutions in Maryland and California pilot photon-counting detector systems ahead of commercial adoption.
- Outpatient Clinics:Ambulatory surgical centers and specialty clinics integrating same-day diagnostic workflows. Urgent care chains in Arizona deploy compact systems to bypass hospital imaging queues.
Volume leader: Hospitals. Steepest expansion trajectory: Diagnostic Imaging Centers.
Technology:
Detector material evolution and reconstruction algorithm advancement now outpace mechanical gantry innovation, compressing upgrade cycles for software-dependent modalities. Vendors compete on computational imaging stacks rather than slice-count specifications alone.
- Dual-Energy CT:Spectral imaging systems acquiring data at two distinct X-ray energy levels to enable material decomposition and tissue characterization. Research hospitals in California and Massachusetts deploy these platforms for coronary plaque analysis and renal stone composition differentiation. The technology captures share fastest as radiology departments seek quantitative biomarker extraction beyond morphological assessment.
- Iterative Reconstruction CT:Algorithmic noise reduction techniques enabling diagnostic image quality at 30 to 60 percent lower radiation dose than filtered back projection. Pediatric hospitals and oncology centers with repeat-scan protocols drive adoption to manage cumulative exposure limits. FDA 510(k) pathway streamlining accelerates vendor competition in dose-optimization software.
- Spiral CT:Continuous patient translation during gantry rotation enabling sub-minute whole-body acquisition. Current installed base standard across community hospitals and imaging centers.
- High-Resolution CT:Sub-millimeter slice thickness protocols optimized for interstitial lung disease and small-airway assessment. Pulmonology departments in academic centers drive protocol standardization.
Dominant by installed base: Spiral CT. Fastest-growing segment: Dual-Energy CT.
Application:
Clinical indication intensity varies with population morbidity patterns, screening program adoption, and interventional radiology expansion across North American health systems. Procedure volume growth concentrates where reimbursement supports preventive imaging and where minimally invasive therapies require procedural guidance.
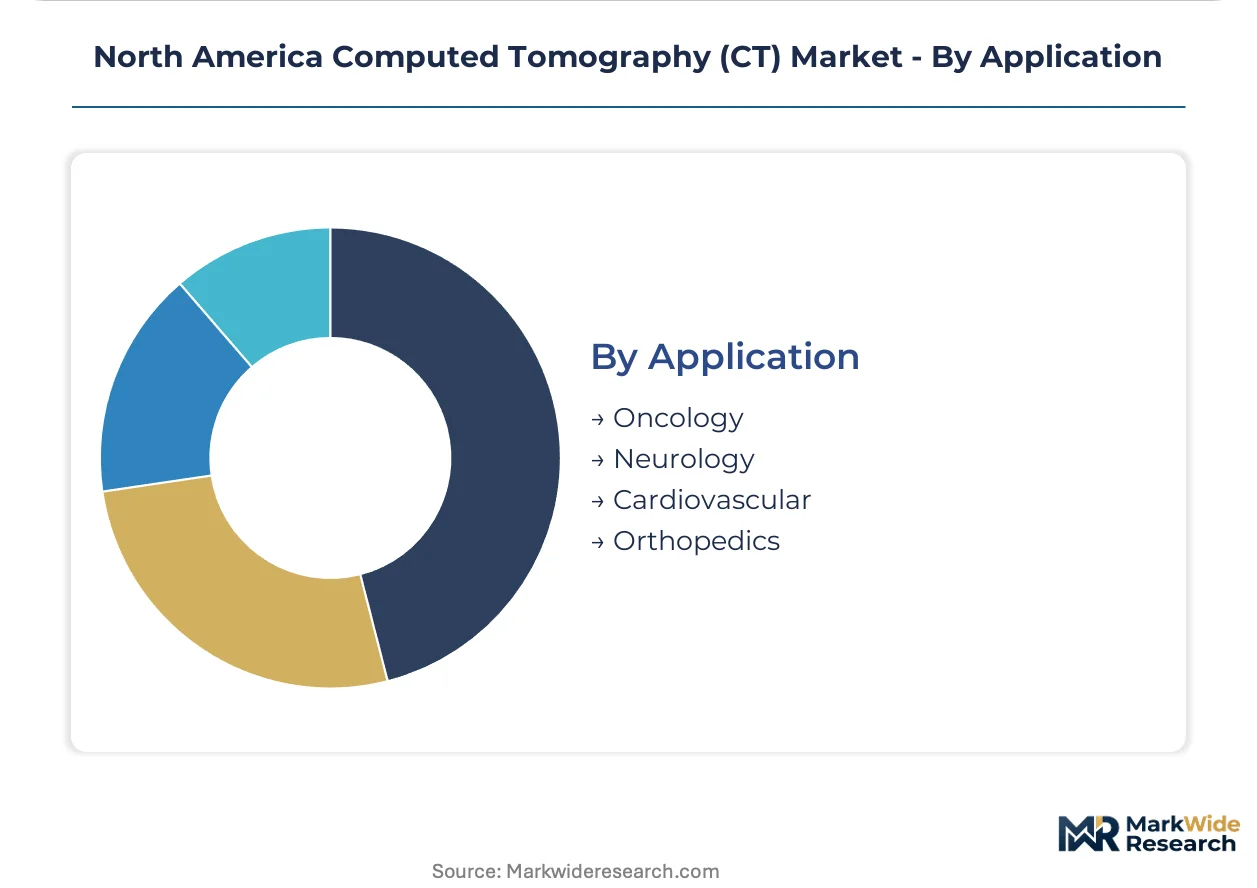
- Oncology:Tumor detection, staging, and treatment response monitoring across solid malignancies. Comprehensive cancer centers in Texas and New York deploy dual-energy systems for therapy planning and immunotherapy monitoring. The application expands most quickly as liquid biopsy integration and radiomics standardization multiply scan frequency per patient journey.
- Cardiovascular:Coronary artery calcium scoring, CT angiography, and structural heart intervention planning. Hospital systems in Florida and California build cardiac CT capacity to reduce invasive catheterization volume. CMS reimbursement stability for coronary CTA drives capital commitment.
- Neurology:Stroke imaging, trauma assessment, and neurosurgical planning. Canadian and US stroke centers deploy portable systems to compress door-to-needle intervals.
- Orthopedics:Fracture characterization, arthroplasty planning, and postoperative complication assessment. Ambulatory surgery centers in Arizona integrate cone-beam systems for intraoperative alignment verification.
Highest procedure volume: Oncology. Gaining share fastest: Cardiovascular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors North American CT innovation through academic medical centers piloting photon-counting detector systems ahead of commercial deployment.
United States
Health system consolidation across the Midwest compresses procurement cycles as integrated delivery networks negotiate enterprise-wide service contracts spanning multi-state footprints. FDA 510(k) pathway streamlining for iterative reconstruction algorithms accelerates equipment upgrade cycles from seven years toward four. Texas and Florida concentrate outpatient clinic expansion where ambulatory surgical centers deploy same-day diagnostic workflows to bypass hospital imaging queues.
Canada
Stroke centers in Ontario and Quebec deploy portable CT systems to eliminate patient transport risks during acute intervention windows. Health Canada regulates medical device licensing through the Medical Devices Bureau while provincial health authorities manage capital allocation for hospital imaging infrastructure. Toronto's University Health Network pilots dual-energy protocols for coronary plaque characterization ahead of community hospital adoption.
Mexico
Private hospital chains in Mexico City and Monterrey upgrade multi-slice capacity to capture medical tourism flows from the United States seeking lower-cost diagnostic imaging. COFEPRIS medical device registration requirements create compliance timelines that favor vendors with established Latin American regulatory affairs infrastructure. Guadalajara's medical device manufacturing corridor supplies detector components to North American OEM assembly facilities.
North America Computed Tomography (CT) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detector technology sophistication and service contract bundling. The North America CT equipment landscape consolidates around imaging conglomerates with installed base leverage and standalone specialists in portable and point-of-care configurations. Three archetypes dominate: full-stack OEMs with detector manufacturing captive, software-centric reconstruction algorithm developers, and independent service organizations unbundling maintenance from equipment financing. Competitive positioning hardens through multi-year fleet standardization agreements and third-party parts sourcing authorization.
Within the full-stack OEM tier, GE HealthCare and Siemens Healthineers occupy positions defined by recurring service revenue across integrated delivery networks and R&D intensity in next-generation detector materials respectively. Canon Medical Systems exemplifies the total cost-of-ownership competitive vector through aggressive contract structuring for mid-tier hospitals. NeuroLogica anchors the portable specialist archetype with concentrated deployment in neuro-intensive care units where bedside imaging eliminates transport risk.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Canon Medical Systems |
| Koninklijke Philips |
| FUJIFILM Holdings |
| NeuroLogica |
| Carestream Health |
| Hitachi Healthcare Systems |
| United Imaging Healthcare |
| Others |
Value Network & Pricing Analysis
A pronounced detector-technology bifurcation separates photon-counting premium systems from commodity spiral CT platforms, manifesting in divergent pricing power and supply chain sourcing strategies across North American procurement channels. Premium-tier vendors command value-based contracts anchored to clinical throughput guarantees and uptime service levels, while mid-tier competitors compete on total cost-of-ownership bundling that obscures component-level margin structures.
Pricing Analysis
Value-based pricing anchors to guaranteed scan throughput and equipment uptime commitments rather than hardware depreciation schedules alone. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting research systems from 128-slice cardiac workhorses and refurbished 64-slice community hospital fleets. Cost compression in mid-tier equipment is intensifying because integrated delivery networks unbundle service contracts from capital financing. Diagnostic imaging centers in Texas and Florida exhibit highest price sensitivity due to volume-based operational models, while academic medical centers in Massachusetts show lowest sensitivity given NIH-funded capital budgets.
Supply Chain Analysis
Helium supply for superconducting magnet cooling rests on Qatar and Russia extraction infrastructure, creating geographic concentration exposure for CT manufacturers dependent on cryogenic cooling systems. Cadmium zinc telluride semiconductor layers for photon-counting detectors draw from Japanese and German specialty material producers, while X-ray tube assemblies source from Chinese and Mexican manufacturing corridors. Single-source vulnerability in helium supply chains threatens production continuity given export restriction risk and price volatility. Distribution runs through OEM direct sales forces for premium systems and third-party imaging equipment distributors for refurbished and portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America CT market sits in a technology-transition phase where photon-counting detector architectures displace legacy energy-integrating scintillator systems across research and premium clinical installations.
For Market Incumbents: Deepen captive manufacturing of cadmium zinc telluride semiconductor layers to secure photon-counting detector supply chains against Japanese and German material bottlenecks. Fortify enterprise-wide service contract penetration across Midwest integrated delivery networks before third-party independent service organizations capture detector replacement and tube refurbishment revenue pools.
For New Entrants and Emerging Players: Enter via portable CT specialization targeting neuro-intensive care units in Canadian stroke centers and US academic medical centers where bedside imaging eliminates patient transport risks and incumbent OEMs maintain limited presence. Pursue FDA 510(k) clearance under abbreviated review tracks for predicate-equivalent mobile configurations to compress regulatory timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with photon-counting detector technology specialists given Medicare reimbursement stability for spectral imaging protocols and material decomposition applications. Acquisition targets should demonstrate established regulatory affairs infrastructure for FDA quality management systems and installed base leverage across hospital networks. The signal to watch is CMS site-of-service parity implementation pace between hospital outpatient departments and freestanding imaging centers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Navigation | Streamlined clearance for iterative reconstruction algorithms accelerates upgrade cycles and software-as-medical-device revenue streams. |
| Photon-Counting Detector R&D Partnership | Academic medical center collaborations in Massachusetts and California compress commercialization timelines for spectral imaging protocols. |
| Enterprise Service Contract Restructuring | Multi-vendor maintenance agreements with Catholic health systems and municipal districts defend recurring revenue against independent servicers. |
| Helium Supply Diversification | Alternative cryogenic cooling technologies reduce Qatar and Russia concentration exposure for superconducting magnet manufacturing. |
| AI Reconstruction Integration | Deep learning denoising modules open pediatric and repeat-scan applications previously constrained by cumulative radiation exposure limits. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, and hospital procurement contract filings, complemented by interviews with biomedical engineers, radiology department chairs, GPO contracts managers, and OEM service operations directors. Secondary validation drew from EPA radiation protection standards, NRC radioactive material licensing records, and American College of Radiology workforce surveys. Bottom-up equipment shipment modeling triangulated against top-down health system capital expenditure tracking.
Cross-referencing historical procurement cycle patterns against expert panel input on photon-counting adoption timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product mobility class, detector slice configuration, end-user facility type, and clinical application intensity. CAGRs derived from curve-fitting observed replacement cycles and technology diffusion rates within academic versus community hospital settings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under helium supply disruption scenarios and radiologist workforce shortage acceleration. Forecasts reflect assumptions on FDA clearance timeline stability and CMS reimbursement parity implementation. A small set of named triggers warrants ongoing watch: photon-counting detector manufacturing yield rates, third-party service organization market share capture, and state-level radiation shielding compliance escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Ultrasound Market
Medical Imaging
Asia-Pacific Nuclear Medicine Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Mammography Detectors Market