
 Europe Primary Angle-Closure Glaucoma Market | 2026-2036
Europe Primary Angle-Closure Glaucoma Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Primary Angle-Closure Glaucoma Market Foresight
Multi-source procurement for intraocular devices is recalibrating how European hospital systems secure glaucoma therapies. Novartis AG leverages its established ophthalmology portfolio across continental Europe. Alcon Inc anchors its position through surgical equipment and consumable bundles. Santen Pharmaceutical Co Ltd specializes in topical delivery formulations for early-stage intervention.
Primary angle-closure glaucoma is an optic neuropathy caused by physical blockage of aqueous humor outflow through the anterior chamber angle, typically characterized by elevated intraocular pressure exceeding 21 mmHg and progressive visual field loss. Its primary commercial purpose is to preserve retinal ganglion cell function and prevent irreversible blindness through pressure reduction. Medications and laser surgery currently lead the product type landscape, while intraocular devices represent the fastest-growing segment as MDR-compliant implants gain surgeon confidence. The end-user structure tilts toward ophthalmology clinics, where higher procedure volumes concentrate margin pools compared to general hospital settings.
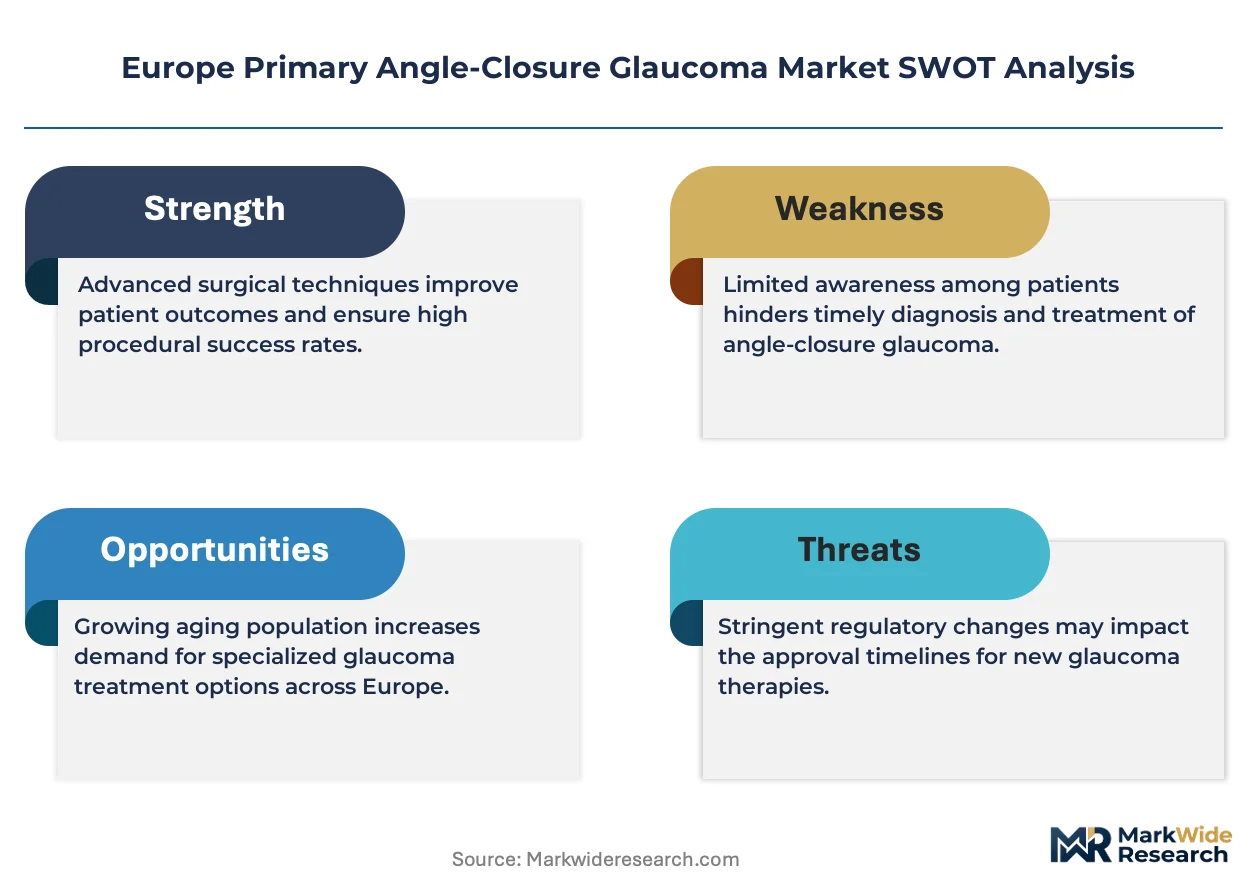
The European Medicines Agency (EMA) governs pharmaceutical approvals for glaucoma therapies, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements on intraocular implants and surgical instruments. REACH compliance additionally shapes material selection for device manufacturers operating within the European Economic Area. Stakeholders must monitor how notified body capacity constraints under MDR affect product launch timelines and competitive positioning.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product launch timelines for intraocular implants while ophthalmology clinics in Germany, France, and the United Kingdom accelerate procurement of minimally invasive surgical systems.
Growth Catalysts
- MDR Compliance Pathways:Stricter clinical evidence requirements under the EU Medical Device Regulation are filtering out marginal device competitors, concentrating procurement among qualified suppliers with established notified body relationships.
- Germany's Hospital Networks:Specialized eye hospital networks across Bavaria and North Rhine-Westphalia are consolidating glaucoma procedure volumes, creating concentrated demand pools for surgical equipment and consumable bundles.
- Laser Trabeculoplasty Adoption:Selective laser trabeculoplasty is overtaking medication-first protocols in early-stage intervention, reducing long-term pharmaceutical dependency and driving capital equipment refresh cycles.
Market Restraints
- Notified Body Bottlenecks:Capacity constraints among EU-authorized notified bodies are extending conformity assessment timelines for intraocular implants, delaying commercialization of next-generation drainage devices.
- Silicone Supply Concentration:Medical-grade silicone sourcing for intraocular lens haptics concentrates among a limited supplier base in Southern Germany, exposing device manufacturers to input cost volatility and allocation risk.
- Pharmaceutical Substitution:Fixed-combination topical therapies are displacing monotherapy prescriptions in early-stage management, compressing addressable patient populations for surgical intervention.
Strategic Opportunities
- France's Underpenetrated Regions:Peripheral ophthalmology clinics in Auvergne-Rhône-Alpes and Occitanie remain underserved for minimally invasive glaucoma surgery, presenting whitespace for equipment placement and surgeon training programs.
- REACH-Compliant Biomaterials:The European Chemicals Agency's REACH framework is incentivizing substitution of conventional device polymers with bioabsorbable alternatives, opening formulation partnerships for specialized chemical suppliers.
- Telemedicine Integration:Remote intraocular pressure monitoring platforms are converging with cloud-based visual field analysis, enabling post-surgical follow-up without clinic visits and expanding rural patient access.
Industry Challenges
- Glaucoma Subspecialty Training Gaps:The pipeline of fellowship-trained angle-closure specialists in the United Kingdom and Italy is insufficient to match procedure volume growth, constraining surgical capacity expansion.
- MDR Technical Documentation Burden:Small and mid-sized device manufacturers face disproportionate compliance costs for clinical evaluation reports and post-market surveillance systems, accelerating consolidation toward scaled players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Primary Angle-Closure Glaucoma Market |
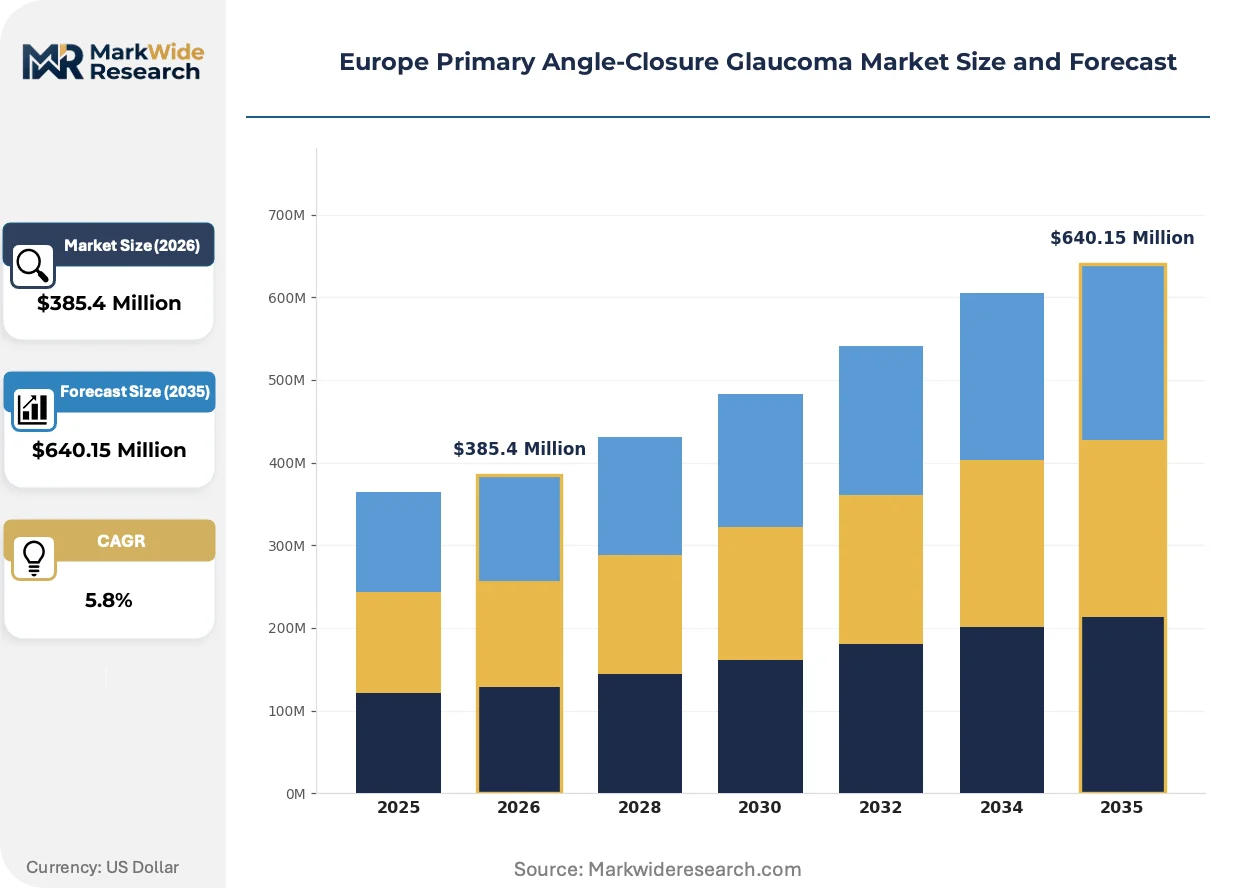
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Surgery, Medications, Intraocular Devices, Goniotomy Delivery Mode: Oral, Injectable, Topical, Surgical End User: Ophthalmology Clinics, Hospitals, Diagnostic Centers, Home Care Application: Diagnosis, Treatment, Management, Follow-up Care |
| Companies Covered | Novartis AG, Alcon Inc, AbbVie Inc, Santen Pharmaceutical Co Ltd, Bausch & Lomb Inc, Teva Pharmaceutical Industries Ltd, Pfizer Inc, Thea Pharma Inc, Viatris Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Primary Angle-Closure Glaucoma Market Shifts & Advancements
Minimally invasive surgical platforms are compressing recovery timelines while regulatory frameworks reshape material selection and notified body relationships across the European Economic Area.
Micro-invasive glaucoma surgery (MIGS) devices incorporating ab-interno stenting mechanisms are overtaking conventional trabeculectomy in early-to-moderate disease stages. German ophthalmology clinics in Stuttgart and Munich are adopting these systems at the fastest clip, driven by bundled reimbursement incentives from statutory health insurers. The shift is compressing average length-of-stay metrics and redirecting capital budgets toward disposable surgical packs.
REACH compliance mandates from the European Chemicals Agency are forcing reformulation of intraocular device polymers to eliminate Substances of Very High Concern. Manufacturers operating within the European Economic Area are substituting traditional phthalate plasticizers with bio-based alternatives in lens haptics and drainage device components. The transition is most advanced among implant suppliers with captive polymer synthesis capabilities in Switzerland and the Netherlands.
Surgeon preference for procedure-specific consumable bundles is displacing à-la-carte device procurement in high-volume French and British clinics. Hospital purchasing committees are consolidating vendor relationships to secure volume-based rebates on surgical packs combining implants, viscoelastics, and post-operative medications. This concentration is most visible in England's NHS Foundation Trusts, where procurement frameworks favor single-source agreements for glaucoma surgery pathways.
Europe Primary Angle-Closure Glaucoma Market Segmentation
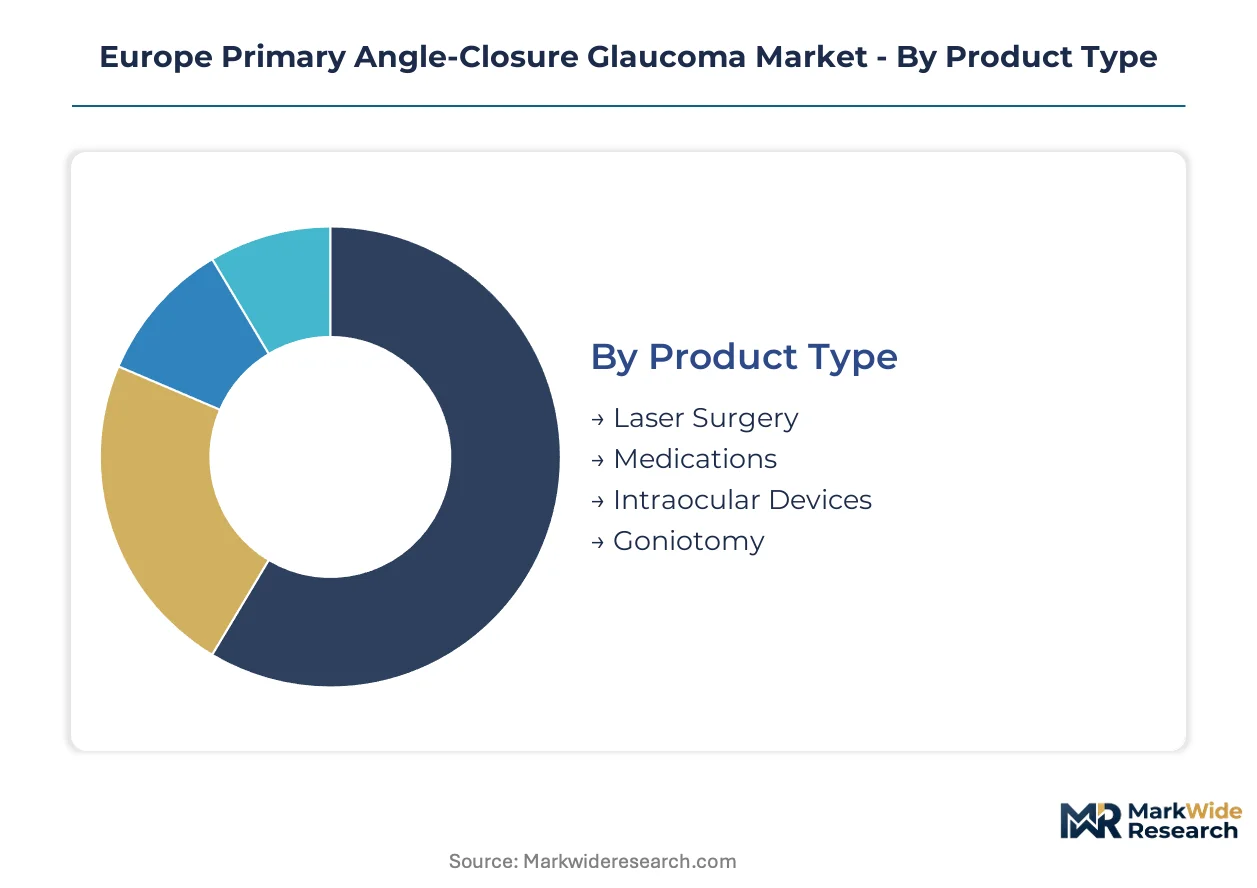
Segmentation in the Europe Primary Angle-Closure Glaucoma Market reveals divergent margin structures across intervention modalities. Product type stratification separates capital-intensive surgical platforms from recurring pharmaceutical revenues, while end-user concentration in specialized ophthalmology clinics reshapes distribution economics.
Product Type:
Standardization dominates laser and medication categories, while intraocular devices demand customization for anatomical variation across patient populations.
- Laser Surgery:Selective laser trabeculoplasty systems utilize frequency-doubled Nd:YAG or diode laser sources to photocoagulate trabecular meshwork tissue. German statutory health insurers in Bavaria and North Rhine-Westphalia now bundle SLT reimbursement with diagnostic workups, accelerating capital replacement cycles in high-volume clinics.
- Medications:Topical formulations—prostaglandin analogs, beta-blockers, alpha-agonists, and carbonic anhydrase inhibitors—reduce aqueous humor production or enhance uveoscleral outflow. Fixed-combination therapies from EMA-approved suppliers are displacing monotherapy prescriptions in France's hospital outpatient settings, compressing pharmaceutical addressable populations.
- Intraocular Devices:Ab-interno stents and drainage implants require MDR-compliant clinical evidence for CE marking.
- Goniotomy:Angle-based incisional surgery using microsurgical goniotomy blades or automated systems.
Most installed capacity flows through Laser Surgery. Expansion is steepest in Intraocular Devices.
Delivery Mode:
Cost tier stratification separates high-touch surgical administration from self-administered topical regimens, with injectable formats occupying a narrow middle band for acute pressure spikes.
- Oral:Systemic carbonic anhydrase inhibitors and hyperosmotic agents for acute angle-closure crises. French emergency departments in Paris and Lyon maintain oral acetazolamide stockpiles for same-day pressure reduction when topical therapy fails.
- Injectable:Intravenous or intracameral formulations for perioperative pressure management. United Kingdom NHS Foundation Trusts restrict injectable use to operating theater settings, limiting addressable volume to surgical caseloads.
- Topical:Patient-administered eye drops dominate early-stage intervention across all European markets. EMA-approved preservative-free formulations command premium pricing in Germany's private insurance segments.
- Surgical:Device-mediated delivery through implanted shunts or stents requires specialized training.
Patient volume concentrates in Topical administration. Margin expansion is most pronounced in Surgical delivery.
End User:
Customer type fragmentation separates high-acuity surgical centers from distributed diagnostic access points, with reimbursement models determining site-of-care economics.
- Ophthalmology Clinics:Specialized facilities concentrate glaucoma procedure volumes and margin pools. Stuttgart and Munich clinics in Germany are adopting MIGS platforms fastest, driven by bundled statutory health insurance incentives.
- Hospitals:Acute settings manage refractory cases and emergency angle-closure attacks. England's NHS Foundation Trusts are consolidating glaucoma surgery pathways into fewer high-volume centers.
- Diagnostic Centers:Independent imaging and visual field testing facilities.
- Home Care:Remote intraocular pressure monitoring and medication adherence platforms.
Procedure revenue pools deepest in Ophthalmology Clinics. Remote monitoring capabilities are expanding fastest in Home Care.
Application:
Maturity gradients separate established diagnostic modalities from emerging AI-assisted follow-up protocols, with treatment applications commanding the dominant revenue share.
- Diagnosis:Gonioscopy, optical coherence tomography, and visual field analysis identify angle closure. German eye hospital networks are standardizing anterior segment OCT for objective angle assessment.
- Treatment:Surgical and pharmaceutical interventions for pressure reduction. French clinics in Auvergne-Rhône-Alpes remain underserved for minimally invasive surgical options.
- Management:Long-term pressure monitoring and medication optimization.
- Follow-up Care:Post-surgical surveillance and progression monitoring.
Commercial investment concentrates in Treatment applications. Technology adoption is climbing fastest in Follow-up Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where glaucoma device manufacturers establish notified body relationships, with Switzerland and the Netherlands capturing formulation chemistry investment while Southern Germany concentrates medical-grade silicone supply.
Germany
Bavaria and North Rhine-Westphalia host specialized eye hospital networks consolidating glaucoma procedure volumes. The EU Medical Device Regulation imposes stricter clinical evidence requirements through German notified bodies, filtering marginal competitors from CE marking pathways. Stuttgart and Munich clinics are adopting minimally invasive surgical platforms fastest, driven by bundled statutory health insurance reimbursement incentives.
France
Peripheral ophthalmology clinics in Auvergne-Rhône-Alpes and Occitanie remain underserved for surgical intervention, presenting whitespace for equipment placement. ANSM governs pharmaceutical approvals for topical therapies while EMA harmonizes centralized marketing authorizations across the European Economic Area. Paris and Lyon emergency departments maintain oral acetazolamide stockpiles for acute angle-closure crises when topical therapy fails.
United Kingdom
NHS Foundation Trusts are consolidating glaucoma surgery pathways into fewer high-volume centers, concentrating procurement leverage. The Medicines and Healthcare products Regulatory Agency enforces MDR transition timelines for intraocular implants already on market. England's hospital purchasing committees favor single-source agreements for surgical packs combining implants, viscoelastics, and post-operative medications.
Switzerland
Swissmedic regulates pharmaceutical and device approvals with mutual recognition agreements easing EEA market access. Captive polymer synthesis capabilities in Basel and Zurich advance REACH-compliant biomaterial substitution for intraocular device components. Swiss implant suppliers are substituting traditional phthalate plasticizers with bio-based alternatives in lens haptics ahead of regulatory deadlines.
Netherlands
Eindhoven Region and Randstad cluster chemical suppliers developing bioabsorbable polymer formulations for drainage device applications. The European Chemicals Agency's REACH framework incentivizes elimination of Substances of Very High Concern from conventional device polymers. Dutch specialty chemical firms are partnering with implant manufacturers on formulation partnerships for next-generation intraocular materials.
Europe Primary Angle-Closure Glaucoma Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioabsorbable material differentiation and telemedicine integration. The vendor base stratifies across multinational pharmaceutical conglomerates with ophthalmology divisions, specialized surgical equipment manufacturers, and regional topical formulation suppliers. Three archetypes dominate: integrated pharma-device hybrids bundling medication and surgical platforms, pure-play device specialists navigating MDR compliance pathways, and generic pharmaceutical manufacturers competing on preservative-free formulation premiums. Competitive moves center on notified body relationship deepening to compress CE marking timelines, and strategic partnerships with REACH-compliant polymer suppliers to secure input material allocation.
Among Swiss- and Dutch-anchored chemical suppliers, formulation specialists exemplify the material-innovation archetype. Novartis AG and Alcon Inc occupy positions as integrated pharma-device hybrids, with the former leveraging established ophthalmology portfolios and the latter anchoring through surgical equipment and consumable bundles. Santen Pharmaceutical Co Ltd represents the topical delivery specialization archetype, focusing on early-stage intervention formulations. These three companies illustrate how competitive positioning diverges across intervention modalities rather than converging on single-technology dominance.
| Leading Market Players |
|---|
| Novartis AG |
| Alcon Inc |
| AbbVie Inc |
| Santen Pharmaceutical Co Ltd |
| Bausch & Lomb Inc |
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc |
| Thea Pharma Inc |
| Viatris Inc |
| Others |
Supply & Pricing Matrix
Bundled procurement frameworks from England's NHS Foundation Trusts are compressing vendor margins and forcing intraocular device manufacturers toward single-source agreements that sacrifice pricing power for volume security. REACH-compliant polymer reformulation adds input cost pressure that suppliers must absorb or pass through selectively.
Pricing Analysis
Input-cost pass-through from medical-grade silicone and bioabsorbable polymer sourcing is fragmenting pricing structures across supplier tiers. Three-tier pricing stratifies across MDR-certified premium implants, transitional standard devices, and economy generics facing commoditization. Cost compression in the economy tier is intensifying because statutory health insurers in Germany and France are tightening reimbursement bands. Hospital purchasing committees show highest price sensitivity, while specialized ophthalmology clinics in Stuttgart and Munich accept premium positioning for bundled surgical packs with training and service attachments.
Supply Chain Analysis
CE marking and MDR technical documentation requirements are gating supplier qualification, concentrating compliant manufacturing in Switzerland, the Netherlands, and Southern Germany. Medical-grade silicone for lens haptics, bioabsorbable polymers for drainage devices, and precision-machined titanium components constitute critical input dependencies. Single-source vulnerability concentrates in Southern German silicone suppliers, exposing device manufacturers to allocation risk. Distribution runs through specialized ophthalmology distributors and hospital purchasing consortia rather than broad-line medical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where surgeon confidence in MDR-compliant implants and bundled reimbursement incentives are shifting procurement toward premium specifications with validated clinical evidence.
For Market Incumbents: Acquire REACH-compliant polymer synthesis capabilities to secure input supply and compress formulation costs before regulatory deadlines tighten. Deepen notified body relationships in Germany and Switzerland to accelerate CE marking timelines for next-generation drainage devices. Bioabsorbable material specialists in the Netherlands pose substitution threats that captive supply chains can neutralize. For New Entrants and Emerging Players: Telemedicine-enabled remote monitoring platforms offer the most penetrable entry vector, with post-surgical follow-up applications in France's Auvergne-Rhône-Alpes and Occitanie regions remaining underserved. Target peripheral ophthalmology clinics lacking MIGS equipment placement through cloud-based visual field analysis partnerships rather than capital-intensive device sales. For Investors and Strategic Acquirers: Asymmetric upside sits with Swiss- and Dutch-anchored chemical suppliers developing bioabsorbable formulations for intraocular applications. The five-to-ten year viability window favors acquisition targets with captive polymer capabilities and established EEA regulatory dossiers. Notified body capacity expansion announcements signal inflection points for device commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerated CE marking timelines compress competitive windows for intraocular implants in German notified body pathways. |
| REACH-Compliant Polymer Partnership | Bioabsorbable formulation alliances with Dutch chemical suppliers secure input allocation ahead of regulatory substitution mandates. |
| Hospital System Bundled Agreement | Single-source surgical pack contracts with England's NHS Foundation Trusts lock in multi-year consumable revenue streams. |
| Surgeon Training Program Expansion | Fellowship partnerships in the United Kingdom and Italy address subspecialty capacity constraints constraining procedure volume growth. |
| Telemedicine Platform Integration | Remote intraocular pressure monitoring with cloud-based visual field analysis extends rural patient access in underserved French regions. |
Research Methodology
Direct dialogue with glaucoma subspecialists, hospital purchasing committee members, biomedical engineers at implant manufacturers, and regulatory affairs leads at notified bodies grounded qualitative findings. Secondary validation drew from EMA centralized marketing authorization databases, EU MDR transition status reports, hospital procurement contract registries, and REACH compliance disclosure filings. Bottom-up and top-down triangulation reconciled procedure volume estimates with statutory health insurance reimbursement data.
Bottom-up modeling anchored forecasts to country-level procedure volumes, statutory reimbursement rates, and device penetration curves across the projection horizon. Segmentation dimensions spanned product type, delivery mode, end-user concentration, and application maturity. CAGRs derived from trend extrapolation of historical statutory health insurance claims data and surgeon adoption surveys. MDR transition timelines and REACH substitution deadlines provided industry-specific forecast boundaries.
Notified body capacity constraints, REACH enforcement intensity, and surgeon training pipeline expansion are the dominant revision risks. Deviation in notified body processing velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Lazy Eye Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Astigmatism Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Neurotrophic Keratitis Market