
 Spectacle Lens Market | 2026-2036
Spectacle Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Spectacle Lens Market Outlook
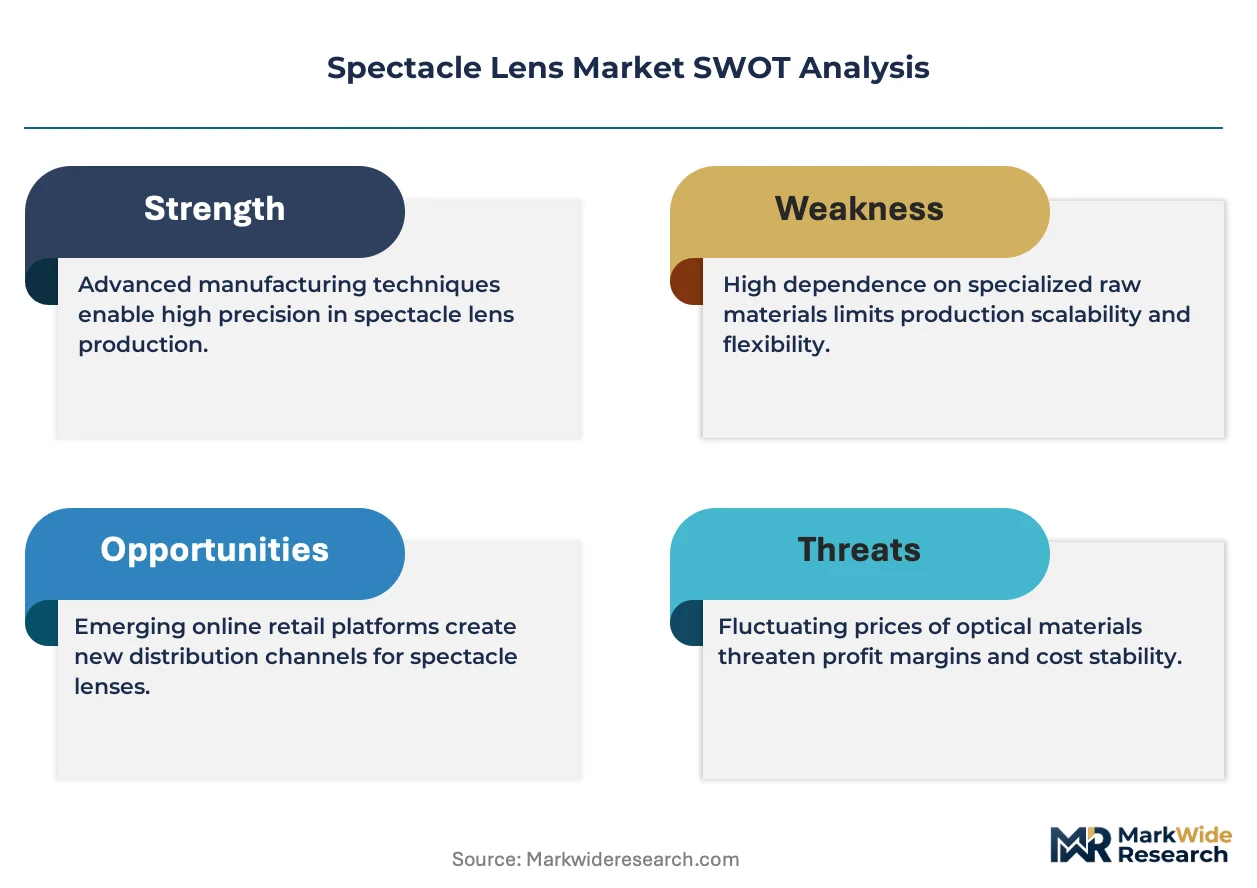
EU REACH chemical safety standards is repositioning material sourcing protocols for spectacle lens manufacturers, raising compliance costs for polycarbonate and high-index resin formulations. EssilorLuxottica leverages its captive monomer-to-lens manufacturing chain to absorb these regulatory burdens internally. Carl Zeiss AG anchors its premium positioning through proprietary freeform surfacing technology that exceeds standard optical tolerances. Hoya Corporation dominates the Asian ophthalmic channel by controlling distribution through direct clinic partnerships across Japan and South Korea.
A spectacle lens is a precision optical element ground or molded to correct refractive errors, typically manufactured from thermoset resins such as allyl diglycol carbonate (CR-39) with Abbe values between 30 and 58, or injection-molded polycarbonate with impact resistance exceeding FDA drop-ball requirements. Progressive addition lenses now command the highest margin pools as presbyopic populations reject visible segment lines in multifocal designs. Photochromic coating applications are expanding fastest among retail consumers seeking dual indoor-outdoor functionality without auxiliary eyewear. Glass material formulations retain niche demand in specific safety-critical industrial applications where scratch resistance outweighs weight penalties.
FDA 21 CFR Part 801 governs impact resistance and labeling for lenses distributed in the United States, while EU MDR Class I rules subject custom-finished spectacle lenses to post-market surveillance obligations. ISO 8980 series standards define optical power tolerances and transmittance requirements that manufacturers must certify for CE marking and international market access. Stakeholders should monitor evolving blue-light filtration claims regulation as ophthalmic health agencies in Germany, France, and Japan develop testing protocols that could disqualify unsubstantiated coating marketing.
Market Dynamics
EU REACH chemical safety standards are forcing spectacle lens manufacturers to requalify resin formulations and coating chemistries, compressing supplier flexibility while elevating compliance costs across polycarbonate and high-index material streams.
Growth Catalysts
- Myopia Epidemic in East Asian School-Age Populations:Rising childhood myopia prevalence in China, Japan, and South Korea is accelerating demand for pediatric progressive lenses and myopia-control optical designs.
- EU MDR Post-Market Surveillance Mandates:Class I device classification for custom-finished spectacle lenses under EU MDR is strengthening quality assurance investments and differentiating compliant manufacturers.
- Photochromic Coating Chemistry Advances:Improved silver halide and naphthopyran formulations are expanding dual indoor-outdoor functionality adoption among retail consumers seeking auxiliary eyewear elimination.
Market Restraints
- Monomer Supply Concentration:Allyl diglycol carbonate (CR-39) precursor production concentrates among specialty chemical suppliers in Germany and Japan, creating input cost volatility and qualification bottlenecks.
- High-Index Resin Technical Limitations:Abbe value degradation above 1.67 refractive index produces chromatic aberration that limits optical performance in severe myopia corrections.
- Blue-Light Filtration Regulatory Friction:Pending testing protocols from ANSM in France and Germany's ophthalmic health agencies threaten to disqualify unsubstantiated coating marketing claims.
Strategic Opportunities
- Underpenetrated Indian Tier-Two Cities:Vision correction clinic penetration remains below 15% in secondary Indian urban centers, creating whitespace for distribution partnerships with regional optical chains.
- Freeform Surfacing Technology Convergence:Integration of precision diamond turning with wavefront-guided optimization enables personalized lens designs that command premium positioning.
- Japan's JIS Standards Harmonization:Alignment of domestic optical tolerances with ISO 8980 series is reducing export certification friction for manufacturers targeting Asia-Pacific markets.
Industry Challenges
- Freeform Surfacing Technician Scarcity:Precision diamond turning and wavefront optimization require specialized optomechanical skills that outpace vocational training program output in manufacturing hubs.
- ISO 8980-3 Transmittance Certification Timelines:UV and blue-light filtration testing protocols extend product launch cycles by 4-8 months for coating-dependent lens portfolios.
- Legacy CRM Integration Complexity:Clinic-direct distribution models in Japan and South Korea demand API connectivity with proprietary practice management software that fragments order-to-fulfillment automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectacle Lens Market |
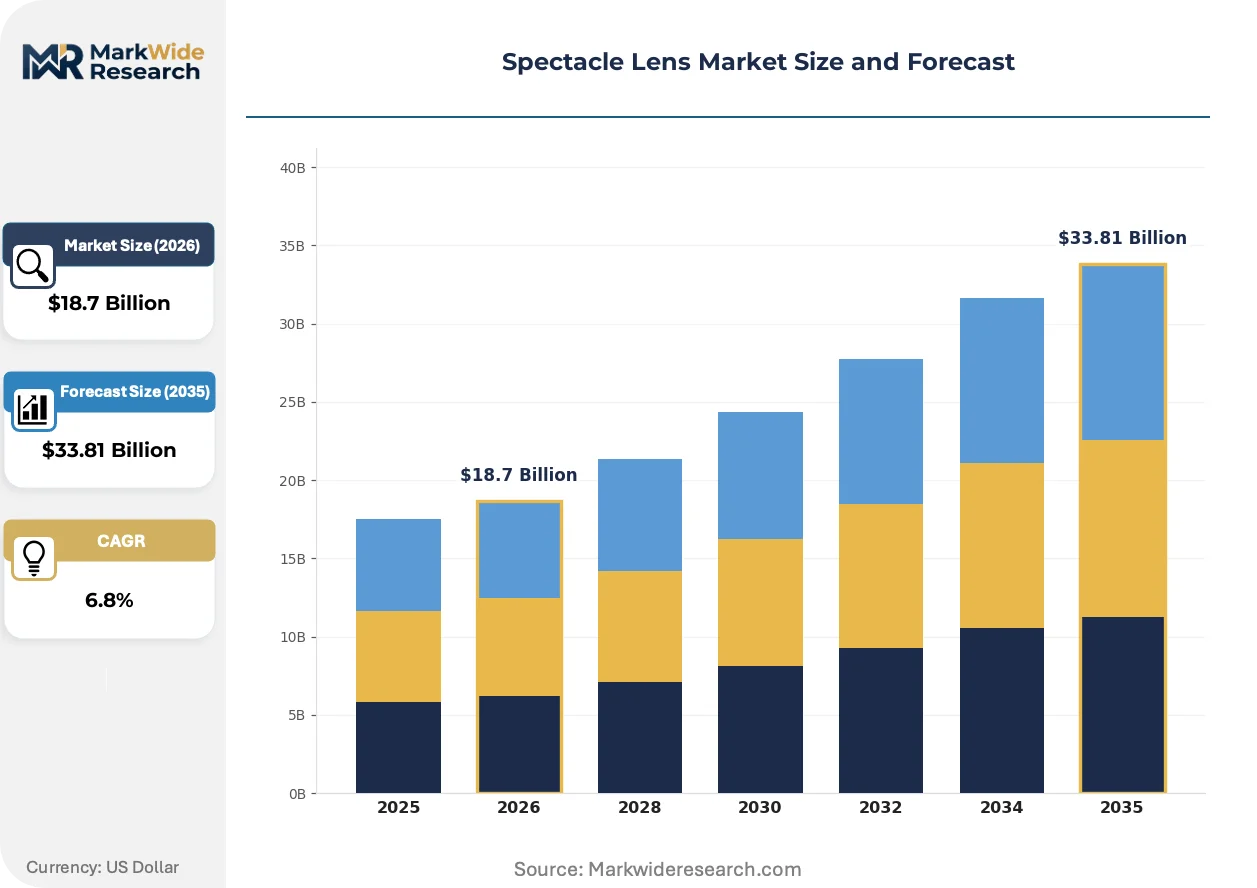
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Trifocal, Progressive Material: Polycarbonate, CR-39, High Index, Glass Coating: Anti-Reflective, Scratch-Resistant, Photochromic, UV Protection End User: Retail Consumers, Optical Stores, Online Retailers, Clinics |
| Companies Covered | EssilorLuxottica, Carl Zeiss AG, Hoya Corporation, Nikon Corporation, Rodenstock GmbH, Seiko Optical Products, Shamir Optical Industry, Tokai Optical, Vision-Ease Lens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectacle Lens Market Strategic Shifts
Digital surfacing workflows and personalized optical design are compressing the gap between prescription measurement and lens fabrication, enabling mass customization that was previously confined to artisanal production.
Freeform lens manufacturing technology is modularizing production economics by decoupling surface generation from polishing and coating stages. Mid-scale optical laboratories in Italy and the United States are adopting compact five-axis generators that previously required centralized factory deployment. This modularity is enabling distributed fabrication networks that reduce shipping distances and prescription turnaround times from weeks to days.
REACH authorization requirements for diisocyanates used in polyurethane coating formulations are tightening material sourcing protocols across European manufacturing facilities. ECHA's 2023 restriction entry is forcing reformulation investments that favor water-based and UV-cured alternatives. High-index resin lens categories with premium anti-reflective stacks face the steepest compliance cost increases, accelerating supplier consolidation toward integrated chemical-lens manufacturers.
Direct-to-consumer refraction apps and online prescription renewal platforms are fragmenting traditional optometrist-dependent purchasing journeys in North American and Western European markets. Younger presbyopic cohorts in the United States increasingly initiate lens replacement through digital channels before confirming fittings at retail partners. This channel bifurcation is compressing wholesale margins while elevating importance of brand recognition and virtual try-on accuracy.
Spectacle Lens Market Segmentation
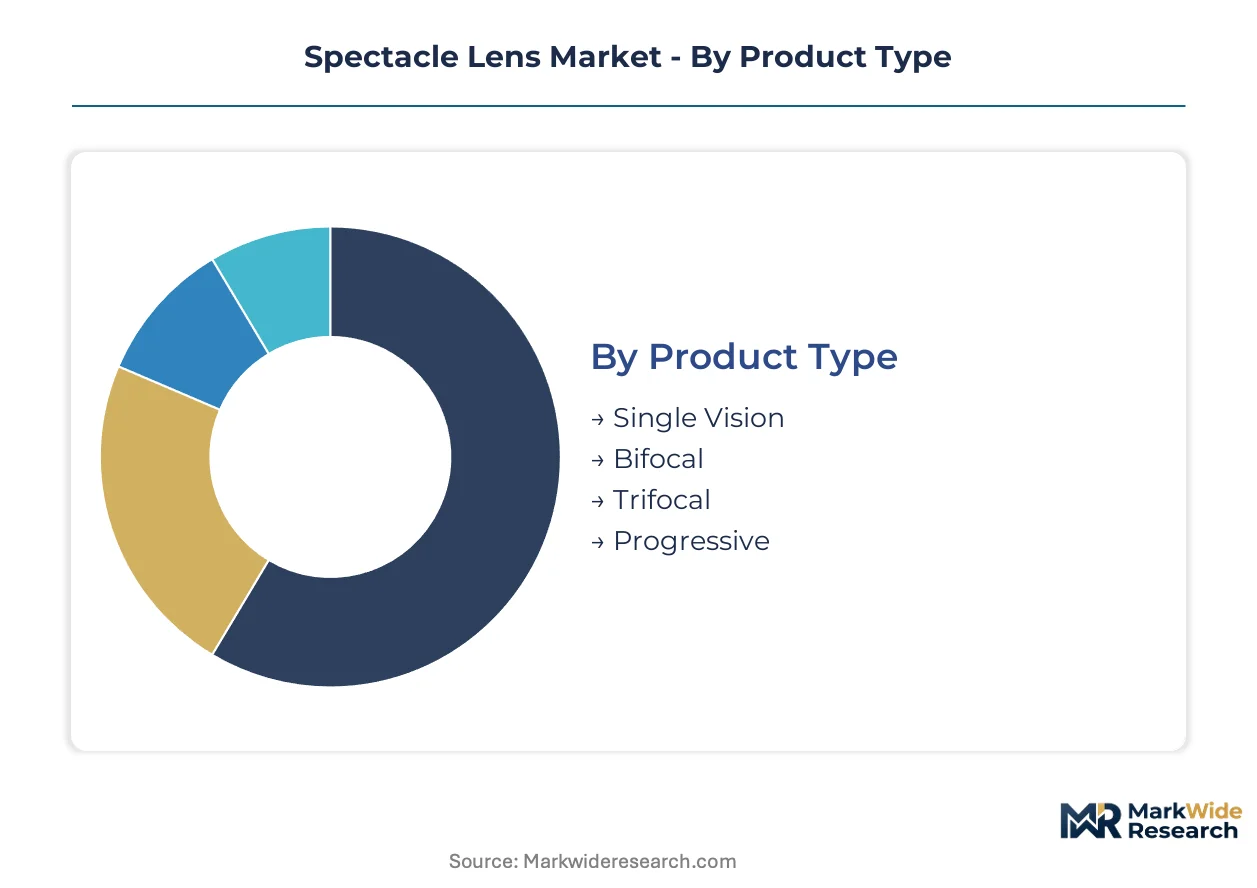
Segmentation in spectacle lenses tracks the divergence between mass-produced standard corrections and precision-customized optical solutions. Each dimension—product design, substrate chemistry, surface engineering, and channel access—carries distinct margin profiles and technical qualification barriers that reshape competitive positioning.
Product Type:
Customization intensity spans from commodity single-vision blanks to fully personalized progressive surfaces requiring wavefront-guided optimization.
- Single Vision:Uniform optical power across the entire lens surface, manufactured through cast molding of CR-39 or injection molding of polycarbonate. Demand concentrates in India's tier-two cities where first-time vision correction users prioritize cost accessibility over advanced features.
- Progressive:Continuous power gradient from distance to near vision eliminates visible segment lines through freeform diamond turning and surface-specific coating protocols. Presbyopic populations in Japan and South Korea reject multifocal designs with visible divisions, accelerating clinic-direct procurement of premium progressive designs.
- Bifocal:Two distinct optical zones separated by a visible segment line, ground from semi-finished blanks with fused or cemented construction.
- Trifocal:Three power zones for distance, intermediate, and near correction, retaining niche demand among industrial safety applications where segment visibility is tolerated.
Leading the category by volume: Single Vision. Expanding most quickly: Progressive.
Material:
Cost tier stratification separates commodity thermosets from high-index resins commanding 3-4x raw material premiums.
- CR-39:Allyl diglycol carbonate thermoset resin with Abbe values of 58 delivering superior optical clarity and minimal chromatic aberration. Allyl diglycol carbonate precursor production concentrates among specialty chemical suppliers in Germany and Japan, creating input cost volatility and qualification bottlenecks for independent lens manufacturers.
- High Index:Dense thermoset formulations above 1.60 refractive index enabling thinner profiles for severe myopia corrections. Abbe value degradation above 1.67 refractive index produces chromatic aberration that limits optical performance, constraining adoption in prescriptions exceeding -8.00 diopters.
- Polycarbonate:Impact-resistant thermoplastic meeting FDA drop-ball requirements through injection molding, dominating pediatric and safety applications.
- Glass:Silicate-based formulations with exceptional scratch resistance, retaining demand in specific safety-critical industrial applications where weight penalties are secondary to surface durability.
Dominating volume: CR-39. Steepest expansion trajectory: High Index.
Coating:
Application-driven margin pools separate functional durability layers from adaptive chemistry commanding premium retail pricing.
- Photochromic:Silver halide or naphthopyran-embedded layers undergoing reversible darkening upon UV exposure, enabling dual indoor-outdoor functionality without auxiliary eyewear. Improved silver halide and naphthopyran formulations are expanding adoption among retail consumers seeking auxiliary eyewear elimination.
- Anti-Reflective:Multi-layer interference coatings of magnesium fluoride and metal oxides reducing surface reflections below 1%. REACH authorization requirements for diisocyanates used in polyurethane coating formulations are tightening material sourcing protocols across European manufacturing facilities.
- Scratch-Resistant:Silicon dioxide or diamond-like carbon hardcoats protecting against mechanical abrasion in daily wear conditions.
- UV Protection:Organic absorber-doped substrates or surface treatments blocking UVA and UVB transmission below 400 nanometers.
Highest volume attachment: Anti-Reflective. Gaining share fastest: Photochromic.
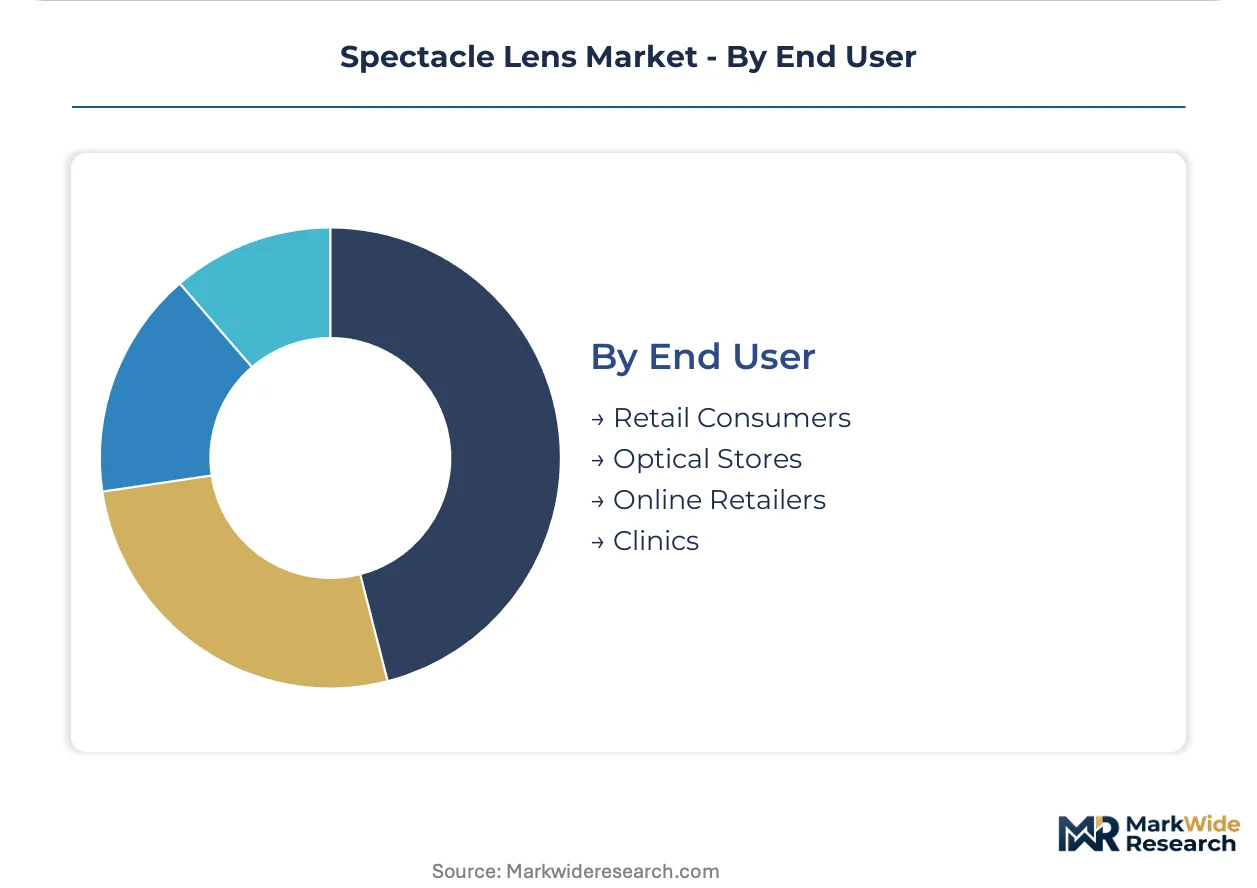
End User:
Channel concentration determines order-to-fulfillment automation requirements and brand control intensity.
- Clinics:Ophthalmology and optometry practices with in-house finishing laboratories, controlling prescription accuracy and lens fitting. Hoya Corporation dominates the Asian ophthalmic channel by controlling distribution through direct clinic partnerships across Japan and South Korea.
- Optical Stores:Independent and chain retail locations with surfacing partnerships or captive edging laboratories, balancing inventory breadth against customization speed.
- Retail Consumers:Individual purchasers through direct-to-consumer refraction apps and online prescription renewal platforms, fragmenting traditional optometrist-dependent purchasing journeys in North American and Western European markets.
- Online Retailers:Digital-native platforms with virtual try-on capabilities and remote prescription verification, compressing wholesale margins while elevating importance of brand recognition and virtual try-on accuracy.
Largest volume channel: Optical Stores. Climbing the fastest: Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port incentives are accelerating ophthalmic manufacturing consolidation along the southern coast, drawing lens coating specialists into bonded logistics zones with 15% corporate tax rates.
China
Myopia progression among Shanghai and Beijing school-age populations drives pediatric progressive lens procurement through hospital-affiliated optical centers. NMPA medical device registration rules now mandate clinical validation for myopia-control claims, extending product approval timelines. Guangzhou's Panyu district hosts the densest cluster of freeform surfacing laboratories serving domestic brands and export orders.
United States
Presbyopic consumers in California and Texas increasingly initiate lens purchases through direct-to-consumer platforms before retail fitting confirmation. FDA 21 CFR Part 801 impact resistance testing requirements govern polycarbonate distribution for pediatric safety applications. Dallas-Fort Worth anchors the largest independent optical laboratory network, with distributed surfacing capacity reducing prescription turnaround to 48 hours.
Germany
REACH authorization constraints on diisocyanate-based coating formulations are elevating compliance costs for high-index resin production in Baden-Württemberg. EU MDR Class I post-market surveillance obligations now apply to custom-finished spectacle lenses distributed across the single market. Munich's optical corridor concentrates precision diamond turning equipment suppliers serving freeform lens manufacturers.
Japan
Clinic-direct distribution models in Tokyo and Osaka sustain premium progressive lens attachment rates among aging presbyopic populations. METI alignment of JIS standards with ISO 8980 series is reducing export certification friction for manufacturers targeting Asia-Pacific markets. Nagoya's Chubu region houses specialized optomechanical training institutes addressing freeform surfacing technician scarcity.
India
Vision correction clinic penetration below 15% in Bangalore and Hyderabad secondary districts creates distribution whitespace for regional optical chain partnerships. BIS certification requirements for imported ophthalmic lenses are strengthening domestic manufacturing quality investments. Mumbai's optical wholesale cluster is consolidating surfacing capacity to serve tier-two city expansion.
Spectacle Lens Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Vertically integrated chemical-lens manufacturers absorb REACH compliance burdens through captive monomer production, while independent laboratories rely on qualified supplier networks. Strategic consolidation concentrates freeform surfacing capacity among scale players, and technology licensing agreements proliferate for wavefront-guided optimization software.
Among Asia-Pacific headquartered manufacturers, Hoya Corporation and Nikon Corporation exemplify clinic-direct distribution archetypes with embedded channel control, while EssilorLuxottica anchors the diversified conglomerate tier spanning material production through retail integration. These three entities represent contrasting strategic postures: captive chemical supply, precision equipment integration, and end-to-end value chain ownership.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Carl Zeiss AG |
| Hoya Corporation |
| Nikon Corporation |
| Rodenstock GmbH |
| Seiko Optical Products |
| Shamir Optical Industry |
| Tokai Optical |
| Vision-Ease Lens |
| Others |
Value Chain & Pricing Dynamics
Clinic-direct procurement preferences in Japan and South Korea for premium progressive designs are compressing wholesale margins and forcing manufacturers to absorb coating compliance costs internally, elevating pricing power for integrated producers with captive resin supply.
Pricing Analysis
Short lead-time premiums of 15-20% apply to freeform surfacing orders fulfilled within 48 hours through distributed laboratory networks in Italy and the United States. Three-tier pricing structure across premium, standard, and economy levels separates wavefront-guided personalized designs from cast-molded single-vision blanks. Price differentiation hinges on ISO 8980-3 certification tier and customization depth. Cost compression in economy-grade CR-39 lenses is intensifying because of allyl diglycol carbonate precursor volatility. Retail consumers through direct-to-consumer platforms exhibit highest price sensitivity; clinic-direct buyers in Tokyo and Osaka show lowest sensitivity due to fitting service bundling.
Supply Chain Analysis
Direct-to-clinic channels handle premium progressive demand across Japan and South Korea, while optical store networks manage mid-tier volume in Germany and the United States. Raw material supply concentrates in Germany and Japan for CR-39 monomers, China for high-index resin precursors, and Italy for freeform surfacing equipment. Distribution runs through ophthalmology practices with in-house finishing laboratories in Asia-Pacific, fragmented independent optical retailers in Western Europe, and consolidating wholesale clusters in India. Single-source vulnerability in allyl diglycol carbonate qualification creates bottleneck risk for independent lens manufacturers lacking captive chemical supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeform surfacing technician scarcity props pricing for precision-manufactured progressive lenses, constraining supply expansion despite demand acceleration from aging presbyopic populations.
For Market Incumbents: Deploy captive monomer production to absorb REACH compliance burdens for diisocyanate-based coating formulations. Consolidate freeform surfacing capacity through precision diamond turning equipment acquisition in Baden-Württemberg and Guangzhou. Defend against direct-to-consumer platform encroachment by embedding virtual try-on accuracy into clinic-direct service bundles. For New Entrants and Emerging Players: Launch via regional optical chain partnerships in Bangalore and Hyderabad secondary districts where vision correction clinic penetration remains below 15%. Target myopia-control optical designs for East Asian school-age populations as the most penetrable segment. Pursue white-label freeform surfacing contracts with mid-scale Italian laboratories seeking coating specialization. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated chemical-lens manufacturers given REACH authorization constraints tightening material sourcing protocols. Long-term viability favors archetypes with captive resin supply and clinic-direct distribution control in Asia-Pacific. Watch NMPA medical device registration timelines for myopia-control claims as inflection indicator for pediatric progressive lens market access.| Strategic Initiative | Industry Significance |
|---|---|
| Freeform Surfacing Capacity Expansion | Distributed five-axis generators in Dallas-Fort Worth reduce prescription turnaround to 48 hours. |
| Backward Integration into Monomer Supply | Captive allyl diglycol carbonate production absorbs ECHA 2023 restriction compliance costs. |
| Clinic-Direct Distribution Partnerships | Embedded channel control in Tokyo and Osaka sustains premium progressive attachment rates. |
| Photochromic Coating Formulation Investment | Silver halide and naphthopyran advances enable dual indoor-outdoor functionality without auxiliary eyewear. |
| Water-Based Coating Transition | UV-cured alternatives to diisocyanate-based formulations satisfy REACH authorization requirements. |
Study Parameters
Independent corroboration across optical laboratory managers, ophthalmology clinic procurement leads, coating chemistry R&D directors, and freeform surfacing equipment suppliers underwrites the qualitative findings. Primary interviews with distribution channel partners in Japan, South Korea, Germany, and India combined with secondary validation from FDA 21 CFR Part 801 filings, ECHA REACH authorization databases, NMPA medical device registration records, and ISO 8980 series certification timelines. Bottom-up prescription volume modeling and top-down value chain margin analysis triangulate market sizing.
Rate-of-change decomposition across the analysis window segments demand by product type (single vision, progressive, bifocal, trifocal), material substrate (CR-39, high-index resin, polycarbonate, glass), coating application (photochromic, anti-reflective, scratch-resistant, UV protection), and end-user channel (clinics, optical stores, retail consumers, online retailers). CAGRs derive from prescription volume growth trajectories, pricing tier evolution, and regional channel shift patterns. Freeform surfacing equipment deployment rates and myopia progression epidemiological data inform supply-side capacity assumptions.
The model assumes a particular technology adoption path; alternative pathways for wavefront-guided optimization software would alter the outlook if virtual try-on accuracy fails to match in-clinic refraction precision. Forecasts reflect assumptions regarding EU MDR Class I surveillance compliance timelines, REACH authorization scope expansion, and NMPA myopia-control claim validation protocols. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Radial Compression Devices Market
Medical Devices
North America C-Arms Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Water Flosser Market
Medical Devices
Struts Implants Market