
 Bathroom and Toilet Assist Devices Market | 2026-2036
Bathroom and Toilet Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bathroom and Toilet Assist Devices Market Intelligence
Home healthcare is consolidating as the dominant end-use vertical, displacing institutional procurement share. Invacare Corporation leverages its North American distribution network to sustain channel control in residential segments. Arjo competes through specialized bariatric and pressure-care engineering. Etac anchors its position with modular Scandinavian-designed systems that integrate across bathroom retrofit workflows.
Bathroom and toilet assist devices encompass mechanically or electrically actuated fixtures that modify standard sanitation infrastructure to accommodate reduced mobility, balance impairment, or post-surgical rehabilitation. These products typically incorporate corrosion-resistant aluminum or stainless steel frames rated for loads exceeding 150 kg, with surface treatments that resist chlorine-based cleaning protocols common in healthcare environments. Raised toilet seats and grab bars represent mature volume categories where margin pools have compressed toward commodity levels, while smart bidet attachments with sensor-activated hygiene functions capture expanding premium positioning. Electric and portable technology segments are gaining fastest among end users retrofitting rental properties or temporary recovery spaces.
The U.S. FDA classifies powered toilet seat lifts as Class II medical devices requiring 510(k) clearance, while the EU Medical Device Regulation mandates CE marking and post-market surveillance for electric assist units sold in member states. Japan's Ministry of Economy, Trade and Industry coordinates with municipal long-term care insurance boards to standardize reimbursement eligibility for approved device categories. Stakeholders must monitor divergence between FDA software-as-medical-device guidance and EU AI Act applicability to emerging sensor-equipped toilet systems.
Market Dynamics
Japan's long-term care insurance system is accelerating municipal subsidy programs for residential bathroom modifications, redirecting procurement from institutional buyers toward individual households and their contractors.
Growth Catalysts
- Japan's LTCI municipal subsidies:Local governments in super-aged municipalities now cover 70-90% of installation costs for approved assist devices, unlocking household-level demand that institutional procurement previously suppressed.
- Sensor-activated hygiene modules:Smart bidet attachments with pressure-sensitive seating and automated cleansing cycles capture premium positioning among post-surgical rehabilitation patients seeking reduced caregiver dependency.
- Corrosion-resistant aluminum framing:Advanced surface treatments rated for chlorine-based healthcare cleaning protocols extend product lifecycles in home healthcare environments, reducing replacement frequency.
Market Restraints
- Stainless steel input volatility:Medical-grade 316L stainless steel pricing fluctuations compress margins on grab bar and frame components sourced through concentrated Asian mill networks.
- EU MDR post-market surveillance:Electric assist units face extended compliance timelines and mandatory clinical follow-up studies, delaying CE-marked product launches by 12-18 months.
- Modular furniture substitution:Scandinavian-designed universal design bathroom systems from integrated fixture manufacturers capture retrofit budgets that discrete assist devices previously accessed.
Strategic Opportunities
- Rental property retrofit channels:Portable and non-permanent installation formats unlock property manager procurement for temporary recovery spaces and aging tenant accommodations.
- FDA 510(k) software-as-medical-device pathway:Sensor-equipped toilet systems with AI-driven fall risk assessment qualify for accelerated clearance under evolving digital health guidance.
- India's PLI scheme for medical devices:Domestic manufacturing incentives for Class B and C devices reduce import dependency and enable price-competitive regional distribution.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized industrial designers capable of integrating pressure-care surfaces with sanitation hygiene requirements command premium compensation and extended recruitment cycles.
- Legacy plumbing infrastructure incompatibility:Electric seat lift mechanisms face installation friction in pre-1980s residential buildings with non-standard flange heights and electrical capacity constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bathroom and Toilet Assist Devices Market |
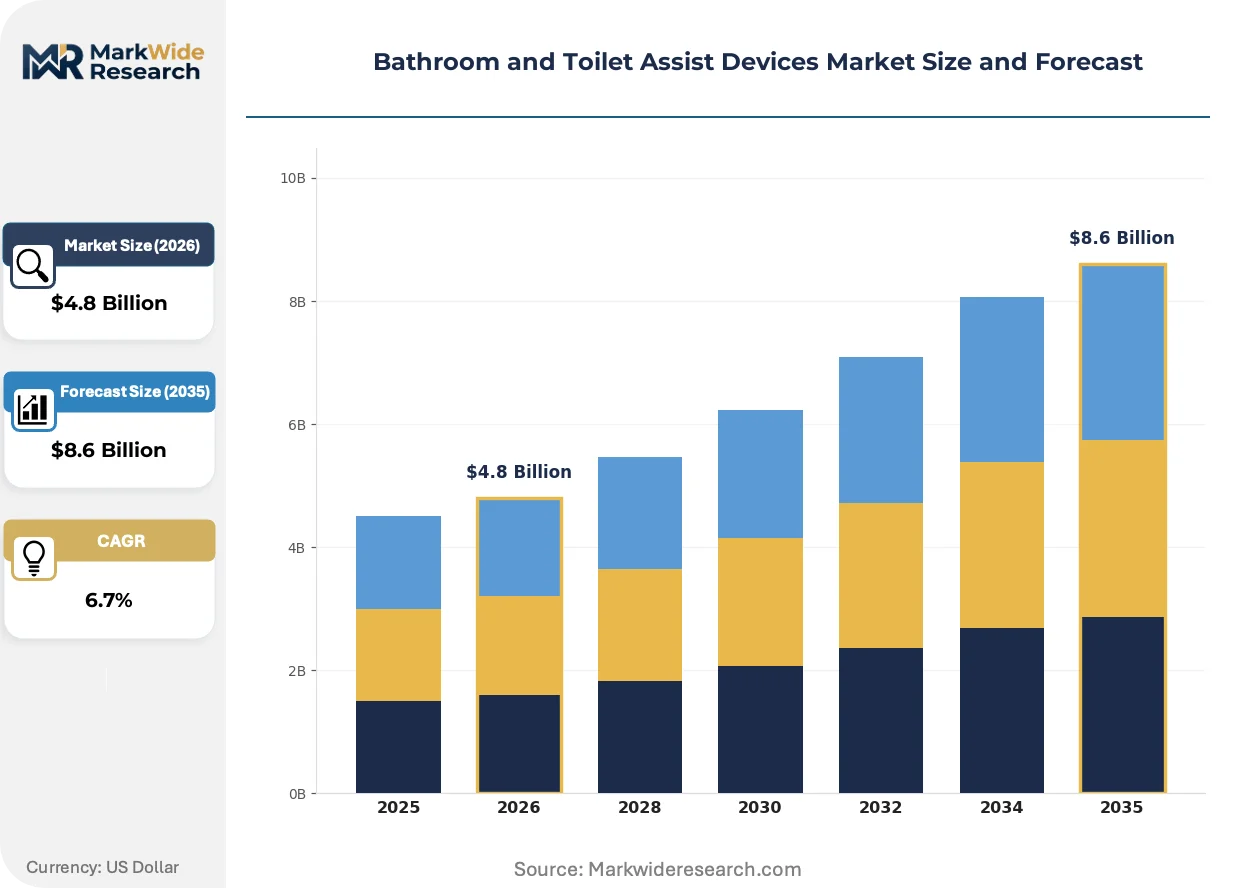
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raised Toilet Seats, Grab Bars, Bidet Attachments, Toilet Frames End User: Senior Citizens, Physically Disabled, Caregivers, Hospitals Technology: Non-Electric, Electric, Smart, Portable Installation Type: Wall-Mounted, Floor-Mounted, Removable, Fixed |
| Companies Covered | Invacare Corporation, Arjo, Etac, Handicare, Bischoff & Bischoff, Performance Health, Sunrise Medical, Prism Medical UK, Drive Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathroom and Toilet Assist Devices Market Strategic Shifts & Innovations
Electrification of mechanical assist functions is fragmenting competitive positioning between established durable medical equipment suppliers and consumer appliance manufacturers entering the hygiene technology space.
Pressure-mapping sensor arrays embedded in toilet seat surfaces detect postural instability and incontinence events in real-time. Home healthcare agencies serving post-stroke rehabilitation patients deploy these units to reduce overnight caregiver staffing ratios. The technology is expanding into remote patient monitoring contracts where reimbursement ties to fall prevention outcomes.
The EU AI Act's risk classification framework reclassifies autonomous hygiene systems with biometric identification capabilities as high-risk AI applications. Manufacturers must implement conformity assessment procedures and maintain post-market logging systems for algorithmic decision trails. Electric bidet segments with user recognition features face 18-24 month compliance recalibration timelines.
Aging-in-place contractors are bundling bathroom retrofit services with long-term maintenance subscriptions, displacing discrete product sales. Home modification specialists in Japan's municipal care networks now specify integrated service contracts covering installation, cleaning protocol training, and annual safety inspections. This consolidation concentrates specification authority with regional contractor consortia rather than individual product vendors.
Bathroom and Toilet Assist Devices Market Segmentation
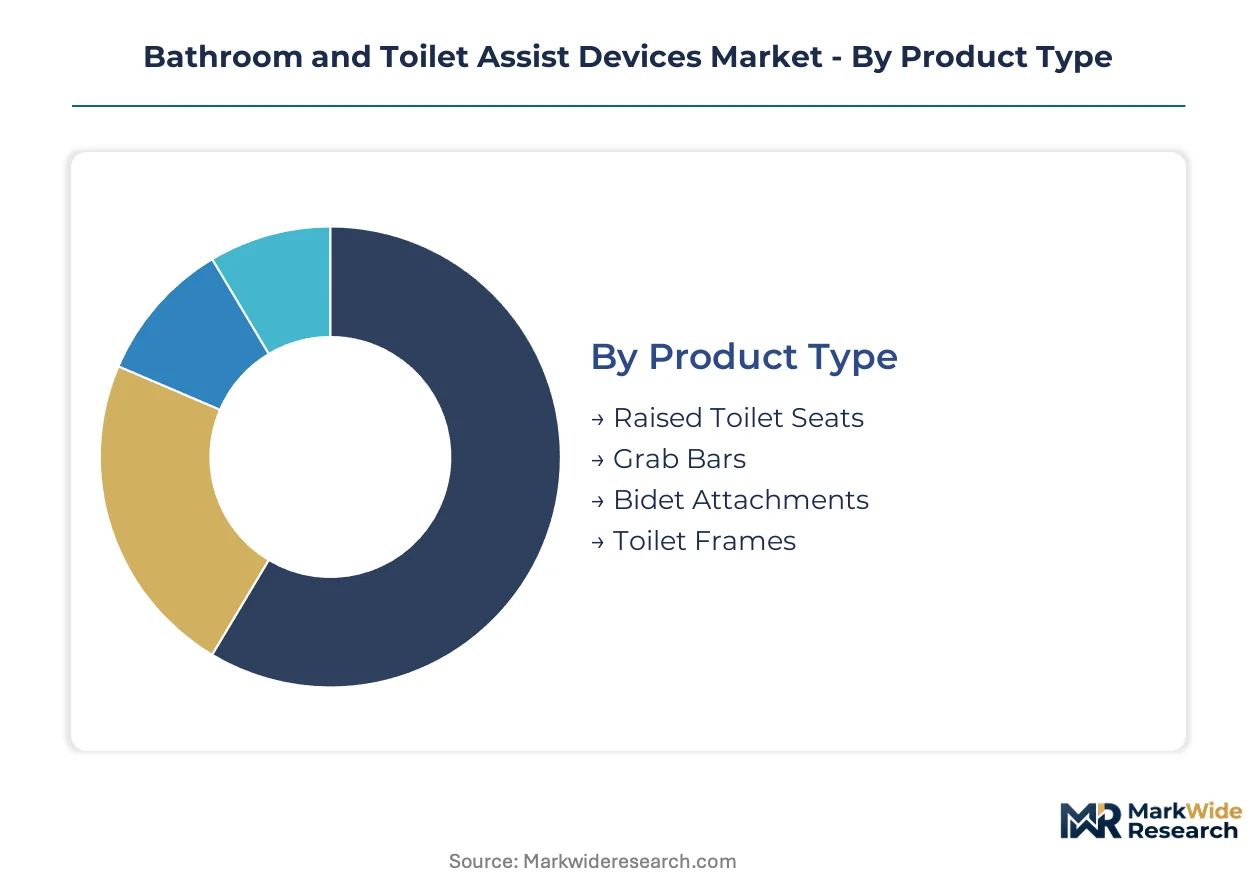
Segmentation in bathroom and toilet assist devices reveals divergent margin structures and procurement pathways. Product maturity varies sharply across mechanical versus electrified categories, while end-user reimbursement eligibility determines pricing power and channel strategy.
Product Type:
Cost tier separates commodity hardware from premium electrified systems with sensor integration.
- Raised Toilet Seats:Polypropylene or molded composite constructions with 50-150mm elevation increments. Demand concentrates in U.S. Medicare Part B reimbursed home healthcare, where durable medical equipment suppliers compete on catalog breadth and prior authorization speed.
- Grab Bars:316L stainless steel or anodized aluminum tubing with concealed flange mounting rated for 113-227 kg pull loads. Japan's municipal LTCI installers specify these in 90% of residential retrofit contracts, driving specification consolidation toward JIS-compliant domestic manufacturers.
- Bidet Attachments:Non-electric mechanical sprayers and premium electric seats with heated water reservoirs.
- Toilet Frames:Freestanding four-legged structures with armrests for lateral transfer assistance.
Volume sits with Grab Bars; growth tilts toward Bidet Attachments.
End User:
Reimbursement eligibility and procurement authority fragment demand across institutional and residential channels.
- Senior Citizens:Independent aging-in-place households purchasing through durable medical equipment retailers or direct-to-consumer channels. Germany's Pflegeversicherung and Japan's LTCI systems now process 70% of claims through certified regional contractors rather than product vendors.
- Physically Disabled:Post-surgical rehabilitation patients and permanent mobility impairment cases requiring ADA-compliant or equivalent accessibility standards. U.S. Department of Veterans Affairs procurement specifications drive volume for bariatric-rated fixtures exceeding 180 kg capacity.
- Caregivers:Family members and paid home health aides seeking reduced physical strain during patient transfers.
- Hospitals:Acute care and long-term care facilities with infection control protocols and centralized purchasing.
Procurement authority concentrates with Hospitals; patient-directed purchasing expands fastest among Senior Citizens.
Technology:
Electrification intensity determines regulatory pathway complexity and service revenue attach rates.
- Non-Electric:Purely mechanical assist functions requiring no electrical supply or software components. These products bypass FDA 510(k) requirements and EU MDR technical documentation, enabling 6-12 month faster commercialization timelines.
- Electric:Motorized seat lifts, heated surfaces, and automated positioning systems. FDA Class II clearance and EU CE marking under MDR impose clinical evaluation requirements that delay market entry by 12-18 months.
- Smart:Sensor-equipped units with pressure mapping, fall detection, and connectivity to remote monitoring platforms.
- Portable:Collapsible or clamp-mounted designs for temporary installation in rental properties and travel use.
Shipment volume favors Non-Electric; value expansion concentrates in Smart systems.
Installation Type:
Permanence of mounting determines addressable building stock and contractor specialization requirements.
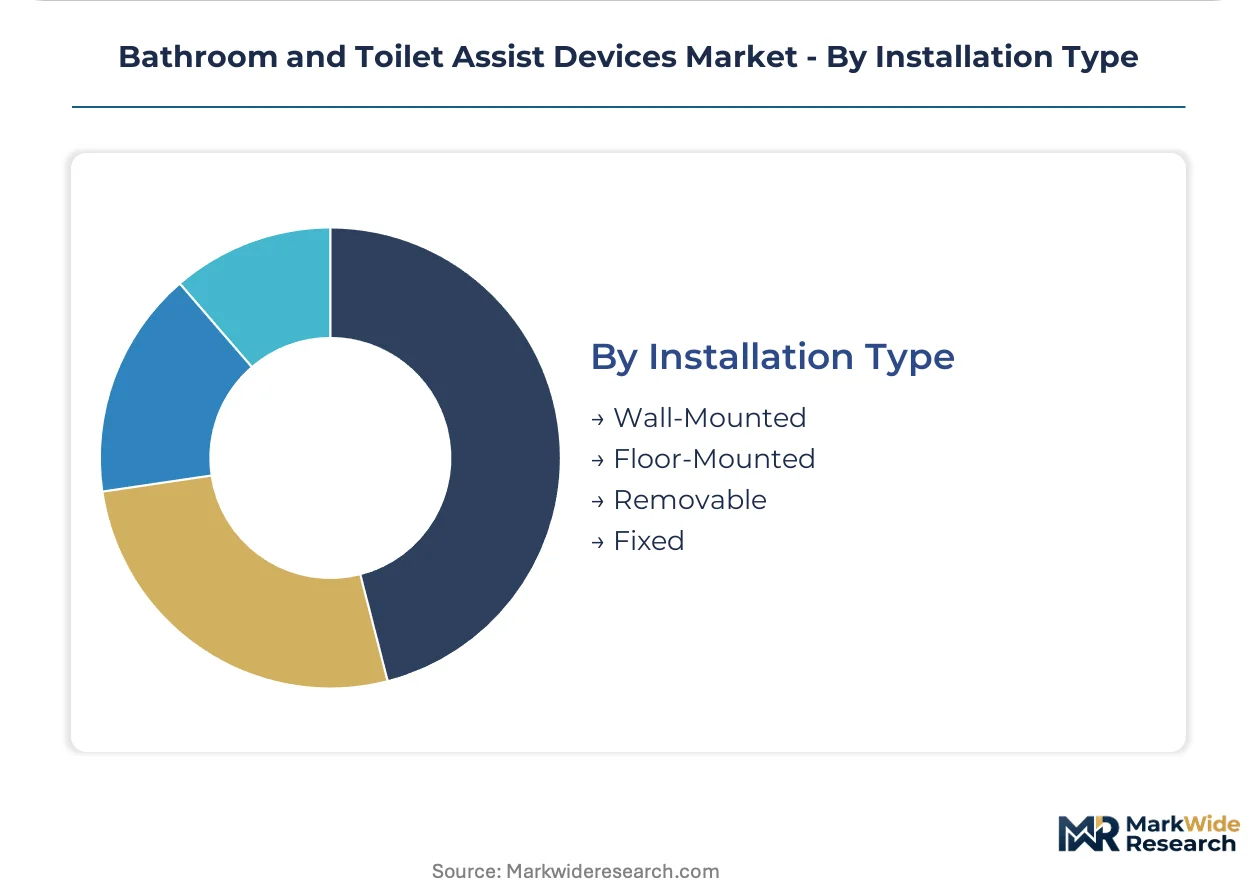
- Wall-Mounted:Concealed or exposed flange anchors requiring structural stud location and load-rated fasteners. These installations dominate new construction and full-gut renovations where framing access permits proper blocking.
- Floor-Mounted:Freestanding frames with anti-tip bases for situations where wall structure cannot support cantilevered loads. Pre-1980s residential buildings with non-standard stud spacing drive substitution toward this category.
- Removable:Suction-cup, clamp, or pressure-fit designs requiring no drilling or permanent modification.
- Fixed:Permanent mechanical or welded connections integrated during initial construction.
Installed base concentrates in Fixed mounting; retrofit flexibility expands fastest through Removable formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's municipal long-term care insurance zones concentrate demand acceleration, while Germany's Pflegeversicherung contracting networks and India's PLI medical device corridors reshape procurement geography across three continents.
United States
The Department of Veterans Affairs procures bariatric-rated fixtures exceeding 180 kg capacity for post-service rehabilitation facilities. FDA Class II 510(k) clearance requirements for powered seat lifts create 12-18 month regulatory lead times that domestic distributors navigate through prior authorization specialization. The Southeast corridor from Florida to Georgia anchors aging-in-place contractor density, where Medicare Part B reimbursement drives durable medical equipment retail consolidation.
Germany
Pflegeversicherung now processes 70% of claims through certified regional contractors rather than direct product vendors, shifting specification authority. The EU Medical Device Regulation mandates post-market surveillance studies that delay CE-marked electric assist launches. North Rhine-Westphalia's industrial rehabilitation cluster concentrates engineering talent for pressure-care surface integration with sanitation systems.
Japan
Super-aged municipalities under METI coordination cover 70-90% of installation costs through LTCI subsidies, unlocking household-level demand previously suppressed by institutional procurement. JIS-compliant domestic manufacturers dominate grab bar specification in 90% of residential retrofit contracts. The Kansai region around Osaka anchors municipal care network contractor consortia that bundle installation with maintenance subscriptions.
India
The PLI scheme for Class B and C medical devices reduces import dependency for electric assist mechanisms and enables price-competitive regional distribution. CDSCO medical device rules impose quality management system requirements that domestic manufacturers address through notified body partnerships. Maharashtra's medical device manufacturing corridor near Mumbai attracts component suppliers for corrosion-resistant aluminum framing systems.
United Kingdom
NHS continuing healthcare budgets contract for residential bathroom modifications, redirecting demand toward local authority means-tested programs. The Care Quality Commission inspects home modification services for safety protocol adherence, influencing contractor selection criteria. The Southeast England cluster around London concentrates occupational therapist networks that specify integrated retrofit workflows over discrete product procurement.
Bathroom and Toilet Assist Devices Market Key Industry Players
Top-tier vendors anchor premium electrified segments, while mid-tier fabricators compete on catalog breadth and prior authorization speed in reimbursed mechanical categories. The vendor base stratifies across durable medical equipment specialists, Scandinavian universal design integrators, and consumer appliance entrants into hygiene technology. Two strategic archetypes dominate: rehabilitation-focused engineering houses with pressure-care expertise, and distribution-heavy suppliers controlling Medicare reimbursement channels. Competitive moves concentrate on backward integration into aluminum extrusion and captive supply of corrosion-resistant surface treatments, alongside geographic expansion through municipal contractor network certification.
Among North American distribution-heavy suppliers, Invacare Corporation and Drive Medical exemplify the Medicare Part B channel control archetype. Arjo and Etac occupy positions within the European engineering-specialist tier, with the former representing bariatric and pressure-care engineering concentration and the latter anchoring modular Scandinavian-designed system integration. Handicare and Prism Medical UK sit within the British Isles contractor-network certification cluster, while Bischoff & Bischoff and Sunrise Medical represent continental European and North American durable medical equipment diversification patterns respectively. Performance Health rounds the named set as a catalog-broad supplier competing on prior authorization infrastructure rather than product specialization.
| Leading Market Players |
|---|
| Invacare Corporation |
| Arjo |
| Etac |
| Handicare |
| Bischoff & Bischoff |
| Performance Health |
| Sunrise Medical |
| Prism Medical UK |
| Drive Medical |
| Others |
Cost & Logistics Intelligence
Municipal long-term care insurance programs in Japan anchor procurement volume and impose contract-based pricing discipline on suppliers seeking certified installer network access. This buyer concentration forces manufacturers to absorb installation cost subsidies through volume commitments rather than premium pricing.
Pricing Analysis
Short lead-time premiums of 15-25% apply to electric assist units requiring FDA 510(k) clearance or EU MDR CE marking, where regulatory delays create spot scarcity. Pricing stratifies across premium smart sensor systems, standard electric seat lifts, and economy mechanical grab bars. Cost compression in stainless steel-framed commodity hardware stems from Asian mill pricing volatility. Hospital procurement committees exhibit lowest price sensitivity due to infection-control specification rigidity, while aging-in-place households through Medicare Part B channels show highest sensitivity to out-of-pocket cost exposure.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for Class B and C medical devices are redirecting electric mechanism sourcing from Chinese suppliers toward Maharashtra-based manufacturers. Medical-grade 316L stainless steel draws from Japanese and South Korean specialty mills, while corrosion-resistant aluminum extrusion rests on Taiwanese surface treatment capabilities. Single-source vulnerability concentrates in sensor chip supply for pressure-mapping arrays. Distribution runs through durable medical equipment suppliers controlling Medicare prior authorization infrastructure, with municipal contractor consortia in Japan and Germany gaining specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EU MDR compliance timelines and FDA software-as-medical-device guidance raise capital barriers, eliminating undercapitalized fabricators unable to fund 18-24 month certification cycles.
For Market Incumbents: To counter modular Scandinavian universal design systems displacing discrete assist device budgets, deepen backward integration into aluminum extrusion and captive corrosion-resistant surface treatment capacity. Prioritize certification investment in FDA 510(k) software-as-medical-device pathways for AI-equipped fall detection systems to lock out appliance manufacturer entrants. For New Entrants and Emerging Players: Launch via portable and removable installation formats targeting rental property managers and temporary recovery space channels underserved by permanent fixture specialists. India's PLI-subsidized manufacturing corridor offers the most penetrable production geography for price-competitive regional distribution. Prioritize direct-to-consumer digital channels bypassing durable medical equipment prior authorization bottlenecks. For Investors and Strategic Acquirers: The window for entry favors engineering-specialist targets with pressure-care surface integration capabilities and existing municipal contractor network certification. Long-term viability hinges on reimbursement strategy sophistication across Japan's LTCI, Germany's Pflegeversicherung, and U.S. Medicare Part B. Monitor FDA digital health guidance finalization as the critical inflection signal for sensor-equipped system valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | Secures priority positioning in Japan's municipal LTCI certified installer networks. |
| Backward Integration into Aluminum Extrusion | Captures margin pool from corrosion-resistant framing supply constrained by Asian mill concentration. |
| Software-as-Medical-Device FDA Submission | Accelerates clearance timelines for AI-driven fall risk assessment sensor systems. |
| Municipal Contractor Network Certification | Unlocks Germany's Pflegeversicherung and Japan's METI-coordinated installation subsidy flows. |
| Portable Product Line Expansion | Accesses rental property retrofit budgets previously unreachable through permanent installation channels. |
Research Approach
Regulatory filings with FDA 510(k) databases, EU MDR notified body documentation, and Japan's LTCI municipal subsidy records formed the secondary backbone. Primary interviews with biomedical engineers specifying hospital infection-control protocols, durable medical equipment procurement managers navigating Medicare Part B prior authorization, municipal long-term care insurance administrators in Japan's super-aged municipalities, and aging-in-place contractors bundling retrofit services validated demand assumptions. Customs data on medical-grade 316L stainless steel and aluminum extrusion trade flows supplemented bottom-up manufacturer shipment analysis, with top-down triangulation against reimbursement claims data.
Historical trendline analysis of product category shifts from mechanical to electrified and smart systems informed penetration curve modeling across the projection horizon. Segmentation dimensions included product type maturity tiers, end-user reimbursement eligibility clusters, technology electrification intensity, and installation permanence categories. CAGRs derived from regression analysis against demographic aging trajectories and municipal subsidy expansion schedules. Industry-specific inputs incorporated FDA digital health guidance evolution and EU AI Act risk classification implementation timelines for biometric-enabled hygiene systems.
The model assumes a particular technology adoption path; alternative pathways for sensor-equipped remote patient monitoring reimbursement would alter the outlook. Forecasts reflect assumptions regarding LTCI municipal subsidy continuation, stainless steel input price stabilization, and MDR post-market surveillance study completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Female Pelvic Implants Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Cyberknife Technology Market
Medical Devices
IOL Delivery Systems Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Laryngoscopes Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Capsulorhexis Forceps Market