
 Stem Cell Characterization Kits Market | 2026-2036
Stem Cell Characterization Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Stem Cell Characterization Kits Market Analytics
Trained cell biologists with expertise in pluripotency marker analysis is collapsing across academic and commercial labs, creating a bottleneck that automated characterization kits are designed to address. Thermo Fisher Scientific leverages its global distribution network to place integrated workflow solutions in major research clusters. STEMCELL Technologies specializes in serum-free media and complementary characterization reagents, anchoring its position in the pluripotent stem cell niche. Miltenyi Biotec controls the magnetic cell separation channel, extending its reach into downstream characterization protocols.
Stem cell characterization kits comprise reagent-based systems for identifying surface markers, genetic signatures, and functional properties that define stem cell identity and differentiation state, typically incorporating fluorescently labeled antibodies, PCR primers, or viability dyes standardized against reference cell lines. Their primary commercial purpose is to replace labor-intensive manual assays with reproducible, scalable protocols that reduce inter-laboratory variability in stem cell quality assessment. Flow cytometry kits capture the largest revenue share among product types due to their entrenched role in immunophenotyping workflows, while imaging systems represent the fastest-expanding category as labs adopt high-content screening for morphological validation. Research laboratories dominate application demand, though regenerative medicine is narrowing the gap as cell therapy developers build in-house quality control capabilities.
The FDA's guidance on Chemistry, Manufacturing, and Controls for cell therapy products shapes kit specifications by mandating traceable, validated reagent lots for IND submissions. EMA's Advanced Therapy Medicinal Products framework and Japan's PMDA regenerative medicine regulations create parallel compliance requirements that multi-regional kit suppliers must harmonize. ISO 20399 standards for ancillary materials further constrain raw material sourcing and documentation burdens. Stakeholders must monitor how evolving pharmacopeial monographs for cell therapy ancillary materials reshape competitive requirements for kit validation packages.
Market Dynamics
The collapse of trained cell biologists specializing in pluripotency marker analysis is forcing laboratories to automate characterization workflows, compressing the addressable market toward integrated kit solutions that eliminate manual expertise dependency.
Growth Catalysts
- NIH Regenerative Medicine Funding:Intensified federal research budgets in the United States are expanding laboratory procurement of standardized characterization tools for pluripotency validation.
- Cell Therapy Manufacturing:Commercial-scale production facilities for autologous and allogeneic therapies are building in-house quality control capabilities requiring validated reagent systems.
- Magnetic Cell Separation Integration:Downstream characterization protocols are increasingly coupled with upstream separation workflows, creating bundled demand for complementary reagent kits.
Market Restraints
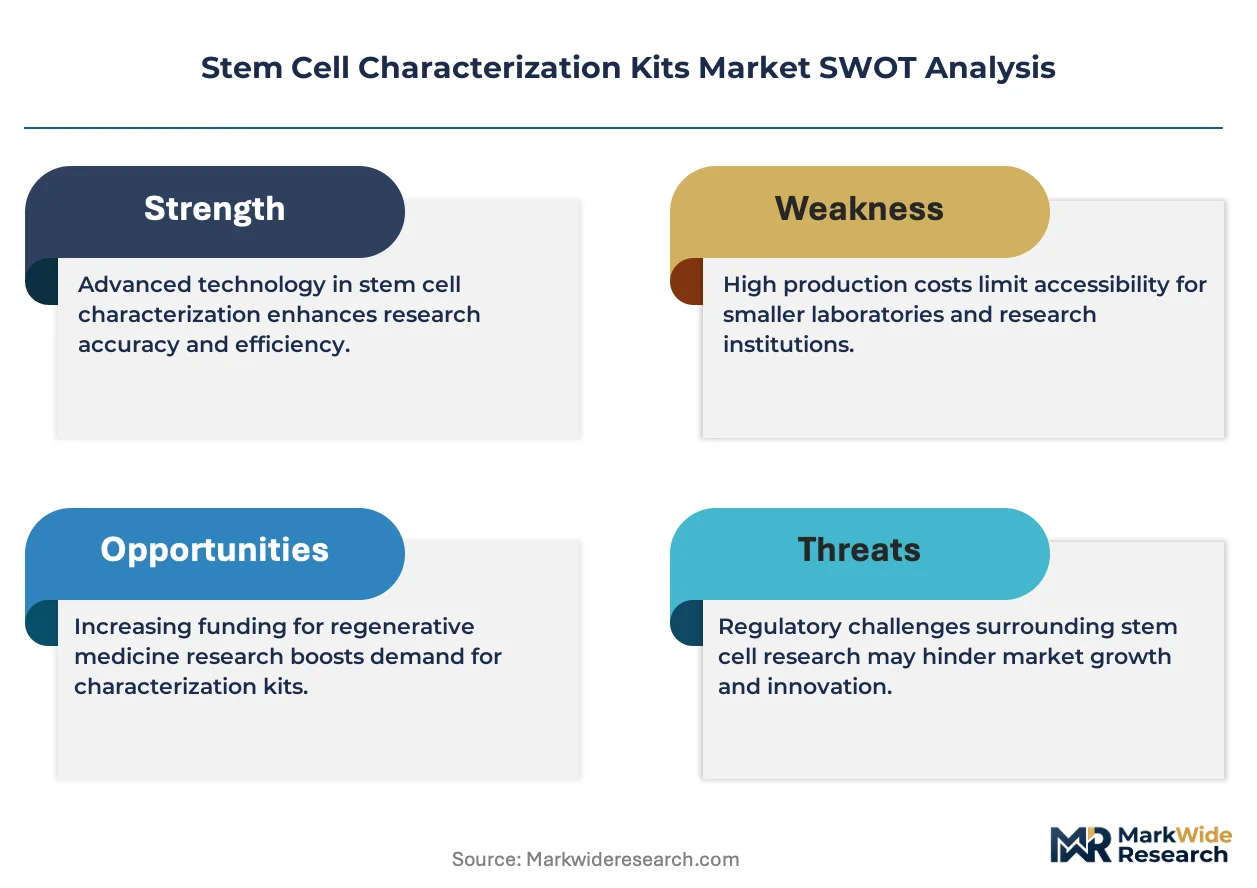
- ISO 20399 Compliance Costs:Ancillary materials standards impose documentation burdens and raw material traceability requirements that inflate kit production overhead.
- Fluorophore Supply Concentration:Specialty dye manufacturing concentrates among limited chemical suppliers, exposing kit producers to input cost volatility and lot-to-lot variability risks.
- Manual Assay Substitution Resistance:Established immunocytochemistry protocols in legacy academic labs resist displacement despite reproducibility advantages of commercial kits.
Strategic Opportunities
- Japan PMDA Regenerative Medicine Pathway:Accelerated approval frameworks for cell therapies are expanding quality control kit demand among Japanese contract development organizations.
- High-Content Imaging Convergence:Morphological validation workflows are integrating artificial intelligence-driven image analysis with traditional marker-based characterization.
- India CDSCO Cell Therapy Guidelines:Emerging regulatory clarity for stem cell products is creating first-mover advantages for kit suppliers establishing localized distribution.
Industry Challenges
- Multiplex Assay Development Talent:Scarcity of assay scientists capable of optimizing antibody panels for simultaneous pluripotency marker detection limits product pipeline velocity.
- Cross-Platform Validation Burden:Kit manufacturers must demonstrate equivalence across flow cytometer instrument models from BD Biosciences, Beckman Coulter, and Sony, fragmenting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stem Cell Characterization Kits Market |
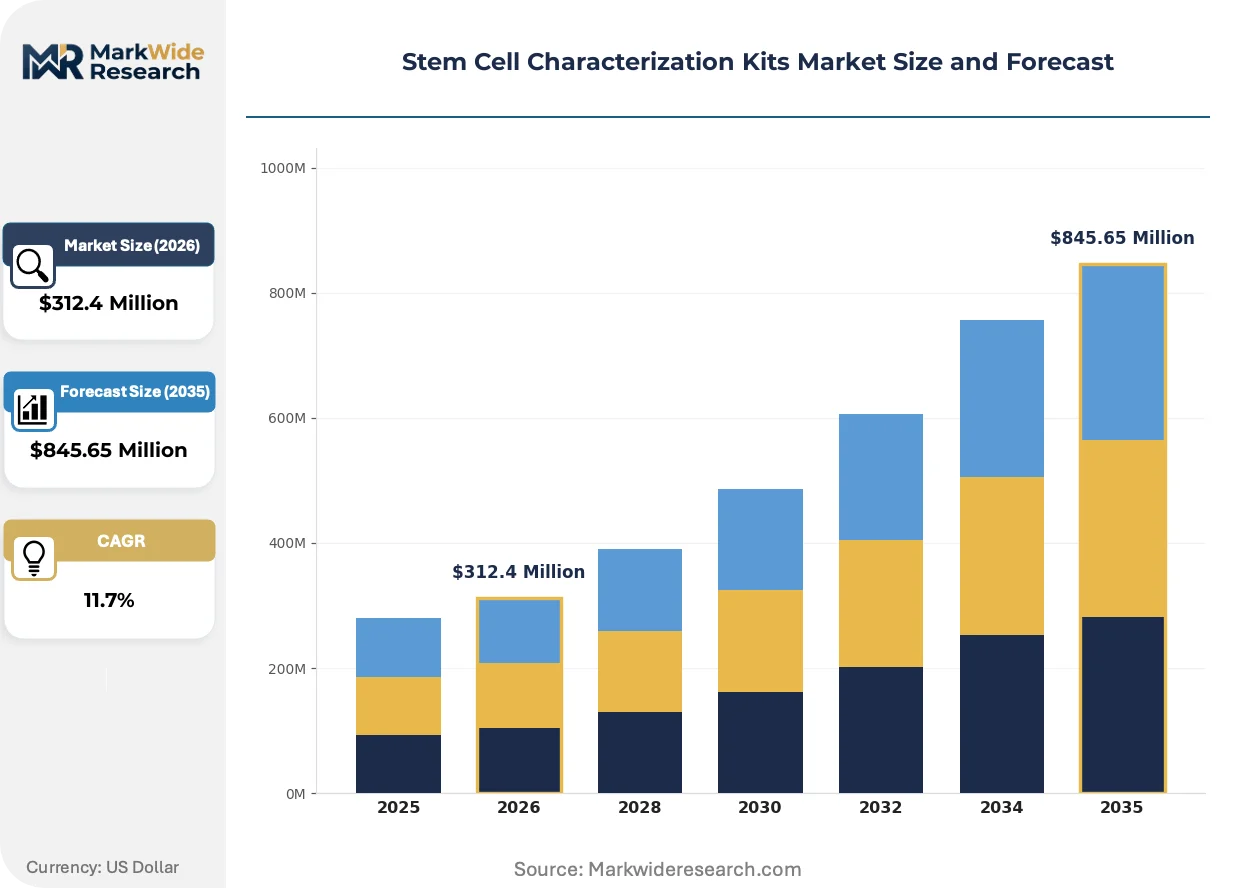
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometry Kits, PCR Kits, Cell Viability Assays, Imaging Systems Application: Research Laboratories, Clinical Diagnostics, Drug Discovery, Regenerative Medicine End User: Academic Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Technology: Microscopy, Proteomics, Genomics, Bioinformatics |
| Companies Covered | Thermo Fisher Scientific Inc., STEMCELL Technologies Inc., Miltenyi Biotec B.V. & Co. KG, Takara Bio Inc., Corning Incorporated, BD Biosciences, Merck KGaA, Bio-Rad Laboratories, REPROCELL Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stem Cell Characterization Kits Market Evolving Landscape
Workflow automation is collapsing the traditional boundary between upstream cell processing and downstream characterization, compressing vendor value propositions toward integrated systems that eliminate manual transfer steps.
High-content screening platforms are decomposing the dominance of flow cytometry in stem cell quality assessment. Cell therapy developers in the United States and Germany are adopting imaging-based morphological validation at three times the pace of academic laboratories. This technology convergence is compressing the market for standalone antibody panels while expanding demand for software-integrated reagent systems.
EMA's Advanced Therapy Medicinal Products framework is tightening Chemistry, Manufacturing, and Controls documentation requirements for IND-equivalent submissions in Europe. Kit suppliers must now provide validated reagent lot traceability packages that satisfy both EMA inspectors and notified body auditors. European contract manufacturers are responding by consolidating vendor relationships toward multi-regional suppliers with harmonized quality systems.
Research laboratories are unbundling after-sales technical support from kit procurement decisions, treating application troubleshooting as an internal competency rather than a supplier obligation. This behavioral shift is compressing pricing premiums for premium-tier characterization products in the United States academic segment. Demand is rotating toward economy-tier reagent systems with streamlined documentation, particularly at state-funded universities facing budget constraints.
Stem Cell Characterization Kits Market Segmentation
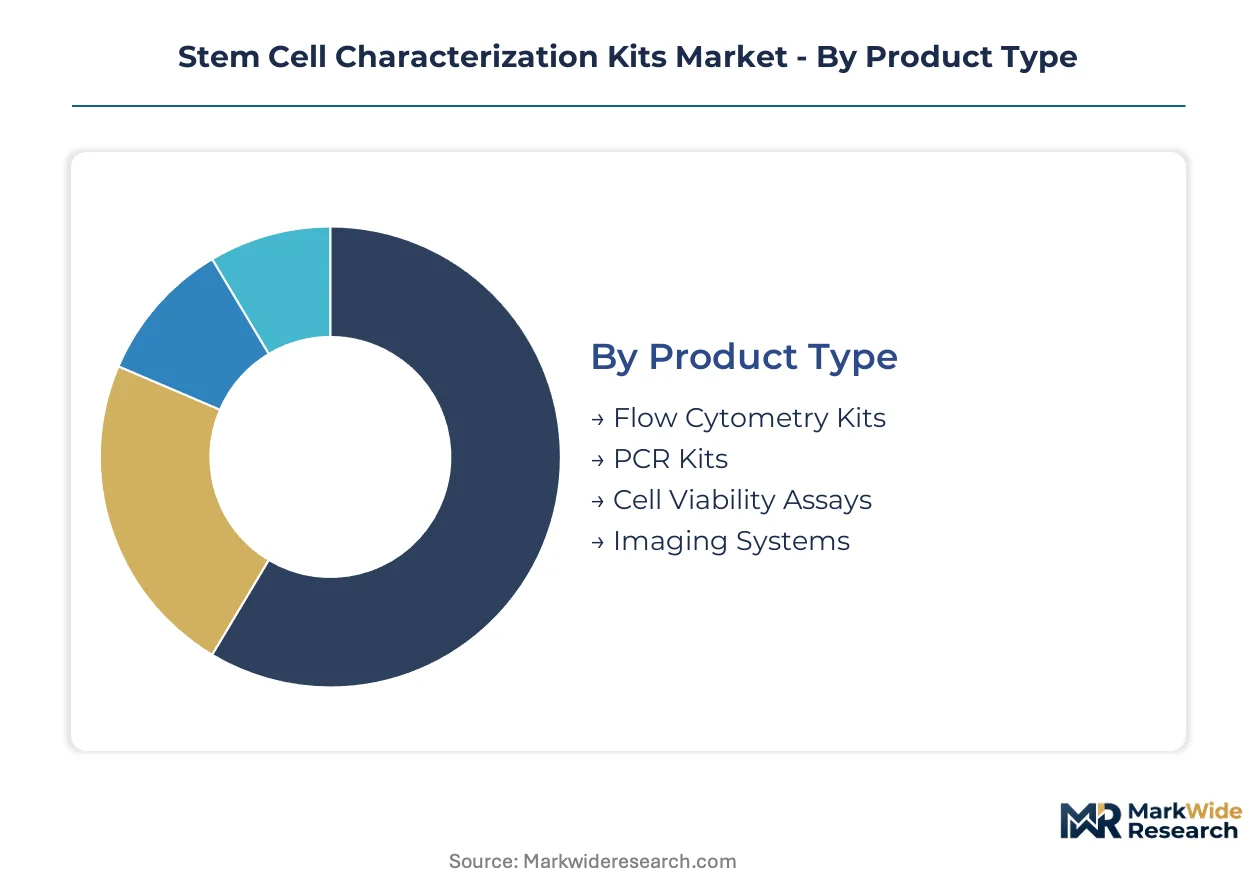
Segmentation in stem cell characterization kits reflects divergent compliance burdens across product categories and end-use settings. Regulatory stringency varies sharply between research-grade and clinical-grade applications, fragmenting vendor strategies and pricing architectures.
Product Type:
FDA Chemistry, Manufacturing, and Controls guidance distinguishes kit categories by validation depth required for IND submissions versus exploratory research use.
- Flow Cytometry Kits:Antibody panels targeting CD markers, SSEA antigens, and transcription factors for pluripotency immunophenotyping. United States academic medical centers concentrate procurement for NIH-funded regenerative medicine workflows, though lot-to-lot variability in fluorophore supply chains constrains standardization.
- Imaging Systems:High-content screening platforms integrating morphological analysis with AI-driven colony classification. German cell therapy developers adopt these systems three times faster than academic laboratories, compressing demand for standalone antibody panels while expanding software-integrated reagent bundles.
- PCR Kits:qPCR primer sets for pluripotency gene expression signatures including OCT4, NANOG, and SOX2.
- Cell Viability Assays:Metabolic and membrane integrity dyes for functional quality assessment in manufacturing settings.
Flow cytometry kits handle the majority of throughput; imaging systems are gaining share fastest.
Application:
Cost tier differentiation separates premium-validated clinical products from economy-tier research reagents.
- Research Laboratories:Exploratory pluripotency validation with flexible, non-GMP protocols. State-funded United States universities facing budget constraints rotate procurement toward economy-tier reagent systems with streamlined documentation, unbundling after-sales technical support from purchase decisions.
- Regenerative Medicine:Commercial-scale cell therapy manufacturing requiring traceable, validated reagent lots for regulatory submissions. EMA Advanced Therapy Medicinal Products framework and FDA parallel guidance mandate documentation packages that inflate kit production overhead.
- Clinical Diagnostics:Patient sample testing for stem cell-based therapeutic monitoring.
- Drug Discovery:High-throughput screening for developmental toxicity and efficacy models.
Research laboratories dominate absolute volume; regenerative medicine applications are climbing the fastest on share expansion.
End User:
Customer type determines procurement centralization versus distributed purchasing authority.
- Academic Institutions:Principal investigator-driven purchasing with heterogeneous protocol preferences. Legacy immunocytochemistry expertise in established United States research universities resists displacement by commercial kits despite reproducibility advantages.
- Pharmaceutical Companies:Centralized quality systems demanding multi-regional suppliers with harmonized ISO 20399 documentation. European contract manufacturers consolidate vendor relationships to reduce audit burden.
- Biotechnology Firms:Venture-funded cell therapy developers building in-house quality control capabilities.
- Contract Research Organizations:Service providers requiring flexible kit portfolios across client regulatory pathways.
Academic institutions anchor baseline demand; pharmaceutical companies show the steepest expansion trajectory.
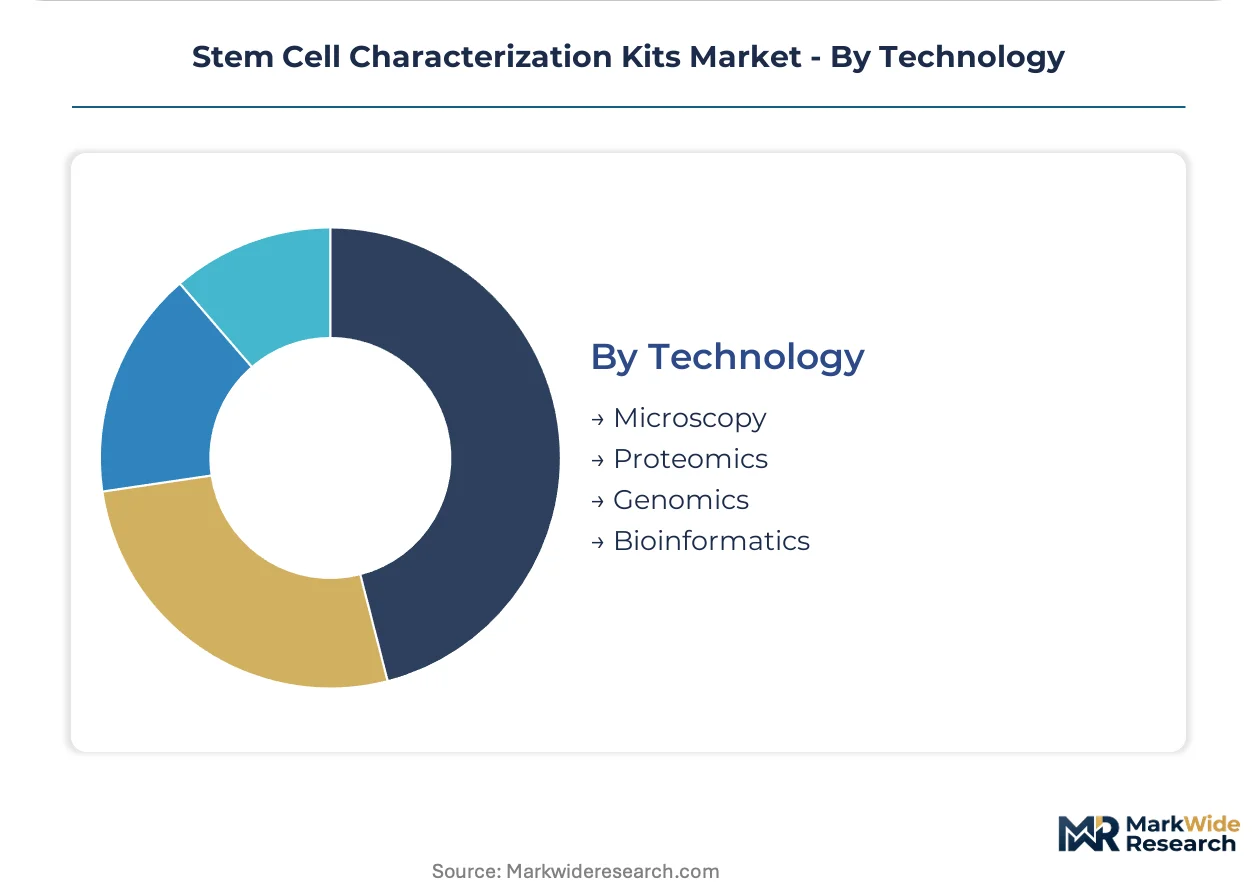
Technology:
Maturity gradients separate established instrumentation from emerging analytical modalities.
- Microscopy:Brightfield and fluorescence imaging for colony morphology assessment. Conventional systems face displacement by high-content platforms integrating automated image analysis.
- Genomics:RNA sequencing and epigenetic profiling for comprehensive identity confirmation. Integration with bioinformatics pipelines accelerates in Japan PMDA-regenerative medicine pathways.
- Proteomics:Mass spectrometry and antibody-based protein quantification for surface marker validation.
- Bioinformatics:Computational pipelines for multi-omics data integration and quality scoring.
Microscopy retains the largest installed base; genomics is expanding most quickly on regulatory validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Chemistry, Manufacturing, and Controls guidance for cell therapy products anchors procurement intensity in the United States, while parallel EMA and PMDA frameworks fragment compliance requirements across developed markets. Academic medical centers and commercial manufacturers concentrate kit demand in specific metropolitan clusters where regenerative medicine infrastructure has matured.
United States
NIH regenerative medicine funding expansion drives laboratory procurement of standardized pluripotency validation tools at academic medical centers. FDA guidance on IND submissions mandates traceable reagent lots, compressing vendor selection toward multi-regional suppliers with harmonized quality systems. The Boston-Cambridge corridor concentrates cell therapy development activity, with Massachusetts General Hospital and Harvard Stem Cell Institute anchoring kit demand for GMP-compliant characterization workflows.
Germany
High-content imaging platform adoption runs three times faster among German cell therapy developers than academic laboratories, shifting demand toward software-integrated reagent bundles. EMA Advanced Therapy Medicinal Products framework tightens documentation requirements for contract manufacturers, consolidating vendor relationships toward suppliers with ISO 20399 compliance. The Heidelberg-Mannheim biotech cluster anchors regenerative medicine manufacturing, with German Cancer Research Center procurement patterns influencing kit specification standards across Central Europe.
Japan
PMDA accelerated approval pathways for regenerative medicine products expand quality control kit demand among contract development organizations. METI funding for induced pluripotent stem cell commercialization compresses timeline pressures on characterization workflow standardization. The Kobe biomedical innovation cluster concentrates cell therapy manufacturing infrastructure, with Riken Center for Biosystems Dynamics Research driving protocol harmonization across Japanese academic-industry partnerships.
United Kingdom
Cell and Gene Therapy Catapult infrastructure investments concentrate manufacturing capability around Stevenage and London, expanding in-house quality control capabilities among emerging biotech firms. MHRA alignment with EMA post-Brexit maintains parallel compliance burdens for multi-regional kit suppliers. The Cambridge-UK biotech corridor anchors pluripotent stem cell research procurement, with Wellcome Trust Sanger Institute spending patterns influencing antibody panel standardization across European academic networks.
India
CDSCO emerging guidelines for stem cell therapy products create first-mover positioning opportunities for kit suppliers establishing localized distribution. Department of Biotechnology funding for regenerative medicine research expands academic laboratory procurement of economy-tier reagent systems. The Hyderabad-Bengaluru pharmaceutical corridor concentrates contract research organization activity, with Centre for Cellular and Molecular Biology procurement driving demand for streamlined documentation products among state-funded institutions.
Stem Cell Characterization Kits Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in stem cell characterization kits, with full-workflow providers commanding premium positioning against modular reagent suppliers. Thermo Fisher Scientific leverages global distribution density to place integrated solutions in major research clusters, while STEMCELL Technologies anchors the pluripotent stem cell niche through serum-free media adjacencies. Miltenyi Biotec extends magnetic separation dominance into downstream characterization protocols. Competitive moves concentrate on strategic partnerships for workflow integration and geographic expansion into emerging regulatory markets.
Within the integrated workflow tier, Thermo Fisher Scientific Inc. occupies a position exemplifying global distribution scale, while STEMCELL Technologies Inc. represents specialization depth in the pluripotent stem cell segment. Miltenyi Biotec B.V. & Co. KG anchors the magnetic cell separation-to-characterization pipeline archetype. These three firms collectively illustrate the competitive tension between breadth and depth strategies, with each representing a distinct path to defensibility in a market where regulatory compliance documentation and application-specific expertise serve as primary differentiation vectors.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| STEMCELL Technologies Inc. |
| Miltenyi Biotec B.V. & Co. KG |
| Takara Bio Inc. |
| Corning Incorporated |
| BD Biosciences |
| Merck KGaA |
| Bio-Rad Laboratories |
| REPROCELL Inc. |
| Others |
Value Network & Pricing Analysis
ISO 20399 ancillary materials standards gate both supplier qualification and price differentiation simultaneously, forcing kit manufacturers to absorb documentation overhead that stratifies offerings across validated clinical-grade and exploratory research-grade tiers.
Pricing Analysis
Long-term offtake agreements dominate procurement between pharmaceutical manufacturers and multi-regional kit suppliers, though academic laboratories transact on spot purchasing with minimal volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated reagent lots with full traceability packages from research-grade antibody panels with streamlined documentation. Cost compression in economy-tier products is intensifying because state-funded United States universities are unbundling after-sales technical support from purchase decisions. Academic principal investigators exhibit the highest price sensitivity, while commercial cell therapy developers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Specialty fluorophore manufacturing concentrates among limited chemical suppliers in Germany, Switzerland, and the United States, exposing kit producers to input cost volatility and single-source vulnerability for critical dye components. Magnetic bead substrates draw from rare earth processing facilities in China, while high-purity antibody production rests on hybridoma cell line repositories concentrated in North America and Europe. Tariff exposure on Chinese-sourced raw materials threatens margin stability for reagent manufacturers without backward integration into captive supply of critical inputs. Distribution runs through authorized distributor networks for academic customers and direct field sales teams for pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as regulatory divergence across FDA, EMA, and PMDA frameworks creates specialized compliance niches that favor focused specialists over broad-line competitors.
For Market Incumbents: Compound defensibility by deepening in-house production of fluorophore conjugates to reduce lot-to-lot variability exposure, while extending magnetic separation dominance into downstream characterization protocols through bundled workflow solutions. The collapse of trained pluripotency assay scientists threatens premium-tier pricing power as customers shift toward economy alternatives. For New Entrants and Emerging Players: Lead with AI-integrated imaging reagent bundles targeting German cell therapy developers, where adoption velocity runs three times faster than academic laboratories and vendor consolidation has not yet matured. India's CDSCO emerging guidelines create first-mover positioning for localized distribution partnerships with Hyderabad-Bengaluru contract research organizations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-content imaging platform development, favoring acquisition of software-integrated reagent specialists over standalone antibody panel manufacturers. Target firms with validated reagent lot traceability systems already harmonized across FDA and EMA submission requirements. Monitor Japan PMDA accelerated approval volume as inflection signal for quality control kit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Workflow Integration Partnership | Thermo Fisher's global distribution density accelerates placement of bundled characterization solutions in Boston-Cambridge research clusters. |
| Regulatory Harmonization Investment | EMA ATMP framework compliance packages reduce audit burden for European contract manufacturers consolidating vendor relationships. |
| AI-Imaging Convergence Development | German cell therapy developers adopt morphological validation platforms three times faster than academic laboratories. |
| Localized Distribution Expansion | India CDSCO guidelines create first-mover positioning for kit suppliers establishing Hyderabad-Bengaluru channel presence. |
| Fluorophore Backward Integration | Captive dye production mitigates lot-to-lot variability risks from concentrated specialty chemical suppliers. |
Research Methodology
Operator-level perspectives from stem cell laboratory directors, regulatory affairs specialists at cell therapy developers, GMP manufacturing quality managers, and academic principal investigators anchored the qualitative base. Primary interview data combined with secondary validation from FDA guidance documents, EMA ATMP framework publications, PMDA regenerative medicine pathway notices, and ISO 20399 standards documentation. Bottom-up reagent demand modeling triangulated against top-down cell therapy manufacturing capacity projections across the analysis window.
Sensitivity analysis tested forecast robustness across alternative regulatory approval velocity scenarios and NIH funding trajectories. Segmentation dimensions modeled include product type, application tier, end-user category, and regional regulatory cluster. CAGRs derived from compound growth trajectory analysis of historical procurement patterns and projected manufacturing capacity buildout. Forecast inputs incorporated cell therapy clinical trial advancement rates and pluripotency validation protocol standardization trends.
Underlying assumptions cover sustained NIH regenerative medicine funding, stable fluorophore supply availability, and progressive regulatory harmonization, with deviation risk concentrated in trade policy shifts affecting Chinese raw material sourcing and unexpected FDA guidance revisions. Practitioners should keep alternative scenarios live as cell therapy commercialization timelines and ancillary materials standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market
Medical Diagnostics
Rapid Medical Diagnostic Kits Market
Medical Diagnostics
Global ELISA Analyzer Market
Medical Diagnostics
Global Histology and Cytology Market
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
X Ray Crystallography Market
Medical Diagnostics
Asia-Pacific Single Cell Analysis Market