
 Medical Bionic Implant Market | 2026-2036
Medical Bionic Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Bionic Implant Market Outlook
Subscription-based remote monitoring and algorithm-driven software updates are restructuring how cardiac and neurostimulation implants create recurring value. Medtronic plc leverages its CareLink network to sustain long-term patient relationships beyond the initial device sale. Boston Scientific Corporation anchors its neuromodulation portfolio with proprietary programming platforms that differentiate post-implant service revenue from hardware margins.
Medical bionic implants are electromechanical systems that replace or augment biological functions through integrated sensors, biocompatible materials such as titanium alloys and platinum-iridium electrodes, and closed-loop feedback circuits powered by inductive charging or primary cell batteries. These devices restore motor, sensory, or cardiac output in patients with irreversible tissue loss or organ failure. Cardiac implants occupy the largest revenue pool due to established reimbursement and repeat intervention rates, while neurostimulation leads growth trajectory as deep-brain and spinal-cord indications expand beyond Parkinson's disease into epilepsy and chronic pain. Prosthetic limbs retain mature volume positions but face margin pressure as 3D-printed socket technology commoditizes lower-extremity hardware.
The FDA's breakthrough device program and the EU MDR clinical evaluation requirements shape product development timelines and evidence-generation budgets for manufacturers seeking dual-market access. Japan's PMDA and Australia's TGA impose additional quality management system audits that filter out early-stage entrants lacking ISO 13485 certification depth. Stakeholders must monitor reimbursement parity between hardware and associated digital services as payers in Germany and France scrutinize remote monitoring fee schedules.
Market Dynamics
The Medical Bionic Implant Market pivots on algorithmic software updates that transform single-sale hardware into recurring revenue streams, forcing manufacturers to restructure R&D budgets toward digital infrastructure and remote monitoring platforms.
Growth Catalysts
- EU MDR Clinical Evidence Pathways:Tighter documentation requirements filter out marginal competitors, concentrating procurement contracts among ISO 13485-certified manufacturers with established post-market surveillance systems.
- Deep-Brain Stimulation Expansion:Epilepsy and obsessive-compulsive disorder indications beyond Parkinson's disease are opening new patient pools in tertiary neurology centers across Japan and Australia.
- Titanium Alloy Supply Concentration:German and Swiss precision forging houses dominate biocompatible metal feedstock, enabling just-in-time production for cardiac lead and cochlear electrode manufacturers.
Market Restraints
- Platinum-Iridium Electrode Cost Volatility:Precious metal price swings compress margins on neurostimulation leads, forcing device makers to hedge through long-term offtake agreements with South African and Russian refiners.
- FDA Breakthrough Device Evidence Burden:Accelerated review timelines demand larger pre-market clinical trials, stretching cash runway for mid-stage developers without established CareLink-scale remote monitoring networks.
- Primary Cell Battery Substitution Pressure:Inductive charging systems threaten to displace non-rechargeable power sources in spinal cord stimulators, obsoleting inventory across legacy implant portfolios.
Strategic Opportunities
- Underpenetrated Chronic Pain Indications:Failed back surgery syndrome patients in Germany and France remain underserved by dorsal root ganglion stimulation, creating white space for targeted physician education programs.
- Convergence of 3D Printing and Socket Scanning:Digital limb prosthetics workflows combining optical measurement with carbon-fiber layup automation are collapsing traditional orthotics channel structures.
- Japan PMDA Priority Review Vouchers:Rare disease device designations offer expedited approval pathways for pediatric cochlear and retinal implant developers willing to front-load clinical investment.
Industry Challenges
- Embedded Firmware Validation Bottlenecks:Closed-loop cardiac resynchronization algorithms require exhaustive electromagnetic interference testing, extending IEC 60601 certification timelines by eight to fourteen months.
- Biocompatibility Testing Capacity Constraints:ISO 10993 cytotoxicity and sensitization studies face backlogs at contract laboratories, delaying first-in-human submissions for novel polymer encapsulation materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Bionic Implant Market |
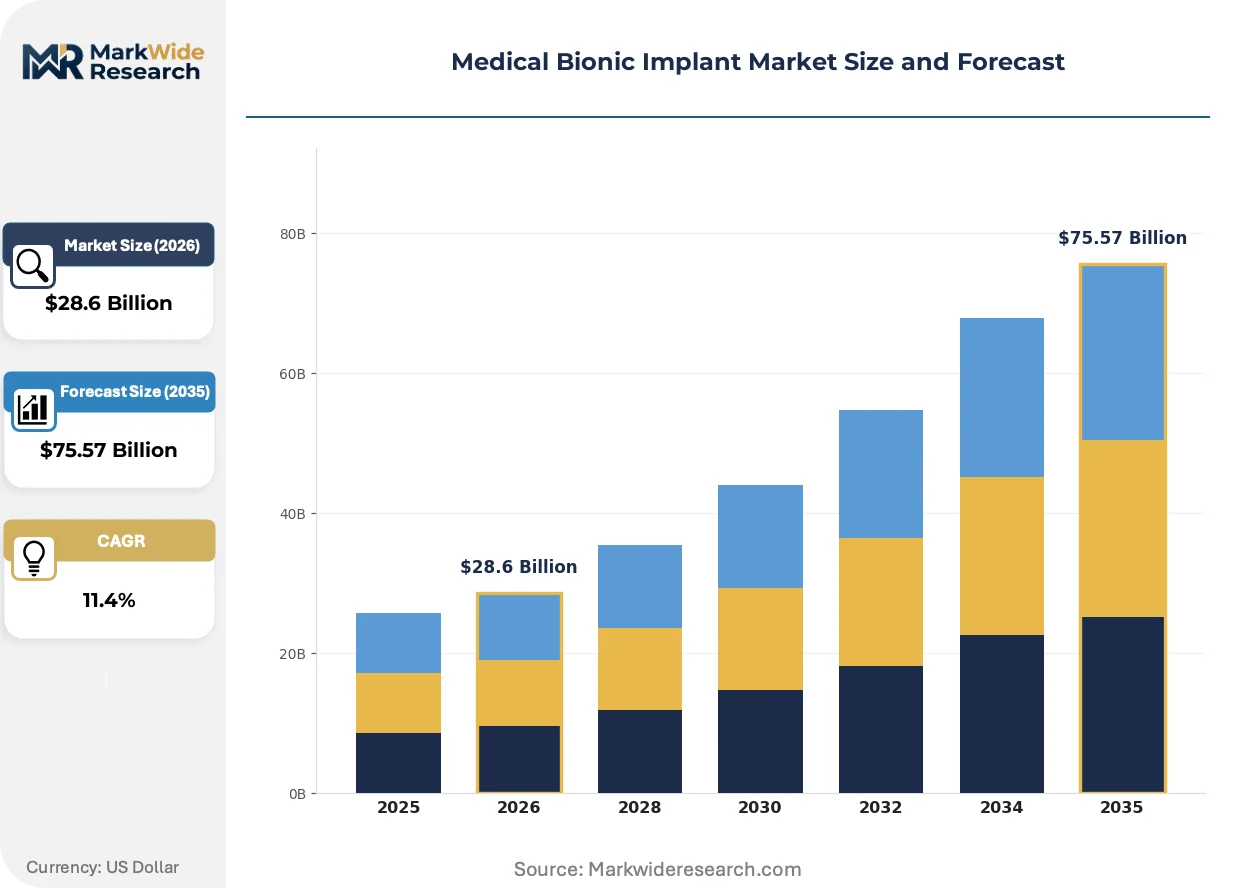
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetic Limbs, Cochlear Implants, Retina Implants, Cardiac Implants Technology: Biomaterials, Electronics, Robotics, Neurostimulation End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Application: Orthopedic, Neurology, Cardiology, Aesthetic Surgery |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Edwards Lifesciences Corporation, Ekso Bionics Holdings Inc., Össur, Ottobock, Cochlear Limited, Abiomed Inc., Zimmer Biomet Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Bionic Implant Market Strategic Shifts
Closed-loop feedback architectures and predictive algorithm suites are displacing open-loop stimulation paradigms, compressing the gap between patient physiological change and therapeutic adjustment while redistributing value capture toward software licensing.
Platinum-iridium electrode arrays with fractal surface geometries are consolidating market share in deep-brain stimulation applications. Major movement disorder centers in Cleveland and Munich have adopted these interfaces for subthalamic nucleus targeting. The technology is consolidating procurement decisions around vendors with proprietary neuronal signal processing libraries, marginalizing hardware-only suppliers.
MDR Article 10 post-market clinical follow-up requirements now mandate systematic device performance tracking across the entire implant lifecycle. Manufacturers must embed data collection infrastructure into routine clinical workflows or risk notified body certificate suspension. Cardiac implant developers with established remote monitoring networks are absorbing compliance costs more efficiently than neuromodulation specialists.
Hospital procurement committees are unbundling hardware acquisition from long-term service contracts, forcing device manufacturers to price remote monitoring and algorithm updates as separate line items. German sickness funds and Australian hospital networks have pioneered this disaggregation, pressuring vendors to demonstrate standalone value for digital subscription revenue.
Medical Bionic Implant Market Segmentation
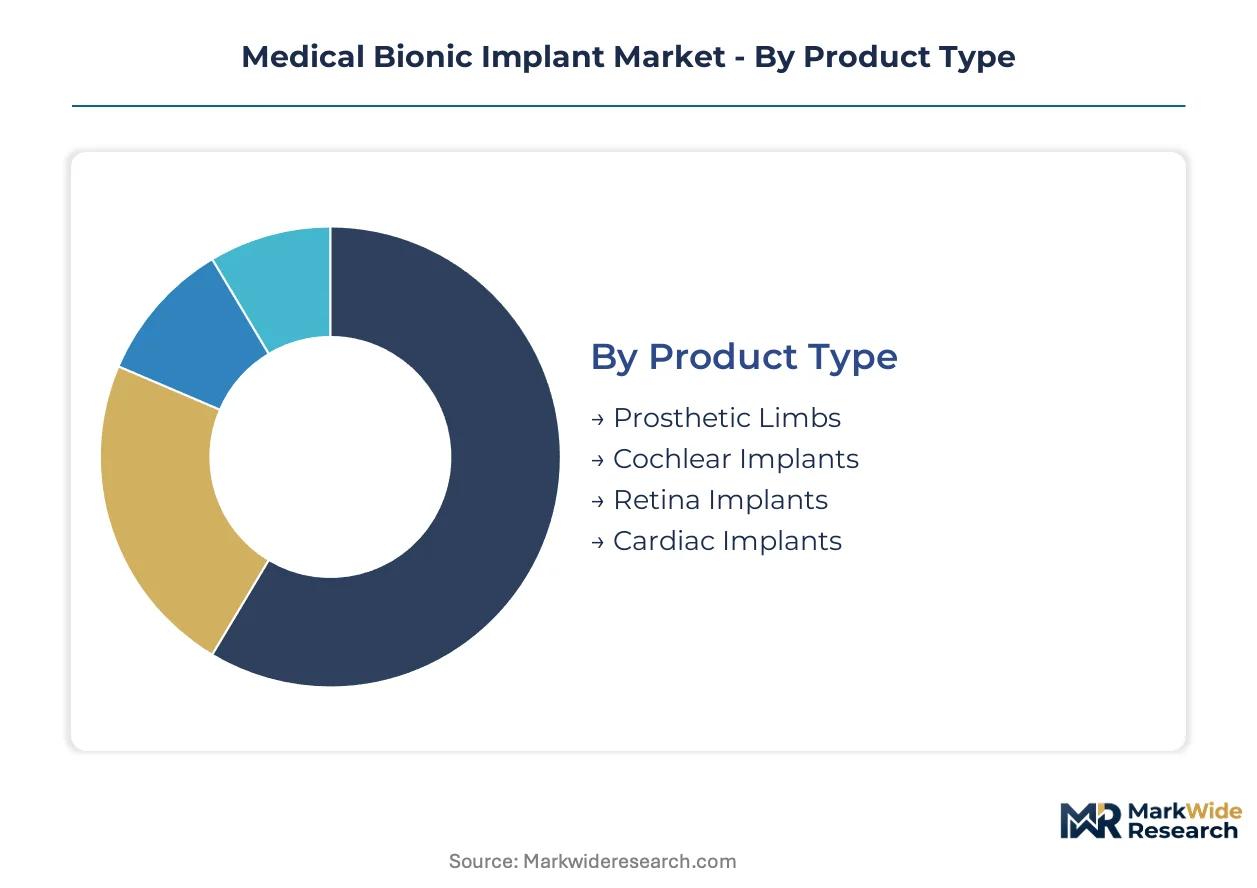
Medical bionic implant segmentation reveals divergent replacement economics across hardware categories. Upgrade cycles for neurostimulation systems outpace cardiac device refresh rates, while prosthetic limb refurbishment patterns track amputation etiology rather than technology obsolescence alone.
Product Type:
Replacement-cycle timing varies dramatically by implant durability and battery architecture, reshaping manufacturer revenue predictability across hardware portfolios.
- Cardiac Implants:Pacemakers and implantable cardioverter-defibrillators incorporate lithium-iodine or lithium-silver vanadium oxide cells with finite 5-7 year lifespans. Demand concentrates in German and United States hospital systems where electrophysiology lab expansion supports generator replacement volumes.
- Cochlear Implants:These devices combine titanium-ceramic housings with platinum electrode arrays and behind-the-ear speech processors. Pediatric fittings in Australian and South Korean cochlear centers drive initial placement growth, while adult upgrades to waterproof external processors sustain aftermarket revenue.
- Prosthetic Limbs:Carbon-fiber composite sockets and myoelectric terminal devices serve traumatic and dysvascular amputations. Volume concentrates in United States veterans affairs facilities and German rehabilitation hospitals with integrated gait analysis laboratories.
- Retina Implants:Epiretinal electrode arrays with inductive power transfer restore limited light perception in retinitis pigmentosa patients. PMDA priority review pathways in Japan accelerate approval timelines for argus-class devices.
Volume placements concentrate in Cardiac Implants; the faster expansion belongs to Cochlear Implants.
Technology:
Cost-tier stratification separates premium closed-loop systems from commodity biomaterial substrates, concentrating R&D investment toward algorithmic differentiation.
- Neurostimulation:Closed-loop deep-brain and spinal-cord stimulators with embedded accelerometers and local field potential sensing enable real-time therapeutic adjustment. Cleveland Clinic and Munich movement disorder centers prioritize these systems for Parkinson's and epilepsy interventions.
- Biomaterials:Titanium alloys, platinum-iridium electrodes, and silicone encapsulants form the structural backbone of implantable hardware. German and Swiss precision forging houses supply feedstock to cardiac lead and cochlear electrode manufacturers.
- Electronics:Application-specific integrated circuits and hermetic feedthrough assemblies manage power delivery and signal processing. FDA electromagnetic compatibility requirements extend certification timelines for novel radiofrequency architectures.
- Robotics:Powered exoskeletons and bionic limb actuators integrate brushless motors with impedance-controlled grasp algorithms. Rehabilitation centers in Japan and Australia pilot these systems for spinal cord injury mobility restoration.
Biomaterials capture the highest shipment volumes; Neurostimulation claims the steepest margin expansion trajectory.
End User:
Customer-type concentration shifts toward outpatient settings as miniaturization and remote monitoring reduce acute-care dependency for implant management.
- Hospitals:Tertiary cardiac and neurology centers perform initial implantation surgeries and device replacement procedures. German sickness funds and Australian hospital networks unbundle hardware procurement from long-term service contracts.
- Rehabilitation Centers:Specialized facilities in Cleveland and Munich provide prosthetic fitting, gait training, and neurostimulation programming. These centers generate recurring revenue through socket replacement and device reprogramming visits.
- Home Care:Remote monitoring platforms and wireless charging systems enable patient-managed maintenance outside clinical settings. Medtronic's CareLink network exemplifies this shift toward distributed care models.
- Clinics:Outpatient electrophysiology and audiology practices handle cochlear processor upgrades and cardiac device interrogations. French and German clinic networks scrutinize remote monitoring fee schedules for reimbursement parity.
Hospitals retain the dominant placement volume; Home Care demonstrates the most rapid adoption acceleration.
Application:
Application-based demand fragmentation reflects divergent clinical evidence requirements and reimbursement maturity across medical specialties.
- Cardiology:Established indications for bradycardia, heart failure, and sudden cardiac death prevention command mature reimbursement codes. Repeat intervention rates for battery depletion sustain replacement volumes.
- Neurology:Deep-brain stimulation for movement disorders and emerging epilepsy indications expand addressable patient pools. PMDA and TGA quality management audits filter out early-stage entrants lacking ISO 13485 certification depth.
- Orthopedic:Limb prosthetics and spinal fusion hardware serve traumatic injury and degenerative disease populations. 3D-printed socket technology commoditizes lower-extremity hardware margins.
- Aesthetic Surgery:Breast reconstruction implants and craniofacial prosthetics address congenital and post-oncologic defects. EU MDR clinical evaluation requirements tighten post-market surveillance obligations for these devices.
Cardiology maintains the largest revenue base; Neurology delivers the fastest-growing application segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic anchors deep-brain stimulation adoption in North America, while Munich movement disorder centers drive European neurostimulation volume. Hospital procurement committees in these metros unbundle hardware from service contracts, reshaping vendor economics across both continents.
United States
Veterans Affairs facilities and tertiary cardiac centers in Cleveland and Boston expand prosthetic and electrophysiology programs as patient candidacy broadens. FDA breakthrough device designations accelerate review timelines while demanding larger pre-market trials. The Cleveland Clinic movement disorder center consolidates procurement around vendors with proprietary neuronal signal processing libraries.
Germany
Sickness funds scrutinize remote monitoring fee schedules, pressuring manufacturers to demonstrate standalone digital subscription value. EU MDR clinical evidence requirements filter out marginal competitors lacking ISO 13485 certification depth. Precision forging houses in Baden-Württemberg supply titanium alloy feedstock to cardiac lead manufacturers on just-in-time contracts.
Japan
PMDA priority review vouchers expedite approval pathways for pediatric cochlear and retinal implant developers willing to front-load clinical investment. Aging populations drive replacement volumes for cardiac implants and cochlear systems. Tokyo and Osaka cochlear centers prioritize waterproof external processor upgrades for adult patients.
Australia
TGA quality management system audits filter out early-stage entrants lacking certification depth, concentrating procurement among established manufacturers. Hospital networks unbundle hardware acquisition from long-term service contracts, following German reimbursement precedents. Sydney and Melbourne rehabilitation centers pilot powered exoskeletons for spinal cord injury mobility restoration.
South Korea
Pediatric cochlear fittings in Seoul and Busan drive initial placement growth as government reimbursement programs expand. MFDS regulatory pathways align with international standards, enabling faster market entry for CE-marked devices. Domestic rehabilitation centers integrate gait analysis laboratories with carbon-fiber prosthetic fitting workflows.
Medical Bionic Implant Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the medical bionic implant landscape. The market structure concentrates around diversified medtech conglomerates with established remote monitoring networks, while mid-stage developers face stretched cash runways from accelerated FDA evidence requirements. Three archetypes dominate: integrated device-service platforms, precision component specialists, and algorithm-driven software licensors. Competitive moves center on M&A to acquire digital infrastructure and strategic partnerships to secure platinum-iridium electrode offtake agreements.
Within the integrated platform tier, Medtronic plc and Boston Scientific Corporation exemplify the shift toward recurring revenue models. Medtronic leverages its CareLink network to sustain patient relationships beyond initial device sales, while Boston Scientific anchors neuromodulation portfolios with proprietary programming platforms. Cochlear Limited occupies a distinct position among hearing restoration specialists, representing the dedicated-device archetype against diversified competitors. These three companies illustrate the strategic divergence between hardware-centric and service-integrated market approaches.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| Ekso Bionics Holdings Inc. |
| Össur |
| Ottobock |
| Cochlear Limited |
| Abiomed Inc. |
| Zimmer Biomet Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
EU MDR sustainability and biocompatibility mandates gate qualified titanium alloy and platinum-iridium electrode supply, restricting premium-tier pricing access to manufacturers with ISO 13485-certified forging partnerships and validated post-market surveillance infrastructure.
Pricing Analysis
Value-based pricing anchored to patient outcome metrics and device longevity governs cardiac and neurostimulation procurement decisions. Three-tier pricing structure across premium closed-loop systems, standard open-loop devices, and economy-grade prosthetic hardware stratifies the market, with algorithmic software subscriptions commanding margin premiums. Cost compression in lower-extremity prosthetics intensifies because 3D-printed socket technology commoditizes carbon-fiber hardware. Rehabilitation centers and German sickness funds exhibit highest price sensitivity, while tertiary cardiac centers prioritize therapeutic efficacy over acquisition cost.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA and South Korea's MFDS frameworks reshape sourcing toward local precision forging and electrode assembly partnerships. German and Swiss titanium alloy feedstock, South African and Russian platinum-iridium refiners, and Taiwanese application-specific integrated circuit foundries anchor upstream supply. Single-source vulnerability concentrates in precious metal electrode arrays, with long-term offtake agreements serving as the primary hedge. Distribution runs through hospital procurement committees and GPO contracts in the United States, direct tender processes in Germany, and centralized government purchasing in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical bionic implant sector sits in a technology-transition phase as closed-loop neurostimulation with embedded accelerometers and local field potential sensing displaces open-loop paradigms across movement disorder and chronic pain indications.
For Market Incumbents: Deploy algorithmic software licensing as the primary lever to differentiate recurring revenue streams from commoditizing hardware margins. Deepen backward integration into platinum-iridium electrode supply through South African refiner partnerships to offset precious metal cost volatility. Accelerate FDA breakthrough device pathway submissions ahead of tightened clinical evidence requirements that threaten to stretch competitor cash runways. For New Entrants and Emerging Players: Algorithm-first dorsal root ganglion stimulation platforms offer a technology-first wedge into underserved failed back surgery syndrome populations in Germany and France. Target pediatric cochlear and retinal implant segments in Japan where PMDA priority review vouchers compress approval timelines for rare disease designations. Pursue hospital system pilot partnerships with integrated remote monitoring capabilities to demonstrate outcome-based value ahead of formal reimbursement negotiations. For Investors and Strategic Acquirers: FDA breakthrough device designation announcements are the leading indicator that mid-stage developers face accelerated evidence burdens requiring CareLink-scale digital infrastructure investments. Five-to-ten year viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. Acquisition targets should display ISO 13485 certification depth, established notified body relationships, and embedded post-market clinical follow-up data collection systems compliant with MDR Article 10 mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct procurement relationships with Cleveland Clinic and Munich movement disorder centers consolidate neurostimulation market access. |
| Software Companion Development | Proprietary programming platforms like Boston Scientific's differentiate post-implant service revenue from terminal device margins. |
| Reimbursement Strategy | Demonstrating remote monitoring parity with hardware fees satisfies German sickness fund scrutiny and unlocks subscription revenue. |
| CE Marking Pathway | EU MDR clinical evidence compliance filters marginal competitors and concentrates procurement among certified manufacturers. |
| Long-term Supply Agreement | Platinum-iridium offtake contracts with South African refiners hedge against electrode cost volatility in neurostimulation leads. |
Study Parameters
Multi-period observation of FDA breakthrough device designations, EU MDR notified body certificate suspensions, and PMDA priority review voucher awards anchored the trend analysis, supplemented by interviews with cardiac electrophysiologists, movement disorder neurologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EUDAMED post-market surveillance databases, Japanese MHLW reimbursement bulletins, and Australian TGA quality audit reports. Bottom-up shipment modeling by implant category triangulated against top-down healthcare expenditure tracking across German sickness funds and United States Medicare claims data.
Segment-weighting approaches distributed value capture across hardware categories, technology tiers, and end-user settings, with replacement-cycle timing and software attachment rates informing revenue predictability assumptions across the projection horizon. Cardiac implant, cochlear system, prosthetic limb, and neurostimulator volumes were modeled against aging population demographics, amputation etiology patterns, and epilepsy indication expansion. CAGRs derived from fitted trend lines incorporating regulatory approval velocity, reimbursement schedule revisions, and raw material cost trajectory inputs.
Several conditions sit outside the modeled scope, including geopolitical disruptions to South African platinum supply, unanticipated FDA guidance revisions on closed-loop algorithm validation, and catastrophic biocompatibility events triggering ISO 10993 protocol changes. Forecasts reflect documented assumptions regarding PMDA and TGA audit intensity, EU MDR implementation consistency, and inductive charging adoption curves in spinal cord stimulation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
Medical Device Coating Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market