
 Global Uterine Manipulation Devices Market | 2026-2036
Global Uterine Manipulation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Uterine Manipulation Devices Market Foresight
Gynecologic surgeon training capacity is collapsing across multiple OECD markets, constraining procedure volume growth and forcing device makers to prioritize automation-ready platforms. CooperSurgical Inc. leverages its integrated fertility-to-surgery portfolio to sustain hospital system relationships. KARL STORZ SE & Co. KG anchors European premium positioning through rigid endoscopy ecosystem control. B. Braun SE competes on disposable kit standardization across ambulatory surgery center networks.
Uterine manipulation devices are mechanical or pneumatic instruments designed to position, elevate, or mobilize the uterus during laparoscopic and open pelvic procedures, typically incorporating atraumatic tips, adjustable curvature shafts, and locking mechanisms to maintain fixed angulation without continuous manual holding. Balloon retractors dominate current revenue pools due to their dual function in tissue displacement and uterine stabilization during complex endometriosis surgery. Winged manipulators represent the fastest-growing product configuration as surgeons seek single-insertion solutions that reduce port-site trauma in multi-quadrant laparoscopy. Deployment patterns increasingly favor single-use kits in North American and Western European facilities seeking to eliminate reprocessing liability and OR turnaround delays.
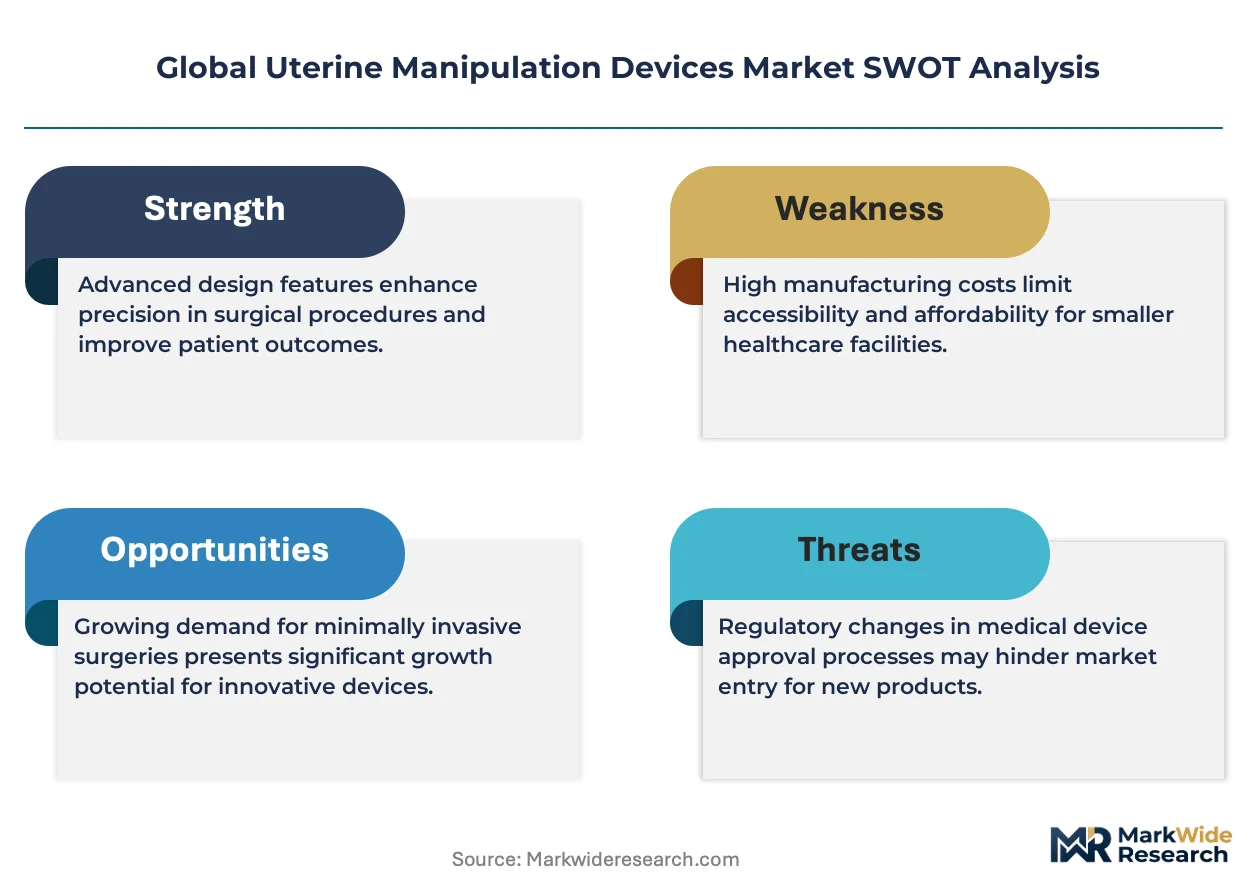
FDA 510(k) clearance requirements and EU MDR technical documentation obligations are extending time-to-market for new uterine manipulator designs, advantaging incumbents with established quality management systems and predicate device libraries. Japan's PMDA and South Korea's MFDS maintain distinct biocompatibility testing protocols that fragment regulatory strategy for Asia-Pacific entry. Stakeholders must monitor evolving sterilization validation standards and surgeon training reimbursement policies as these factors will determine which product formats achieve scalable clinical adoption.
Market Dynamics
Surgeon training pipeline collapse across OECD markets is forcing device manufacturers toward automation-ready platforms that reduce procedural dependency on specialist labor pools.
Growth Catalysts
- EU MDR recertification waves:Incumbent manufacturers with established technical documentation libraries are capturing market share from smaller competitors facing extended compliance timelines.
- Ambulatory surgery center expansion:United States outpatient facilities are driving demand for single-use disposable kits that eliminate reprocessing liability.
- Silicone balloon catheter advances:Dual-function designs integrating tissue retraction with uterine stabilization are expanding addressable procedure volumes in complex endometriosis cases.
Market Restraints
- Specialized polymer supply concentration:Medical-grade silicone sourcing depends on a limited supplier base concentrated in Germany and Japan, creating input cost volatility.
- FDA 510(k) predicate device requirements:Novel manipulator designs without established predicates face 18-24 month clearance timelines that compress first-mover advantages.
- Laparoscopic skill attrition:Declining gynecologic surgery fellowship completion rates in the United States and United Kingdom constrain procedure volume expansion regardless of device availability.
Strategic Opportunities
- South Korea MFDS pathway optimization:Streamlined biocompatibility testing protocols for Class II devices create faster entry for standardized manipulator designs.
- Robotic-assisted hysterectomy convergence:Integration of manipulator devices with da Vinci surgical systems opens premium pricing tiers in academic medical centers.
- India PLI scheme leverage:Domestic manufacturing incentives for medical devices enable cost-competitive production for export to Southeast Asian markets.
Industry Challenges
- Sterilization validation backlog:ISO 17664 documentation requirements for reusable instruments are extending quality assurance cycles and delaying product launches.
- OR integration complexity:New manipulator designs must demonstrate compatibility with existing laparoscopic tower configurations from KARL STORZ and Stryker without workflow disruption.
- Surgeon retraining burden:Novel articulation mechanisms require hands-on proctoring programs that strain manufacturer clinical education budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Uterine Manipulation Devices Market |
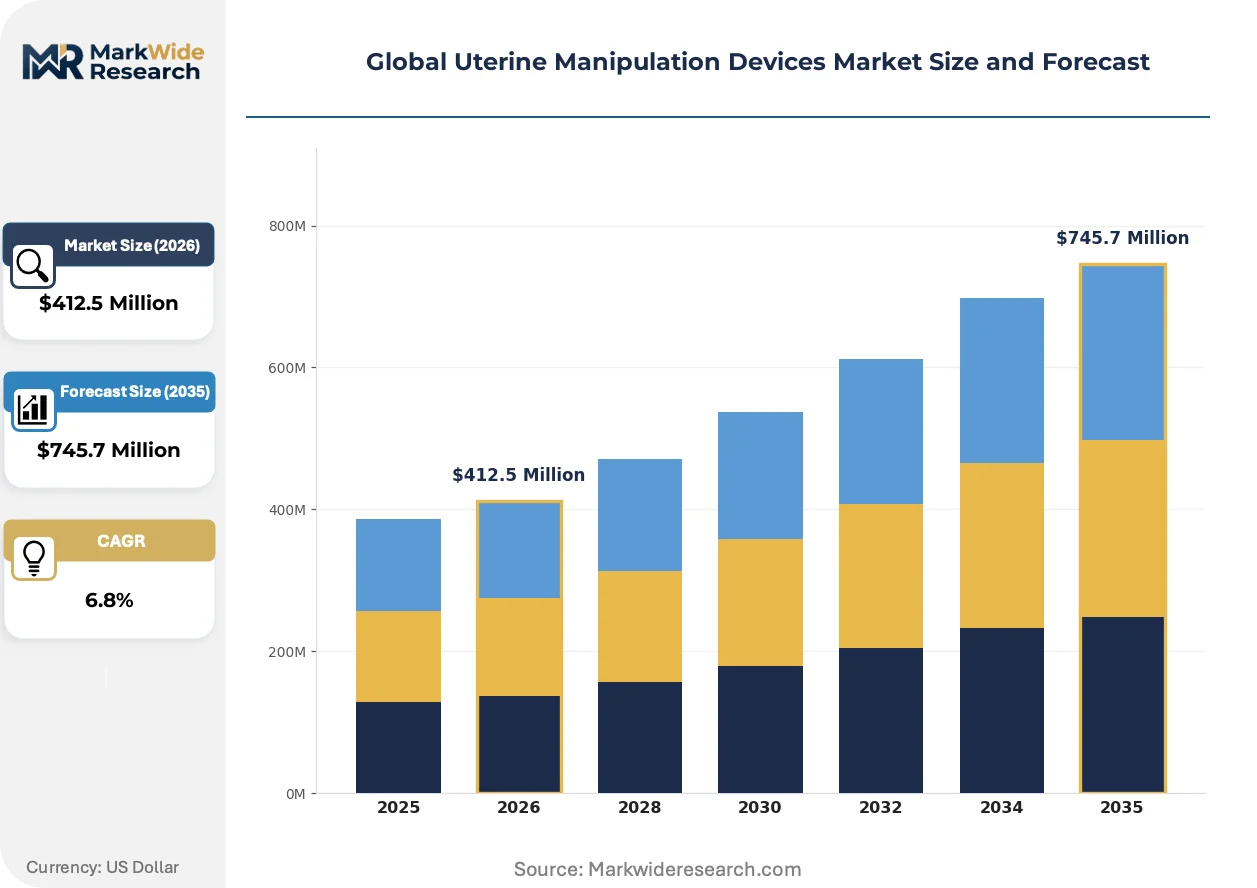
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Retractors, V-Step Manipulators, Screwing Manipulators, Winged Manipulators, Others Application: Gynecologic Surgery, Assisted Reproductive Technology, Laparoscopy, Hysteroscopy, Endometriosis Surgery End User: Hospitals, Specialty Clinics, Fertility Centers, Ambulatory Surgery Centers, Diagnostic Laboratories Deployment: Disposable, Reusable, Manual, Motorized, Single-Use Kits |
| Companies Covered | CooperSurgical Inc., KARL STORZ SE & Co. KG, B. Braun SE, CONMED Corporation, Richard Wolf GmbH, Utah Medical Products, Inc., Conkin Surgical Instrument Ltd., Purple Surgical, Laborie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Uterine Manipulation Devices Market Shifts & Advancements
Winged single-insertion manipulators are capturing preference shifts as surgeons prioritize port-site reduction over traditional multi-instrument approaches in complex pelvic surgery.
Articulating shaft designs with programmable curvature memory are supplanting fixed-angle stainless steel instruments in high-volume laparoscopic hysterectomy programs. Academic medical centers in Germany and Japan are piloting these platforms for multi-quadrant endometriosis resections. The technology is compressing demand for conventional reusable manipulators while expanding the addressable market for premium single-use configurations.
EU MDR Article 10 technical documentation obligations are extending design dossier preparation timelines by 40-60 percent for new uterine manipulator submissions. Manufacturers with legacy device portfolios are prioritizing recertification of proven designs over novel platform development. Smaller European competitors without dedicated regulatory affairs teams are exiting the market, consolidating share among incumbents with established quality management systems.
Hospital procurement departments are unbundling device purchases from bundled payment contracts, creating direct price negotiation leverage previously held by group purchasing organizations. This shift is most visible in United States health systems pursuing Medicare Advantage expansion, where device cost transparency affects per-procedure margin calculations. Manufacturers are responding with tiered pricing structures that separate premium automation-ready platforms from standard mechanical configurations.
Global Uterine Manipulation Devices Market Segmentation
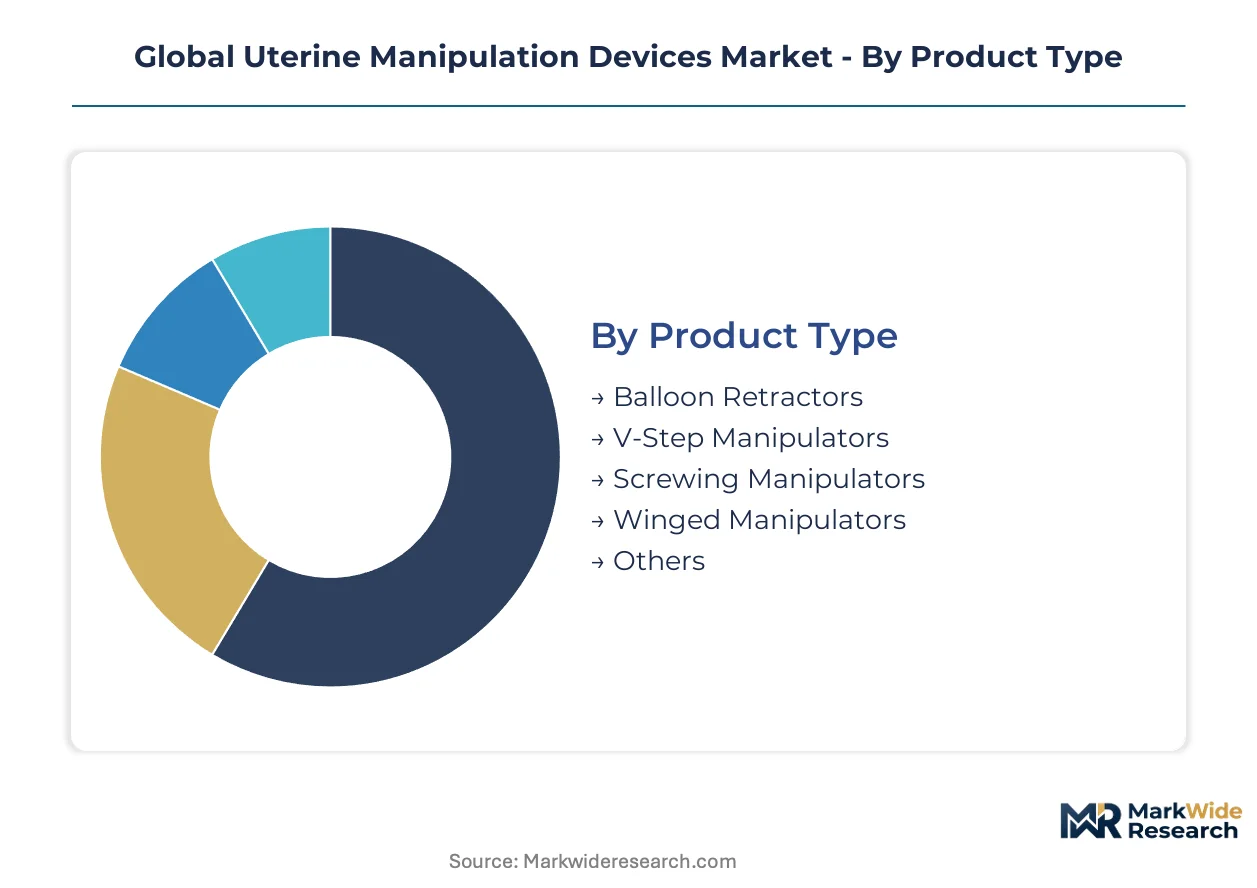
Uterine manipulation devices fragment across four structural dimensions. Product configuration determines clinical utility and pricing power. Deployment mode shapes sterilization liability and procurement economics. Application focus and end-user setting dictate regulatory pathway and sales channel strategy.
Product Type:
Balloon retractors dominate domestic hospital procurement in the United States and Germany. Winged manipulators and V-Step variants drive export-led growth into Japan and South Korea.
- Balloon Retractors:Silicone balloon catheters integrate tissue displacement with uterine stabilization through dual-lumen designs. Demand concentrates in academic medical centers performing complex endometriosis resections, constrained by medical-grade silicone supply concentration in Germany and Japan.
- Winged Manipulators:Single-insertion platforms reduce port-site trauma through integrated atraumatic tips and locking angulation mechanisms. Japanese and South Korean surgeons prioritize these configurations for multi-quadrant laparoscopy, accelerating adoption ahead of EU MDR recertification timelines.
- V-Step Manipulators:Stepwise depth-adjustment shafts enable controlled uterine positioning without instrument exchange.
- Screwing Manipulators:Threaded fixation mechanisms maintain rigid uterine orientation during prolonged hysterectomy procedures.
- Others:Specialized configurations including magnetic guidance adapters and suction-assisted stabilizers address niche procedural requirements.
Balloon retractors command the established base. The steepest expansion runs through winged manipulators.
Application:
Cost tier stratification separates high-complexity surgical applications from diagnostic and fertility procedures. Gynecologic surgery and endometriosis surgery anchor premium pricing. Assisted reproductive technology and hysteroscopy compete on volume economics.
- Gynecologic Surgery:Laparoscopic hysterectomy and myomectomy procedures require adjustable curvature shafts with programmable locking mechanisms. United States hospital systems standardize on automation-ready platforms to offset collapsing fellowship training pipelines.
- Endometriosis Surgery:Multi-quadrant pelvic resections demand dual-function devices combining tissue retraction with uterine mobilization. German academic centers pilot articulating shaft designs with curvature memory, compressing demand for fixed-angle instruments.
- Assisted Reproductive Technology:Embryo transfer procedures utilize low-profile manipulators for cervical canal navigation.
- Laparoscopy:General pelvic laparoscopy applications favor standardized disposable kits across ambulatory surgery center networks.
- Hysteroscopy:Diagnostic and operative hysteroscopy procedures drive volume demand for single-use balloon retractors.
Gynecologic surgery anchors revenue concentration. Endometriosis surgery is climbing the fastest as disease recognition expands addressable procedure volumes.
End User:
Customer type determines procurement authority and contract structure. Hospitals and ambulatory surgery centers negotiate directly with manufacturers. Fertility centers and specialty clinics purchase through distributor networks.
- Hospitals:Integrated delivery networks in the United States and Germany consolidate device purchasing across obstetrics and gynecology service lines. Medicare Advantage expansion drives unbundling of device purchases from bundled payment contracts, creating direct price negotiation leverage.
- Ambulatory Surgery Centers:United States outpatient facilities prioritize single-use disposable kits to eliminate reprocessing liability and OR turnaround delays. Standardized kit configurations from B. Braun SE dominate network procurement.
- Specialty Clinics:Independent gynecologic practices favor reusable instruments with established sterilization protocols.
- Fertility Centers:Assisted reproductive technology clinics require specialized low-profile manipulators for embryo transfer procedures.
- Diagnostic Laboratories:Pathology and diagnostic imaging centers utilize manipulators for specimen retrieval and positioning support.
Hospitals retain procurement volume leadership. Ambulatory surgery centers are gaining share fastest as outpatient hysterectomy migration accelerates.
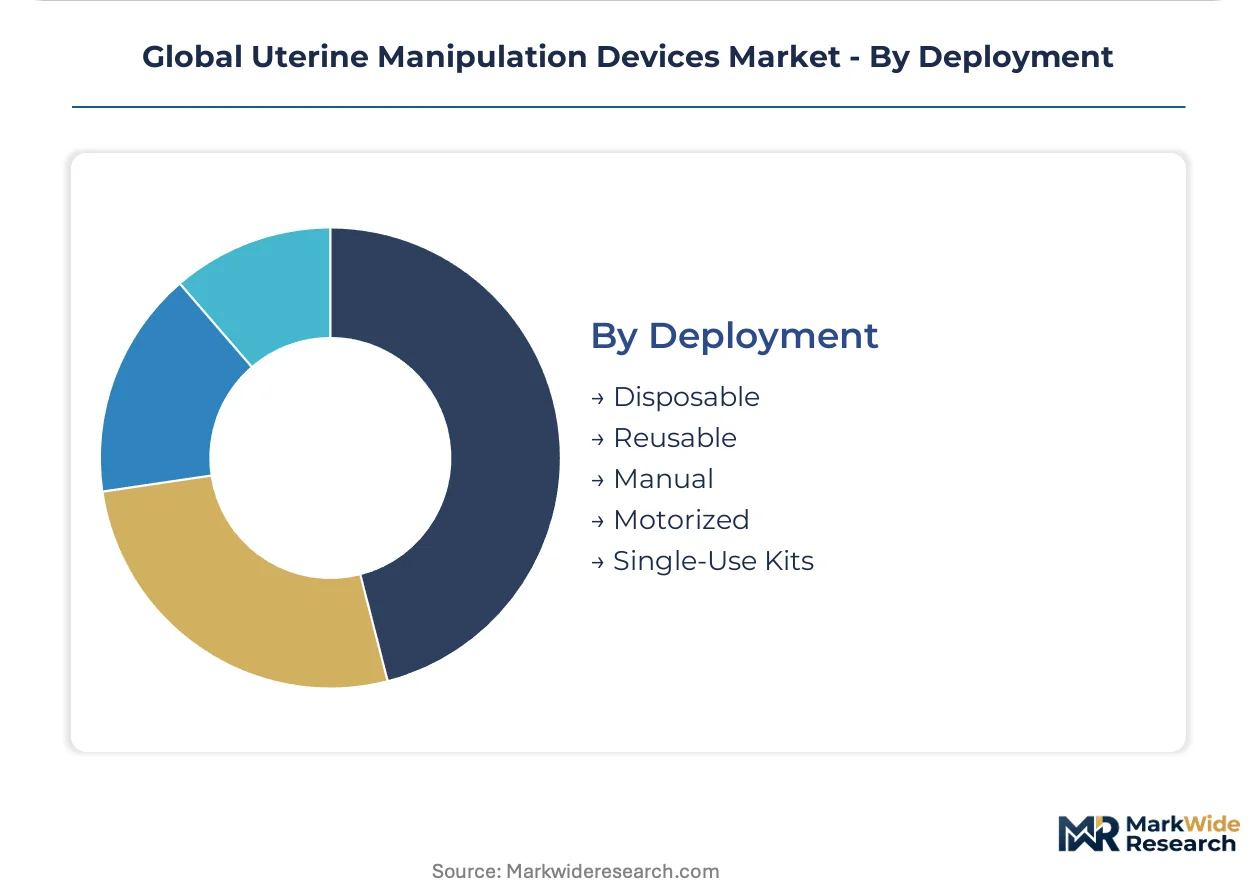
Deployment:
Supply concentration in medical-grade polymers shapes deployment economics. Single-use kits depend on German and Japanese silicone suppliers. Reusable instruments face ISO 17664 documentation backlogs extending quality assurance cycles.
- Disposable:Individual-use devices eliminate cross-contamination risk and reprocessing documentation burden. United States and Western European facilities drive demand concentration, constrained by specialized polymer supply volatility.
- Single-Use Kits:Pre-configured procedure packs integrate manipulators with ancillary instruments and drapes. Ambulatory surgery center expansion in the United States accelerates kit standardization across network facilities.
- Reusable:Stainless steel and polymer instruments with validated sterilization protocols sustain presence in cost-constrained health systems.
- Manual:Hand-operated mechanical manipulators dominate established laparoscopic programs without robotic integration.
- Motorized:Powered articulation platforms enable programmable curvature control for complex multi-quadrant procedures.
Disposable configurations anchor current revenue. Single-use kits are expanding most quickly as procurement departments prioritize OR efficiency over per-unit cost minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor United States market entry, while EU MDR recertification timelines reshape European competitive positioning. Japan's PMDA and South Korea's MFDS maintain distinct protocols that fragment Asia-Pacific regulatory strategy.
United States
Ambulatory surgery center expansion and Medicare Advantage unbundling drive single-use kit demand. FDA 510(k) predicate device requirements compress first-mover advantages for novel manipulator designs. The Cleveland Clinic and Mayo Clinic anchor academic medical center adoption of automation-ready platforms.
Germany
Medical-grade silicone supply concentration and rigid endoscopy ecosystem control sustain premium positioning. EU MDR Article 10 technical documentation obligations extend design dossier timelines by 40-60 percent. Berlin and Munich academic centers pilot articulating shaft designs with curvature memory.
Japan
PMDA biocompatibility testing protocols and multi-quadrant laparoscopy specialization accelerate winged manipulator adoption. METI industrial policy supports domestic manufacturing of precision surgical instruments. Tokyo and Osaka metropolitan clusters concentrate gynecologic surgery fellowship programs.
South Korea
MFDS streamlined Class II device pathways create faster entry for standardized manipulator designs. Robotic-assisted hysterectomy convergence opens premium pricing tiers in Seoul academic medical centers. The Seoul Capital Area concentrates outpatient surgical infrastructure expansion.
India
PLI scheme domestic manufacturing incentives enable cost-competitive production for Southeast Asian export. CDSCO regulatory harmonization efforts accelerate import substitution for disposable surgical kits. Maharashtra and Gujarat industrial corridors attract medical device contract manufacturing investment.
Global Uterine Manipulation Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated quality management systems capturing share from smaller competitors facing extended EU MDR compliance timelines. The market structure favors incumbents with established predicate device libraries and sterilization validation capabilities. Three archetypes dominate: integrated surgical portfolio holders, rigid endoscopy ecosystem controllers, and disposable kit standardization specialists. Competitive moves concentrate on M&A for regulatory asset accumulation and strategic partnerships for robotic platform integration.
Among integrated portfolio holders, CooperSurgical Inc. and CONMED Corporation exemplify the fertility-to-surgery relationship model that sustains hospital system contracting. KARL STORZ SE & Co. KG occupies a position within the rigid endoscopy ecosystem control archetype, anchoring European premium positioning through tower configuration compatibility requirements. B. Braun SE represents the disposable kit standardization specialist tier, with network procurement dominance across United States ambulatory surgery center expansion.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| KARL STORZ SE & Co. KG |
| B. Braun SE |
| CONMED Corporation |
| Richard Wolf GmbH |
| Utah Medical Products, Inc. |
| Conkin Surgical Instrument Ltd. |
| Purple Surgical |
| Laborie |
| Others |
Supply & Pricing Matrix
Silicone balloon catheter substitution for fixed-angle stainless steel instruments is redrawing procurement geography toward German and Japanese polymer suppliers while compressing margins on legacy mechanical platforms. Hospital systems unbundling device purchases from bundled payment contracts now negotiate directly against this concentrated supply base, amplifying price volatility for disposable configurations.
Pricing Analysis
Contract structures stratify across long-term offtake agreements with integrated delivery networks, spot purchases by independent ambulatory surgery centers, and project-based tenders for academic medical center automation-ready platforms. Price differentiation hinges on FDA 510(k) predicate device availability and ISO 13485 certification tier, with premium automation-ready configurations commanding substantial markups over standard mechanical alternatives. Cost compression in mid-tier disposable kits is intensifying as B. Braun SE and KARL STORZ SE & Co. KG escalate network procurement competition. Ambulatory surgery centers exhibit highest price sensitivity due to per-procedure margin calculations under Medicare Advantage expansion, while academic medical centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Strategic stockpiling of medical-grade silicone dominates inventory strategy among German and Japanese suppliers facing extended EU MDR recertification timelines, contrasting with just-in-time preferences for stainless steel instrument fabrication. Geographic supply concentration centers on Germany, Japan, and the United States for polymer feedstocks and precision machining capacity. Raw material dependencies rest on medical-grade silicone elastomers, surgical-grade stainless steel, and sterilization-grade packaging films. Single-source vulnerability in silicone polymerization capacity creates exposure to input cost shocks. Distribution runs through group purchasing organizations and direct hospital system contracts, with ambulatory surgery center networks increasingly bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified gynecologic surgeons capable of complex multi-quadrant laparoscopy are becoming scarcer across OECD markets, concentrating value capture among device platforms that reduce procedural dependency on specialist labor pools. This capability scarcity rewards manufacturers with automation-ready portfolios and penalizes commodity mechanical suppliers.
For Market Incumbents: Compound regulatory asset advantages by accelerating EU MDR recertification of predicate device libraries before smaller competitors exhaust compliance timelines, while deepening backward integration into medical-grade silicone supply through captive arrangements with German and Japanese polymer houses. Prioritize automation-ready platform R&D to offset laparoscopic skill attrition in United States and United Kingdom fellowship programs. Channel control through integrated fertility-to-surgery portfolios sustains hospital system relationships against disposable kit standardization specialists. For New Entrants and Emerging Players: Post-market surveillance and clinical education service layers represent underexploited white space where incumbent quality management systems are stretched thin by documentation backlogs. Target South Korean MFDS Class II streamlined pathways for standardized winged manipulator designs, leveraging faster clearance timelines against EU MDR-delayed competitors. Pursue robotic-assisted hysterectomy convergence partnerships with da Vinci surgical system integrators as the primary go-to-market angle, securing premium pricing tiers in Seoul and Tokyo academic medical centers ahead of reimbursement policy codification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed disposable kit specialists lacking sterilization validation capabilities and automation-ready R&D pipelines. Five-to-ten year viability favors targets with established ISO 17664 documentation libraries and predicate device portfolios transferable across regulatory regimes. Watch for MFDS and PMDA biocompatibility testing protocol harmonization as the inflection signal indicating scalable Asia-Pacific entry for standardized platform designs.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | Incumbents with established technical documentation libraries capture share from compliance-constrained competitors. |
| Robotic Platform Integration Partnership | da Vinci surgical system compatibility opens premium pricing tiers in academic medical centers. |
| Single-Use Kit Standardization | B. Braun SE network procurement dominance eliminates reprocessing liability across United States ambulatory surgery center expansion. |
| Backward Integration into Silicone Supply | German and Japanese polymer sourcing concentration rewards captive supply arrangements with input cost stability. |
| Surgeon Training Proctoring Programs | Novel articulation mechanism adoption requires hands-on clinical education investment that strains manufacturer budgets. |
Research Methodology
A spread of perspectives from gynecologic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions underpinning this analysis. Primary interviews with these stakeholders were cross-validated against secondary sources including FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract records, and CMS Medicare procedure volume data. Bottom-up procedure volume estimates were triangulated with top-down manufacturer revenue allocations across product configurations and deployment modes.
Segmentation dimensions modeled include product type, application focus, end-user setting, and deployment configuration across the projection horizon. CAGRs were derived from procedure volume trajectories, price elasticity assumptions by customer tier, and regulatory pathway timing differentials. Forecast inputs incorporated laparoscopic hysterectomy migration rates to ambulatory settings, EU MDR recertification completion schedules, and robotic-assisted surgery platform penetration curves in academic medical centers.
Forecasts assume regulatory continuity in FDA 510(k) predicate device requirements, EU MDR Article 10 technical documentation obligations, and Japan PMDA biocompatibility testing protocols; material policy shifts in sterilization validation standards or surgeon training reimbursement would require re-modeling. Revision becomes warranted when laparoscopic skill attrition rates or silicone polymer supply disruptions cross thresholds that alter procedure volume or input cost assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gracey Curette Market
Medical Devices
US Contact Lenses Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Syringeless Injector Market
Medical Devices
South Korea ECG Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Pipette Controllers Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Urometer Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
3D Printed Prosthetics Market