
 Phototherapy Lamps Market | 2026-2036
Phototherapy Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Phototherapy Lamps Market Analytics
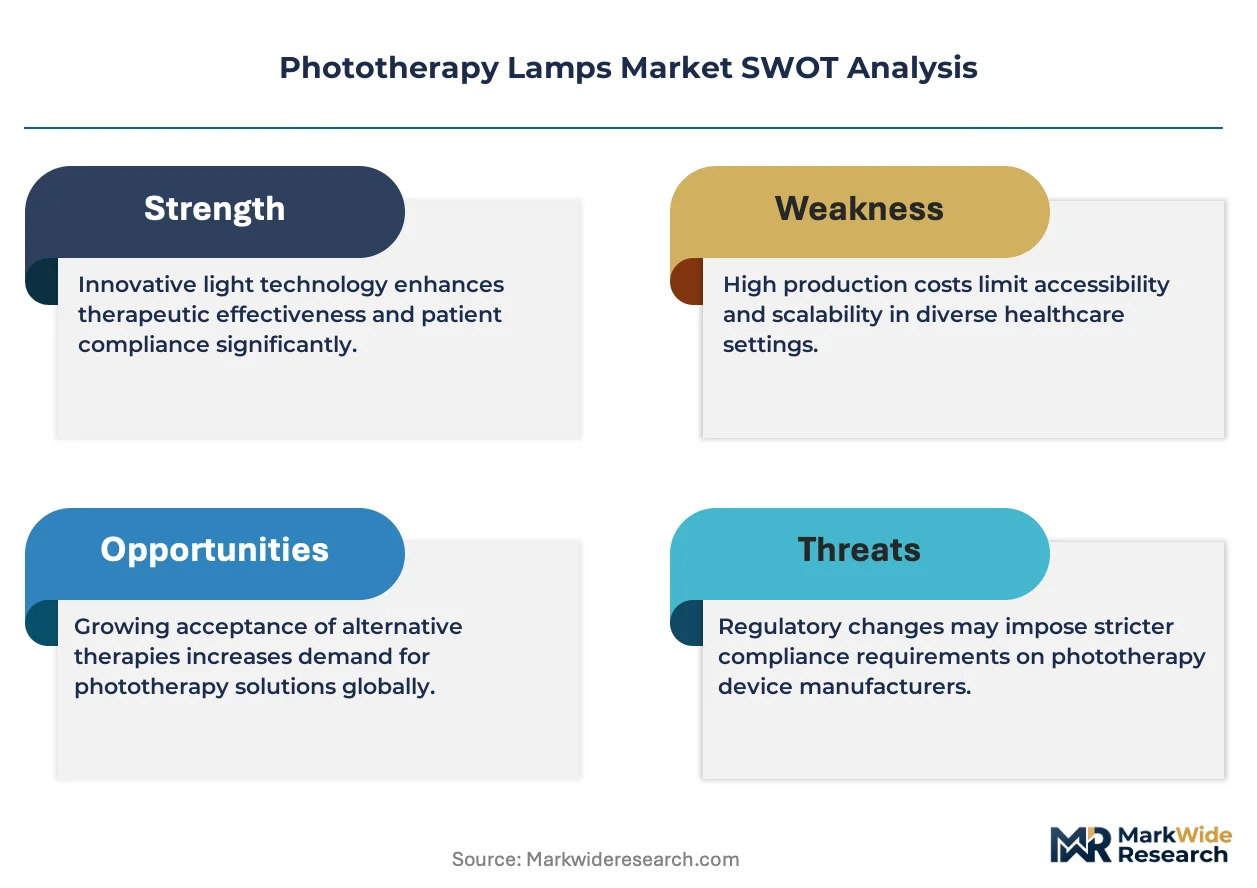
The phototherapy lamps market is repositioning around a sharp split between hospital-grade LED systems with precision wavelength control and commodity fluorescent units serving cost-sensitive clinics. Philips Healthcare leverages its spectral engineering capabilities to dominate premium neonatal installations across European tertiary centers. Herbert Waldmann GmbH & Co. KG anchors the dermatology segment with UV-filtered cabin systems that sustain premium pricing through modular lamp replacement programs.
Phototherapy lamps are therapeutic light-emitting devices engineered to deliver specific wavelengths—typically 425–475 nm for blue light, 600–700 nm for red light, or narrowband UVB at 311 nm—through calibrated irradiance panels or fiber-optic blankets to treat bilirubin accumulation, psoriasis, circadian rhythm disruption, or seasonal affective conditions. LED product types are capturing margin pools as solid-state sources displace mercury-bearing fluorescent tubes under REACH substance restrictions and Ecodesign efficiency mandates. Blue light therapy applications for neonatal jaundice represent the most structurally defended segment, given the non-discretionary nature of birth-related treatment protocols and the limited substitute efficacy of exchange transfusion.
FDA 510(k) pathways and the EU Medical Device Regulation (MDR) Class IIa requirements shape product development cycles, with notified body scrutiny intensifying for homecare devices that shift treatment from supervised to unsupervised settings. The EU F-Gas Regulation and parallel EPA SNAP restrictions on mercury-containing lamps are accelerating fluorescent phase-out timelines, compressing replacement demand into LED upgrade cycles. Stakeholders must monitor how national reimbursement authorities classify home phototherapy units—whether as durable medical equipment or wellness devices—as this determination will reshape channel economics and patient access models.
Market Dynamics
LED-based phototherapy systems are compressing replacement cycles as mercury-bearing fluorescent tubes face accelerating phase-out mandates under the EU F-Gas Regulation and parallel EPA SNAP restrictions, forcing capital redeployment toward solid-state platforms with precision wavelength calibration.
Growth Catalysts
- Neonatal protocol standardization:Government maternity health programs in India are scaling hospital-based phototherapy access in tier-2 and tier-3 cities, embedding blue-light systems into essential newborn care infrastructure.
- REACH substance restrictions:The European Union's chemical framework is accelerating fluorescent lamp obsolescence, redirecting procurement budgets toward LED alternatives with compliant material compositions.
- Homecare regulatory streamlining:FDA 510(k) clearance pathways for LED-based devices are shortening time-to-market for manufacturers targeting unsupervised treatment settings.
Market Restraints
- Mercury supply chain concentration:Fluorescent tube manufacturing depends on limited mercury sourcing channels, creating input volatility as environmental bans tighten global availability.
- EU MDR Class IIa scrutiny:Notified body examination intensity for homecare phototherapy units is extending certification timelines and elevating compliance expenditure.
- Exchange transfusion residual efficacy:Severe neonatal jaundice cases retain surgical fallback options that cap pricing power for phototherapy in critical care segments.
Strategic Opportunities
- Modular lamp replacement programs:UV-filtered cabin manufacturers are capturing recurring revenue through subscription-style service contracts for dermatology installations.
- Homecare reimbursement reclassification:National health authorities in multiple markets are reconsidering whether phototherapy units qualify as durable medical equipment versus wellness devices, with favorable rulings unlocking patient access subsidies.
- Red light therapy convergence:Circadian rhythm and seasonal affective disorder applications are expanding addressable demand beyond traditional neonatal and dermatology verticals.
Industry Challenges
- Spectral engineering talent scarcity:Precision wavelength control for LED systems requires specialized optical design expertise that outpaces current training pipeline output.
- Legacy fluorescent infrastructure stranded value:Clinics with recent fluorescent installations face accelerated obsolescence before depreciation recovery, complicating capital planning.
- Homecare risk management frameworks:Insurers and liability carriers are developing new coverage models for unsupervised phototherapy that delay product rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phototherapy Lamps Market |
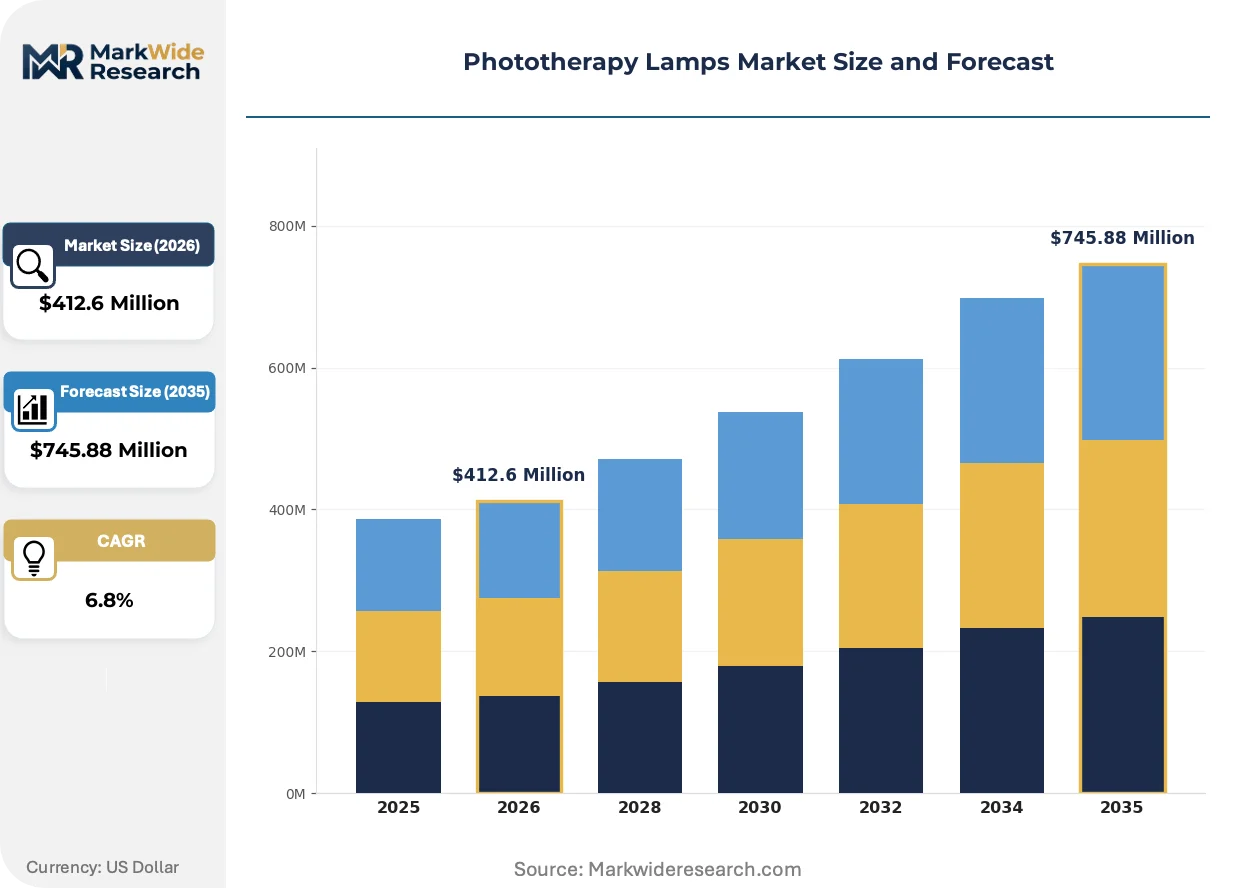
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Xenon Application: Skin Disorders, Mood Disorders, Sleep Disorders, Neonatal Jaundice End User: Hospitals, Clinics, Homecare Settings, Wellness Centers Technology: Blue Light Therapy, Red Light Therapy, UV Light Therapy, Laser Therapy |
| Companies Covered | GE Healthcare, Philips Healthcare, Natus Medical Incorporated, Atom Medical Corporation, Herbert Waldmann GmbH & Co. KG, National Biological Corporation, Daavlin Group, Inc., Dräger, STRATA Skin Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phototherapy Lamps Market Evolving Landscape
Solid-state light sources are fundamentally restructuring competitive positioning around spectral precision and connected monitoring capabilities, compressing the viable technology set for new market entrants.
LED arrays with calibrated irradiance panels are overtaking mercury-vapor fluorescent tubes in neonatal intensive care procurement. European tertiary centers are prioritizing solid-state platforms with real-time dosimetry feedback. This transition is compressing margins for legacy tube manufacturers while enabling premium pricing for systems with integrated monitoring.
The EU F-Gas Regulation and EPA SNAP program are accelerating fluorescent phase-out timelines across medical device supply chains. Manufacturers are redirecting R&D expenditure toward LED platform development to maintain market access. Homecare segments face the steepest compliance adaptation costs due to smaller operational buffers.
Hospital procurement committees are unbundling after-sales service from equipment purchase contracts, creating standalone service markets. Dermatology clinics in Germany and France are negotiating modular lamp replacement subscriptions separately from capital acquisitions. This shift is most visible in European markets with mature medical device leasing infrastructure.
Phototherapy Lamps Market Segmentation
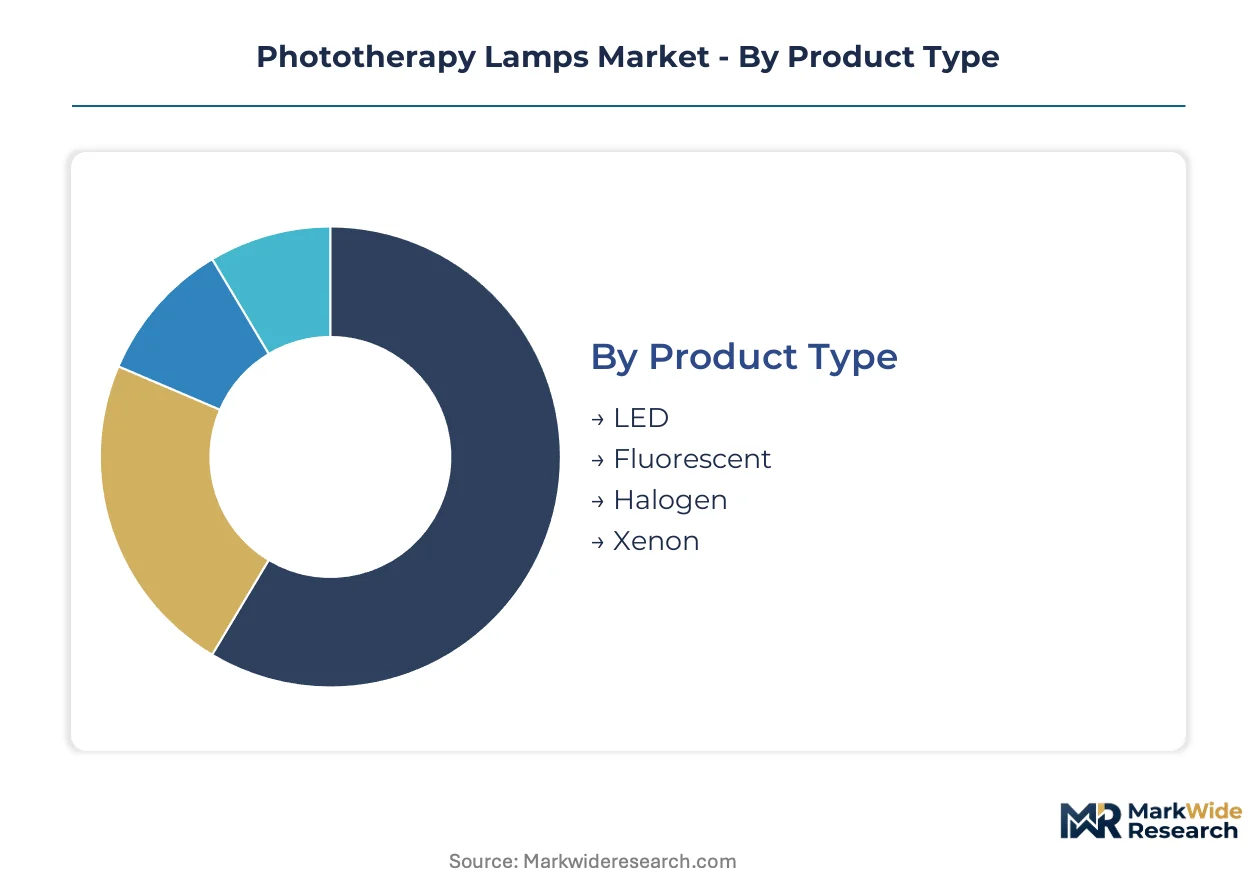
Phototherapy lamps segment across wavelength precision, clinical setting, and treatment protocol. Each axis carries distinct regulatory pathways and margin structures that determine competitive positioning.
Product Type:
LED platforms dominate new procurement as spectral engineering capabilities separate premium systems from commodity replacements.
- LED:Solid-state arrays deliver calibrated irradiance at 425–475 nm for neonatal jaundice with real-time dosimetry feedback. European tertiary centers prioritize these systems for precision wavelength control under Ecodesign efficiency mandates.
- Fluorescent:Mercury-bearing tubes face accelerating obsolescence under EU F-Gas Regulation and EPA SNAP restrictions. India and Southeast Asia retain residual demand where capital constraints delay LED conversion cycles.
- Halogen:Thermal emission sources persist in legacy dermatology cabins requiring broad-spectrum output.
- Xenon:Pulsed arc lamps serve specialized laser-pumped applications with limited addressable volume.
Mature deployment sits with Fluorescent. Newer deployment is concentrated in LED.
Application:
Clinical protocol standardization creates divergent growth trajectories across therapeutic verticals.
- Neonatal Jaundice:Blue-light treatment protocols are embedded in essential newborn care infrastructure. India's government maternity health programs are scaling hospital-based access in tier-2 and tier-3 cities, cementing structural demand.
- Skin Disorders:UV-filtered cabin systems treat psoriasis and vitiligo through modular lamp replacement programs. German and French dermatology clinics sustain premium pricing through subscription-style service contracts.
- Mood Disorders:Seasonal affective disorder applications are expanding addressable demand beyond traditional clinical settings.
- Sleep Disorders:Circadian rhythm correction drives homecare segment development with regulatory scrutiny intensifying for unsupervised use.
Volume concentration rests with Neonatal Jaundice. Margin expansion is strongest in Skin Disorders.
End User:
Care setting determines reimbursement classification and channel economics for device manufacturers.
- Hospitals:Neonatal intensive care units in developing economies are expanding procurement of blue-light systems. Capital budgets favor LED platforms with integrated monitoring and precision wavelength calibration.
- Homecare Settings:FDA 510(k) clearance pathways are shortening time-to-market for LED-based devices. National reimbursement authorities are reconsidering whether units qualify as durable medical equipment versus wellness devices.
- Clinics:Cost-sensitive installations in tier-2 and tier-3 Indian cities balance efficacy requirements against capital constraints.
- Wellness Centers:Commercial aesthetic applications operate outside medical device reimbursement frameworks with limited regulatory oversight.
Procurement authority clusters with Hospitals. Patient access expansion is concentrated in Homecare Settings.
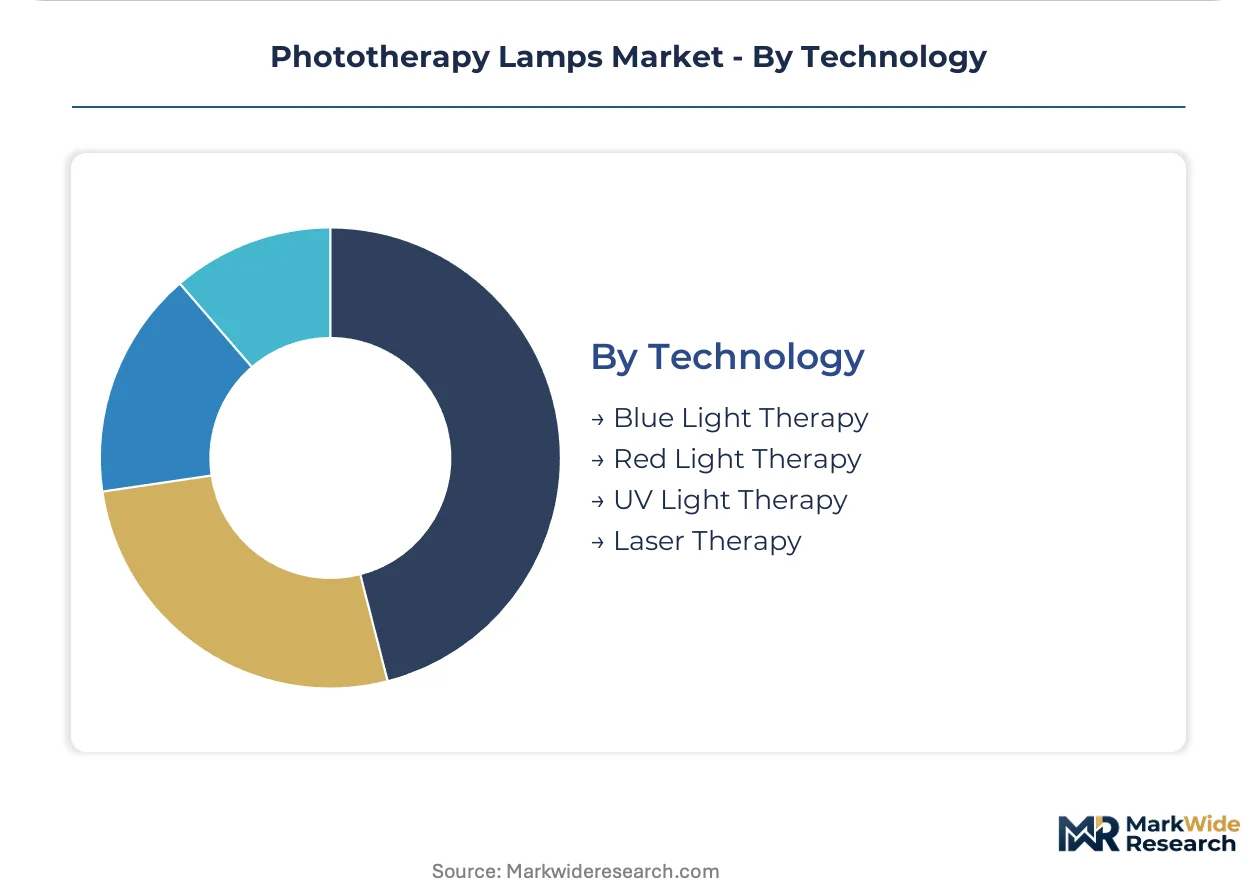
Technology:
Wavelength specificity defines clinical efficacy and regulatory classification across therapeutic modalities.
- Blue Light Therapy:425–475 nm emission targets bilirubin photoisomerization in neonatal jaundice treatment. Non-discretionary birth-related protocols limit substitute efficacy from exchange transfusion alternatives.
- UV Light Therapy:Narrowband UVB at 311 nm serves psoriasis and vitiligo protocols with dermatology cabin installations dominating European premium segments.
- Red Light Therapy:600–700 nm applications for circadian rhythm and wound healing are expanding beyond traditional verticals.
- Laser Therapy:Coherent emission sources serve precision dermatological applications with specialized training requirements limiting addressable provider base.
Clinical validation concentrates with Blue Light Therapy. Addressable market expansion is steepest for Red Light Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's medical device corridor anchors procurement activity for blue-light neonatal systems, with tier-2 and tier-3 Indian cities scaling hospital infrastructure under government maternity health programs.
United States
FDA 510(k) clearance pathways are shortening time-to-market for LED-based homecare devices targeting seasonal affective disorder and circadian rhythm applications. EPA SNAP restrictions on mercury-containing lamps are accelerating fluorescent phase-out timelines across medical device supply chains. Boston's cluster of neonatal intensive care research centers is piloting precision wavelength calibration systems for tertiary installations.
Germany
UV-filtered cabin systems for psoriasis and vitiligo sustain premium pricing through modular lamp replacement programs in dermatology clinics. EU MDR Class IIa scrutiny is extending certification timelines for homecare phototherapy units while elevating compliance expenditure. The Stuttgart-Tübingen medical technology corridor hosts engineering centers specializing in spectral control for solid-state therapeutic platforms.
India
Government maternity health programs are embedding blue-light systems into essential newborn care infrastructure across tier-2 and tier-3 cities. Central Drugs Standard Control Organization oversight is tightening quality benchmarks for imported LED therapeutic devices. Ahmedabad's medical device manufacturing zone is expanding domestic production capacity for cost-sensitive clinic installations.
Japan
Ministry of Economy, Trade and Industry efficiency mandates are redirecting hospital procurement budgets toward LED alternatives with compliant material compositions. Pharmaceutical and Medical Devices Agency examination protocols are intensifying for unsupervised homecare treatment settings. Osaka's precision optics cluster is developing real-time dosimetry feedback systems for neonatal intensive care units.
United Kingdom
Medicines and Healthcare products Regulatory Agency alignment with EU MDR frameworks is reshaping notified body engagement for therapeutic light device manufacturers. National Health Service reimbursement authorities are reconsidering whether home phototherapy units qualify as durable medical equipment versus wellness devices. London's dermatology research centers are advancing narrowband UVB protocols for psoriasis treatment cabins.
Phototherapy Lamps Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the phototherapy lamps landscape, with integrated device manufacturers maintaining captive spectral engineering capabilities while contract assemblers serve cost-sensitive segments. Market structure tilts toward consolidation in premium neonatal and dermatology verticals, with mid-tier fragmentation in homecare and wellness applications. Three archetypes dominate: diversified healthcare conglomerates with cross-divisional light therapy portfolios, specialized therapeutic device engineers with modular service programs, and regional fabricators targeting price-sensitive clinic procurement. Competitive moves center on regulatory pre-clearance strategies for homecare expansion and backward integration into LED array sourcing.
Among diversified healthcare conglomerates, GE Healthcare and Philips Healthcare exemplify scale-driven archetypes with cross-divisional spectral engineering capabilities. Herbert Waldmann GmbH & Co. KG occupies a position within the specialized therapeutic device tier, representing German-engineered cabin system expertise. Dräger anchors the neonatal critical care vector with integrated monitoring and therapeutic light platforms. These named entities sit within broader competitive dynamics where regulatory navigation and service contract structuring separate premium positioning from commodity replacement cycles.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Natus Medical Incorporated |
| Atom Medical Corporation |
| Herbert Waldmann GmbH & Co. KG |
| National Biological Corporation |
| Daavlin Group, Inc. |
| Dräger |
| STRATA Skin Sciences |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation mandates for mercury-bearing lamp phase-out are forcing procurement committees in German and French dermatology clinics to accelerate LED conversion timelines, compressing supplier response windows and elevating premium pricing for solid-state platforms with precision wavelength calibration.
Pricing Analysis
Value-based pricing anchored to clinical throughput and bilirubin reduction efficacy separates premium LED installations from commodity fluorescent replacements. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier—FDA 510(k) cleared systems command 40-60% markups over uncertified wellness devices—and by after-sales service bundling. Cost compression in economy-tier fluorescent segments is intensifying because REACH substance restrictions are accelerating obsolescence before depreciation recovery. Hospital procurement committees in India exhibit highest price sensitivity, while European tertiary centers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Reverse-logistics flows for modular lamp replacement programs in UV-filtered dermatology cabins are creating captive aftermarket revenue streams for German-engineered systems. Manufacturing concentration centers on China for LED array fabrication, Germany for precision optical calibration, and India for cost-sensitive clinic assembly. Mercury sourcing for residual fluorescent production draws from limited Kazakh and Kyrgyz mining channels. Single-source vulnerability in gallium nitride substrate supply creates exposure to export restriction shocks. Distribution runs through medical device leasing houses in Europe and direct hospital procurement in developing economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phototherapy lamps market sits in a technology-transition phase where solid-state LED platforms are displacing mercury-bearing fluorescent tubes under accelerating environmental mandates.
For Market Incumbents: Hedge against stranded fluorescent inventory by accelerating backward integration into LED array sourcing and securing long-term gallium nitride supply agreements. Redirect R&D expenditure toward real-time dosimetry feedback systems before EU MDR Class IIa scrutiny extends certification timelines for homecare entrants.
For New Entrants and Emerging Players: The price-point gap between premium European cabin systems and economy fluorescent units in tier-2 Indian cities offers white-space entry through modular service subscription models. Target cost-sensitive clinic procurement in Ahmedabad's manufacturing corridor with CE-marked LED platforms positioned between uncertified wellness devices and hospital-grade installations.
For Investors and Strategic Acquirers: The window for entry favors specialized therapeutic device engineers with captive spectral engineering capabilities and recurring revenue from lamp replacement programs. Long-term viability hinges on regulatory navigation expertise for homecare reimbursement reclassification. Monitor FDA 510(k) clearance velocity for LED-based unsupervised treatment devices as inflection indicator for patient access subsidy expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa scrutiny elevates compliance expenditure for homecare entrants targeting unsupervised settings. |
| Backward Integration into LED Arrays | Gallium nitride substrate sourcing secures supply continuity as fluorescent phase-out compresses conversion timelines. |
| Hospital System Partnership | Indian government maternity health programs embed blue-light systems into tier-2 and tier-3 infrastructure procurement. |
| Software Companion Development | Real-time dosimetry feedback differentiates premium neonatal installations in European tertiary centers. |
| Reimbursement Strategy | National health authority classification as durable medical equipment unlocks patient access subsidies for homecare segments. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR notified body guidance, and Indian CDSCO quality benchmarks, complemented by interviews with neonatal intensive care unit directors, dermatology clinic procurement managers, biomedical engineers, and GPO contracts administrators. Secondary validation drew from hospital procurement databases, medical device leasing records, and REACH substance restriction filings. Bottom-up unit shipment estimates triangulated against top-down wavelength-specific market sizing across the analysis window.
Cross-referencing historical fluorescent-to-LED conversion patterns with panel input from spectral engineering specialists informed the projection framework. Segmentation dimensions modeled include product type, application protocol, end-user setting, and technology wavelength. CAGRs were derived from installed base replacement cycles and penetration rate assumptions for homecare reimbursement expansion. Industry-specific inputs incorporated EU F-Gas Regulation phase-out timelines and Indian government maternity health program procurement schedules.
Inputs from notified body examination reports and national reimbursement authority rulings were available through the study window; gaps in real-time homecare adverse event data introduce uncertainty bands around patient access model forecasts. Practitioners should monitor FDA 510(k) clearance velocity for unsupervised LED devices and EU MDR Class IIa certification timeline extensions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
IV Equipment Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Prescription Lens Market
Medical Devices
Bowel Stimulators Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Transilluminators Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
At-Home Blood Collection Kits and Devices Market