
 Global High-Flow Nasal Cannula Market | 2026-2036
Global High-Flow Nasal Cannula Market Size, Share, and Industry Trends Forecast 2026-2036
Global High-Flow Nasal Cannula Market Foresight
Hospital-grade heated humidification is rotating toward premium specifications as clinicians demand tighter temperature control and lower noise thresholds. Fisher & Paykel Healthcare leverages its integrated humidifier platform to dominate the adult cannula segment across acute care settings. Vapotherm competes through precision flow modulation technology that targets hypoxemic respiratory failure protocols. Teleflex anchors its position via broad catheter and airway portfolios that bundle high-flow delivery with vascular access lines.
A high-flow nasal cannula delivers heated, humidified oxygen at flow rates exceeding standard nasal cannula limits, typically operating between 20–60 liters per minute with fractional inspired oxygen titration. The device prevents mucosal drying, reduces anatomical dead space, and generates positive end-expiratory pressure to support spontaneous breathing in hypoxemic patients. Adult cannula configurations command the largest revenue pool given ICU and emergency department volume, while home care settings represent the fastest-growing therapy area as discharge protocols shift toward ambulatory respiratory support. Pediatric and neonatal segments occupy specialized niches where lower-flow precision and softer material compositions determine supplier selection.
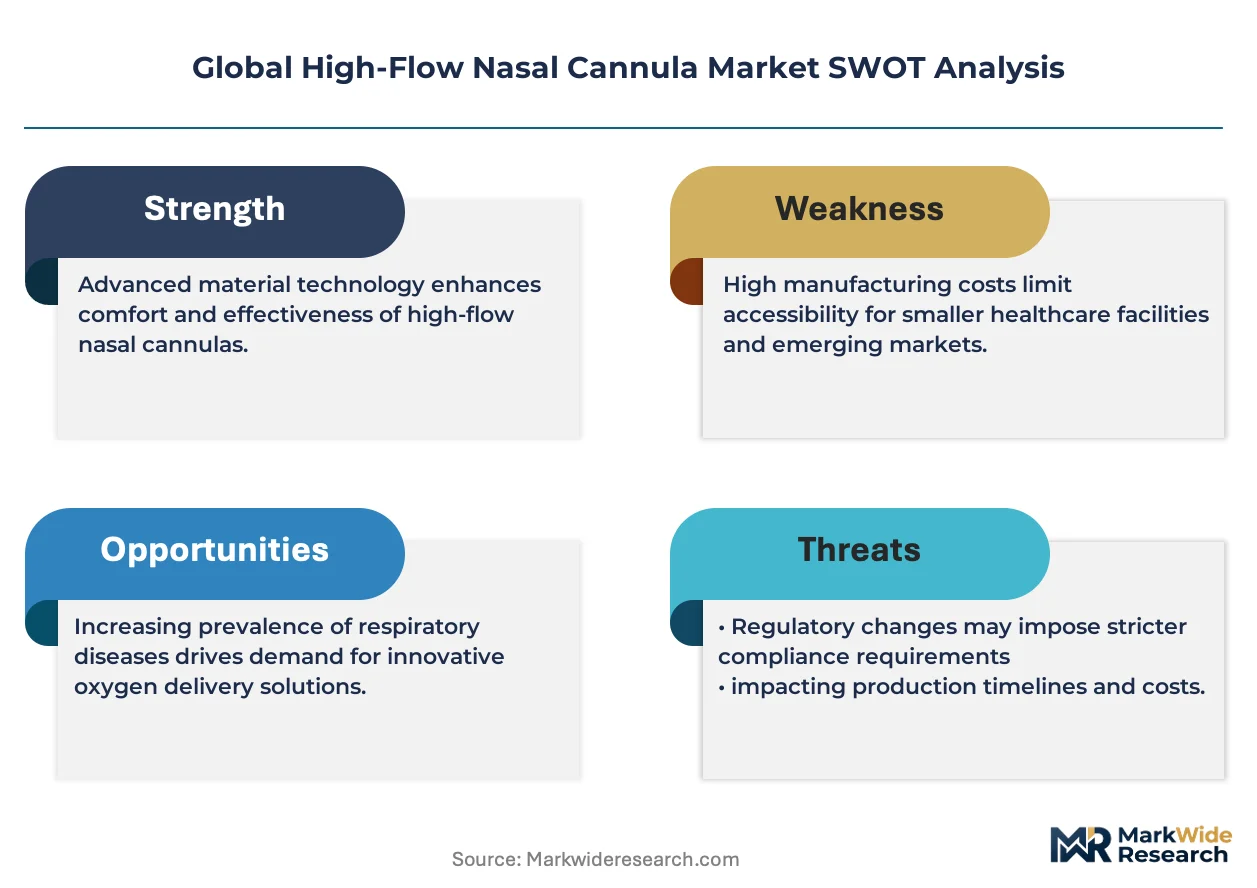
The FDA governs Class II respiratory device clearances through 510(k) pathways that mandate biocompatibility and electrical safety testing, while the EU MDR requires notified body conformity assessments for CE marking of active therapeutic devices. ISO 80601-2-90 establishes particular requirements for high-flow respiratory therapy equipment, creating baseline interoperability standards that manufacturers must satisfy for multi-regional market access. Stakeholders should monitor evolving reimbursement codes for home-based high-flow therapy as payers reassess cost-offset models against hospital readmission metrics.
Market Dynamics
Hospital discharge protocols are accelerating ambulatory respiratory support adoption, compressing the traditional inpatient-centric device procurement model toward home-based therapy configurations. This demand rotation is forcing manufacturers to reengineer portable heated humidification systems while maintaining clinical equivalence with ICU-grade platforms.
Growth Catalysts
- COPD prevalence escalation:Aging demographics in the United States, China, and Germany are expanding the addressable patient pool for chronic respiratory management. Pulmonology departments are integrating high-flow therapy earlier in disease progression protocols.
- ISO 80601-2-90 harmonization:The international standard for high-flow respiratory equipment is streamlining multi-regional product registrations. Manufacturers leveraging this baseline are accelerating market access across previously fragmented certification landscapes.
- Acute care workflow integration:Emergency departments are adopting high-flow nasal cannula systems as first-line intervention for hypoxemic respiratory failure. This clinical positioning is displacing non-invasive ventilation in select patient stratifications.
Market Restraints
- Silicone supply concentration:Medical-grade tubing and cannula materials depend on specialized polymer suppliers concentrated in East Asian manufacturing clusters. Input cost volatility constrains margin stability for device assemblers.
- Reimbursement code fragmentation:Payer classification inconsistencies across Medicare, Medicaid, and private insurers create administrative friction. Home-based high-flow therapy lacks standardized durable medical equipment coding in multiple jurisdictions.
- Non-invasive ventilation substitution:Bilevel positive airway pressure systems retain established reimbursement pathways and clinician familiarity. This incumbent technology limits high-flow penetration in sleep-disordered breathing applications.
Strategic Opportunities
- Pediatric home care expansion:Bronchiolitis and congenital airway anomaly management is migrating from hospital wards to domestic settings in Germany and Japan. Lower-flow precision devices with softer material compositions command premium positioning.
- EU MDR conformity acceleration:The Medical Device Regulation's stricter notified body requirements are elevating barriers for marginal competitors. Well-capitalized manufacturers can capture share from suppliers facing extended recertification timelines.
- Remote monitoring convergence:Integration of high-flow delivery with cloud-connected respiratory analytics platforms is enabling predictive intervention models. This technology pairing supports value-based care contracting with integrated health systems.
Industry Challenges
- Biocompatibility testing backlog:FDA 510(k) submissions for novel cannula materials face extended review queues. Electrical safety validation for heated humidifier components compounds regulatory timeline uncertainty.
- Legacy EMR integration complexity:Hospital information systems require custom interface development to capture high-flow therapy parameters. This technical friction delays procurement committee approvals for multi-device platform rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High-Flow Nasal Cannula Market |
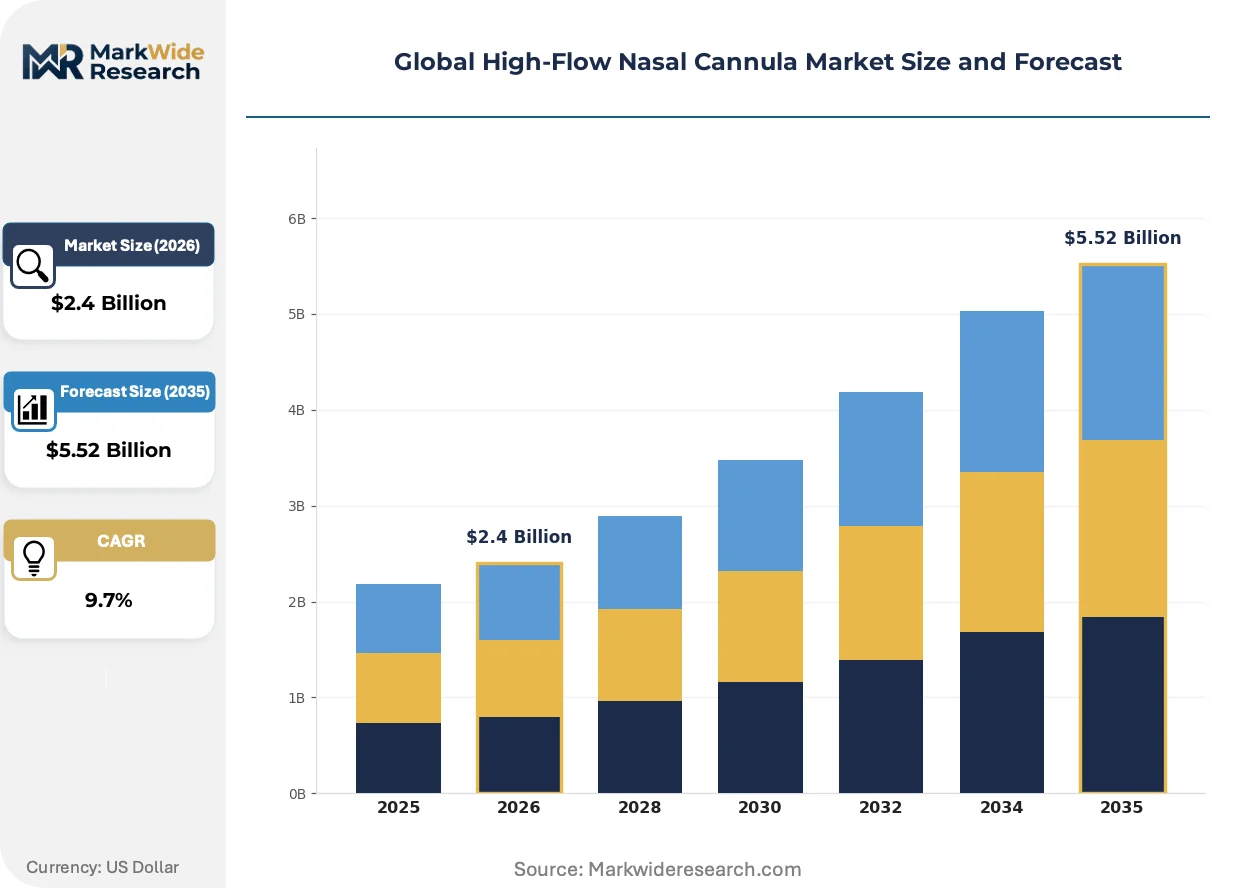
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Cannula, Pediatric Cannula, Neonatal Cannula, Disposable Cannula Therapy Area: Respiratory Distress, Chronic Obstructive Pulmonary Disease, Bronchopulmonary Dysplasia, Pneumonia, Sleep Apnea End User: Hospitals, Ambulatory Surgery Centers, Home Care Settings, Specialty Clinics Distribution Channel: Direct Sales, Medical Distributors, E-commerce Platforms, Retail Pharmacies |
| Companies Covered | Fisher & Paykel Healthcare, Teleflex, Vapotherm, ResMed, Becton Dickinson, Smiths Group, Flexicare Medical, Teijin Pharma, Hamilton Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High-Flow Nasal Cannula Market Shifts & Advancements
Heated humidification engineering is undergoing modularization, enabling component-level upgrades that extend device lifecycle value. This architectural shift is compressing capital replacement cycles while elevating service revenue attachment rates.
Precision flow modulation technology is decomposing the traditional binary distinction between low-flow nasal cannula and mechanical ventilation. Adult ICUs in the United States are adopting these intermediate systems for spontaneous breathing trials. The resulting clinical flexibility is compressing ventilator dependency duration and freeing critical care capacity.
The FDA's continued classification oversight for Class II respiratory devices is tightening predicate device equivalence requirements. Manufacturers must now demonstrate substantial equivalence through expanded clinical validation datasets. This regulatory elevation most affects pediatric and neonatal segments where patient safety thresholds command heightened scrutiny.
After-sales service unbundling is disrupting the traditional capital-plus-consumables bundling model. Hospital procurement committees are separating device acquisition from preventive maintenance contracts. This purchasing behavior shift is most visible in United States integrated delivery networks negotiating multi-site standardization agreements.
Global High-Flow Nasal Cannula Market Segmentation
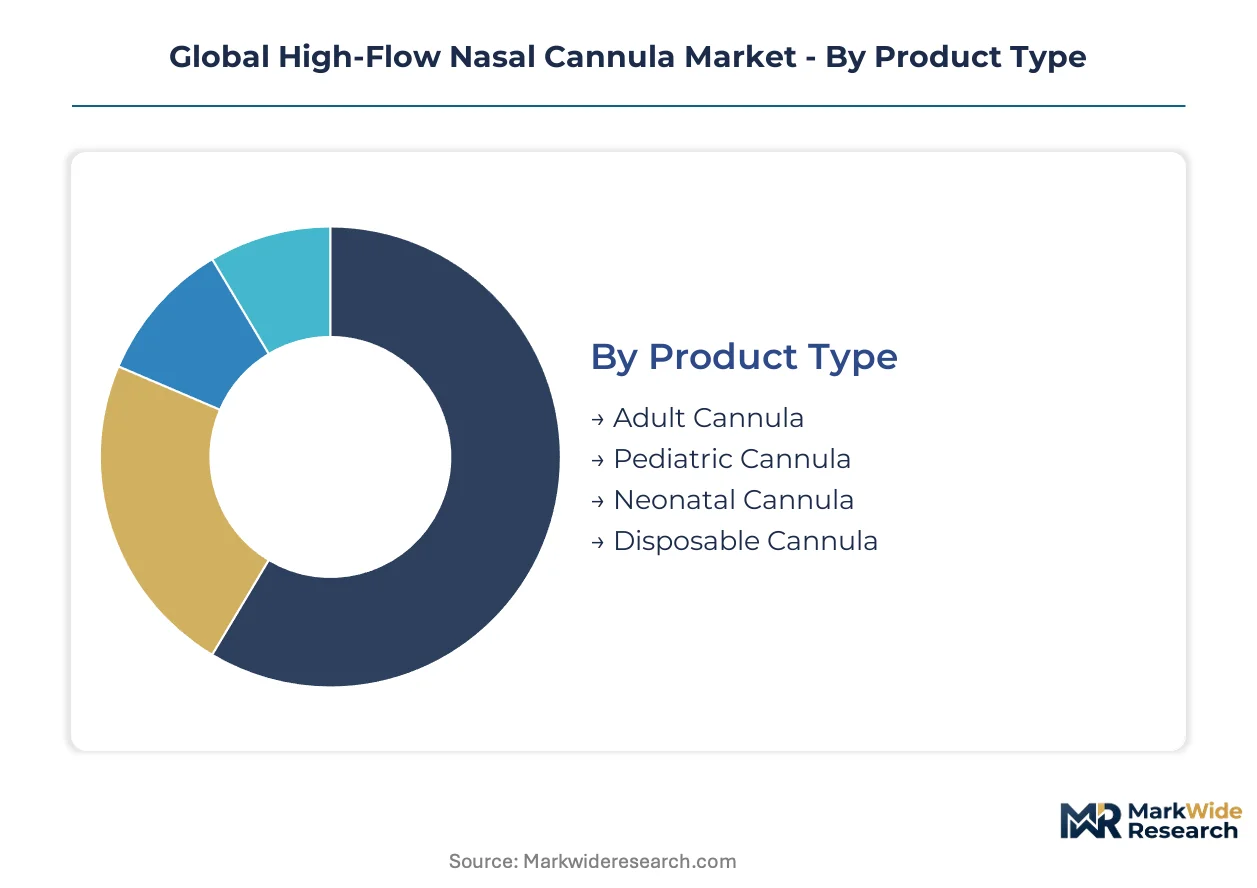
Segmentation in the high-flow nasal cannula market determines procurement pathways, reimbursement eligibility, and clinical workflow integration. Manufacturers configure product portfolios across patient demographics, therapy protocols, and care settings to capture volume and margin simultaneously.
Product Type:
Substitution pressure from non-invasive ventilation systems weighs heaviest on adult configurations, while neonatal and pediatric segments defend position through specialized material requirements and lower-flow precision engineering.
- Adult Cannula:Heated humidification platforms deliver 20–60 liters per minute through wide-bore nasal prongs designed for acute hypoxemic respiratory failure. Demand concentrates in United States hospital ICUs where emergency departments are displacing bilevel positive airway pressure for first-line intervention.
- Pediatric Cannula:Softer silicone compositions and reduced flow ranges accommodate developing airway anatomy in patients aged one month to twelve years. Germany and Japan are expanding home-based bronchiolitis management, creating demand for portable heated humidification with parental interface simplicity.
- Neonatal Cannula:Micro-prong designs with sub-two-millimeter diameter address premature infant nasal septum fragility. FDA Class II scrutiny elevates biocompatibility testing burdens for novel material submissions.
- Disposable Cannula:Single-use configurations dominate ambulatory and home care settings where cross-contamination protocols mandate frequent replacement cycles.
Adult cannula retains volume leadership; pediatric configurations hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates acute intervention protocols from chronic management reimbursement pathways, with hospital-based therapies commanding premium pricing against home care alternatives.
- Respiratory Distress:Acute hypoxemia management in emergency departments and ICUs represents the foundational clinical application driving heated humidifier platform adoption across acute care networks.
- Chronic Obstructive Pulmonary Disease:Early disease-stage integration of high-flow therapy is expanding addressable patient pools in aging United States, China, and Germany demographics. Pulmonology departments are revising step-care protocols to position cannula therapy before non-invasive ventilation escalation.
- Bronchopulmonary Dysplasia:Neonatal ICU applications require precise fractional inspired oxygen titration and flow modulation to support developing lung tissue in premature infants.
- Pneumonia:Community-acquired and hospital-acquired infection management leverages high-flow delivery to reduce intubation rates and mechanical ventilation dependency duration.
- Sleep Apnea:Substitution threat from established continuous positive airway pressure reimbursement pathways limits penetration; high-flow systems compete on comfort and mask-free adherence advantages.
Respiratory distress anchors revenue concentration; COPD management is climbing the fastest as disease-stage protocols shift.
End User:
Customer type fragmentation is compressing traditional hospital-centric procurement models toward distributed care settings with diverging technical and service requirements.
- Hospitals:Integrated delivery networks in the United States negotiate multi-site standardization agreements separating capital acquisition from preventive maintenance contracts. ICU and emergency department volume sustains premium heated humidifier platform deployment.
- Ambulatory Surgery Centers:Same-day respiratory support requirements favor compact, rapid-deployment systems with simplified staff training protocols.
- Home Care Settings:Discharge protocol acceleration is forcing manufacturers to reengineer portable heated humidification while maintaining clinical equivalence with ICU-grade platforms. Reimbursement code fragmentation across Medicare, Medicaid, and private insurers constrains expansion velocity.
- Specialty Clinics:Pulmonology and sleep medicine practices require intermediate flow systems for diagnostic and therapeutic trial applications.
Hospitals retain volume leadership; home care settings hold the steepest expansion curve.
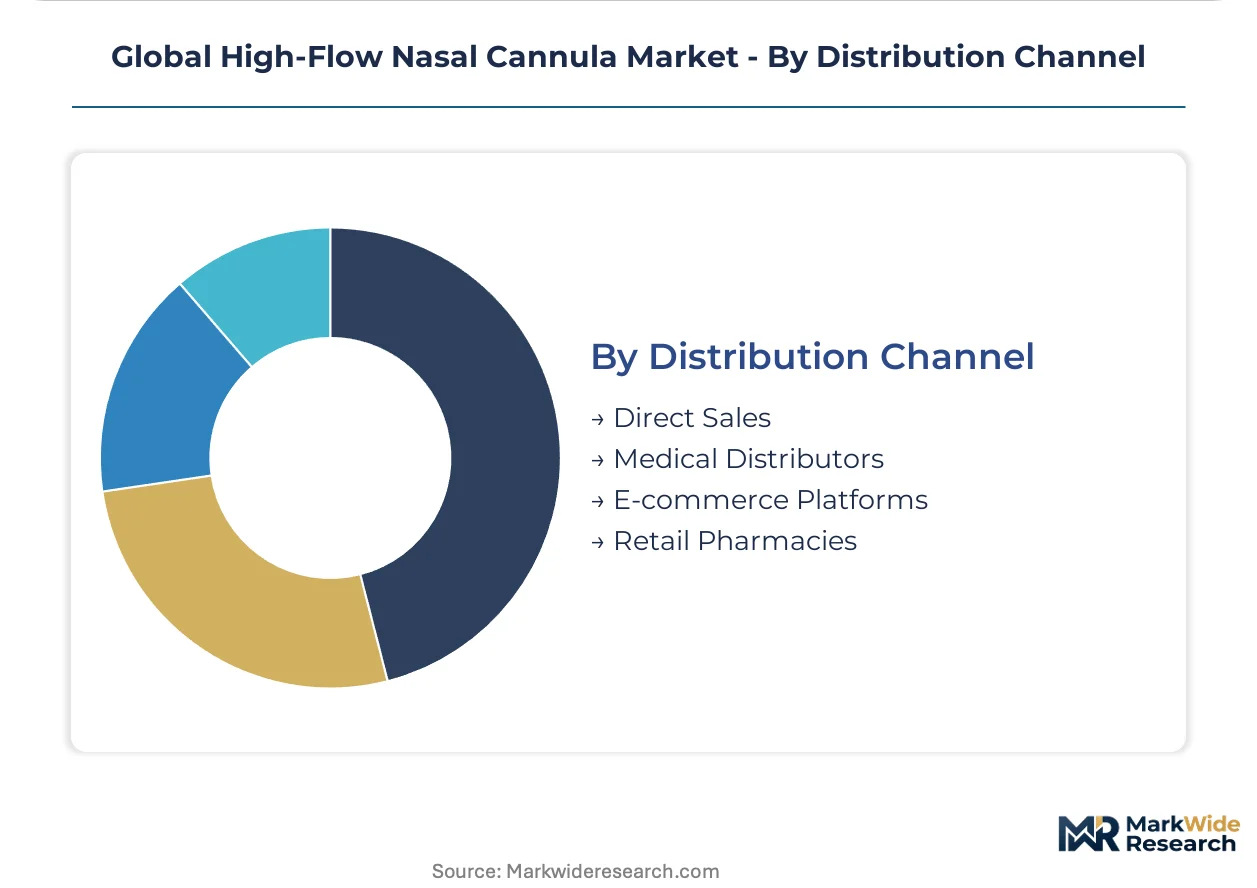
Distribution Channel:
Supply concentration in East Asian polymer manufacturing clusters shapes channel economics, with direct sales relationships offering margin protection against distributor markup compression.
- Direct Sales:Manufacturer field forces engage integrated delivery networks and hospital procurement committees for multi-device platform rollouts requiring custom EMR interface development.
- Medical Distributors:Regional warehousing and logistics networks address acute care replenishment cycles for disposable cannula and humidifier chamber consumables.
- E-commerce Platforms:Home care patient and caregiver direct purchasing is expanding as durable medical equipment coding standardization progresses in select jurisdictions.
- Retail Pharmacies:Limited to accessory and replacement component distribution where prescription requirements and insurance pre-authorization create transaction friction.
Medical distributors retain volume leadership; e-commerce platforms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: United States hospital procurement committees absorb premium pricing for ICU-grade platforms, while Chinese provincial health authorities negotiate aggressively on bulk tenders. German outpatient reimbursement codes create intermediate sensitivity for home care expansion.
United States
Emergency department volume and integrated delivery network consolidation drive heated humidifier platform deployment. FDA 510(k) pathways for Class II respiratory devices mandate biocompatibility validation that extends clearance timelines. Boston and Minneapolis medical device clusters concentrate engineering talent for precision flow modulation systems.
Germany
Aging demographics and COPD prevalence expand pulmonology department budgets for early-stage respiratory intervention. EU MDR notified body conformity assessments elevate barriers for marginal competitors seeking CE marking. Baden-Württemberg manufacturing corridors host specialized polymer suppliers for medical-grade cannula tubing.
China
Provincial hospital construction and ICU bed expansion create procurement volume for domestic and multinational suppliers. NMPA registration requirements for active therapeutic devices demand local clinical trial data. Shanghai and Suzhou industrial parks concentrate device assembly operations serving Asia-Pacific distribution networks.
Japan
Pediatric bronchiolitis protocols and home care discharge acceleration drive demand for lower-flow precision devices. PMDA quality management system inspections extend market access timelines for foreign manufacturers. Tokyo and Osaka metropolitan areas concentrate respiratory specialist practices adopting intermediate oxygen delivery systems.
India
Private hospital chain expansion and medical tourism infrastructure investment create tier-1 city demand for acute care platforms. CDSCO import licensing and local manufacturing incentives under PLI schemes reshape supplier market access. Hyderabad and Bengaluru medical device corridors attract contract manufacturing for disposable cannula components.
Global High-Flow Nasal Cannula Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium positioning concentrates around integrated humidifier platforms with precision flow control, while scale-driven manufacturers compete on consumable pricing and distribution reach. Three archetypes dominate: integrated system specialists, component-scale suppliers, and diversified medical device conglomerates. M&A activity targets respiratory technology capabilities, while geographic expansion through distributor partnerships accelerates emerging market penetration.
Among diversified medical device conglomerates, Teleflex and Becton Dickinson exemplify portfolio-breadth strategies that bundle airway management with vascular access and medication delivery systems. Fisher & Paykel Healthcare anchors the integrated system specialist tier through its origin in humidification engineering. Hamilton Medical occupies a position within precision ventilation technology that extends into high-flow respiratory support workflows.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare |
| Teleflex |
| Vapotherm |
| ResMed |
| Becton Dickinson |
| Smiths Group |
| Flexicare Medical |
| Teijin Pharma |
| Hamilton Medical |
| Others |
Supply & Pricing Matrix
Capacity utilization at East Asian polymer manufacturing clusters shapes both input cost floors and supplier pricing power across heated humidifier platform assembly. Scale concentration in medical-grade silicone production creates asymmetric margin pressure that propagates through disposable cannula pricing tiers.
Pricing Analysis
FDA 510(k) classification dictates the pricing tier structure across premium, standard, and economy levels in the high-flow nasal cannula market. Price differentiation hinges on biocompatibility certification grade and heated humidifier precision specifications. Pricing pressure stems from Medicare reimbursement code fragmentation that constrains home care expansion velocity. Ambulatory surgery centers exhibit the highest price sensitivity due to capital budget constraints, while United States integrated delivery networks absorb premium pricing for ICU-grade platforms.
Supply Chain Analysis
Inventory lead times for medical-grade silicone tubing extend when East Asian manufacturing clusters face capacity constraints. Supply concentrates in China, South Korea, and Germany for specialized polymer inputs. Raw material dependencies include platinum-cured silicone, heated element alloys, and precision flow sensors. Single-source vulnerability in medical-grade polymer supply creates structural risk exposure. Distribution runs through medical distributors with regional warehousing networks addressing acute care replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across patient demographics and care settings creates niche capture opportunities as discharge protocols accelerate home-based respiratory support demand.
For Market Incumbents: Compound platform stickiness through backward integration into heated humidifier component manufacturing and predictive service contract attachment. Non-invasive ventilation substitution in sleep-disordered breathing applications threatens margin pools in the adult segment. Capacity addition in Baden-Württemberg polymer corridors secures input cost stability against East Asian supply volatility. For New Entrants and Emerging Players: Lead with pediatric home care configurations in Germany and Japan where bronchiolitis management protocols favor lower-flow precision devices with parental interface simplicity. The most penetrable segment is portable heated humidification for ambulatory respiratory support. A direct-to-patient e-commerce go-to-market angle bypasses distributor markup compression in standardized consumable categories. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated system specialists with consumable attachment rates and preventive maintenance contract penetration. Long-term viability over the coming decade rests on software companion development for remote respiratory analytics platforms. Acquisition target archetypes include precision flow modulation technology developers and cloud-connected monitoring platform operators. The signal to watch is CMS durable medical equipment coding standardization for home-based high-flow therapy.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Biocompatibility validation for novel cannula materials accelerates predicate device clearance timelines. |
| CE Marking Pathway | EU MDR notified body conformity assessments elevate barriers for marginal competitors seeking European market access. |
| Hospital System Partnership | Integrated delivery network standardization agreements separate capital acquisition from preventive maintenance contracts. |
| Software Companion Development | Cloud-connected respiratory analytics platforms enable predictive intervention models for value-based care contracting. |
| Reimbursement Strategy | CMS durable medical equipment coding standardization unlocks home care expansion velocity across Medicare jurisdictions. |
Research Methodology
The analysis maps adult cannula configurations, pediatric precision devices, neonatal micro-prong designs, and portable heated humidification systems, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and pulmonology department heads. Primary interview data triangulates against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 80601-2-90 certification registries. Bottom-up patient volume modeling and top-down manufacturer revenue aggregation ensure cross-validation consistency.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions including patient age demographic, therapy protocol acuity, care setting infrastructure, and regional regulatory cluster. CAGRs derive from patient volume epidemiology trajectories and device replacement cycle assumptions. Forecast inputs incorporate COPD prevalence projections and ICU bed expansion rates in priority markets.
Forecasts assume regulatory continuity in FDA Class II device oversight and EU MDR notified body operations; material policy shifts would require re-modeling. Reimbursement code fragmentation and silicone supply concentration represent specific risk factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Tourniquet Systems Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
Global Ventilators Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Cervical Fusion Market