
 Hyperpigmentation Treatment Devices Market | 2026-2036
Hyperpigmentation Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperpigmentation Treatment Devices Market Outlook
Software-defined treatment protocols is repositioning how device manufacturers bundle value beyond hardware sales. Cutera leverages cloud-based parameter libraries to sustain recurring engagement with dermatology clinics. Alma Lasers anchors its commercial strategy through installed-base upgrades rather than sole reliance on new system placements.
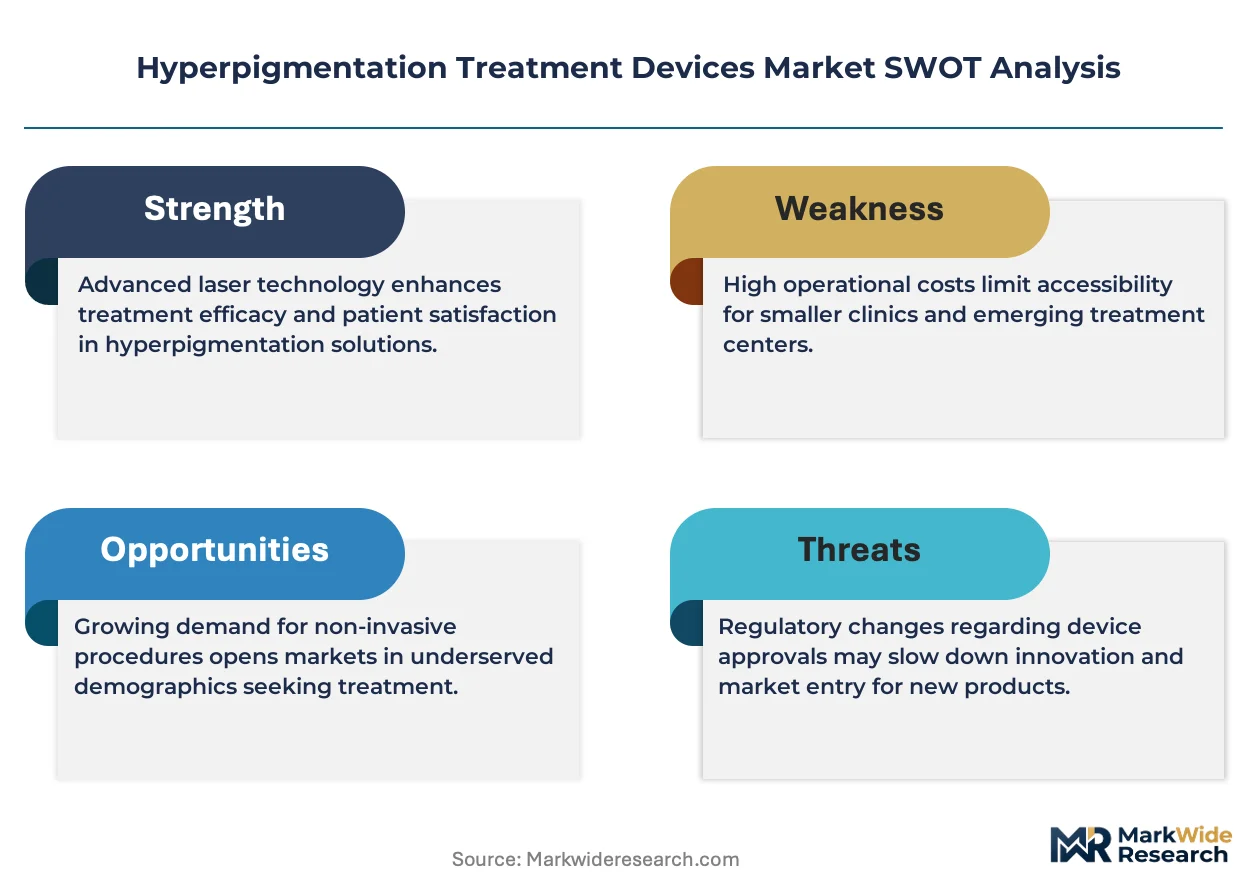
Hyperpigmentation treatment devices are electromechanical or energy-based systems engineered to deliver controlled thermal, light, or radiofrequency energy at wavelengths between 532 nm and 1064 nm to disrupt melanin deposits in epidermal or dermal tissue. Laser devices command the largest revenue pool due to higher capital pricing and consumable attachment cycles, while radiofrequency devices represent the fastest-expanding segment as providers seek options with reduced post-inflammatory hyperpigmentation risk in darker skin phototypes. Nanotechnology integration into topical delivery systems is creating hybrid protocol demand that links in-clinic devices with adjuvant home care.
FDA 510(k) clearance requirements and the EU MDR framework govern device safety and clinical evidence standards, with FDA scrutiny intensifying for software-controlled energy modulation features. Brazil's ANVISA and South Korea's MFDS are converging toward IEC 60601-1-2 electromagnetic compatibility benchmarks, complicating multi-regional product launches. Stakeholders must monitor how AI-driven skin analysis tools become regulated as accessory medical devices rather than standalone software.
Market Dynamics
Software-defined energy modulation is compressing hardware replacement cycles as dermatology clinics prioritize protocol subscriptions over capital equipment turnover.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated review timelines for laser systems with predicate device equivalence are shortening commercialization horizons for manufacturers with established installed bases.
- Brazilian medical spa consolidation:Chains like Corpo Dourado and Clinica da Pele are standardizing phototherapy protocols across multi-site networks, creating volume purchase commitments.
- Picosecond pulse technology:Shorter thermal exposure windows are expanding treatable skin phototype ranges, opening addressable patient pools previously excluded from laser protocols.
Market Restraints
- Consumables cost concentration:Single-source sapphire crystal handpiece suppliers in Germany control pricing for premium laser delivery systems, squeezing clinic margins.
- Radiofrequency substitution threat:Non-light energy modalities are capturing Fitzpatrick Type V-VI patient segments where laser-induced post-inflammatory hyperpigmentation risk deters adoption.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations for Class IIa energy devices are extending recertification timelines and documentation costs.
Strategic Opportunities
- Indian tier-2 city penetration:Underdeveloped dermatology infrastructure in cities like Indore and Kochi presents first-mover positioning for fractional laser service models.
- Home-use adjuvant device convergence:Pairing in-clinic treatments with LED mask protocols creates recurring revenue streams through consumable topical coupling systems.
- South Korea MFDS fast-track designation:Breakthrough device status for AI-guided melanin depth mapping accelerates approval for integrated diagnostic-treatment platforms.
Industry Challenges
- Laser safety officer certification scarcity:Qualified medical physicists with ANSI Z136.3 training are concentrated in São Paulo and Seoul, constraining clinic expansion in secondary markets.
- Legacy EMR integration friction:Proprietary device software architectures resist interoperability with Epic and Cerner systems, complicating treatment documentation workflows.
- IP licensing complexity in fractional scanning:Patent thickets around micro-lens array designs are forcing manufacturers into costly cross-licensing arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperpigmentation Treatment Devices Market |
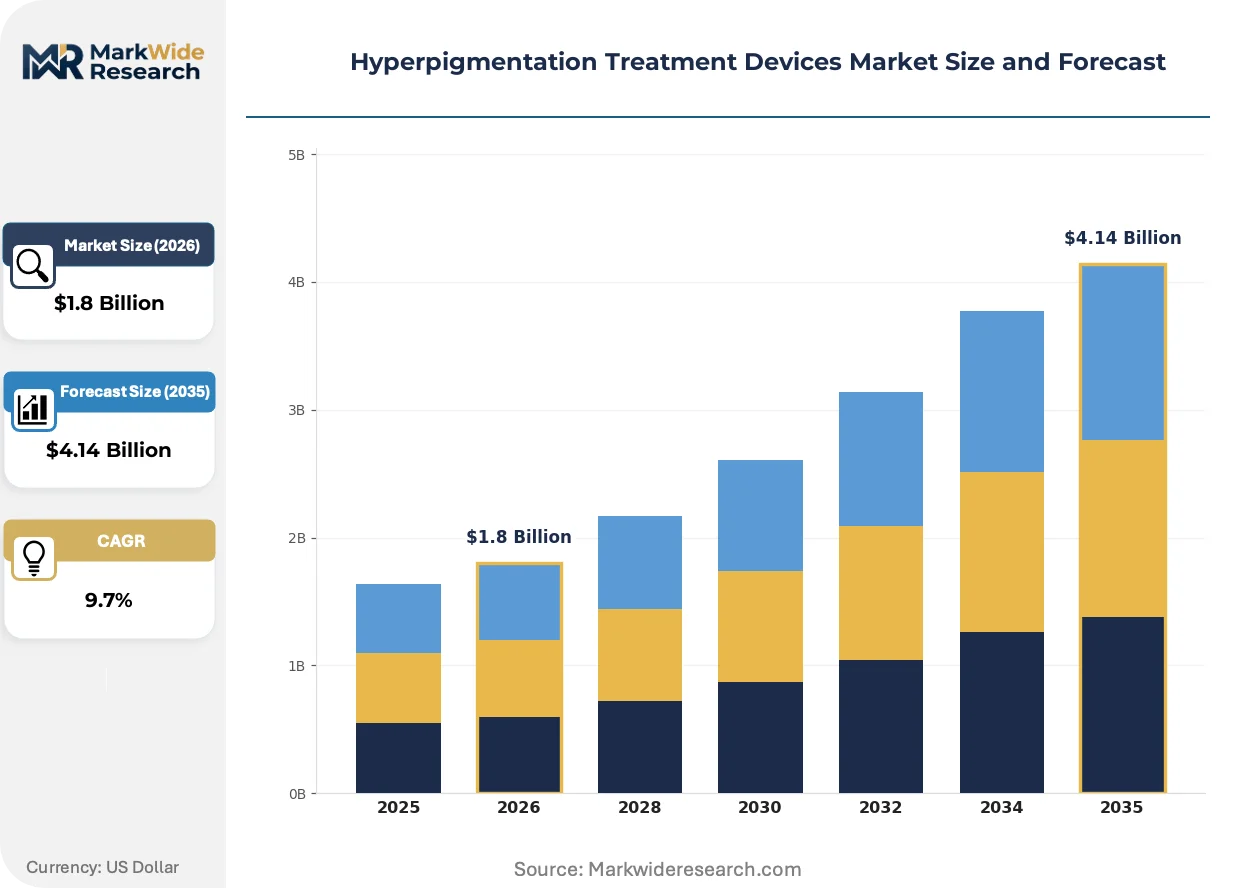
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Intense Pulsed Light, Radiofrequency Devices, Topical Treatments Application: Sun Damage, Melasma, Post-Inflammatory Hyperpigmentation, Age Spots End User: Dermatology Clinics, Medical Spas, Home Users, Hospitals Technology: Nanotechnology, Phototherapy, Chemical Peels, Microneedling |
| Companies Covered | Cutera, Cynosure Lutronic, Syneron Medical Ltd, Candela Corporation, Sciton, Hologic, Alma Lasers, Fotona, Lumenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperpigmentation Treatment Devices Market Strategic Shifts
Energy delivery architectures are fragmenting into componentized subsystems that clinics can reconfigure without full device replacement, reshaping capital deployment patterns across aesthetic medicine.
Picosecond Nd:YAG platforms are modularizing treatment parameter sets into downloadable protocol libraries. Dermatology groups in Texas and Florida are adopting quarterly subscription tiers that refresh clinical guidelines without hardware upgrades. This architecture is compressing manufacturer revenue recognition from upfront equipment sales into recurring service contracts.
EU MDR Annex XIV post-market clinical follow-up requirements are mandating real-world evidence collection for intense pulsed light systems. Device holders must now submit periodic safety update reports with patient-reported outcome data. Medium-sized manufacturers with limited pharmacovigilance infrastructure are outsourcing surveillance to specialized CROs in Ireland and the Netherlands.
After-sales service unbundling is disrupting traditional distributor relationships in Brazil. Clinica de Dermatologia São Paulo and similar large group practices are negotiating direct technical support contracts with manufacturers, bypassing local equipment dealers. This pattern is most visible in Rio de Janeiro state, where consolidated purchasing cooperatives command pricing leverage unavailable to independent practices.
Hyperpigmentation Treatment Devices Market Segmentation
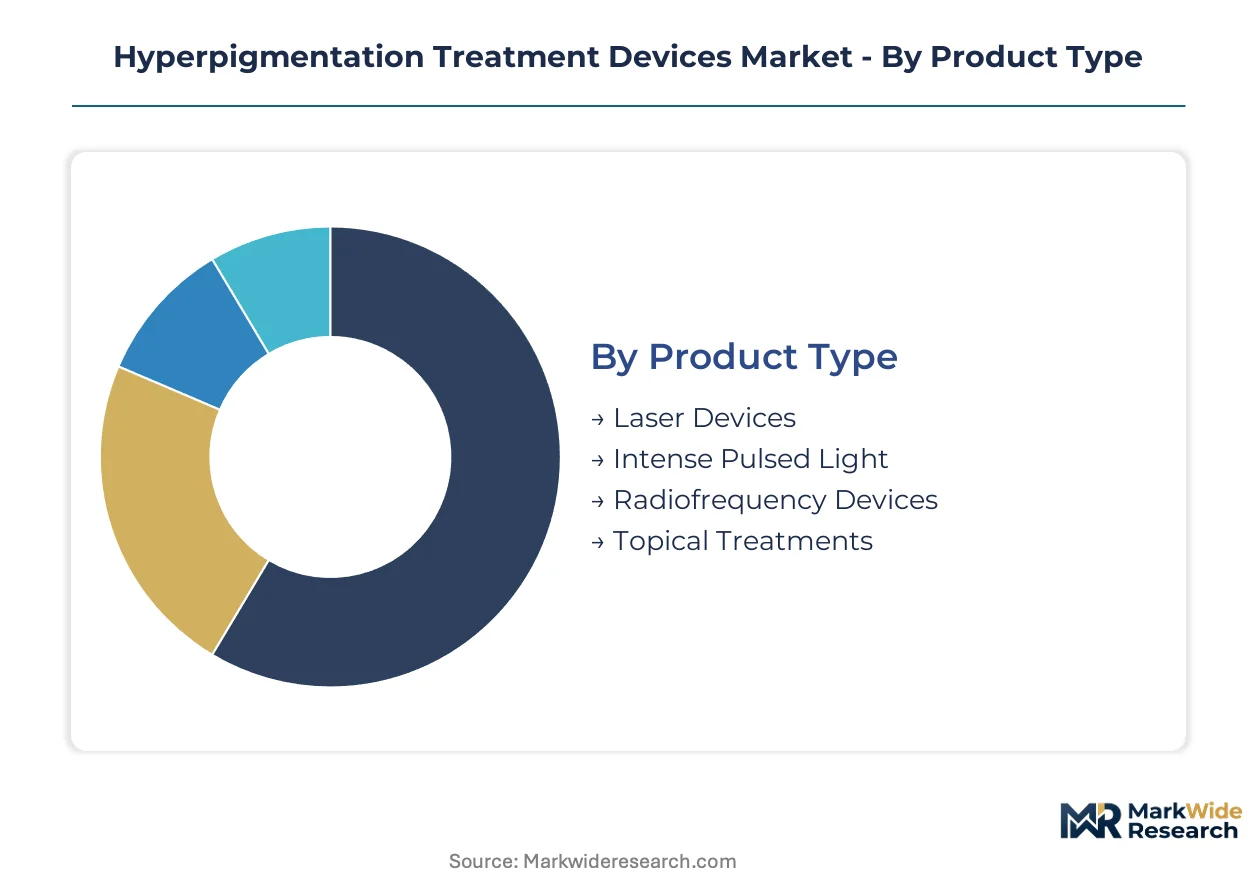
Energy modality selection determines capital intensity, consumable economics, and treatable patient populations across aesthetic medicine. Device manufacturers structure product portfolios around wavelength specificity, pulse duration control, and software-defined protocol libraries that reshape how clinics deploy treatment capacity.
Product Type:
Wavelength precision and thermal damage thresholds differentiate capital equipment categories, with melanin-selective absorption curves governing clinical efficacy across skin phototypes.
- Laser Devices:Solid-state and diode laser systems deliver monochromatic energy at 532 nm, 755 nm, or 1064 nm wavelengths with nanosecond to picosecond pulse widths. Dermatology clinics in São Paulo and Seoul concentrate procurement here, drawn by established reimbursement pathways and higher per-treatment pricing power.
- Intense Pulsed Light:Broadband flashlamp systems emit polychromatic energy across 500-1200 nm spectra, filtered for specific chromophore targeting. Medical spa chains in Brazil standardize on IPL for its lower capital entry point and reduced operator certification requirements.
- Radiofrequency Devices:Non-light energy modalities generate thermal coagulation through tissue impedance, eliminating melanin absorption competition. Demand concentrates among providers serving Fitzpatrick Type V-VI patient populations where laser-induced PIH risk constrains adoption.
- Topical Treatments:Prescription and cosmeceutical formulations containing hydroquinone, tranexamic acid, or cysteamine derivatives serve as standalone or adjuvant protocols. Home-use channels in South Korea and the United States drive volume through direct-to-consumer distribution.
Mature deployment sits with Laser Devices. Newer deployment is concentrated in Radiofrequency Devices.
Application:
Pathology-specific treatment protocols demand distinct energy parameters, with dermal-epidermal junction depth and melanin distribution patterns driving device configuration choices.
- Sun Damage:Solar lentigines and diffuse photodamage respond to 532 nm KTP laser or IPL protocols targeting superficial melanin deposits. Coastal dermatology markets in Florida and California concentrate demand, with seasonal treatment cycles peaking in post-summer months.
- Melasma:Recalcitrant dermal melanin deposition requires combination approaches pairing low-fluence laser with topical tyrosinase inhibitors. Latin American clinics report higher case volumes due to genetic predisposition and ultraviolet exposure patterns.
- Post-Inflammatory Hyperpigmentation:Trauma-induced melanin overproduction demands conservative energy settings and extended treatment intervals. Radiofrequency modalities are gaining share fastest in this segment among providers serving darker skin phototypes.
- Age Spots:Seborrheic keratoses and benign pigmented lesions respond to single-treatment laser ablation or cryotherapy alternatives. Geriatric-focused aesthetic practices in Japan and Germany concentrate procedural volume.
Volume concentration rests with Sun Damage. Steepest expansion trajectory belongs to Post-Inflammatory Hyperpigmentation as provider confidence in darker skin protocols improves.
End User:
Capital availability, regulatory licensing requirements, and patient throughput economics segment the customer base into distinct procurement behavior patterns.
- Dermatology Clinics:Board-certified practices prioritize FDA 510(k)-cleared devices with established clinical evidence packages and malpractice insurance compatibility. These accounts drive premium pricing and multi-system purchases.
- Medical Spas:Non-physician supervised aesthetic centers concentrate demand for IPL and lower-cost laser platforms with simplified operator interfaces. Brazilian chains like Corpo Dourado negotiate enterprise pricing through consolidated purchasing cooperatives.
- Home Users:Consumer-grade LED masks and microcurrent devices serve maintenance protocols between professional treatments. South Korean e-commerce platforms and U.S. direct-to-consumer brands dominate distribution.
- Hospitals:Academic medical centers and integrated health systems acquire devices for dermatology residency training and complex case referral networks. Procurement flows through centralized capital equipment committees with extended evaluation cycles.
Revenue concentration aligns with Dermatology Clinics. Account growth is accelerating fastest in Medical Spas as franchise models proliferate.
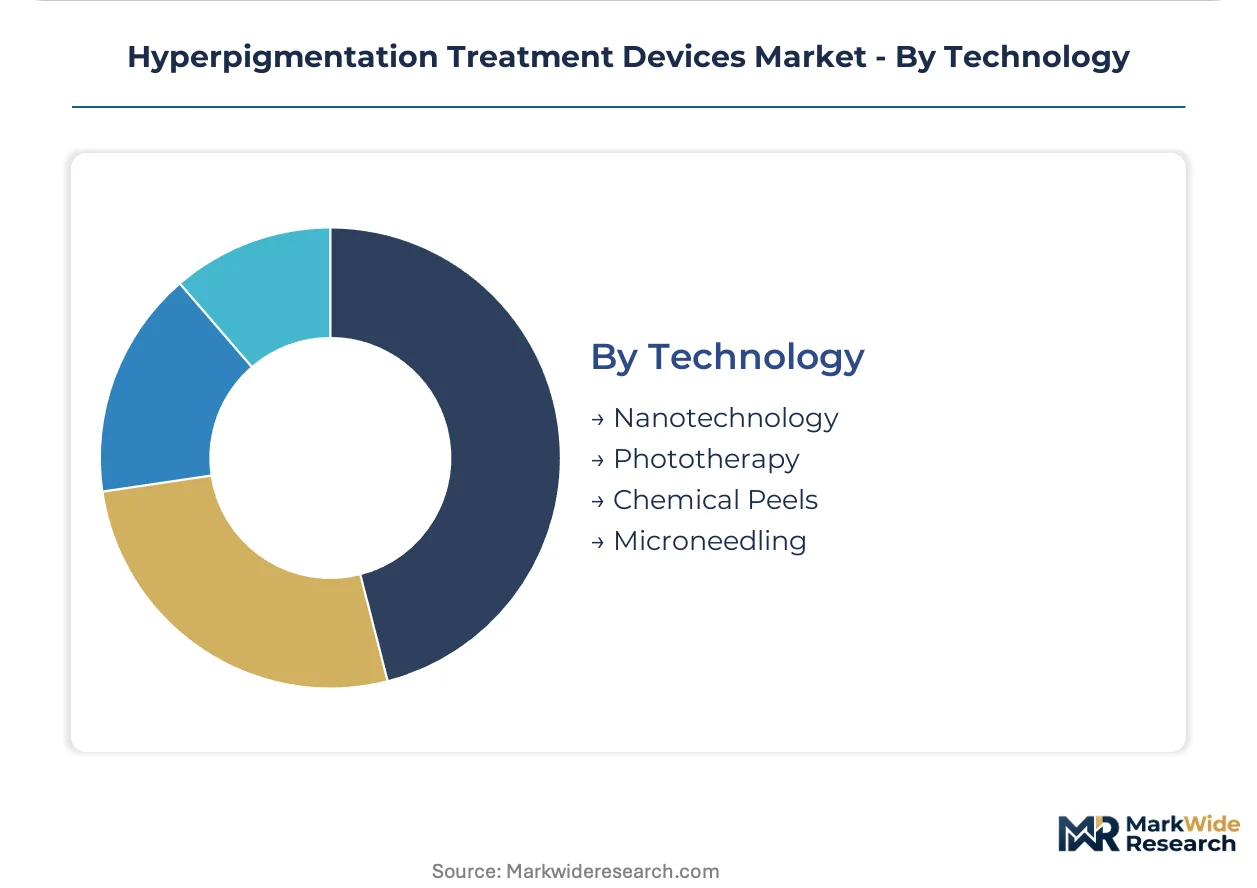
Technology:
Adjuvant and standalone modalities complement energy-based devices, creating protocol ecosystems that manufacturers bundle for competitive differentiation.
- Nanotechnology:Liposomal and nanoemulsion delivery systems enhance transepidermal penetration of depigmenting agents. Korean and Japanese topical manufacturers lead formulation innovation, supplying hybrid protocol demand from device companies.
- Phototherapy:Narrowband UVB and excimer laser systems serve vitiligo and resistant melasma cases in hospital-based dermatology departments. Regulatory clearance pathways differ from aesthetic laser categories.
- Chemical Peels:Superficial to medium-depth acid formulations (glycolic, salicylic, trichloroacetic) provide melanin dispersion through controlled epidermal injury. Medical spas deploy these as entry-level services with minimal equipment investment.
- Microneedling:Percutaneous collagen induction combined with topical infusion creates mechanical melanin disruption. Fractional radiofrequency microneedling devices are displacing standalone needling in premium clinic segments.
Established integration sits with Chemical Peels. Technology convergence is advancing fastest in Nanotechnology as device-topical hybrid protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors device procurement volumes across the Americas, with dermatology clinic chains consolidating purchasing power through cooperative networks that bypass traditional distributor markups.
United States
FDA 510(k) clearance timelines for laser systems with predicate device equivalence are compressing commercialization horizons for manufacturers with established installed bases. The agency intensifies scrutiny of software-controlled energy modulation features, demanding expanded premarket documentation for AI-guided parameter adjustment. Texas and Florida dermatology groups lead adoption of subscription-based protocol libraries that refresh clinical guidelines without hardware replacement.
Brazil
ANVISA electromagnetic compatibility benchmarks are converging toward IEC 60601-1-2 standards, complicating multi-regional product launches for manufacturers without localized testing infrastructure. Medical spa chains including Corpo Dourado and Clinica da Pele negotiate enterprise pricing through consolidated purchasing cooperatives. Rio de Janeiro state practices command pricing leverage unavailable to independent clinics through direct technical support contracts with manufacturers.
South Korea
MFDS fast-track designation for breakthrough devices accelerates approval timelines for AI-guided melanin depth mapping platforms. Seoul Capital Area dermatology clinics drive demand for integrated diagnostic-treatment systems that combine imaging with energy delivery. The regulator's convergence toward international electromagnetic compatibility standards enables faster parallel submissions in export markets.
Germany
EU MDR Annex XIV post-market clinical follow-up requirements mandate real-world evidence collection for intense pulsed light systems, extending recertification timelines. Medium-sized manufacturers outsource pharmacovigilance surveillance to specialized CROs in Ireland and the Netherlands. Bavarian sapphire crystal handpiece suppliers control pricing for premium laser delivery systems, squeezing downstream clinic margins across European markets.
India
Underdeveloped dermatology infrastructure in tier-2 cities including Indore and Kochi presents first-mover positioning for fractional laser service models. CDSCO device registration pathways remain fragmented across state-level import licensing requirements. Maharashtra and Karnataka urban clusters concentrate qualified laser safety officer training programs, constraining clinic expansion in secondary markets lacking ANSI Z136.3-certified medical physicists.
Hyperpigmentation Treatment Devices Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the device ecosystem, with solid-state laser foundries absorbing fixed costs while software-defined protocol developers capture recurring revenue streams. The vendor base stratifies into three tiers: integrated multinationals with full-wavelength portfolios, regional specialists dominating single-modality segments, and emerging platform players bundling diagnostic imaging with treatment delivery. Dominant competitive moves include installed-base upgrade campaigns that displace new system placements, and cross-licensing arrangements to navigate patent thickets around fractional scanning architectures.
Within the integrated multinational tier, Cutera and Alma Lasers exemplify divergent commercial strategies—one leveraging cloud-based parameter libraries for recurring clinic engagement, the other anchoring growth through installed-base upgrades rather than sole reliance on new capital equipment sales. Cynosure Lutronic occupies a position between these archetypes, with device naming conventions suggesting North American operational origins. These three entities collectively represent the competitive spectrum from hardware-centric to subscription-model positioning across dermatology clinic procurement channels.
| Leading Market Players |
|---|
| Cutera |
| Cynosure Lutronic |
| Syneron Medical Ltd |
| Candela Corporation |
| Sciton |
| Hologic |
| Alma Lasers |
| Fotona |
| Lumenis |
| Others |
Value Chain & Pricing Dynamics
Subscription protocol commitments from Texas and Florida dermatology groups are forcing manufacturers to restructure revenue recognition from upfront equipment sales toward recurring service contracts, compressing hardware replacement cycles and redistributing margin capture across multi-year engagement horizons.
Pricing Analysis
Margin tightening in premium laser tiers reflects sapphire crystal handpiece single-source dependency from Bavarian suppliers. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared systems with full clinical evidence packages from IPL platforms with simplified operator interfaces and consumer-grade LED masks. Cost-down pressure on mid-range systems accelerates because Brazilian medical spa chains negotiate enterprise pricing through consolidated purchasing cooperatives. Medical spas exhibit highest price sensitivity due to capital constraints and non-physician supervision licensing, while academic medical centers demonstrate lowest sensitivity given centralized capital equipment committee procurement.
Supply Chain Analysis
Direct-to-clinic technical support contracts bypass traditional distributor markups in Rio de Janeiro state. Manufacturing concentration rests on Germany for precision optical components, South Korea for AI-guided imaging subsystems, and the United States for solid-state laser foundries. Device assembly draws from Japanese nanotechnology topical suppliers, Italian fractional scanning micro-lens fabricators, and Taiwanese semiconductor controllers. Single-source vulnerability around German sapphire crystal suppliers constrains margin flexibility for premium laser delivery systems. Distribution runs through consolidated purchasing cooperatives in Brazil, direct manufacturer relationships in Seoul Capital Area, and traditional medical equipment dealers in Indian tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Annex XIV post-market clinical follow-up requirements erect substantial compliance infrastructure barriers that favor incumbent device holders with established pharmacovigilance capabilities over capital-constrained challengers.
For Market Incumbents: Hedge against radiofrequency substitution threats by securing backward integration into AI-guided melanin depth mapping software rather than sole reliance on hardware refresh cycles. Defend installed-base positions through cloud-based parameter library subscriptions that lock dermatology clinics into recurring engagement. Prioritize certification investment for ANSI Z136.3 laser safety officer training programs to constrain competitor expansion in secondary markets lacking qualified medical physicists. For New Entrants and Emerging Players: Medical spa chains in Brazil represent the most penetrable channel archetype given their consolidated purchasing cooperatives and appetite for lower capital entry points. Target post-inflammatory hyperpigmentation protocols for Fitzpatrick Type V-VI patient populations where provider confidence in darker skin laser protocols remains underdeveloped. Pursue white-space positioning in Indian tier-2 cities through fractional laser service models that circumvent laser safety officer certification scarcity constraining incumbent expansion. For Investors and Strategic Acquirers: The window for entry favors software-defined protocol developers with recurring revenue streams over capital-heavy hardware manufacturers facing compressed replacement cycles. Platform players bundling diagnostic imaging with treatment delivery offer superior long-term viability given convergence toward integrated diagnostic-treatment systems. Monitor MFDS fast-track designation approvals for AI-guided platforms as signal of regulatory pathway efficiency enabling faster parallel submissions in export markets.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Cloud-based parameter libraries sustain recurring engagement with dermatology clinics beyond hardware sales. |
| CE Marking Pathway | EU MDR Annex XIV compliance infrastructure filters out capital-constrained competitors from European markets. |
| Hospital System Partnership | Academic medical center procurement committees anchor premium pricing for FDA 510(k)-cleared devices. |
| Reimbursement Strategy | Established clinical evidence packages enable malpractice insurance compatibility for board-certified practices. |
| Regulatory Approval Pathway | MFDS fast-track designation accelerates market entry for AI-guided melanin depth mapping platforms. |
Study Parameters
Independent corroboration across FDA 510(k) clearance databases, EU MDR notified body documentation, and ANVISA electromagnetic compatibility filings underwrites the qualitative findings. Primary interviews with dermatology clinic procurement directors, biomedical engineers configuring laser safety protocols, GPO contracts managers at hospital systems, and medical spa chain operations executives combined with secondary validation from SEC 10-K filings of listed device manufacturers, customs import records for optical components, and patent databases tracking fractional scanning architectures. Bottom-up installed-base estimates and top-down addressable patient population calculations triangulate market sizing.
Comparable-period anchoring to historical predicate device equivalence approvals and software-controlled energy modulation feature introductions shaped the projection horizon. Segmentation modeling spans energy modality, treatable skin phototype range, end-user capital availability, and regulatory clearance tier across the analysis window. CAGRs derive from fitted adoption curves calibrated to clinic expansion rates in named metropolitan clusters and medical spa franchise proliferation patterns. Forecast inputs incorporate laser safety officer training program capacity constraints and sapphire crystal supplier pricing leverage.
Several conditions sit outside the modeled scope, including abrupt FDA guidance shifts on AI-driven skin analysis tool classification, tariff disruptions affecting German optical component imports, and pandemic-related clinic capacity constraints. Forecasts reflect documented assumptions regarding software-defined protocol subscription conversion rates and electromagnetic compatibility standard convergence timelines. Practitioners should monitor MFDS breakthrough device designation velocity and Brazilian purchasing cooperative negotiation outcomes for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Stool Management Systems Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Critical Care Devices Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Blood Lancet Market
Medical Devices
Infertility Devices Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Australia Spinal Surgery Devices Market