
 Next Generation Ultrasound Systems Market | 2026-2036
Next Generation Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Ultrasound Systems Market Foresight
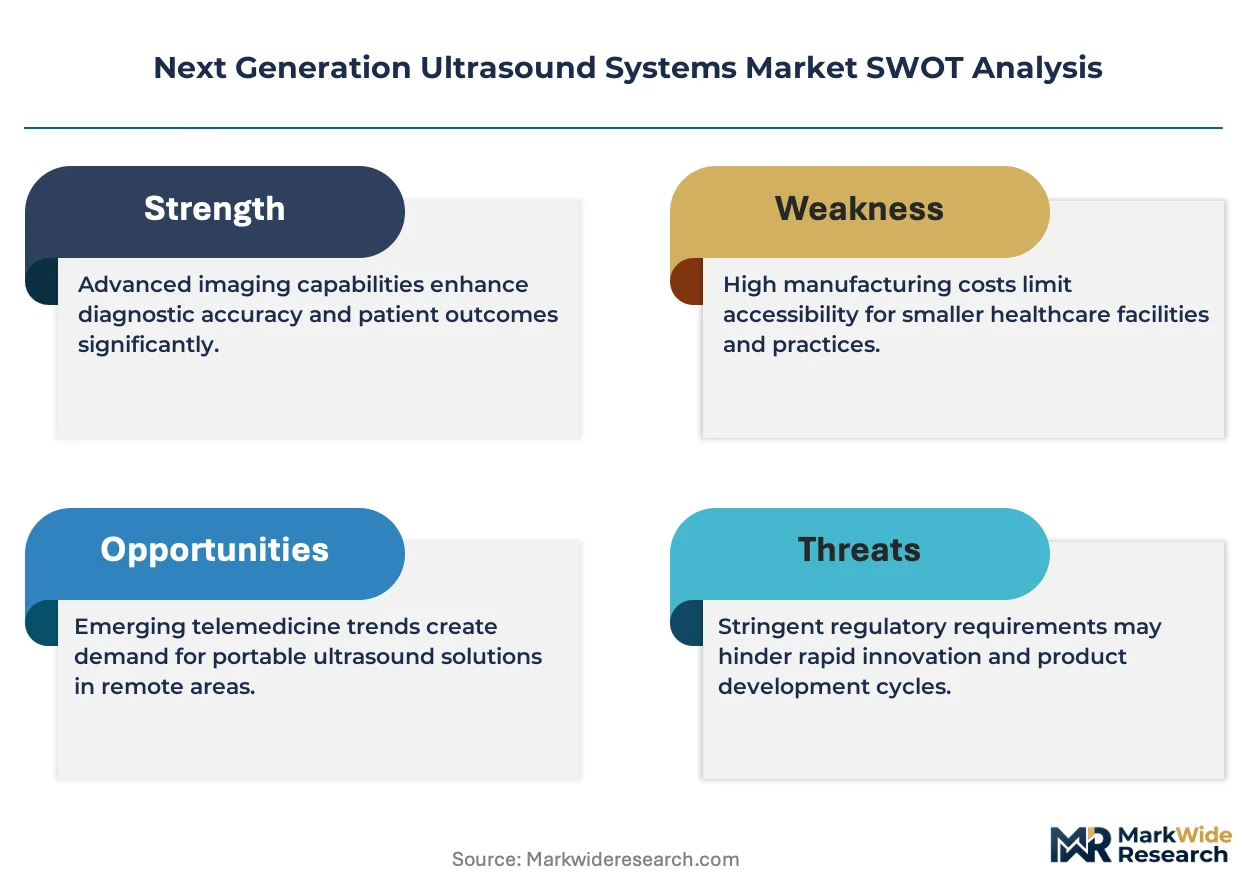
Silicon-based transducer materials is shifting toward capacitive micromachined ultrasound transducers (CMUTs) in premium system tiers, reducing manufacturing cost curves while preserving image fidelity. GE Healthcare leverages in-house semiconductor fabrication to anchor its console ultrasound portfolio. Siemens Healthineers differentiates through AI-integrated workflow software across its 4D imaging platforms. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. competes aggressively on portable system cost structures in emerging markets.
Next generation ultrasound systems integrate piezoelectric or CMUT arrays operating at 1-15 MHz with beamforming processors and AI-assisted reconstruction algorithms to generate real-time anatomical and functional images for diagnostic decision-making. Console ultrasound retains the dominant share of revenue pools due to premium pricing and comprehensive modality coverage, while handheld ultrasound exhibits the fastest expansion trajectory as semiconductor miniaturization collapses form factors. Contrast-enhanced ultrasound commands disproportionate margins in cardiology and oncology workflows where tissue perfusion assessment drives clinical value.
The FDA's software-as-a-medical-device pathway and the EU MDR's post-market surveillance requirements shape validation timelines and commercial access for AI-enabled ultrasound platforms. Japan's PMDA and China's NMPA impose distinct clinical evidence standards that fragment regulatory strategy for multinational vendors. Stakeholders must monitor how national reimbursement decisions for point-of-care ultrasound categories reshape deployment economics across health system tiers.
Market Dynamics
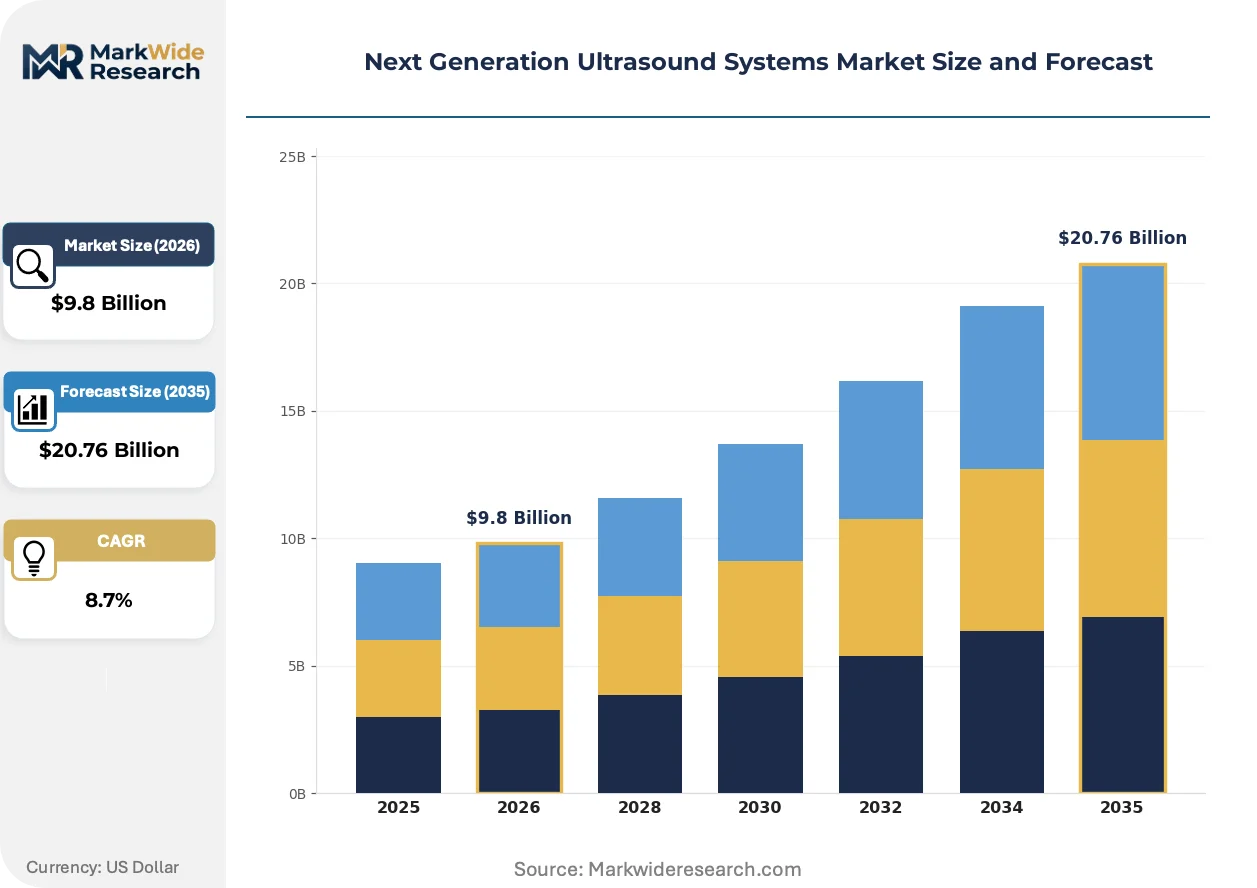
CMUT semiconductor fabrication is compressing transducer costs while FDA software-as-a-medical-device clearances accelerate AI diagnostic deployment timelines, forcing incumbents to restructure R&D allocation toward algorithmic differentiation.
Growth Catalysts
- Point-of-care network expansion:Health systems in the United States, Germany, and China are deploying portable ultrasound clusters in emergency departments and ambulatory surgical centers to reduce imaging bottlenecks.
- FDA software-as-a-medical-device pathway:Streamlined 510(k) clearances for AI-enabled diagnostic algorithms reduce validation timelines and unlock reimbursement codes for automated measurement tools.
- CMUT transducer maturation:Capacitive micromachined ultrasound transducers manufactured on silicon wafers cut per-channel costs by half while preserving bandwidth for harmonic imaging.
Market Restraints
- EU MDR post-market surveillance burden:Enhanced clinical follow-up requirements for Class IIa and above devices extend recertification cycles and inflate quality management system costs.
- Gallium nitride wafer supply concentration:Premium beamforming processors depend on substrates sourced from a concentrated foundry base in East Asia, creating input vulnerability.
- Acoustic impedance matching limitations:Conventional backing materials constrain bandwidth in portable form factors, capping image quality gains against console systems.
Strategic Opportunities
- Rural India penetration gap:District hospital networks lack imaging infrastructure; low-cost handheld systems with telemedicine integration address 600-million-plus uncovered populations.
- Contrast-enhanced oncology workflows:Microbubble perfusion imaging for liver and renal lesion characterization commands premium pricing in tertiary cancer centers.
- ISO 13485:2016 harmonization:Unified quality management standards across notified bodies reduce duplicate audit costs for multinational manufacturers.
Industry Challenges
- Deep learning validation engineering scarcity:FDA predicate device strategies for AI algorithms require specialized regulatory science talent that pools in Boston and San Francisco hubs.
- Installed base interoperability friction:DICOM-RT and HL7-FHIR integration with legacy PACS architectures delays enterprise deployment of cloud-native ultrasound platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Ultrasound Systems Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Console Ultrasound, Handheld Ultrasound, Micro Ultrasound Technology: 3D Imaging, 4D Imaging, Doppler Ultrasound, Contrast-enhanced Ultrasound End User: Hospitals, Diagnostic Centers, Clinics, Research Institutes Application: Cardiology, Obstetrics, Abdominal Imaging, Musculoskeletal |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., FUJIFILM Holdings Corporation, Hitachi, Ltd., Butterfly Network, Inc., TeraTech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Ultrasound Systems Market Shifts & Advancements
Semiconductor miniaturization and algorithmic reconstruction are collapsing the performance gap between handheld and console architectures, while regulatory pathways for autonomous diagnostic software rewrite competitive moats.
CMUT arrays fabricated on 200-millimeter silicon wafers are modularizing transducer supply chains by enabling MEMS foundries to produce acoustic elements alongside inertial sensors and RF components. Cardiology departments in German university hospitals are piloting these devices for bedside hemodynamic assessment. The technology is modularizing procurement decisions by decoupling transducer performance from piezoelectric ceramic supply constraints.
The FDA's software-as-a-medical-device framework is compressing validation timelines for AI-enabled left-ventricular ejection fraction algorithms. Manufacturers now submit standalone software updates without hardware recertification. Cardiovascular imaging suites in the United States are the primary adopters, restructuring service contracts to include algorithmic enhancement subscriptions.
Hospital procurement committees are unbundling hardware acquisition from service agreements, compressing vendor lock-in durations. Group purchasing organizations negotiate direct software licenses with AI developers, bypassing traditional OEM distribution. This pattern is most visible in United States integrated delivery networks where capital committees prioritize interoperability over single-source bundling.
Next Generation Ultrasound Systems Market Segmentation
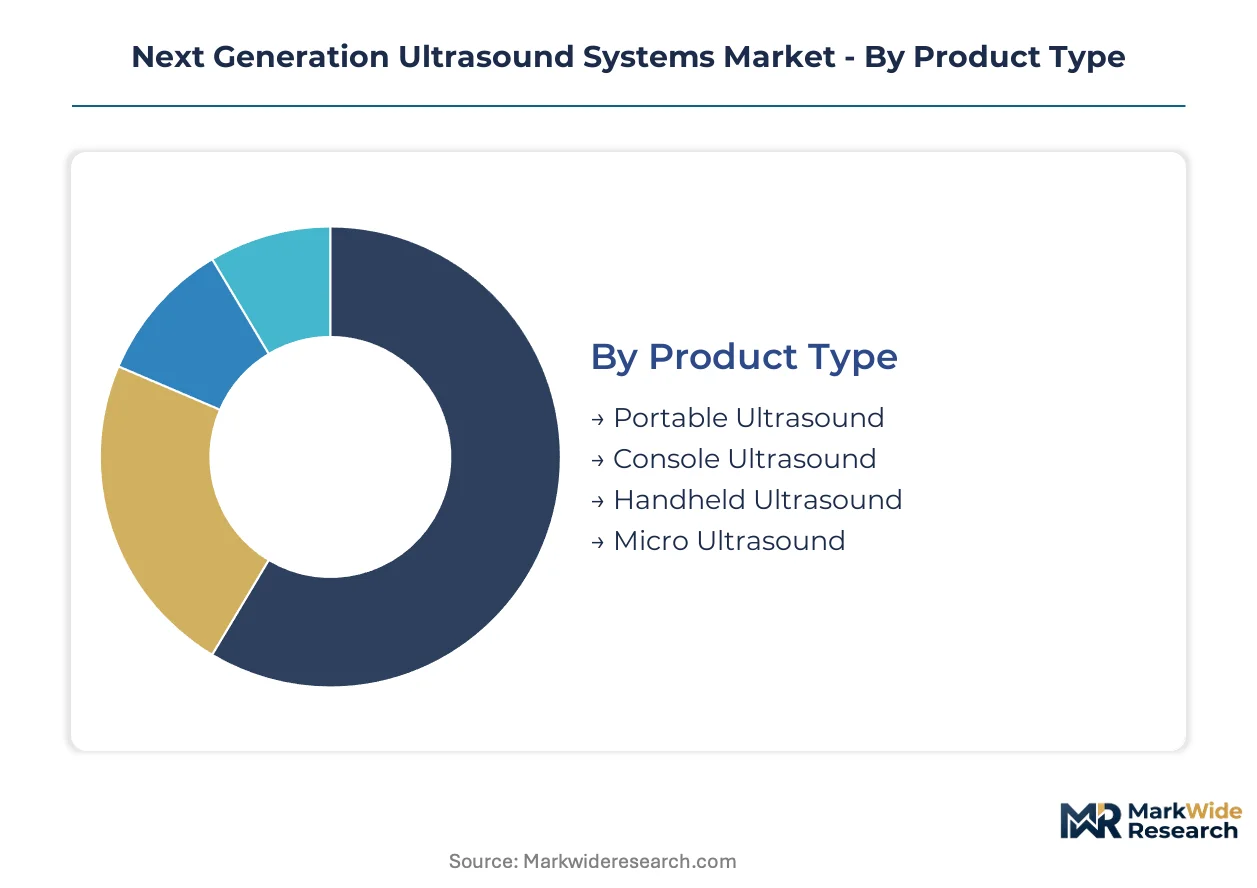
Segmentation in next generation ultrasound systems reveals divergent margin structures across hardware form factors and imaging modalities. Procurement committees weight capital intensity against clinical throughput, while regulatory pathways vary sharply by technology type.
Product Type:
Console systems command premium pricing through comprehensive transducer arrays, while portable and handheld architectures capture volume through semiconductor miniaturization.
- Console Ultrasound:Full-featured systems integrate 128+ channel beamformers with specialized transducers for cardiology and obstetrics. Tertiary hospitals in the United States and Germany anchor procurement, driven by replacement cycles for aging installed bases and AI-integrated workflow demands.
- Portable Ultrasound:Battery-powered cart-based systems deliver 80% of console image quality at 40% of the footprint. Emergency departments in China and ambulatory surgical centers in Germany deploy these in point-of-care networks to reduce radiology department bottlenecks.
- Handheld Ultrasound:Smartphone-connected probes collapse form factors to pocket size. District hospitals in India and rural clinics in China adopt these for telemedicine-linked triage where capital budgets exclude console systems.
- Micro Ultrasound:Sub-millimeter resolution systems target preclinical research and dermatology applications. Academic medical centers in Japan and specialized dermatology clinics in Germany represent the concentrated demand base.
Mature deployment sits with Console Ultrasound. Newer deployment is concentrated in Handheld Ultrasound.
Technology:
Algorithmic reconstruction capabilities separate premium tiers from standard imaging, with regulatory clearances creating distinct commercial access timelines.
- 4D Imaging:Real-time volumetric acquisition with spatiotemporal resolution enables fetal cardiac assessment and interventional guidance. Maternal-fetal medicine departments in the United States and Germany drive replacement demand, constrained by premium pricing and specialized operator training requirements.
- Contrast-enhanced Ultrasound:Microbubble perfusion imaging delivers radiation-free tissue characterization for liver and renal lesions. Oncology centers in Germany and cardiology departments in the United States command premium reimbursement for these workflows where tissue perfusion assessment replaces CT or MRI.
- 3D Imaging:Static volumetric reconstruction supports surgical planning and volume measurement. General imaging departments in China deploy these for abdominal and obstetric applications where real-time 4D capabilities exceed clinical need.
- Doppler Ultrasound:Frequency-shift detection maps blood flow velocity and direction. Vascular surgery and cardiology units across hospital tiers standardize on this modality for hemodynamic assessment.
Established clinical validation sits with Doppler Ultrasound. Accelerating regulatory clearance is concentrating in Contrast-enhanced Ultrasound.
End User:
Capital availability and patient throughput determine procurement specifications, with reimbursement codes shaping deployment economics across facility types.
- Hospitals:Integrated health systems in the United States and university hospitals in Germany deploy mixed fleets of console and portable systems across cardiology, emergency, and critical care departments. AI-enabled diagnostic tools and enterprise PACS integration drive replacement cycles.
- Diagnostic Centers:Dedicated imaging facilities in China and India optimize throughput with mid-tier portable systems. Volume-based reimbursement models favor rapid patient turnover over premium image resolution.
- Clinics:Primary care and specialty clinics in Germany and the United States adopt handheld systems for point-of-care triage. Capitated payment structures reward rapid diagnostic confirmation without referral delays.
- Research Institutes:Preclinical and clinical research centers in Japan and the United States procure micro-ultrasound and high-frequency systems for pharmaceutical development and device validation studies.
Consolidated purchasing power sits with Hospitals. Expanding point-of-care deployment is concentrating in Clinics.
Application:
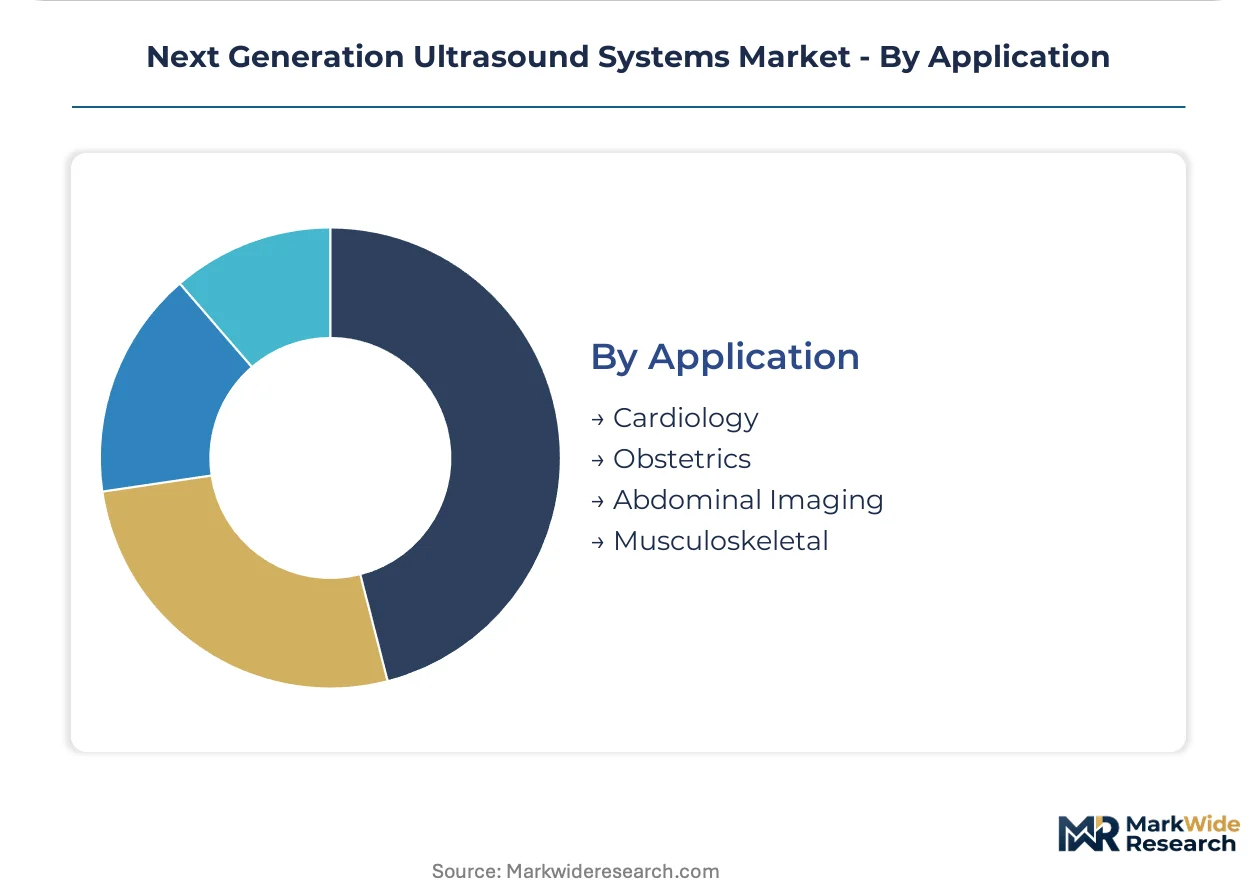
Clinical workflow requirements dictate transducer specifications and software feature sets, with cardiology and obstetrics representing the highest-value use cases.
- Cardiology:Echocardiography demands phased-array transducers and specialized quantification software for left-ventricular function assessment. Cardiovascular departments in the United States and Germany lead AI-enabled automation adoption, with FDA 510(k) clearances for ejection fraction algorithms accelerating deployment.
- Obstetrics:Fetal imaging requires high-resolution linear and curvilinear transducers with 4D reconstruction capabilities. Maternal health networks in China and specialized women's hospitals in Germany invest in these systems where perinatal screening programs drive volume.
- Abdominal Imaging:General-purpose curvilinear transducers address liver, renal, and gallbladder assessment. Community hospitals and diagnostic centers across geographies standardize on these workflows for bread-and-butter radiology volume.
- Musculoskeletal:High-frequency linear transducers visualize tendons, ligaments, and peripheral nerves. Sports medicine clinics in the United States and orthopedic departments in Germany deploy these for injection guidance and injury assessment.
Reimbursement stability sits with Abdominal Imaging. Technology differentiation is concentrating fastest in Cardiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health systems in the United States, Germany, and China concentrate procurement of next generation ultrasound systems, driven by point-of-care network expansion and replacement cycles for aging installed bases. Regulatory pathways in these markets reshape product development priorities for multinational vendors.
United States
Cardiovascular imaging suites drive replacement demand for AI-enabled console systems. FDA software-as-a-medical-device clearances compress validation timelines for automated ejection fraction algorithms. Boston and San Francisco hubs concentrate regulatory science talent for deep learning validation engineering.
Germany
University hospitals in Bavaria and Baden-Württemberg pilot CMUT-based bedside hemodynamic assessment devices. EU MDR post-market surveillance requirements extend recertification cycles for Class IIa and above devices. The Eindhoven-to-Munich corridor anchors semiconductor fabrication partnerships for transducer supply chains.
China
Emergency departments deploy portable ultrasound clusters to reduce radiology bottlenecks in tier-one cities. NMPA imposes distinct clinical evidence standards that fragment multinational regulatory strategies. Shenzhen and Shanghai industrial zones concentrate domestic manufacturing of cost-optimized handheld systems for rural telemedicine networks.
Japan
Academic medical centers in Tokyo and Osaka procure micro-ultrasound systems for preclinical pharmaceutical research. PMDA clinical evidence standards diverge from FDA pathways, requiring separate validation studies. The Kanto region concentrates specialized demand for high-frequency dermatology applications.
India
District hospital networks lack imaging infrastructure across Maharashtra and Karnataka states. CDSCO regulatory frameworks for software-as-a-medical-device remain under development, creating access uncertainty. Low-cost handheld systems with telemedicine integration address 600-million-plus uncovered populations in rural districts.
Next Generation Ultrasound Systems Market Competitive Landscape
Algorithmic differentiation dominates the current landscape as vendors restructure R&D allocation toward AI-enabled diagnostic capabilities. The vendor base concentrates around diversified medical technology conglomerates with captive semiconductor fabrication, tier-one imaging specialists with workflow software integration, and emerging cost-optimized portable system manufacturers. Strategic archetypes include premium console incumbents defending installed base positions, portable system challengers exploiting semiconductor miniaturization, and AI-native software developers seeking standalone regulatory clearances. Technology licensing and strategic partnerships represent the dominant competitive moves, with M&A activity targeting algorithmic capabilities and MEMS foundry access.
Among diversified medical technology conglomerates, GE Healthcare exemplifies the premium console archetype through in-house semiconductor fabrication control. Siemens Healthineers occupies a position emphasizing AI-integrated workflow software across imaging platforms. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the cost-optimized portable system challenger archetype competing aggressively in emerging markets. These three anchors illustrate divergent strategic vectors: captive supply chain control, algorithmic differentiation, and manufacturing cost structure optimization.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| FUJIFILM Holdings Corporation |
| Hitachi, Ltd. |
| Butterfly Network, Inc. |
| TeraTech Corporation |
| Others |
Supply & Pricing Matrix
Console-to-handheld performance bifurcation separates premium AI-integrated systems from cost-optimized portable units, with this divergence manifesting in both pricing power and supply chain configurations. Premium tiers command hardware-software bundled contracts with captive semiconductor fabrication, while handheld volumes flow through contract MEMS foundries in East Asia with minimal service attachment.
Pricing Analysis
Volume concentration in handheld systems runs against margin capture in console platforms. Three-tier pricing structure across premium, standard, and economy levels tracks AI algorithm integration depth and transducer channel count. Pricing pressure stems from Shenzhen-based manufacturers compressing portable system cost curves through CMUT wafer sourcing at scale. Diagnostic centers in India and China exhibit highest price sensitivity, while cardiovascular departments in German university hospitals accept premium positioning for FDA-cleared autonomous measurement tools.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam handle finished system warehousing for Asia-Pacific and European markets respectively. Transducer fabrication concentrates in Taiwan, South Korea, and the United States through 200-millimeter CMOS foundries. Gallium nitride substrates for beamforming processors draw from concentrated East Asian wafer suppliers. Single-source vulnerability sits with specialty acoustic backing materials sourced from Japanese chemical suppliers. Distribution runs through direct hospital procurement committees and group purchasing organizations in the United States, with OEM service contracts unbundling from hardware acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMUT semiconductor technology is displacing legacy piezoelectric ceramic transducers, rewriting cost structures and procurement patterns across all system tiers.
For Market Incumbents: To counter handheld challengers exploiting MEMS foundry commoditization, anchor premium console positions through in-house silicon fabrication control and AI algorithm subscription bundling. Lock hospital system relationships via enterprise PACS integration and FDA-cleared autonomous diagnostic software that raises switching costs. For New Entrants and Emerging Players: AI-native software modules cleared through FDA software-as-a-medical-device pathway offer the most penetrable wedge into cardiovascular imaging suites seeking algorithmic enhancement without hardware replacement. Target rural Indian district hospitals with telemedicine-integrated handheld systems priced below console depreciation thresholds, leveraging Shenzhen manufacturing partnerships for CMUT cost parity. For Investors and Strategic Acquirers: Re-rating potential sits with MEMS foundry specialists possessing CMUT process expertise given transducer supply chain modularization accelerating across premium tiers. Long-term viability favors algorithmic differentiation over hardware commoditization. Watch FDA 510(k) clearance velocity for autonomous ejection fraction algorithms as inflection indicator for AI-native software valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CMUT Foundry Partnership | Secures transducer supply chain independence from piezoelectric ceramic constraints. |
| FDA SaMD Clearance Pathway | Accelerates AI algorithm deployment without hardware recertification cycles. |
| Hospital System Partnership | Locks enterprise PACS integration and raises competitor switching costs. |
| Software Companion Development | Enables recurring revenue streams from algorithmic enhancement subscriptions. |
| Reimbursement Strategy | Secures CPT codes for autonomous measurement tools in cardiovascular workflows. |
Research Methodology
Document review covered FDA 510(k) clearances, EU MDR technical documentation, and NMPA registration filings, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and CMUT foundry operations directors. Secondary validation drew from SEC 10-K disclosures, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up unit shipment estimates triangulated against top-down healthcare capital expenditure surveys.
Segment-level outputs across product type, technology, end user, and application dimensions were generated through the projection horizon. CAGRs were derived from replacement cycle analysis of aging installed bases and point-of-care network expansion trajectories. Forecast inputs incorporated CMUT wafer yield improvements, FDA software-as-a-medical-device clearance velocity, and national reimbursement decisions for point-of-care categories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR recertification delays or gallium nitride supply disruptions. Outputs reflect documented assumptions around semiconductor miniaturization curves and regulatory pathway harmonization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Imaging Services Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Italy Mammography Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Gallium-68 Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
C-Arms Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Medical Image Analysis Software Market