
 Skin Rejuvenation Devices Market | 2026-2036
Skin Rejuvenation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Rejuvenation Devices Market Analytics
MDR is realigning the cost-of-entry calculus for device manufacturers seeking European market access, forcing substantial clinical evidence investments that favor well-capitalized incumbents. Lumenis leverages its vertical integration into laser source manufacturing to sustain margin structures under rising compliance burdens. Alma Lasers anchors its position through geographic dominance across Middle Eastern and Asian markets where regulatory harmonization remains fragmented. Cutera differentiates via specialized product architecture targeting the medical spa channel rather than hospital procurement.
Skin rejuvenation devices are energy-delivery systems that apply controlled thermal, light, or acoustic energy to dermal and epidermal tissue, typically operating at wavelengths between 532 nm and 10,600 nm or radiofrequency ranges of 1–40 MHz to stimulate collagen remodeling and cellular turnover. Their primary commercial purpose is to provide non-invasive or minimally invasive alternatives to surgical cosmetic procedures for skin texture, tone, and laxity improvement. Laser devices occupy the largest revenue pool due to established reimbursement pathways and physician familiarity, while radiofrequency devices represent the fastest-growing category as fractional delivery systems broaden treatable patient phenotypes. Home-use LED devices command lower per-unit pricing but expand addressable volume through direct-to-consumer channel penetration.
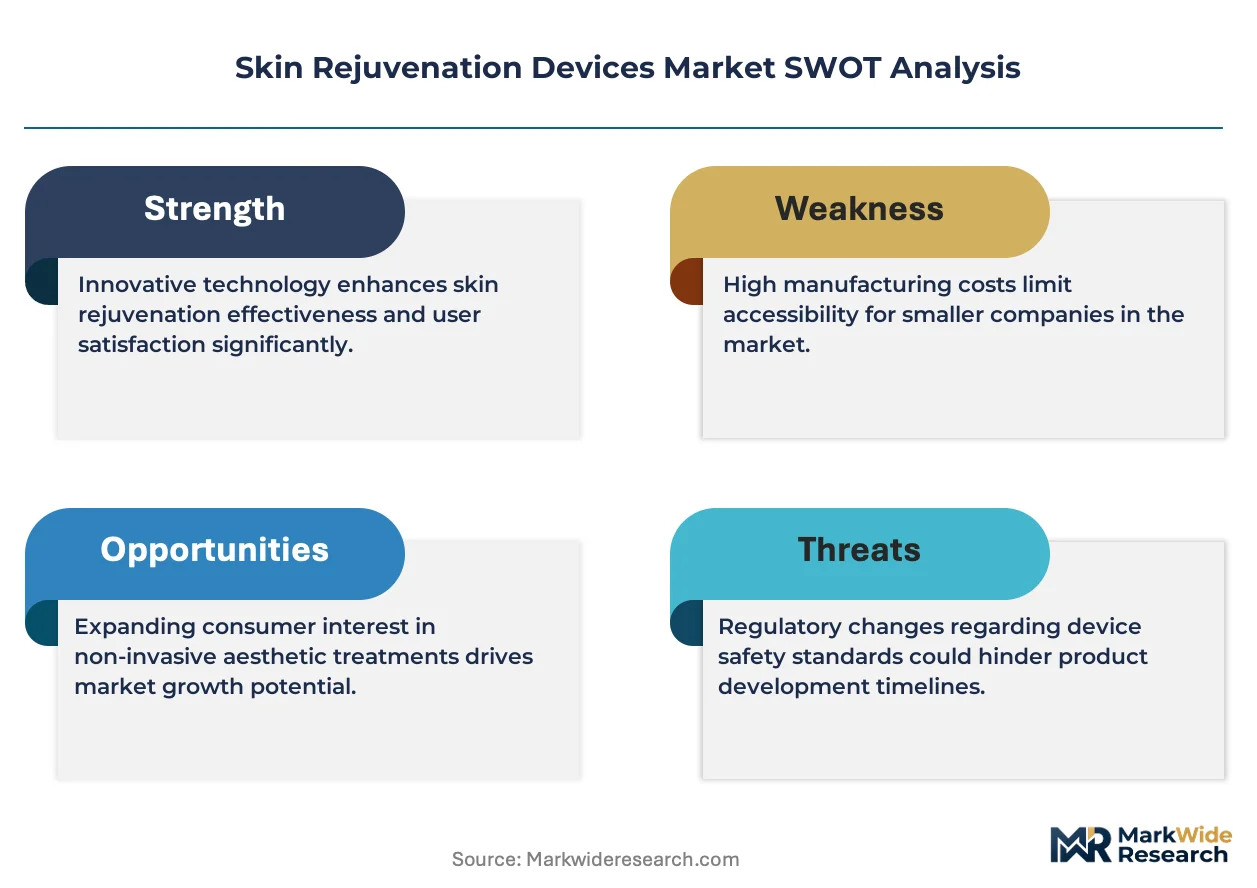
FDA, MDR, and ISO 13485 collectively shape product development timelines, with FDA 510(k) pathways demanding predicate device comparisons and MDR requiring post-market surveillance infrastructure that smaller manufacturers struggle to fund. The EU AI Act introduces additional algorithmic transparency obligations for devices incorporating real-time skin analysis or automated parameter adjustment. Stakeholders must monitor evolving notified body capacity constraints in Europe and FDA guidance on energy-based device reclassification that could compress approval timelines for novel modalities.
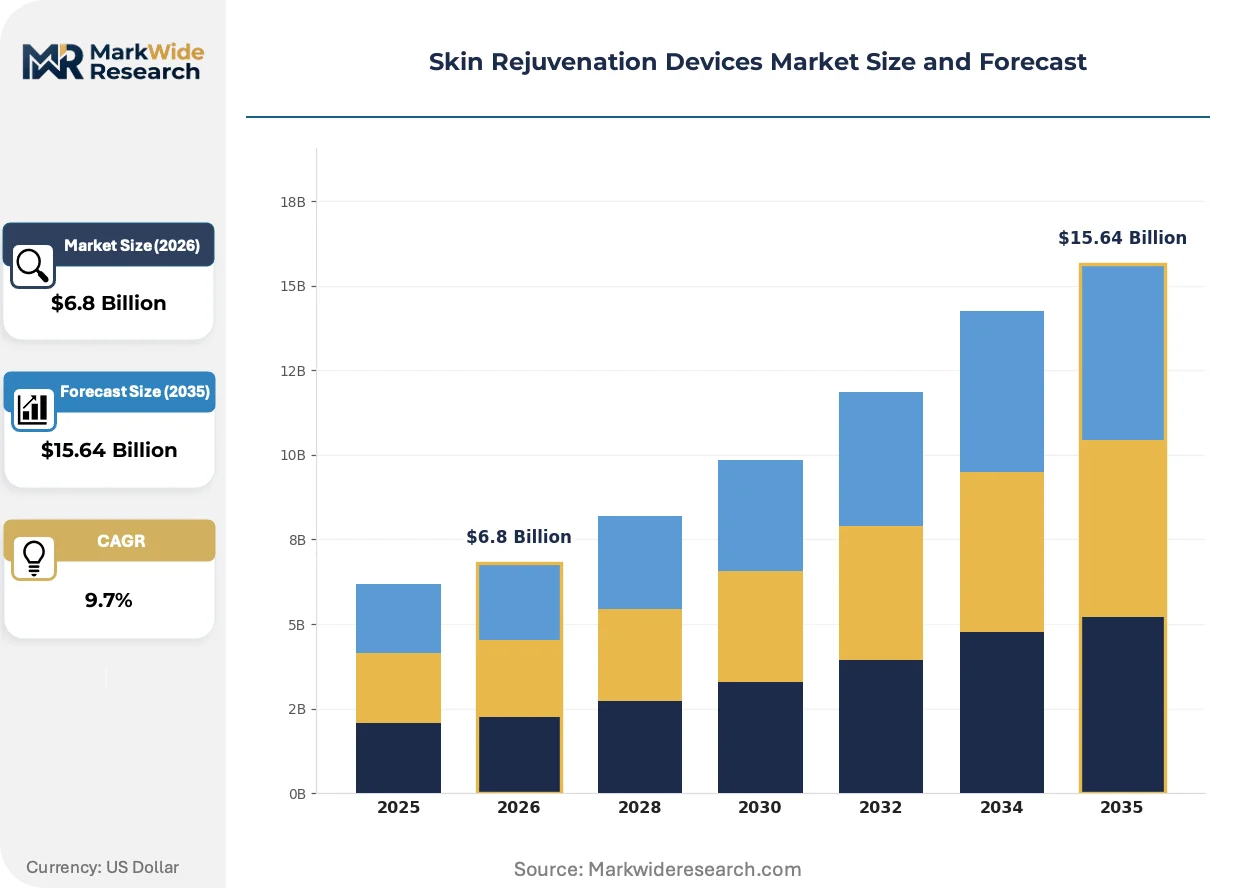
Market Dynamics
Fractional radiofrequency delivery systems are compressing treatment protocols from multi-session regimens to single-visit outcomes, forcing manufacturers to recalibrate device architecture around speed-to-result rather than cumulative efficacy metrics.
Growth Catalysts
- MFDS fast-track pathways:South Korea's streamlined premarket review for energy-based aesthetic devices accelerates commercialization timelines for novel fractional systems targeting the Gangnam clinic cluster.
- Medical spa channel expansion:US-based aesthetic chains are consolidating procurement power through group purchasing organizations, creating dedicated capital allocation pools for multi-platform installations.
- Collagen remodeling science:Published histological evidence from controlled trials now supports 3D volumetric assessment protocols, expanding reimbursable indications beyond cosmetic classification.
Market Restraints
- Premium laser source concentration:German and US suppliers control 80% of solid-state and fiber laser component output, exposing device OEMs to extended lead times and minimum order quantity escalation.
- MDR clinical evidence burdens:European notified bodies now mandate prospective post-market surveillance studies for Class IIb energy devices, requiring 3-5 year follow-up cohorts that exhaust mid-tier R&D budgets.
- Topical retinoid substitution:Prescription-grade tretinoin formulations at $30-50 monthly price points capture budget-conscious patients seeking texture improvement without capital expenditure.
Strategic Opportunities
- Brazilian private clinic networks:São Paulo and Rio de Janeiro aesthetic medicine groups are upgrading from IPL legacy systems, creating replacement demand for multi-wavelength platforms with integrated cooling.
- EU AI Act algorithmic transparency:Automated skin analysis modules with documented training data provenance qualify for expedited CE marking under the regulatory sandbox provisions.
- Home-use LED convergence:Wearable mask formats incorporating 633nm and 830nm diodes are capturing direct-to-consumer volume previously reserved for professional fractional treatments.
Industry Challenges
- Clinical application specialist scarcity:Device manufacturers struggle to recruit dermatologists with dual competency in laser physics and aesthetic practice management for field training roles.
- ISO 13485 transition complexity:Smaller OEMs face 18-24 month certification cycles to meet updated risk management and software lifecycle requirements for connected devices.
- Predicate device 510(k) erosion:FDA's tightened substantial equivalence standards for energy-based devices force novel indications toward de novo pathways with 12-18 month timeline extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Rejuvenation Devices Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, LED Devices, Radiofrequency Devices, Ultrasound Devices End User: Clinics, Hospitals, Home Users, Medical Spas Application: Wrinkle Reduction, Acne Scarring, Pigmentation Treatment, Skin Tightening Technology: Non-Ablative, Ablative, Microdermabrasion, Chemical Peels |
| Companies Covered | Lumenis, Cutera, Alma Lasers, Cynosure, Sciton, Fotona, Lutronic, InMode, Syneron Candela, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Rejuvenation Devices Market Evolving Landscape
Real-time thermal feedback integration is replacing fixed-parameter protocols, enabling personalized energy delivery that adapts to individual tissue impedance variations during treatment sessions.
Picosecond-domain laser systems with 755nm and 1064nm wavelength options are overtaking nanosecond Q-switched platforms for pigmented lesion and tattoo removal applications. US dermatology groups are standardizing procurement around these platforms to compress patient throughput times. The technology is overtaking legacy equipment in resale value calculations, with nanosecond system trade-in allowances collapsing by half.
The EU AI Act's algorithmic transparency mandates are forcing manufacturers to document training data provenance for real-time skin analysis modules. This documentation burden favors incumbent developers with established clinical image libraries. Class IIb devices incorporating automated parameter adjustment face the steepest compliance costs, with notified bodies requiring disclosure of edge-case failure modes.
After-sales service unbundling is disrupting traditional capital equipment contracts across US medical spa chains. Buyers now prefer per-treatment consumable pricing with separate maintenance subscriptions rather than bundled warranty structures. This preference shift concentrates in the Sun Belt states where seasonal demand volatility makes fixed cost commitments undesirable.
Skin Rejuvenation Devices Market Segmentation
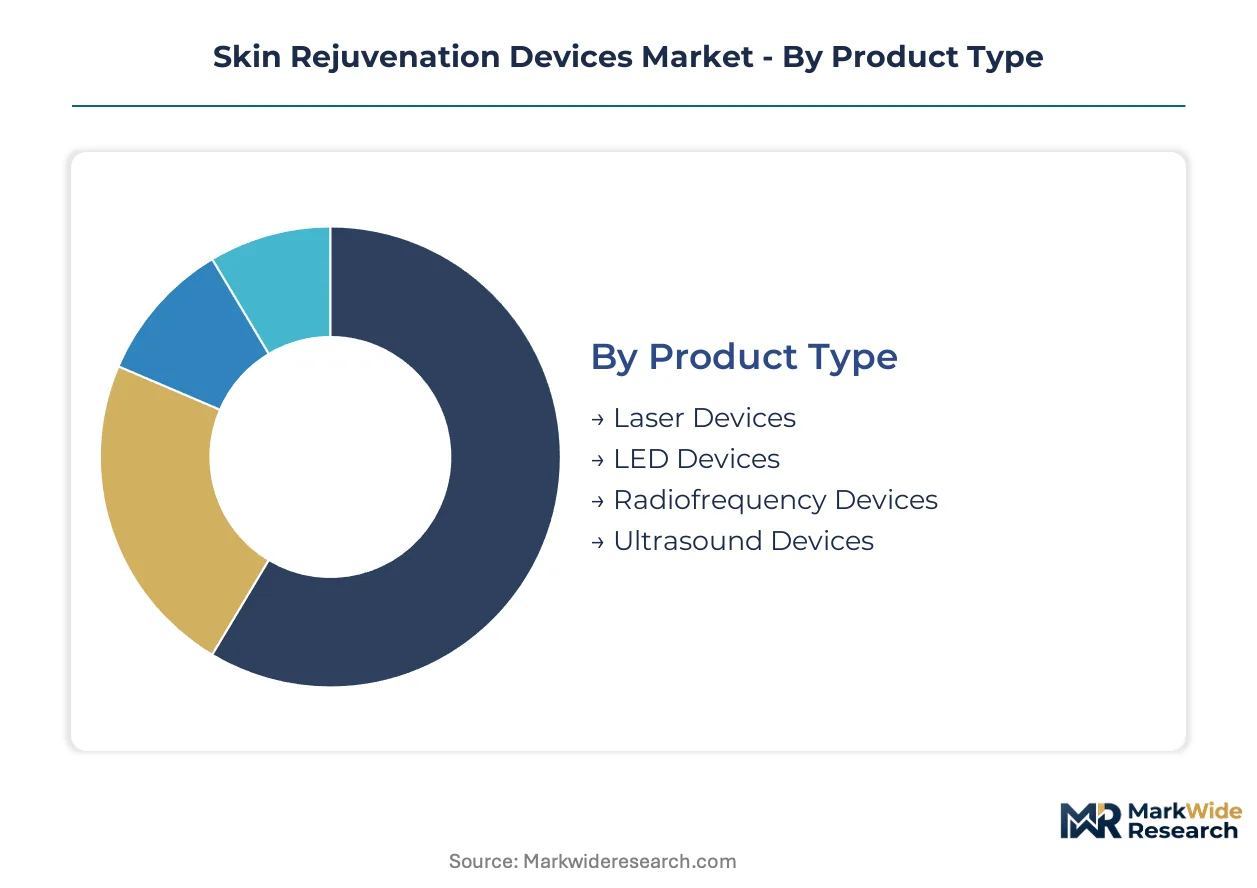
Energy-delivery specifications and treatment settings vary sharply across device categories, dictating capital intensity and regulatory classification. Procurement patterns in dermatology clinics diverge from medical spa chains based on reimbursement eligibility and patient throughput requirements.
Product Type:
Replacement cycles in aesthetic medicine are compressing as fractional delivery systems obsolete multi-session protocols, forcing clinic buyers to prioritize speed-to-result in capital planning.
- Laser Devices:Solid-state and fiber laser systems operating between 532 nm and 10,600 nm dominate hospital procurement through established reimbursement codes. US dermatology groups standardize around picosecond-domain platforms to compress patient throughput times.
- Radiofrequency Devices:Fractional RF systems with 1–40 MHz range are broadening treatable patient phenotypes through impedance-adaptive delivery. South Korea's Gangnam clinic cluster drives fastest upgrade velocity for these platforms.
- LED Devices:Wearable mask formats with 633nm and 830nm diodes capture direct-to-consumer volume.
- Ultrasound Devices:Microfocused ultrasound systems target deeper dermal layers for non-surgical lifting applications.
Laser Devices sits at the top of the volume ranking, with Radiofrequency Devices climbing the fastest.
End User:
Channel concentration in the United States reflects divergent capital allocation cycles between institutional buyers and independent aesthetic chains.
- Medical Spas:US-based aesthetic chains consolidate procurement through group purchasing organizations, creating dedicated capital pools for multi-platform installations. Sun Belt state operators prefer per-treatment consumable pricing over bundled warranties.
- Clinics:Dermatology and aesthetic medicine clinics in São Paulo and Rio de Janeiro are upgrading from IPL legacy systems, generating replacement demand for multi-wavelength platforms with integrated cooling.
- Hospitals:Academic medical centers prioritize devices with published histological evidence supporting reimbursable indications.
- Home Users:Direct-to-consumer LED mask penetration expands addressable volume at lower per-unit price points.
Medical Spas command the steepest equipment spend per outlet, while Home Users expand the addressable base most rapidly.
Application:
Clinical evidence requirements from FDA and MDR reshape which indications qualify for reimbursement versus cosmetic classification.
- Wrinkle Reduction:Collagen remodeling protocols with 3D volumetric assessment now support expanded reimbursable indications beyond cosmetic codes.
- Skin Tightening:Radiofrequency and ultrasound modalities concentrate demand in Middle Eastern markets where physician-operated clinic density exceeds hospital alternatives.
- Pigmentation Treatment:Picosecond-domain systems with 755nm and 1064nm options displace nanosecond platforms.
- Acne Scarring:Fractional laser and RF combinations target atrophic scar revision in Asian markets.
Wrinkle Reduction generates the largest procedure volume, with Skin Tightening gaining share fastest among younger patient cohorts.
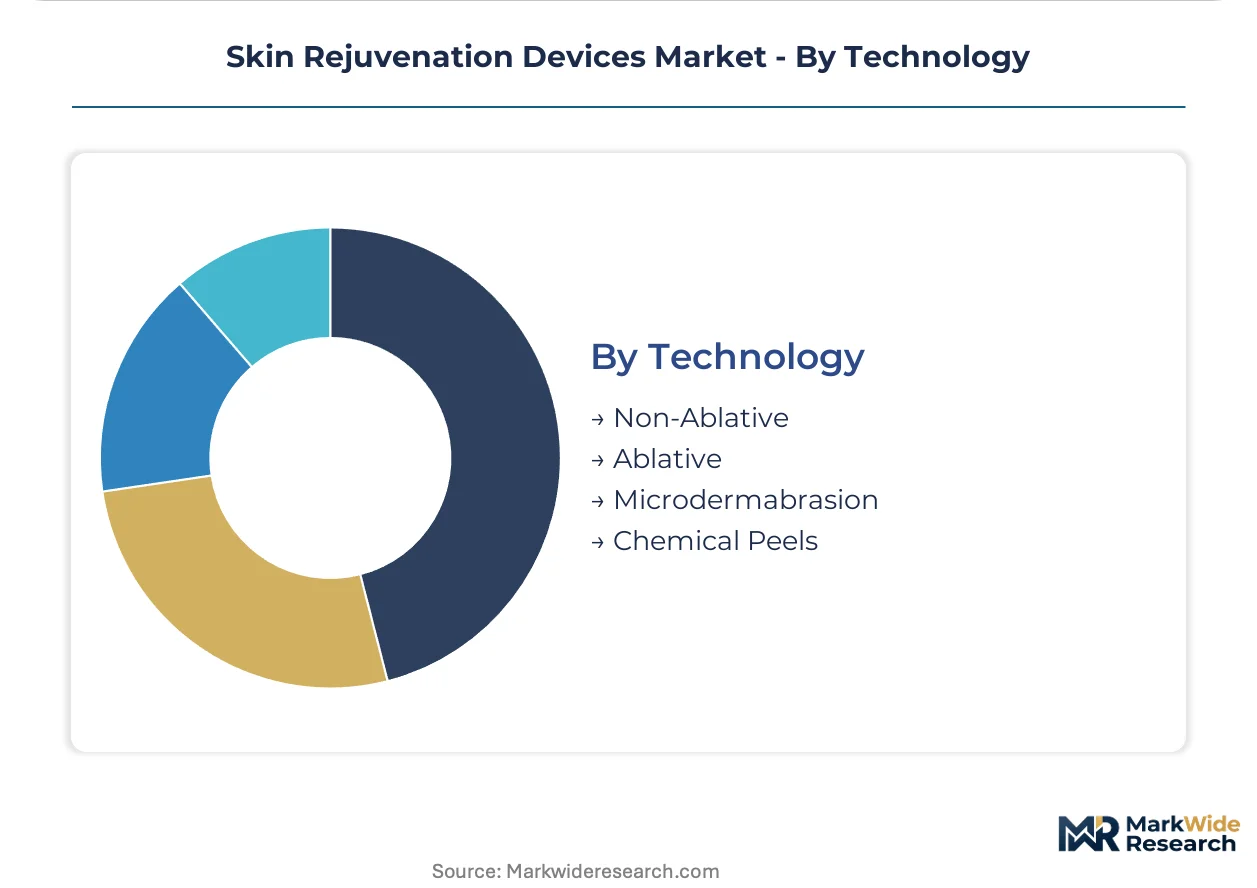
Technology:
Regulatory classification under MDR and FDA pathways correlates directly with ablation depth and recovery time profiles.
- Non-Ablative:Light and radiofrequency systems preserving epidermal integrity dominate medical spa installations for minimal-downtime protocols. EU AI Act algorithmic transparency mandates apply to automated parameter adjustment modules in this category.
- Ablative:CO2 and erbium laser systems with controlled tissue vaporization require longer certification cycles under updated ISO 13485 risk management requirements.
- Microdermabrasion:Mechanical exfoliation systems occupy lower price tiers with minimal regulatory burden.
- Chemical Peels:Topical acid formulations compete for texture improvement budgets against capital equipment alternatives.
Non-Ablative technology leads procedure counts, with Ablative platforms retaining premium positioning for severe photodamage cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist dermatologists and aesthetic medicine practitioners concentrate in metropolitan clusters across five national markets, each shaped by distinct regulatory frameworks and procurement channels.
United States
Medical spa chains in Florida, Texas, and California consolidate procurement through group purchasing organizations, creating dedicated capital pools for multi-platform installations. FDA 510(k) pathways demand predicate device comparisons, tightening substantial equivalence standards for energy-based systems. The Sun Belt corridor drives fastest upgrade velocity as seasonal demand volatility pushes operators toward per-treatment consumable pricing.
South Korea
Gangnam district clinics anchor regional demand for fractional radiofrequency systems, outpacing most other national markets in consumer willingness to pay for non-invasive procedures. MFDS fast-track pathways accelerate commercialization timelines for novel energy-based aesthetic devices. Seoul's aesthetic medicine infrastructure concentrates physician-operated density that exceeds hospital alternatives.
Germany
MDR clinical evidence burdens now mandate prospective post-market surveillance studies for Class IIb energy devices, exhausting mid-tier R&D budgets. German suppliers control solid-state and fiber laser component output, exposing device OEMs to extended lead times. Munich and Düsseldorf academic medical centers prioritize platforms with published histological evidence supporting reimbursable indications.
Brazil
São Paulo and Rio de Janeiro aesthetic medicine groups upgrade from IPL legacy systems, generating replacement demand for multi-wavelength platforms with integrated cooling. ANVISA premarket review timelines extend for novel energy-based modalities lacking local clinical data. The southeastern corridor concentrates private clinic networks with capital allocation flexibility exceeding public hospital procurement.
United Arab Emirates
Dubai and Abu Dhabi medical tourism infrastructure drives demand for premium laser and radiofrequency platforms targeting international patient flows. MOHAP registration requirements harmonize with Saudi SFDA standards across Gulf Cooperation Council markets. The emirates' physician-operated clinic density exceeds hospital alternatives, concentrating procurement decisions in private capital pools.
Skin Rejuvenation Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Incumbent manufacturers with captive laser source production sustain margin structures under rising compliance burdens. Three strategic archetypes dominate: vertically integrated component producers, geographic-focused distributors, and channel-specialized platform developers. M&A activity concentrates on acquiring algorithmic skin analysis capabilities, while strategic partnerships target regulatory sandbox access for AI-enabled devices.
Among Israeli-origin energy-device developers, Lumenis and Alma Lasers exemplify divergent geographic strategies—one leveraging backward integration into laser source manufacturing, the other anchoring position across Middle Eastern and Asian markets where regulatory harmonization remains fragmented. Cutera occupies a position within the medical spa channel-specialized tier, targeting procurement patterns distinct from hospital-based competitors. These three represent archetypal competitive positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Lumenis |
| Cutera |
| Alma Lasers |
| Cynosure |
| Sciton |
| Fotona |
| Lutronic |
| InMode |
| Syneron Candela |
| Others |
Value Network & Pricing Analysis
EU MDR post-market surveillance mandates now gate qualified supply access and premium-tier pricing power, as manufacturers lacking clinical evidence infrastructure face exclusion from reimbursable device categories while incumbents with captive laser source production capture margin expansion.
Pricing Analysis
Bundled capital equipment contracts are unbundling into per-treatment consumable pricing with separate maintenance subscriptions across Sun Belt medical spa chains. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service architecture, with de novo pathway devices commanding premium positioning. Pricing pressure stems from home-use LED mask penetration at lower price points, compressing mid-tier professional system margins. Medical spa group purchasing organizations exhibit highest price sensitivity, while academic medical centers prioritize histological evidence over unit cost.
Supply Chain Analysis
Freight cost escalation for solid-state laser components from Germany and fiber laser assemblies from the United States is compressing OEM margins on transatlantic shipments. German and US suppliers control critical laser source output, exposing device manufacturers to extended lead times and minimum order quantity escalation. Supply chain risk centers on single-source dependency for 755nm and 1064nm picosecond-domain laser crystals. Distribution runs through authorized dealer networks serving dermatology clinics and medical spa chains, with direct-to-consumer LED channels bypassing traditional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in algorithmic skin analysis modules and fractional radiofrequency platforms, as component cost compression in LED diodes and impedance-adaptive delivery systems enables premium-tier repositioning.
For Market Incumbents: Anticipate predicate device 510(k) erosion by accelerating de novo pathway investments for novel fractional modalities, while deepening backward integration into laser source manufacturing to defend margin structures against German and US supplier concentration. Priority levers include acquiring algorithmic skin analysis capabilities and securing MFDS fast-track positioning for Gangnam clinic cluster penetration. For New Entrants and Emerging Players: Enter via Brazilian private clinic networks upgrading from IPL legacy systems in São Paulo and Rio de Janeiro, where ANVISA review timelines favor established clinical data packages. Target home-use LED convergence with wearable mask formats incorporating 633nm and 830nm diodes, leveraging direct-to-consumer channel penetration with documented training data provenance for EU AI Act compliance. For Investors and Strategic Acquirers: Roll-up economics work for algorithmic skin analysis specialists because EU AI Act transparency mandates concentrate compliance costs on incumbents with established clinical image libraries. Long-term viability favors platforms with integrated cooling architecture and multi-wavelength capability. Signal to monitor: FDA guidance on energy-based device reclassification compressing approval timelines for novel modalities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence investments favor well-capitalized developers with post-market surveillance infrastructure. |
| Hospital System Partnership | Academic medical centers prioritize platforms with published histological evidence supporting reimbursable indications. |
| Software Companion Development | EU AI Act algorithmic transparency mandates force documentation of training data provenance for automated modules. |
| Reimbursement Strategy | 3D volumetric assessment protocols expand reimbursable indications beyond cosmetic classification for collagen remodeling. |
| Geographic Expansion | MFDS fast-track pathways accelerate commercialization timelines for fractional systems targeting Gangnam clinic density. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology clinic operators, medical spa procurement directors, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, MFDS registration databases, EU MDR notified body guidance, and hospital procurement contract repositories. Bottom-up device shipment modeling and top-down aesthetic medicine expenditure analysis provided cross-verification.
Comparable-period anchoring tied projection assumptions to historical replacement cycle compression and regulatory pathway evolution across the analysis window. Segmentation dimensions modeled include energy delivery modality, treatment ablation depth, end-user channel, and regional regulatory cluster. CAGRs derived from installed base growth and upgrade velocity patterns, with specific inputs from fractional radiofrequency adoption curves and picosecond-domain laser displacement timelines.
Inputs from notified body capacity assessments and MFDS fast-track approval records were available through the study window; gaps in real-time trade data for solid-state laser components introduce uncertainty bands around OEM cost structure assumptions. Forecasts reflect documented predicate device trends and MDR surveillance burden evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Venturi Mask Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Vascular Boot Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
China Artificial Organs and Bionic Implants Market