
 Global Parkinson's Disease Drugs Market | 2026-2036
Global Parkinson's Disease Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Parkinson's Disease Drugs Market Foresight
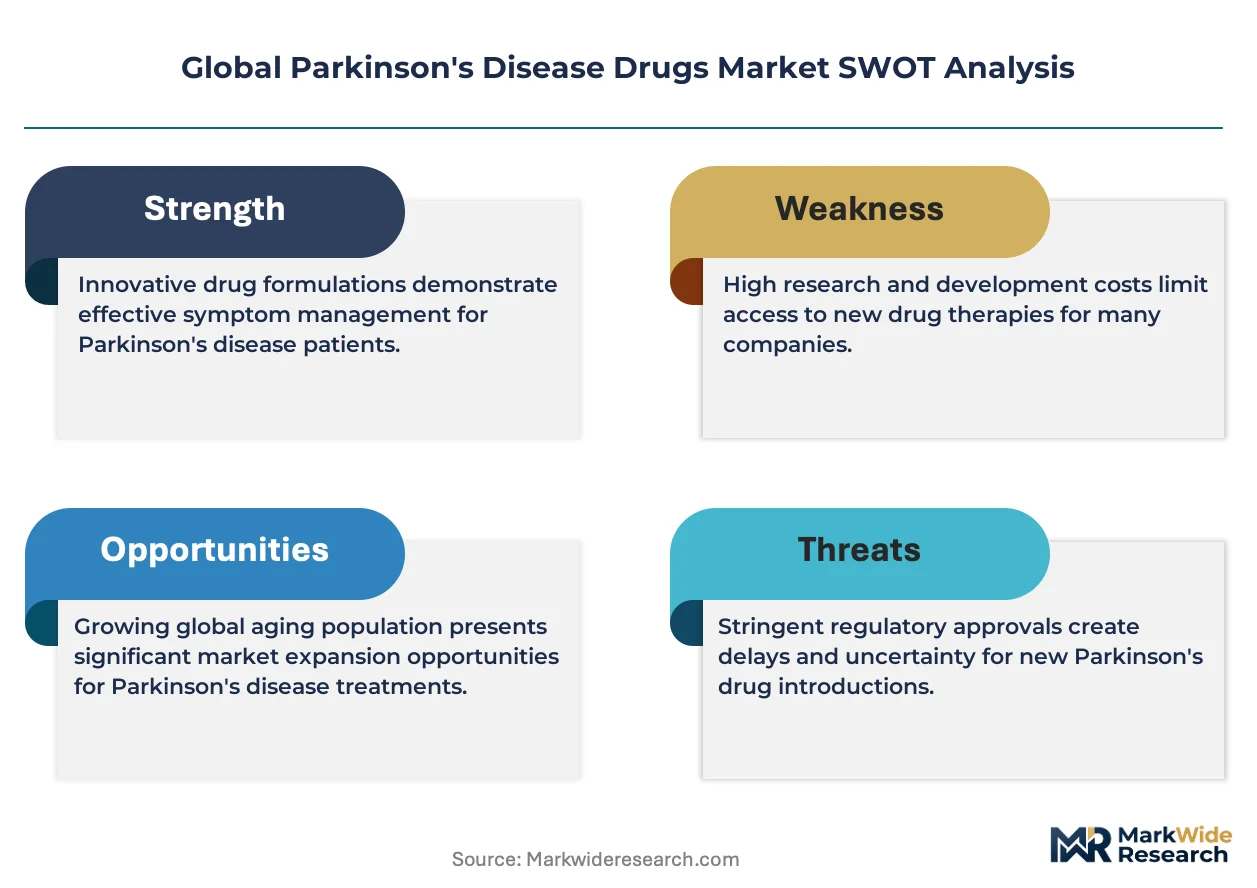
Hospital and specialty pharmacy procurement is reconfiguring how Parkinson's therapies reach patients, with centralized purchasing agreements now governing formulary placement for high-cost infusion and implantable drug-device combinations. AbbVie dominates the advanced therapy segment through its deep portfolio in continuous dopaminergic delivery. Teva Pharmaceutical Industries Ltd. leverages its generic levodopa manufacturing scale to anchor cost-sensitive markets across Latin America and Eastern Europe. Pfizer Inc. competes through its neurology franchise, sustaining R&D investment in novel mechanisms beyond dopamine replacement.
Parkinson's disease drugs comprise pharmaceutical agents that modulate dopaminergic neurotransmission, including levodopa precursors, direct dopamine receptor agonists, and enzymes that inhibit peripheral or central catabolism of dopamine, formulated to achieve sustained plasma concentration profiles that minimize motor fluctuation. Their primary purpose is to restore functional motor control and manage non-motor symptoms in patients with progressive dopaminergic neuron degeneration. Levodopa-based regimens remain the structural backbone of symptomatic treatment, though margin pools increasingly shift toward transdermal and subcutaneous delivery modes that command premium pricing for adherence and pharmacokinetic advantages. Motor symptom management occupies the largest application share, while disease progression delay represents the fastest-growing segment as developers target alpha-synuclein and neuroinflammation pathways.
FDA accelerated approval designations and EMA conditional marketing authorizations are compressing development timelines for disease-modifying candidates, though post-market confirmatory requirements add commercial risk. The EU MDR framework imposes stricter clinical evidence standards on drug-device combination products, including subcutaneous pumps and inhalation systems. Japan's PMDA orphan drug incentives sustain trial enrollment in Asia-Pacific development programs. Stakeholders must monitor regulatory divergence between these agencies on biomarker-based endpoints, as alignment or fragmentation will determine whether parallel development strategies remain economically viable.
Market Dynamics
FDA accelerated approval pathways for neurodegenerative therapies are compressing clinical trial timelines while simultaneously elevating post-market evidence burdens, reshaping how developers allocate capital across discovery and commercialization phases.
Growth Catalysts
- Hospital movement disorder unit expansion:Neurology departments in the United States, Germany, and Japan are establishing dedicated Parkinson's centers that concentrate prescribing authority for advanced infusion and implantable therapies.
- EMA conditional marketing authorizations:The European framework permits earlier patient access to disease-modifying candidates targeting alpha-synuclein aggregation, accelerating revenue recognition for developers with biomarker-validated endpoints.
- Subcutaneous pump adoption:Continuous dopaminergic delivery systems are displacing oral levodopa regimens in patients with motor fluctuations, commanding premium reimbursement for pharmacokinetic stability.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for carbidopa and entacapone concentrates in Chinese and Indian facilities, exposing formulators to geopolitical and logistics disruptions.
- EU MDR clinical evidence requirements:The framework imposes stricter documentation burdens on drug-device combinations including subcutaneous infusion pumps and inhalation systems, extending time-to-market.
- Generic levodopa price compression:Teva Pharmaceutical Industries and regional manufacturers in Eastern Europe and Latin America anchor cost-sensitive segments, eroding margin pools for branded oral formulations.
Strategic Opportunities
- Brazil's ANVISA orphan drug pathway:The regulator offers tax incentives and expedited review for therapies addressing neurodegenerative conditions with prevalence below specified thresholds.
- Transdermal patch expansion:Rotigotine and emerging dopamine agonist patches address adherence gaps in elderly populations with dysphagia or cognitive impairment.
- Japan PMDA-Sakigake designation:The framework provides priority consultation and shortened review timelines for disease-modifying candidates with novel mechanisms beyond dopamine replacement.
Industry Challenges
- Biomarker endpoint validation:Developers face inconsistent acceptance of alpha-synuclein seeding assays and neuroimaging surrogates across FDA, EMA, and PMDA review divisions.
- Specialty pharmacy credentialing:High-cost infusion therapies require accreditation with limited distribution networks, creating bottleneck capacity for patient onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Parkinson's Disease Drugs Market |
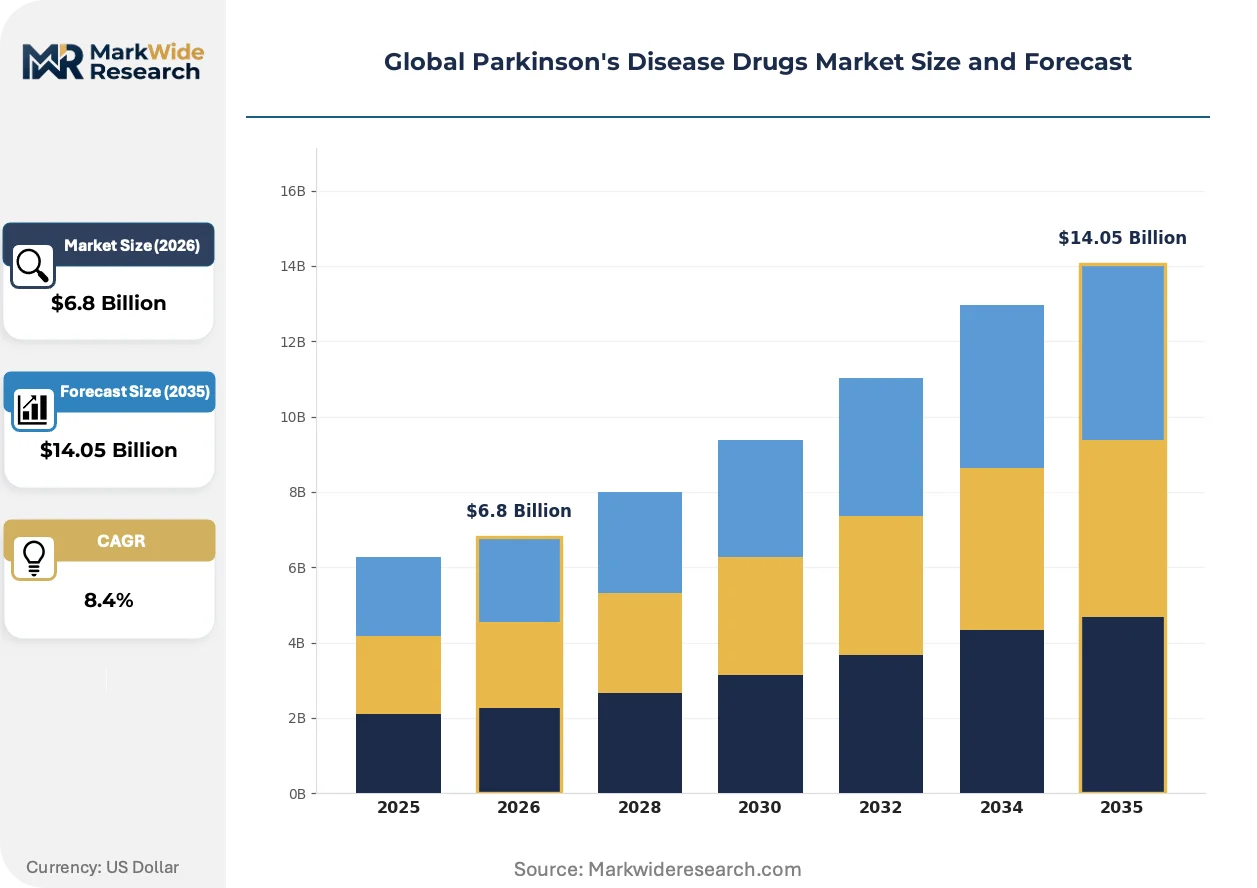
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
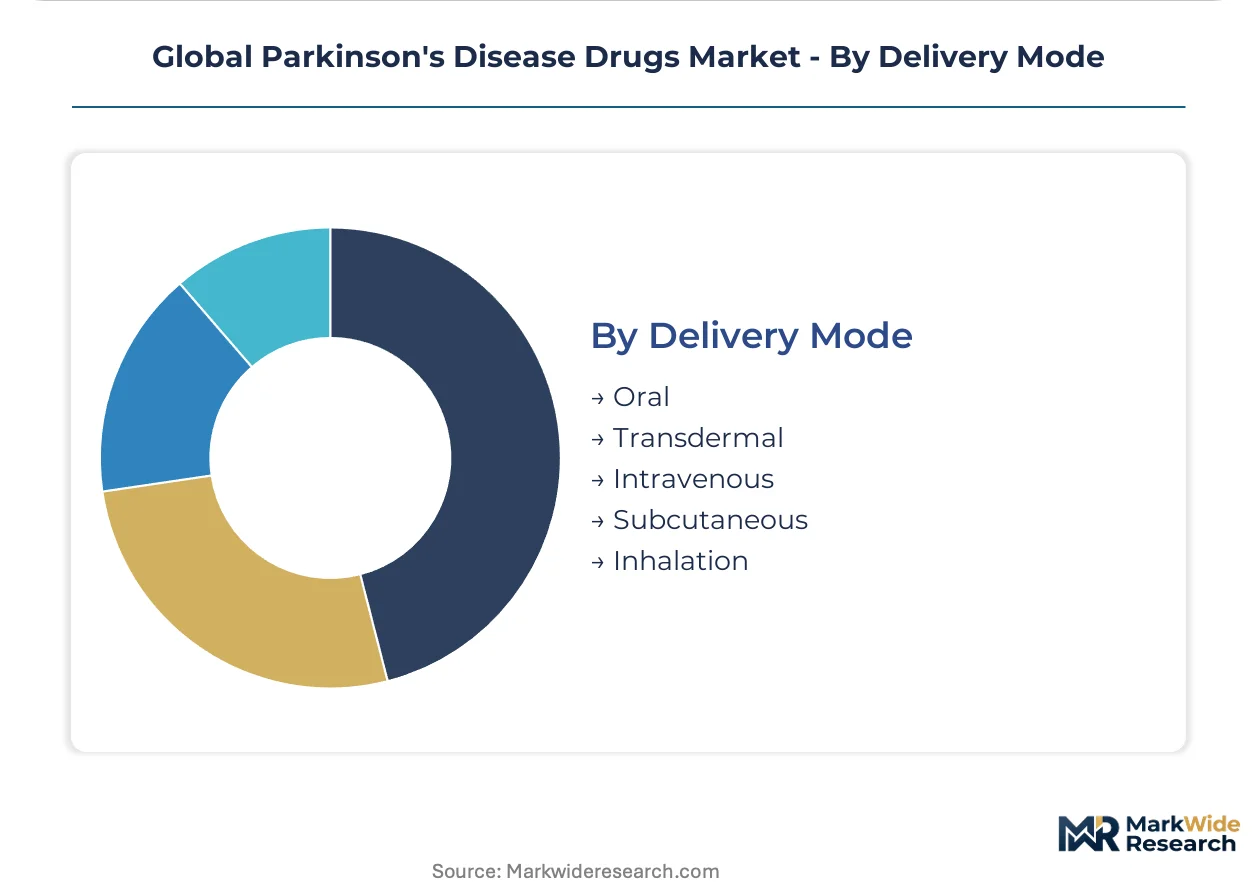
| Segmentation | Product Type: Levodopa, Dopamine Agonists, MAO-B Inhibitors, COMT Inhibitors, Anticholinergics Application: Motor Symptom Management, Non-Motor Symptom Relief, Disease Progression Delay, Symptomatic Treatment End User: Neurologists, Movement Disorder Clinics, Long-Term Care Facilities, Research Institutions Delivery Mode: Oral, Transdermal, Intravenous, Subcutaneous, Inhalation |
| Companies Covered | F. Hoffmann-La Roche Ltd, Acadia Pharmaceuticals Inc., UCB S.A, Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., AbbVie Inc., Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Parkinson's Disease Drugs Market Shifts & Advancements
Continuous delivery modalities are displacing intermittent oral dosing as the clinical standard for advanced Parkinson's, while regulatory frameworks evolve to accommodate biomarker-driven approval pathways that compress traditional phase structures.
Subcutaneous levodopa-carbidopa intestinal gel pumps are collapsing the distinction between hospital-based care and home administration. Movement disorder specialists in the United States and Germany are implanting these systems in patients experiencing severe motor fluctuations, enabling 16-hour continuous dopaminergic stimulation that eliminates peak-dose dyskinesia and off-period disability. The technology is collapsing reimbursement frameworks built around oral pharmacy benefit structures, forcing payers to create new device-centric coverage categories.
EMA's evolving stance on surrogate endpoint acceptance for neurodegenerative conditions is accelerating conditional approval designations. The regulator has published reflection papers on alpha-synuclein quantification in cerebrospinal fluid, creating a pathway for developers to demonstrate target engagement prior to clinical outcome confirmation. European trial sponsors are restructuring phase programs to incorporate these biomarker milestones, compressing traditional development timelines by 18-24 months for candidates with mechanistic validation.
Centralized hospital procurement consortia are consolidating formulary decisions for high-cost Parkinson's therapies. Specialty pharmacy networks in the United States are displacing traditional retail channels for infusion and implantable drug-device combinations, requiring manufacturers to establish direct contractual relationships with integrated delivery networks. This channel migration is most pronounced in Medicare Advantage populations, where risk-bearing entities prioritize adherence-monitoring capabilities and total cost-of-care contracts over drug acquisition price alone.
Global Parkinson's Disease Drugs Market Segmentation
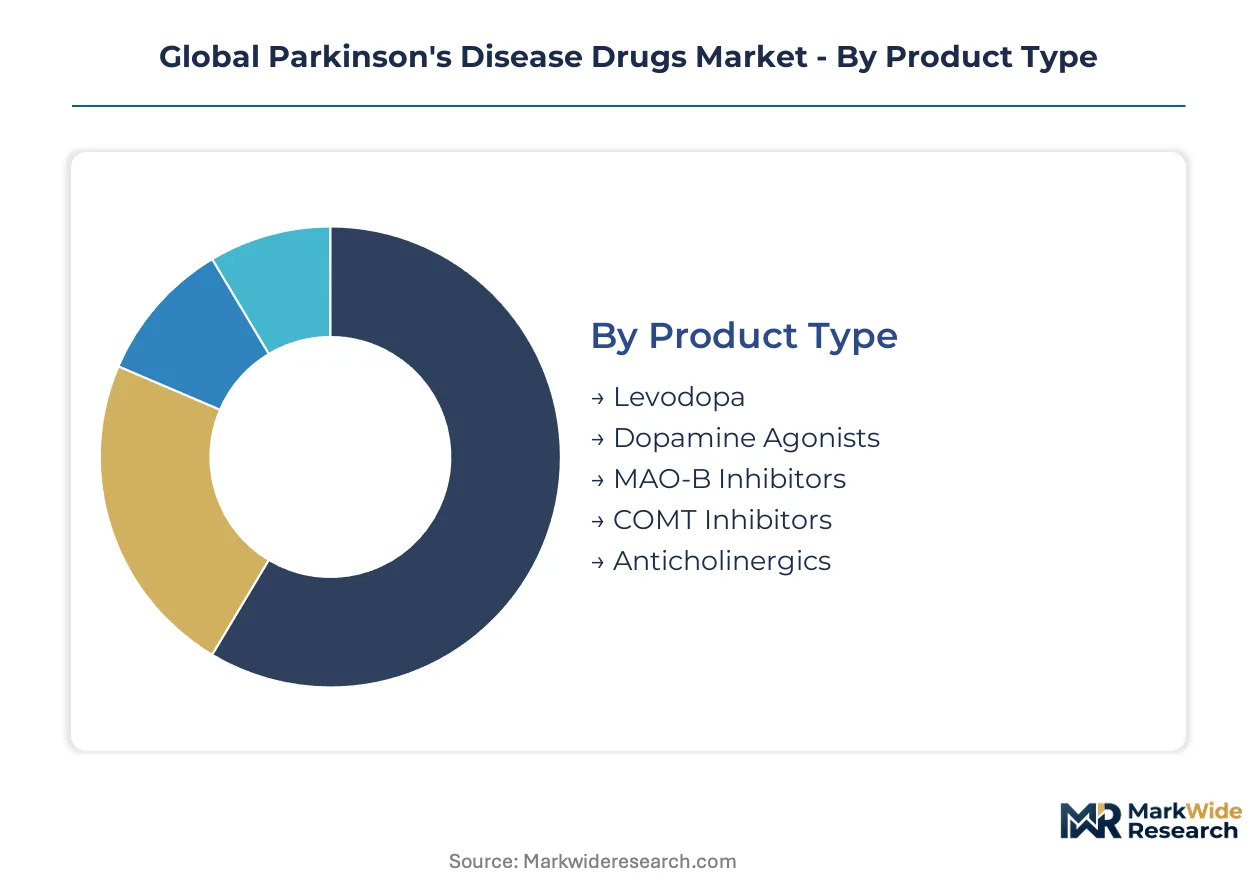
Segmentation in Parkinson's therapeutics reveals how prescribing authority, reimbursement pathways, and patient acuity intersect to determine commercial access. Each dimension—molecule class, clinical application, care setting, and delivery technology—carries distinct margin and volume characteristics that shape portfolio allocation decisions.
Product Type:
The use-case spectrum spans acute symptom control through chronic maintenance, with each pharmacological class occupying distinct positions in treatment algorithms and patent landscapes.
- Levodopa:The dopamine precursor remains the pharmacological foundation, formulated with peripheral decarboxylase inhibitors to enhance central bioavailability. Demand concentrates in movement disorder clinics across the United States and Germany, where continuous delivery formulations command premium reimbursement against generic oral competition.
- Dopamine Agonists:Direct receptor stimulation agents—pramipexole, ropinirole, rotigotine—serve as monotherapy in early disease and adjunct therapy in advanced stages. Prescribing volumes cluster in Japan and France, where transdermal rotigotine patches address adherence challenges in elderly populations with dysphagia.
- MAO-B Inhibitors:Selegiline and rasagiline extend dopamine half-life through selective monoamine oxidase inhibition.
- COMT Inhibitors:Entacapone and opicapone block peripheral catechol-O-methyltransferase to prolong levodopa plasma levels.
- Anticholinergics:Trihexyphenidyl and benztropine address tremor-predominant phenotypes through muscarinic receptor antagonism.
Established volume favors levodopa; emerging adoption favors dopamine agonists.
Application:
Cost tier differentiation separates acute symptomatic relief from premium-priced disease modification candidates.
- Motor Symptom Management:Bradykinesia, rigidity, and tremor control therapies constitute the foundational revenue pool, with levodopa-carbidopa combinations and dopamine agonists dominating hospital formularies. Concentrated prescribing authority resides in United States academic medical centers and German university hospitals with dedicated movement disorder units.
- Non-Motor Symptom Relief:Cognitive impairment, autonomic dysfunction, and psychiatric comorbidity treatments represent an underserved segment with limited approved options. Demand is expanding most quickly in Japan, where PMDA orphan drug incentives accelerate development for dementia with Lewy bodies and REM sleep behavior disorder.
- Disease Progression Delay:Alpha-synuclein targeting immunotherapies and neuroinflammation modulators occupy clinical trial pipelines.
- Symptomatic Treatment:General maintenance regimens encompass the majority of chronic prescriptions.
Revenue concentration sits with motor management; pipeline investment targets progression delay.
End User:
Customer type determines procurement channel, with hospital-based specialists controlling access to high-cost infusion therapies.
- Neurologists:General neurology practices manage the majority of early-stage prescriptions, with prescribing patterns shaped by Medicare Part D formularies in the United States and statutory health insurance reimbursement lists in Germany.
- Movement Disorder Clinics:Subspecialty centers concentrate expertise for advanced therapies including subcutaneous pumps and deep brain stimulation coordination. These facilities in Boston, Munich, and Osaka anchor adoption curves for device-enabled drug delivery.
- Long-Term Care Facilities:Nursing homes and skilled nursing facilities manage polypharmacy in frail elderly populations.
- Research Institutions:Academic medical centers conduct Phase II-III trials for disease-modifying candidates.
Volume flows through neurologists; margin capture favors movement disorder clinics.
Delivery Mode:
Technology maturity creates a spectrum from commoditized oral generics to premium device-dependent systems.
- Oral:Immediate-release and extended-release tablets dominate prescription volume, with generic levodopa-carbidopa eroding branded margins across Eastern Europe and Latin America.
- Transdermal:Rotigotine patches provide 24-hour dopaminergic stimulation without gastrointestinal absorption variability. Adoption concentrates in France and the United Kingdom, where NICE and HAS assessments favor adherence advantages in cognitively impaired populations.
- Intravenous:Hospital-administered formulations serve acute intervention scenarios.
- Subcutaneous:Levodopa-carbidopa intestinal gel pumps enable continuous ambulatory delivery.
- Inhalation:Inhaled levodopa addresses off-period rescue needs.
Oral formulations anchor volume; subcutaneous systems climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for neurodegenerative therapies anchor commercial strategy in the United States, while EMA conditional authorizations and Japan's PMDA orphan incentives create parallel development tracks across three distinct regulatory environments.
United States
Medicare Part D formularies and Medicare Advantage risk-bearing contracts concentrate prescribing authority for infusion and implantable therapies. FDA's accelerated approval pathway compresses phase structures for alpha-synuclein targeting candidates. Movement disorder centers in Boston, Cleveland, and San Francisco anchor adoption curves for subcutaneous pump systems.
Germany
Statutory health insurance reimbursement lists and Diagnosis-Related Group hospital payments structure access to advanced therapies. EMA conditional marketing authorizations enable earlier patient access to disease-modifying candidates. University hospitals in Munich, Berlin, and Tübingen concentrate expertise for continuous dopaminergic delivery coordination.
Japan
PMDA orphan drug incentives and Sakigake priority review designation accelerate development timelines for novel mechanisms. Aging demographics and long-term care insurance expansion sustain demand for adherence-optimized formulations. Osaka and Tokyo academic medical centers lead Asia-Pacific enrollment for neurodegenerative trials.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning frameworks determine formulary placement for high-cost therapies. MHRA post-Brexit regulatory autonomy enables divergence from EMA timelines on biomarker-based endpoints. London and Manchester movement disorder units concentrate prescribing for transdermal and infusion systems.
Brazil
ANVISA orphan drug pathway offers tax incentives and expedited review for neurodegenerative therapies below prevalence thresholds. Unified Health System procurement consortia negotiate volume discounts for chronic neurological treatments. São Paulo and Rio de Janeiro university hospitals anchor Latin American trial enrollment and specialist referral networks.
Global Parkinson's Disease Drugs Market Competitive Landscape
Integrated neurology franchises and generic manufacturing specialists split the market into distinct capability tiers. Large-cap pharmaceutical companies with established hospital sales infrastructure capture premium-priced device-enabled therapies, while regional formulators anchor cost-sensitive oral segments through manufacturing scale. Three archetypes dominate: continuous delivery system developers, generic levodopa manufacturers, and disease-modifying biologics pioneers. Competitive intensity centers on M&A targeting movement disorder clinic networks and strategic partnerships for biomarker validation platforms.
Among the integrated neurology developers, AbbVie Inc. and Pfizer Inc. exemplify the franchise-depth archetype, with AbbVie representing continuous dopaminergic delivery specialization and Pfizer occupying novel mechanism research positioning. Teva Pharmaceutical Industries Ltd. anchors the manufacturing-scale tier, with its corporate structure signaling generic and specialty pharmaceutical capabilities across cost-sensitive geographies.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Acadia Pharmaceuticals Inc. |
| UCB S.A |
| Pfizer Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Boehringer Ingelheim International GmbH |
| Others |
Supply & Pricing Matrix
Shanghai-Port of Rotterdam freight corridors govern API cost dynamics for carbidopa and entacapone, concentrating pricing power with Chinese manufacturers while forcing Western formulators into premium-device differentiation to escape commodity margin compression.
Pricing Analysis
Customization-premium spreads separate continuous dopaminergic delivery systems from generic oral levodopa, with subcutaneous pumps commanding value-based reimbursement against per-unit transactional pricing for immediate-release tablets. Price differentiation rests on pharmacokinetic stability certification and hospital formulary tier placement. Cost compression in oral generics intensifies as Teva and regional manufacturers scale entacapone production. Long-term care facilities exhibit highest price sensitivity; movement disorder clinics show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates API sourcing risk for peripheral decarboxylase inhibitors and COMT blockers. Active pharmaceutical ingredient manufacturing concentrates in China and India, drawing from specialized chemical intermediates and catalyst precursors. Single-source vulnerability persists for rotigotine patch polymers. Distribution runs through centralized hospital procurement consortia and specialty pharmacy networks with limited distribution credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device servicing contracts and patient adherence monitoring subscriptions expand faster than hardware sales, transforming Parkinson's therapeutics into a recurring-revenue business where pump maintenance and telemedicine coordination capture lifetime value.
For Market Incumbents: Build regulatory data moats through biomarker validation platforms that lock in FDA accelerated approval precedents. Defend against generic pump commoditization by securing exclusive formulary contracts with Medicare Advantage risk-bearing entities. Deepen backward integration into carbidopa API production to neutralize Chinese supply volatility. For New Entrants and Emerging Players: Brazil's ANVISA orphan drug pathway offers expedited market entry with tax-advantaged manufacturing status. Target non-motor symptom relief as the most penetrable segment, where dementia with Lewy bodies and autonomic dysfunction lack approved options. Partner with Japanese academic medical centers for PMDA-Sakigake designation to compress review timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical neurology franchises divesting non-core Parkinson's assets. Five-to-ten-year viability hinges on disease-modifying pipeline depth beyond dopamine replacement. Watch EMA conditional marketing authorization designations as inflection signals for alpha-synuclein targeting candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Validation Partnership | Secures FDA precedent for alpha-synuclein seeding assays in accelerated approval pathways. |
| Specialty Pharmacy Network Accreditation | Unlocks limited distribution access for high-cost infusion therapies in Medicare Advantage. |
| Continuous Delivery System Launch | Collapses reimbursement frameworks toward device-centric coverage categories in Germany. |
| EMA Conditional Marketing Authorization | Compresses development timelines through surrogate endpoint acceptance in neurodegenerative trials. |
| API Manufacturing Scale-Up | Reduces dependency on Chinese carbidopa suppliers through captive production in India. |
Research Methodology
The analysis maps continuous dopaminergic delivery systems, oral levodopa formulations, and disease-modifying biologics, each validated through movement disorder specialists, hospital formulary directors, and payer access specialists. Primary interviews with regulatory affairs leads at FDA, EMA, and PMDA converge with secondary sources including ClinicalTrials.gov, EMA submission databases, and Medicare Part D formulary files. Bottom-up prescription volume modeling triangulates against top-down manufacturer revenue disclosures.
Assumptions hold regulatory pathway convergence and reimbursement tier stability fixed while varying biomarker endpoint acceptance and generic entry timing across the projection horizon. Segmentation dimensions span molecule class, delivery mode, care setting, and regional regulatory cluster. CAGRs derive from patient population epidemiology and therapy adoption curve synthesis, with infusion pump penetration and disease-modifying candidate approval probability as key forecast inputs.
Practitioners should monitor FDA confirmatory trial requirement revisions and EMA MDR enforcement intensity for early signals of commercial timeline compression. Forecasts reflect assumptions about accelerated approval durability and post-market evidence generation success. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Leukotriene Inhibitors Market
Pharmaceuticals
Targeted Therapeutics Market