
 Ultrasound Transducers Market | 2026-2036
Ultrasound Transducers Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Transducers Market Intelligence
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape between established manufacturers with notified-body relationships and newer entrants facing extended conformity timelines. GE HealthCare leverages its vertically integrated probe manufacturing to sustain cost advantages across linear and phased array portfolios. Siemens Healthineers anchors its position through deep R&D investment in single-crystal piezoelectric materials. Koninklijke Philips N.V. competes by controlling distribution channels that bundle transducers with premium ultrasound platforms.
Ultrasound transducers convert electrical pulses into acoustic waves and vice versa, typically employing lead zirconate titanate or single-crystal piezoelectric elements operating at frequencies from 2 to 15 MHz for tissue penetration and resolution trade-offs. Convex array transducers dominate obstetric and abdominal applications where deep-field imaging commands stable replacement demand, while phased array systems lead cardiology due to narrow intercostal windows requiring small footprints. Doppler imaging technology captures expanding margin pools as vascular and hemodynamic assessments shift into outpatient settings.
FDA 510(k) clearances and CE marking under MDR govern acoustic output limits, biocompatibility testing, and electromagnetic compatibility for ultrasound transducers entering clinical use. The EPA and RoHS frameworks additionally constrain lead content and hazardous substance profiles in piezoelectric element manufacturing. Stakeholders must monitor evolving notified-body capacity in Europe and FDA review timeline variability as these regulatory frictions directly determine product launch cadence and geographic revenue sequencing.
Market Dynamics
Single-crystal piezoelectric materials are compressing transducer manufacturing economics while FDA and CE marking timelines under MDR bifurcate vendor qualification speeds, creating divergent competitive trajectories across hospital procurement channels.
Growth Catalysts
- Point-of-care expansion:Cardiology and obstetrics departments in the United States, Germany, and China are replacing aging installed bases with compact systems. This drives stable replacement demand for convex and phased array transducers.
- RoHS and EPA frameworks:Lead-content restrictions in piezoelectric manufacturing are accelerating investment in alternative material formulations. Vendors with compliant supply chains capture procurement preference.
- Doppler imaging migration:Vascular and hemodynamic assessments are shifting into outpatient settings. This expands addressable volume for specialized transducer configurations.
Market Restraints
- Notified-body capacity constraints:CE marking under EU MDR faces extended conformity timelines as European notified bodies struggle with backlog. Newer entrants face 12-18 month delays versus established manufacturers.
- Lead zirconate titanate supply concentration:Piezoelectric ceramic supply concentrates among Asian specialty chemical producers. Input cost volatility constrains margin flexibility for Western transducer assemblers.
- Acoustic output safety limits:FDA 510(k) clearances enforce strict acoustic intensity thresholds. These technical ceilings prevent certain high-frequency configurations from reaching clinical deployment.
Strategic Opportunities
- India point-of-care penetration:CDSCO regulatory pathways are streamlining for Class B medical devices. Underpenetrated district hospital networks present white-space demand for cost-optimized linear probes.
- Wireless transducer convergence:Integration of Bluetooth Low Energy with capacitive micromachined ultrasound transducers enables tablet-based imaging. Emergency medicine and field triage applications are piloting these configurations.
- Japan METI innovation incentives:Subsidies for next-generation diagnostic equipment are accelerating single-crystal adoption. Domestic manufacturers are qualifying advanced materials for export markets.
Industry Challenges
- Electromagnetic compatibility certification:IEC 60601-1-2 testing for radiated emissions requires specialized anechoic chamber facilities. Smaller vendors face capex barriers for in-house compliance verification.
- Single-crystal fabrication expertise:Crystal growth and doping precision demands materials science PhD-level talent. The skill gap concentrates among legacy Japanese and German specialty ceramics firms.
- Legacy platform integration:New transducer designs must maintain backward compatibility with installed ultrasound consoles. This constrains form-factor innovation and extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Transducers Market |
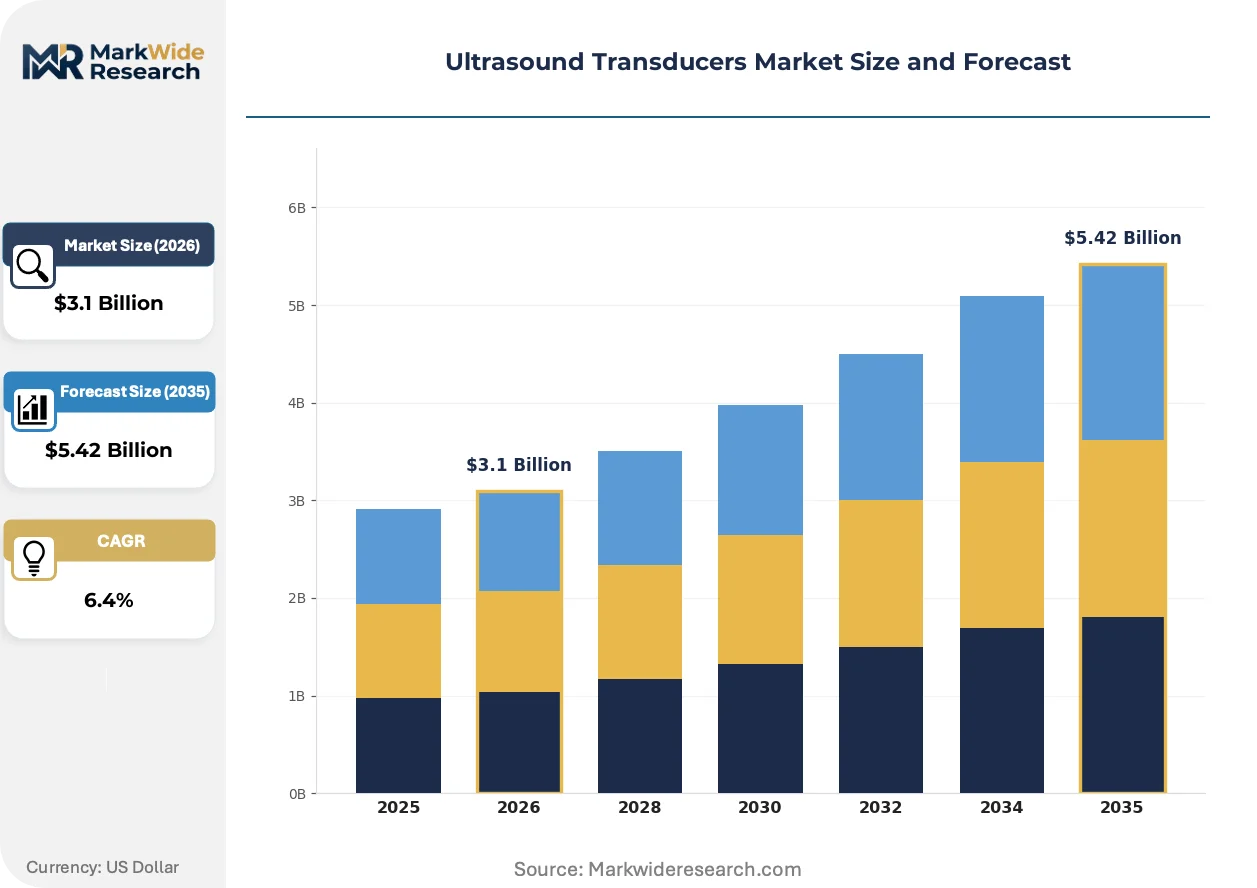
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Array, Convex Array, Phased Array, Endocavitary Application: Obstetrics, Cardiology, Urology, Musculoskeletal End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: 2D Imaging, 3D Imaging, Doppler Imaging, Elastography |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Samsung Medison Co., Ltd., Esaote SPA, Hitachi, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Transducers Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory recalibration are compressing traditional competitive moats while opening asymmetric advantages for vendors with compliant supply chains and advanced piezoelectric capabilities.
Capacitive micromachined ultrasound transducers (CMUTs) are fragmenting the conventional piezoelectric paradigm by enabling batch fabrication on silicon substrates. Semiconductor foundries in Taiwan and South Korea are adding CMUT process modules. This technology is fragmenting cost structures across portable and handheld ultrasound segments by eliminating discrete ceramic element bonding.
EU MDR Article 10 technical documentation requirements are extending conformity assessment durations for acoustic output biocompatibility testing. Notified bodies are demanding expanded clinical evidence for transducer surface materials. High-frequency intracavitary probes face the most severe timeline compression as manufacturers refile legacy device registrations.
Hospital procurement departments are unbundling transducer replacement contracts from original equipment manufacturer service agreements. Third-party refurbishers in Florida and Bavaria are capturing aftermarket volume with ISO 13485-certified probe repair. This behavior is most visible in United States academic medical centers with dedicated clinical engineering departments.
Ultrasound Transducers Market Segmentation
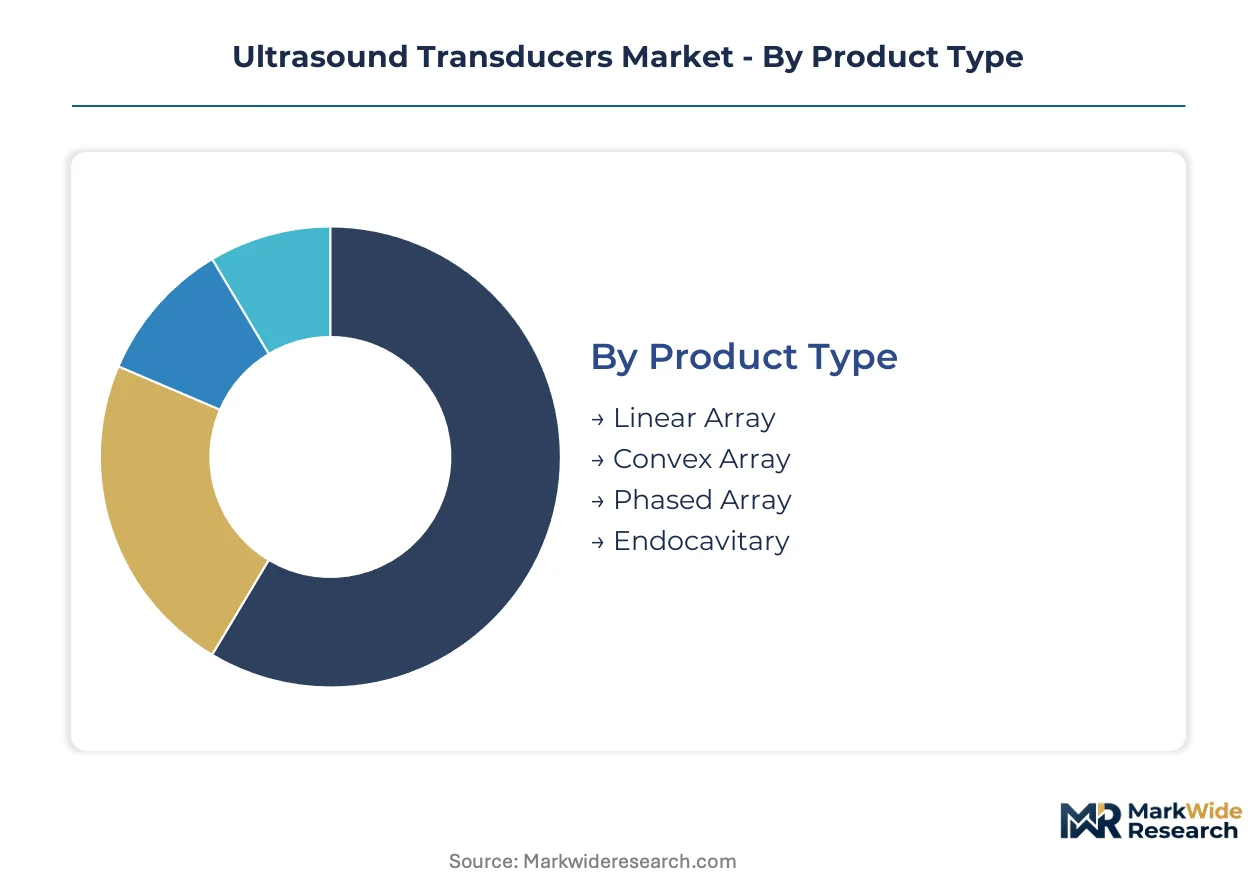
Ultrasound transducer segmentation reveals divergent vulnerability profiles across product architectures and imaging modalities. Substitute technologies—particularly CMUTs and wireless configurations—threaten legacy piezoelectric segments unevenly, reshaping procurement priorities and vendor R&D allocation.
Product Type:
Convex array transducers face the most immediate substitution pressure from semiconductor-fabricated alternatives, while phased array systems defend their position through specialized acoustic physics that CMUTs have yet to replicate at clinical scale.
- Convex Array:Curved piezoelectric elements operating at 2-5 MHz penetrate abdominal and obstetric tissue depths. Replacement demand concentrates in United States and Chinese district hospitals upgrading aging installed bases, though CMUT pilot programs in Taiwan foundries threaten long-term volume.
- Phased Array:Electronically steered beams from small footprints address cardiac imaging through narrow intercostal windows. German and Japanese cardiac centers sustain premium procurement despite higher unit costs, as beam-forming precision remains unmatched by emerging alternatives.
- Linear Array:High-frequency 7-15 MHz elements target superficial vascular and musculoskeletal structures.
- Endocavitary:Intracavitary probes with specialized sterilization protocols serve gynecologic and urologic endoscopy suites.
Convex array retains volume leadership; phased array holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive cardiology deployments from outpatient-accessible musculoskeletal workflows, with reimbursement differentials driving divergent technology adoption timelines.
- Cardiology:Hemodynamic assessment and structural heart evaluation demand premium phased array and Doppler configurations. United States hospital systems bundle these with enterprise ultrasound platforms, creating captive demand that resists point-of-care fragmentation.
- Obstetrics:Fetal anatomical surveys and biometry measurements rely on convex array penetration depths. Chinese maternal health infrastructure expansion and replacement cycles in German university hospitals sustain stable procurement volumes.
- Urology:Transrectal and transabdominal prostate imaging employs specialized endocavitary and curvilinear geometries.
- Musculoskeletal:Tendon, ligament, and joint surface evaluation favors portable linear array systems in outpatient sports medicine.
Cardiology commands the highest revenue per procedure; musculoskeletal is climbing the fastest as point-of-care penetration accelerates.
End User:
Customer type determines service contract attachment rates and replacement cycle predictability, with hospital procurement departments increasingly unbundling transducer purchases from OEM maintenance agreements.
- Hospitals:Academic medical centers in the United States and Germany maintain dedicated clinical engineering departments capable of ISO 13485-certified probe refurbishment, enabling third-party aftermarket capture and pressuring OEM pricing.
- Diagnostic Centers:High-throughput imaging chains in China prioritize throughput-optimized convex arrays for abdominal and obstetric screening volumes.
- Clinics:Point-of-care expansion drives compact wireless transducer demand in emergency medicine and primary care settings.
- Research Institutions:Preclinical and translational imaging laboratories source specialized high-frequency prototypes and experimental CMUT configurations.
Hospitals retain volume leadership; clinics are gaining share fastest as ambulatory site-of-care migration accelerates.
Technology:
Margin concentration tracks functional complexity, with Doppler and elastography configurations capturing premium pricing over basic 2D imaging as vascular and tissue characterization applications expand.
- Doppler Imaging:Pulsed-wave and continuous-wave modalities capture blood flow velocity and direction. Outpatient vascular labs in Germany and the United States are migrating these assessments from hospital radiology departments, expanding addressable volume for specialized transducer configurations.
- 3D Imaging:Volume acquisition and multiplanar reconstruction require matrix array architectures with dense element counts. Obstetric anatomical surveys and cardiac structural assessments in Japanese tertiary centers drive adoption despite longer acquisition times.
- 2D Imaging:Conventional B-mode grayscale remains the foundational modality across all clinical settings.
- Elastography:Tissue stiffness mapping through acoustic radiation force impulse or shear wave techniques targets liver fibrosis and lesion characterization.
2D imaging retains volume leadership; Doppler imaging holds the steepest expansion curve as vascular assessment decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and China concentrate the highest transducer replacement spending, driven by point-of-care expansion programs and aging installed base turnover. Academic medical centers and district hospital networks across these markets prioritize convex and phased array configurations for cardiology and obstetrics workflows.
United States
Academic medical centers in Boston and Baltimore drive premium phased array procurement for structural heart programs. FDA 510(k) clearance timelines for acoustic output safety shape vendor qualification cadences. Third-party probe refurbishers in Florida capture aftermarket volume from ISO 13485-certified clinical engineering departments.
Germany
University hospitals in Munich and Heidelberg sustain demand for single-crystal piezoelectric transducers in cardiac imaging suites. CE marking under EU MDR extends conformity timelines for notified-body relationships. Bavarian specialty ceramics firms concentrate crystal growth expertise for export-qualified probe assemblies.
China
District hospital networks in Jiangsu and Zhejiang provinces expand point-of-care convex array deployment for maternal health screening. NMPA regulatory pathways streamline Class II medical device registration for domestic manufacturers. Yangtze River Delta probe assemblers scale output for replacement cycles in aging installed bases.
Japan
Tertiary cardiac centers in Tokyo and Osaka anchor premium procurement for Doppler-enabled phased array systems. METI innovation subsidies accelerate single-crystal material adoption in next-generation diagnostic equipment. Nagoya-area ceramics specialists supply precision-doped crystals for intracavitary probe fabrication.
India
District hospital infrastructure in Maharashtra and Karnataka presents white-space demand for cost-optimized linear probes in emergency medicine. CDSCO regulatory streamlining for Class B devices reduces import clearance friction. Mumbai-based diagnostic chains pilot wireless transducer configurations for outpatient vascular assessment.
Ultrasound Transducers Market Key Industry Players
Player mix skews toward diversified medical imaging conglomerates with captive probe manufacturing capabilities, while specialized transducer fabricators occupy niche technology tiers. Consolidation pressure concentrates among established manufacturers with notified-body relationships and vertically integrated piezoelectric supply chains. Two strategic archetypes dominate: scale-driven platform bundlers and materials-science specialists. Competitive moves center on M&A for single-crystal fabrication expertise and strategic partnerships for CMUT foundry access.
Among diversified imaging conglomerates, GE HealthCare and Siemens Healthineers exemplify the scale-driven archetype through in-house probe manufacturing and platform bundling strategies. Koninklijke Philips N.V. occupies a position emphasizing distribution channel control. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the emerging specialist tier with cost-optimized linear probe offerings for point-of-care expansion markets. These three anchors illustrate how regulatory qualification speed and materials science capabilities stratify competitive positioning across hospital procurement channels.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Samsung Medison Co., Ltd. |
| Esaote SPA |
| Hitachi, Ltd. |
| Others |
Cost & Logistics Intelligence
Single-crystal piezoelectric materials replacing lead zirconate titanate ceramics are simultaneously shifting procurement geography toward Japanese and German specialty ceramics clusters while compressing manufacturing economics across convex and phased array transducer portfolios.
Pricing Analysis
Cost-plus contracts with lead zirconate titanate indexation dominate OEM procurement from Asian specialty chemical producers. Pricing stratifies across premium single-crystal, standard PZT-based, and economy refurbished tiers, with FDA 510(k) clearance tier commanding measurable brand premium. Cost compression in economy tiers is intensifying because third-party refurbishers in Florida and Bavaria capture ISO 13485-certified aftermarket volume. Academic medical centers exhibit lowest price sensitivity due to bundled platform procurement, while district hospital networks in China and India drive hardest bargain on per-probe replacement contracts.
Supply Chain Analysis
Nagoya-to-Shanghai specialty ceramics transit underwrites critical single-crystal feedstock flows for premium transducer fabrication. Piezoelectric element supply draws from Japan, Germany, and China, with probe final assembly concentrating in Yangtze River Delta and Bavarian industrial corridors. Single-source vulnerability concentrates in high-purity lead zirconate titanate formulations from Asian chemical producers. Distribution runs through hospital procurement departments, GPO contracts, and third-party clinical engineering channels with divergent service attachment rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States academic medical centers with dedicated clinical engineering departments capable of ISO 13485-certified probe refurbishment, fragmenting OEM pricing power across replacement cycles.
For Market Incumbents: Consolidate single-crystal fabrication expertise through captive supply arrangements with Nagoya-area ceramics specialists or backward integration into crystal growth operations. Deepen notified-body relationship investment to sustain CE marking velocity under EU MDR against emerging entrant delays. Defend against CMUT substitution by accelerating matrix array Doppler configurations that semiconductor alternatives cannot yet replicate at clinical scale. For New Entrants and Emerging Players: Anchor in India's district hospital infrastructure expansion, where CDSCO regulatory streamlining for Class B devices reduces import clearance friction relative to FDA or CE pathways. Target cost-optimized linear probe configurations for emergency medicine point-of-care deployment, leveraging wireless transducer convergence pilots in Mumbai diagnostic chains. Pursue OEM white-label partnerships to bypass direct hospital procurement committee barriers. For Investors and Strategic Acquirers: The market sits at a materials-transition phase that favors single-crystal fabrication specialists with export-qualified probe assembly capabilities. Long-term viability over the next decade rests on securing positions in next-generation piezoelectric supply chains before CMUT foundry economics mature. Watch FDA 510(k) clearance timeline variability and notified-body capacity constraints as inflection signals for competitive qualification speed divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Crystal Fabrication Acquisition | Captures materials science expertise concentrated among legacy Japanese and German ceramics firms. |
| CE Marking Fast-Track Investment | Accelerates EU MDR conformity timelines against notified-body backlog constraining newer entrants. |
| Wireless Transducer Platform Launch | Targets emergency medicine and field triage applications piloting Bluetooth-enabled CMUT configurations. |
| Third-Party Refurbishment Partnership | Captures aftermarket volume from academic medical centers with ISO 13485-certified clinical engineering. |
| India Distribution Channel Expansion | Penetrates underpenetrated district hospital networks via CDSCO-streamlined Class B device pathways. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, CE marking databases, and hospital procurement contracts through bottom-up and top-down triangulation. Primary interviews engaged ultrasound system product managers, biomedical engineering directors at academic medical centers, GPO contracts managers, and notified-body regulatory specialists. Secondary sources included NMPA registration filings, EU MDR technical documentation requirements, and specialty ceramics trade flow data from Japanese and German export authorities.
Segmentation dimensions modeled span product type, application, end user, and technology across the projection horizon. Convex array, phased array, linear array, and endocavitary architectures were cross-tabulated against cardiology, obstetrics, urology, and musculoskeletal applications. CAGRs derived from replacement cycle analysis, point-of-care expansion trajectories, and materials substitution curves. Forecast inputs incorporated single-crystal adoption rates, CMUT foundry capacity buildout, and regulatory qualification velocity differentials.
Material uncertainties — notified-body capacity constraints, lead zirconate titanate supply volatility, and CMUT clinical validation timelines — sit outside the modeled envelope. Forecasts reflect assumptions about acoustic output safety thresholds, electromagnetic compatibility certification stability, and hospital procurement unbundling behavior. Practitioners should keep alternative scenarios live as EU MDR implementation maturity and semiconductor-fabricated transducer clinical equivalence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Capsule Endoscope and Workstations Market
Medical Devices
Global Ventilators Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Smart Stairlift Market
Medical Devices
Contact Thermometer Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Bioimpedance Devices Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market