
 Global Network Operating Systems Market | 2026-2036
Global Network Operating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Operating Systems Market Intelligence
The market's end-user focus is broadening from traditional enterprise data centers to encompass hyperscale cloud providers and edge computing deployments. Cisco sustains a significant footprint through its extensive portfolio and established enterprise channels. Arista Networks competes on high-performance switching for cloud and data center environments. Juniper Networks differentiates with its focus on service provider and automated network solutions.
A network operating system is specialized software embedded in routers and switches, managing functions like packet forwarding and routing protocols. Its primary purpose is to orchestrate data traffic and enforce network security policies across hardware. The Data Center NOS solution type currently constitutes a major share of the market's value. Concurrently, deployments for edge computing represent the fastest-growing segment, driven by latency-sensitive applications and IoT.
Regulatory frameworks influence product design and market access, with standards from organizations like the ISO setting a baseline for interoperability. In the United States, cybersecurity mandates for government contractors shape feature requirements, while in China, MIIT directives guide network infrastructure development. The critical decision for buyers remains the strategic choice between integrated, vendor-specific ecosystems and open, disaggregated networking models.
Market Dynamics
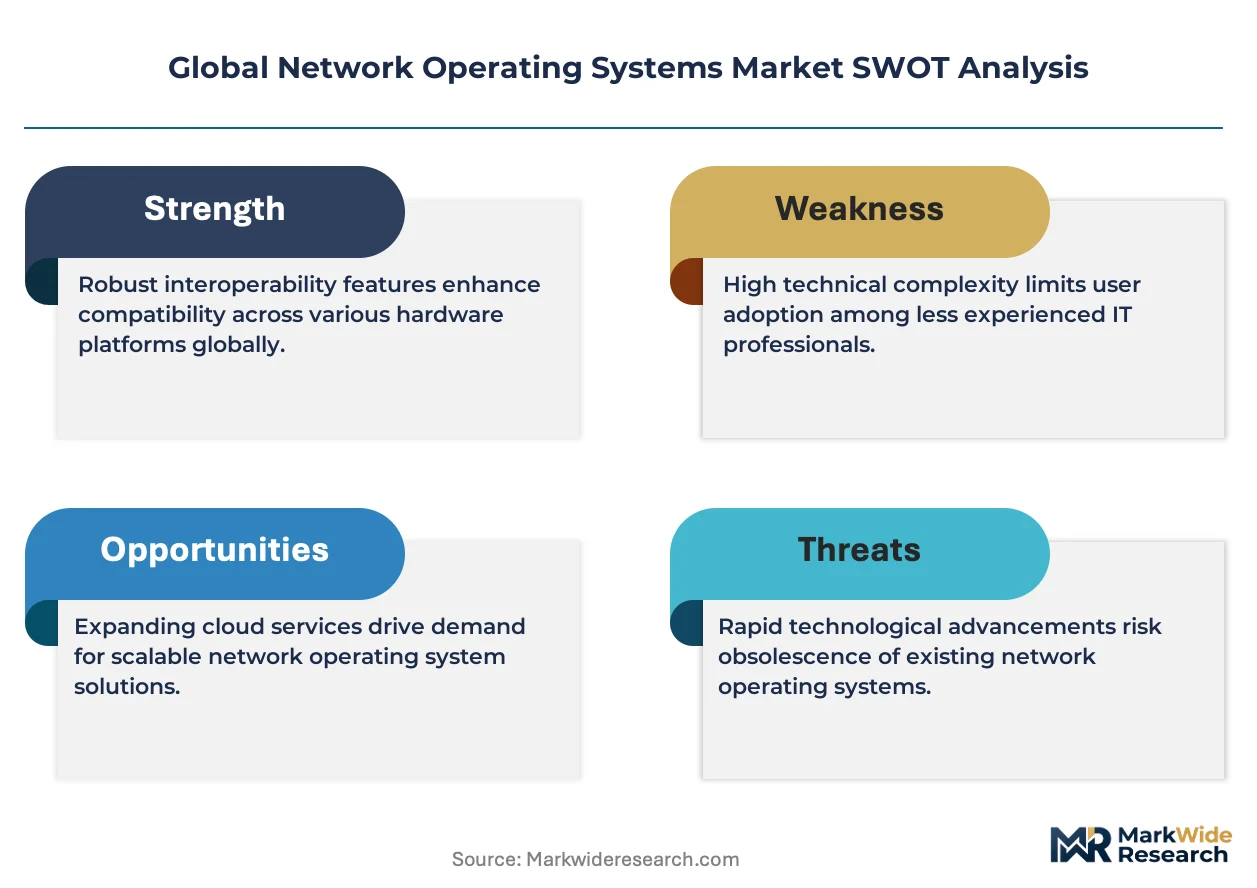
The central tension shaping the network operating system market is the strategic conflict between vertically integrated, single-vendor ecosystems and open, disaggregated networking models. This choice dictates architecture, operational flexibility, and long-term vendor dependency for enterprise and service provider customers.
Growth Catalysts
- SD-WAN Architectures:The enterprise shift to Software-Defined Wide Area Networks modernizes branch and remote office connectivity, creating direct demand for NOS platforms that can manage complex, application-aware routing policies across distributed hardware.
- Hyperscale Data Center Expansion:Construction and upgrades of massive data centers by cloud operators, particularly in the United States, require high-performance, scalable NOS solutions capable of managing tens of thousands of servers and switches.
- Edge Computing Deployments:The proliferation of IoT devices and latency-sensitive applications fuels investment in edge infrastructure, necessitating lightweight, secure, and remotely manageable network operating systems deployed outside traditional data centers.
Market Restraints
- High Switching Costs:Deep integration of proprietary NOS with specific hardware creates significant vendor lock-in, making migration to a different platform a costly and complex undertaking for established enterprises.
- Interoperability Complexity:Achieving seamless interoperability and consistent policy enforcement in multi-vendor network environments remains a significant technical hurdle, discouraging the adoption of best-of-breed but disparate solutions.
- Legacy System Inertia:Large organizations with stable, existing network infrastructure often exhibit resistance to the operational risk and re-training costs associated with adopting fundamentally new networking paradigms like disaggregation.
Strategic Opportunities
- AI-Driven Automation:Integrating artificial intelligence for IT operations (AIOps) into NOS platforms presents an opportunity to deliver self-healing, predictive networks that can preemptively identify and resolve issues, reducing downtime.
- Specialized Automotive NOS:The rise of connected and autonomous vehicles creates a new market for specialized network operating systems designed to manage in-vehicle data traffic with stringent real-time, security, and functional safety requirements.
- Open Source Adoption:Contributing to and building commercial offerings around open-source NOS projects like SONiC allows vendors to access a growing ecosystem and appeal to customers seeking to avoid vendor lock-in.
Industry Challenges
- Network Automation Skill Gap:A persistent shortage of network engineers who possess both traditional routing and switching expertise and modern software development skills (NetDevOps) slows the adoption of more advanced, programmable network solutions.
- Security Vulnerability Management:The increasing complexity and software-defined nature of modern NOS platforms expand the potential attack surface, demanding constant vigilance, rapid patching, and sophisticated security feature development from vendors.
- Standardization Pace:The development of industry-wide standards for open networking and disaggregation, while progressing, can lag behind the pace of proprietary innovation, creating periods of uncertainty for buyers committing to open models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Operating Systems Market |
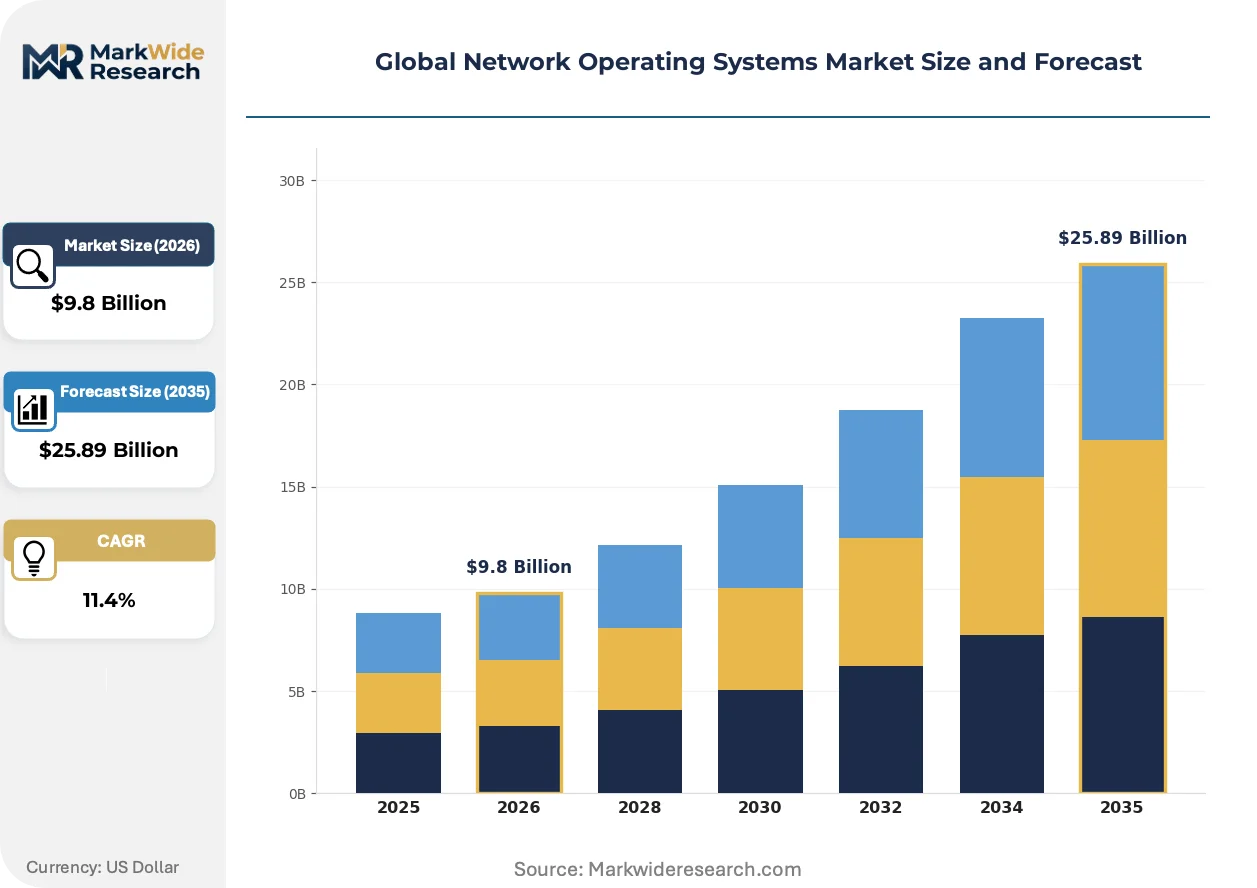
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing, Virtualized Environments Solution Type: Enterprise NOS, Carrier NOS, Data Center NOS, Industrial NOS, Embedded NOS End User Industry: Telecommunications Providers, Financial Institutions, Government Agencies, Education Institutions, Technology Firms Network Technology Supported: Ethernet, MPLS, SD-WAN, VPN, IoT Networking, 5G Networks |
| Companies Covered | Arista Networks, Huawei, Cisco, IP Infusion, Infinera, Juniper Networks, Dell, Alibaba, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Operating Systems Market Strategic Shifts & Innovations
The evolution of network operating systems is defined by a decisive shift toward software-centric models and increased abstraction from underlying hardware. This transition is enabling greater automation, flexibility, and the infusion of intelligence directly into the network fabric itself, changing how networks are built and managed.
Disaggregated networking separates the NOS software from the physical switch, offering greater choice. This approach is gaining traction among hyperscale cloud providers and large telecommunication firms seeking to optimize costs and accelerate innovation cycles. The open NOS software layer is absorbing functions previously locked into proprietary hardware, including advanced telemetry and programmable forwarding plane logic.
European Union regulations surrounding digital sovereignty, including the NIS 2 Directive, are influencing product development. This forces NOS vendors to provide greater transparency into their software supply chain and demonstrate robust cybersecurity postures. Service providers operating within the EU are consequently prioritizing suppliers that can deliver detailed security attestations and support data residency requirements.
A notable behavioral change involves a pivot from perpetual licensing toward consumption-based subscription models for advanced NOS features. This disrupts the traditional, large upfront capital expenditure cycle in favor of a more flexible operational expense model. The shift is most apparent among managed service providers, who can now align their software costs directly with customer usage and service-level agreements.
Global Network Operating Systems Market Segmentation
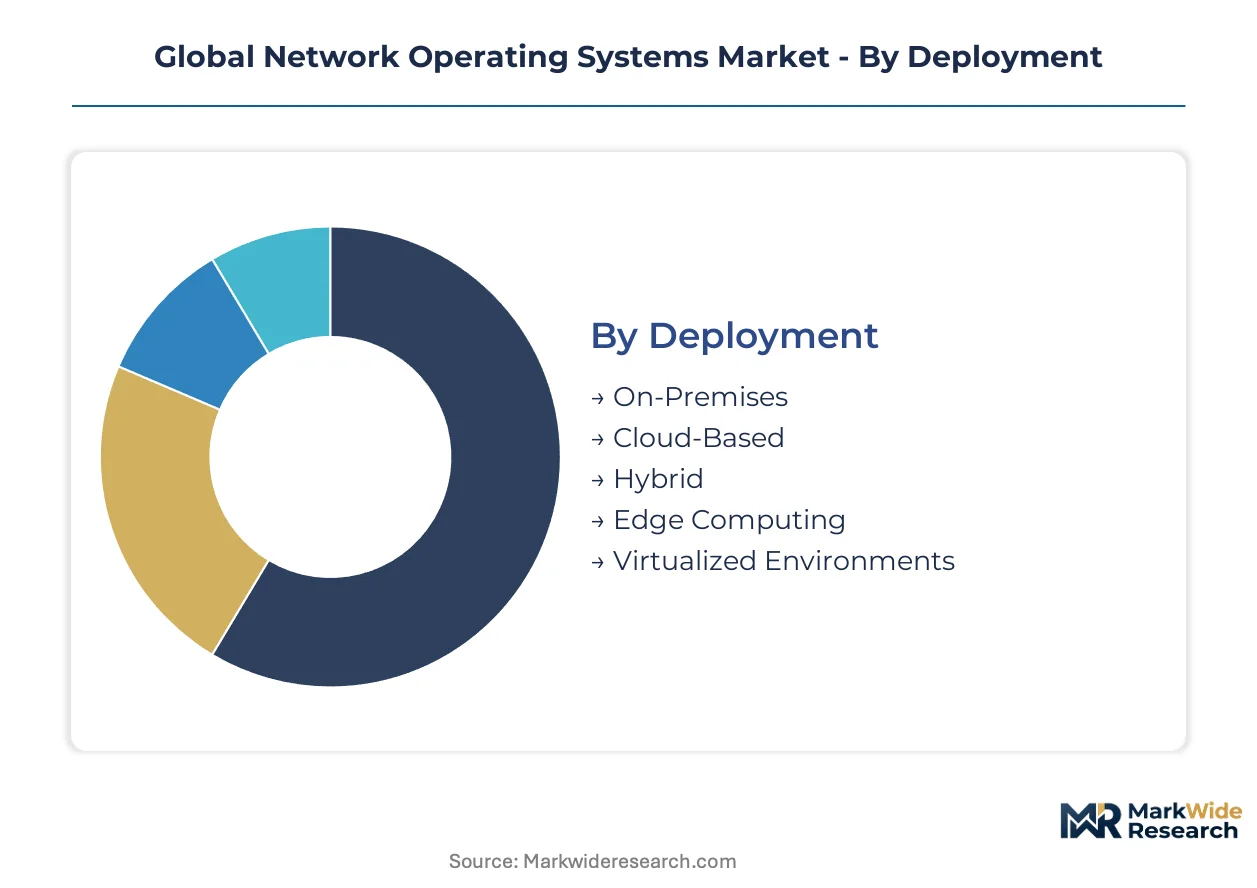
The network operating systems market is segmented by critical dimensions that reflect varying operational needs and technological priorities across diverse deployments. Analyzing these segments provides a detailed understanding of where market value is generated and where future growth drivers are concentrated. This granular view assists stakeholders in identifying key investment areas and strategic differentiation.
Deployment:
The market's deployment models demonstrate a clear split between traditional infrastructure and distributed, modern network architectures. Volume demand still originates from established on-premises solutions, while premium offerings increasingly focus on specialized cloud and edge environments.
- Edge Computing:This deployment involves NOS platforms managing network functions at the periphery of the network, closer to data sources and end-users. Demand in the United States and Europe is driven by latency-sensitive applications like industrial IoT and autonomous vehicles.
- On-Premises:These deployments involve NOS software running on hardware physically located within an organization's own data center or facilities. Large enterprises and government agencies globally continue to rely on on-premises solutions for stringent security and control requirements.
- Cloud-Based:Cloud-based NOS solutions deliver network management and control functionalities as a service over public or private cloud infrastructure. This model offers scalability and reduced capital expenditure for many global technology firms.
- Hybrid:Hybrid deployments combine elements of both on-premises and cloud-based NOS, allowing organizations to leverage the benefits of each model. Enterprises in various sectors utilize hybrid solutions for flexible workload placement.
- Virtualized Environments:These solutions involve NOS running as virtual machines on standard server hardware, decoupling network functions from dedicated physical appliances. Virtualized environments provide agility and cost efficiency for many telecommunications providers.
Mature deployment sits with On-Premises solutions. Newer deployment is concentrated in Edge Computing.
Solution Type:
Solution types for network operating systems are defined by their intended application scope, ranging from broad enterprise use to highly specialized industrial controls. Each type addresses distinct performance, security, and scalability requirements inherent to its target environment.
- Data Center NOS:This solution type is specifically designed for the high-performance, high-density networking requirements of modern data centers, managing vast numbers of servers and switches. Hyperscale cloud providers in the United States and China are significant consumers due to continuous infrastructure expansion.
- Enterprise NOS:Enterprise NOS caters to the diverse networking needs of businesses, managing local area networks (LANs) and wide area networks (WANs) for internal operations. Global corporations rely on Enterprise NOS for secure and efficient communication across their distributed offices.
- Carrier NOS:Carrier NOS is tailored for telecommunications service providers, managing large-scale, complex networks that support voice, data, and video services. Telecommunications providers in Europe and Asia are upgrading their carrier networks for 5G readiness.
- Industrial NOS:Industrial NOS operates in harsh environments, supporting critical infrastructure and operational technology (OT) networks in manufacturing, energy, and utilities. Industrial applications require robust security and real-time deterministic performance.
- Embedded NOS:Embedded NOS refers to specialized network operating systems integrated directly into networking hardware devices like routers, switches, and firewalls. These compact systems provide foundational network control and packet processing capabilities.
Data Center NOS represents the fastest-growing trajectory, driven by cloud adoption.
End User Industry:
The market's end-user landscape reflects distinct operational demands and regulatory compliance needs across various sectors. Each industry segment prioritizes specific NOS features, from high security in finance to scalability in telecommunications.
- Telecommunications Providers:These entities deploy NOS to manage their extensive infrastructure, enabling voice, data, and mobile services for vast subscriber bases. Network modernization initiatives by providers in Japan and Germany are driving significant NOS investment.
- Technology Firms:This segment includes hyperscale cloud operators, software companies, and internet service providers that require highly scalable and programmable NOS solutions. Hyperscale data center growth in the United States particularly drives demand for advanced NOS.
- Financial Institutions:Financial institutions utilize NOS for secure, high-speed transaction processing and data management across their global networks. Stringent regulatory requirements for data integrity and cybersecurity shape their NOS adoption.
- Government Agencies:Government bodies deploy NOS for secure communication, data exchange, and critical infrastructure management. Cybersecurity mandates from the US government influence feature requirements for NOS vendors.
- Education Institutions:Education institutions leverage NOS to manage campus networks, supporting student connectivity, research facilities, and administrative operations. Scalability and ease of management are key considerations for these networks.
Network expansion is driven by Telecommunications Providers and Technology Firms.
Network Technology Supported:
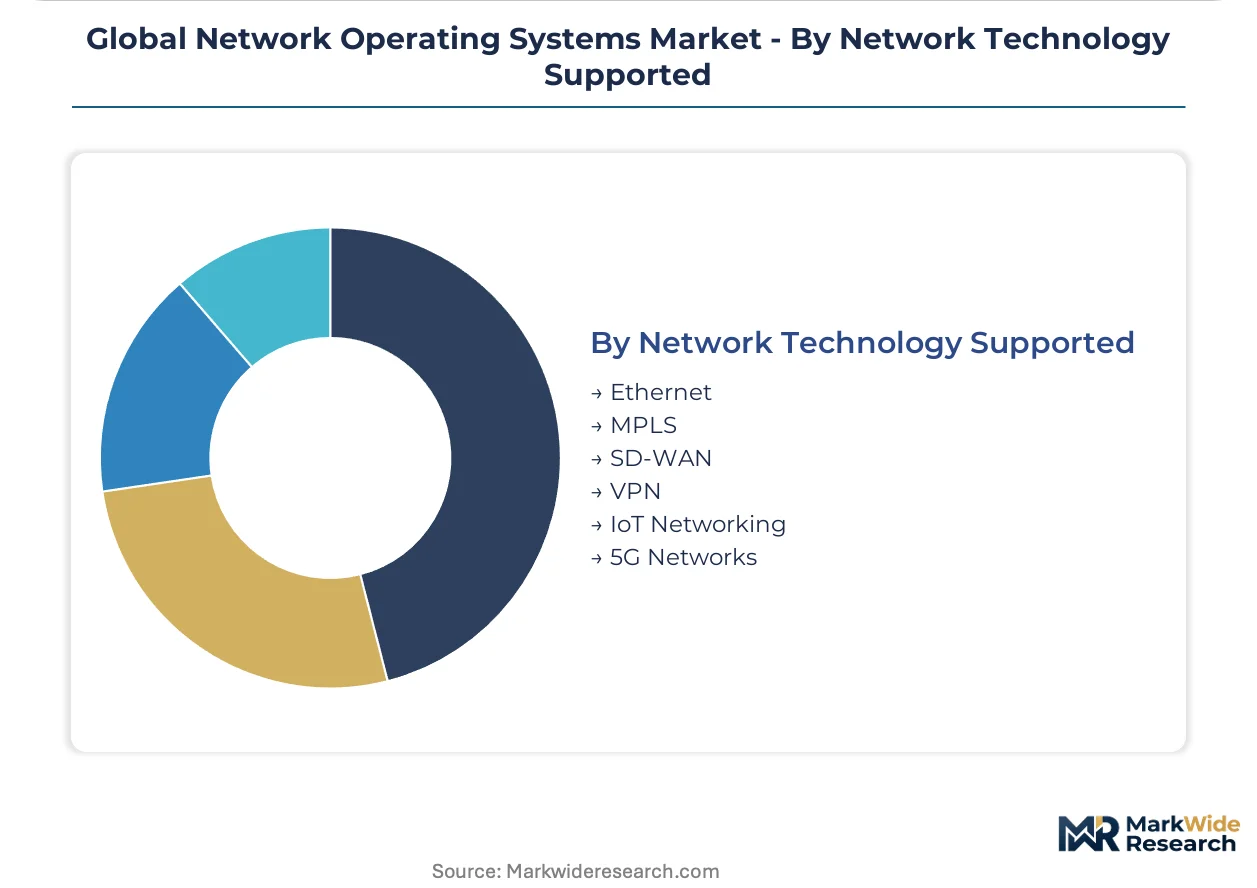
Network operating systems are continuously evolving to support new and emerging network technologies, enabling advanced capabilities like software-defined networking and IoT connectivity. Each technology segment requires specialized NOS features for optimal performance and management.
- SD-WAN:SD-WAN architectures leverage NOS to provide centralized control and intelligent traffic steering across wide area networks, optimizing application performance. Enterprises globally are adopting SD-WAN for improved branch office connectivity and cost efficiency.
- 5G Networks:NOS platforms supporting 5G are crucial for managing the complex, high-bandwidth, and low-latency requirements of next-generation mobile networks. Telecommunications providers in South Korea and China are heavily investing in 5G-capable NOS solutions.
- Ethernet:Ethernet support is fundamental for NOS, providing the foundational layer for local area network communication and data center connectivity. Ethernet remains a ubiquitous technology across all industry sectors.
- MPLS:Multi-Protocol Label Switching (MPLS) is a data-carrying mechanism that enables efficient data forwarding within telecommunications networks. Service providers utilize MPLS for traffic engineering and VPN services.
- VPN:Virtual Private Network (VPN) capabilities within NOS ensure secure, encrypted communication over public networks, connecting remote users and branch offices. Cybersecurity concerns drive continuous demand for robust VPN features.
- IoT Networking:NOS supporting IoT networking manages connectivity and data flow for a vast array of interconnected devices. Edge computing deployments are increasingly integrated with IoT networking solutions.
Significant demand originates from SD-WAN and 5G Networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' Northern Virginia data center corridor, benefiting from significant state and local tax incentives, drives substantial network operating system demand. This concentration supports hyperscale cloud providers and large-scale enterprise deployments. Such strategic zones foster innovation and investment in advanced network infrastructure.
United States
United States demand for NOS platforms stems from continuous hyperscale data center expansion and stringent government cybersecurity mandates. Federal cybersecurity mandates for contractors shape feature requirements for network operating system vendors. Major cloud operators in Silicon Valley and the Northern Virginia corridor drive significant investment.
China
China's market expansion is propelled by its massive 5G network rollout and continuous hyperscale data center construction. MIIT directives strongly guide network infrastructure development and procurement for domestic providers. The Yangtze River Delta region, including Shanghai, is a hub for advanced 5G infrastructure deployment.
Germany
German telecommunications providers are modernizing their networks, driving demand for advanced network operating systems. The EU's NIS 2 Directive influences product development, requiring greater transparency in software supply chains. Frankfurt, a critical internet exchange point, sees substantial investment in secure NOS solutions.
Japan
Japan's market for network operating systems benefits from ongoing 5G network upgrades and broad digital transformation initiatives. METI initiatives encourage the adoption of advanced IT solutions, including programmable network infrastructure. Tokyo's metropolitan area serves as a primary hub for telecom providers investing in next-generation NOS.
South Korea
South Korea drives demand through aggressive 5G network expansion and burgeoning edge computing deployments. Government policies actively promote advanced network infrastructure to support smart city initiatives and IoT. Seoul and its surrounding Gyeonggi Province are focal points for deploying next-generation, low-latency network operating systems.
Global Network Operating Systems Market Key Industry Players
Top-tier vendors anchor the global network operating systems market, while specialized solution providers and open-source contributors target niche segments. The landscape features established network equipment manufacturers, high-performance data center specialists, and agile software-centric innovators. Key archetypes include integrated hardware-software providers and disaggregated NOS developers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and technological capabilities.
Within the integrated hardware-software provider archetype, Cisco Systems Inc. maintains a significant market presence, leveraging its extensive portfolio and established enterprise channels. Arista Networks Inc. exemplifies high-performance switching specialists, primarily serving cloud and data center environments with advanced network operating systems. Juniper Networks Inc. occupies a distinct position by focusing on service provider and automated network solutions, differentiating through software-defined capabilities. These entities represent different strategic approaches to network infrastructure provision.
| Leading Market Players |
|---|
| Arista Networks |
| Huawei |
| Cisco |
| IP Infusion |
| Infinera |
| Juniper Networks |
| Dell |
| Alibaba |
| Hewlett Packard Enterprise |
| Others |
Cost & Logistics Intelligence
Specialized silicon component pricing, influenced by global semiconductor supply, cascades into the cost structures of network operating system vendors. This directly impacts premium and value-tier offerings across integrated and disaggregated solutions.
Pricing Analysis
Short lead times for bespoke network operating system deployments command premium pricing, while standardized software licenses may offer volume discounts. Subscription-based models are increasingly prevalent for advanced NOS features, aligning costs with operational expenditure. Price differentiation stems from customization levels for hyperscale data centers and the depth of integrated after-sales support. Pricing softness stems from the availability of open-source alternatives and the push for disaggregated networking. Hyperscale cloud providers exhibit high price sensitivity due to vast infrastructure, while government agencies prioritize security and compliance over cost.
Supply Chain Analysis
Workforce availability in key semiconductor manufacturing geographies, particularly Taiwan and South Korea, directly influences the supply chain for network operating systems. The NOS supply chain relies on specialized ASICs and high-performance network processors, primarily sourced from these regions. A structural risk involves single-source vulnerability for advanced chipsets, potentially disrupting hardware availability. Distribution runs through direct vendor relationships for hyperscale operators and a network of channel partners for broader enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The network operating systems market operates within a supply-constrained environment, primarily due to a persistent shortage of network automation engineers. This talent bottleneck limits the rapid adoption of advanced programmable network solutions, thereby propping up pricing for specialized integration services.
For Market Incumbents: Acquire specialized AIOps software firms to integrate predictive analytics and self-healing capabilities directly into NOS platforms. Incumbents must enhance their software-defined networking portfolios to counter the threat from open, disaggregated models. Investing in NetDevOps training programs for existing channels can mitigate the network automation skill gap. This strategy reinforces established enterprise channels against agile software-centric innovators.
For New Entrants and Emerging Players: The NIS 2 Directive in Europe opens a window for new entrants offering transparent software supply chain attestations and robust cybersecurity features. Target the rapidly growing edge computing segment with lightweight, secure, and remotely manageable NOS solutions. Focus on open-source contributions and community building to attract customers seeking to avoid vendor lock-in. A cloud-native deployment model offers a penetrable entry point for SMBs seeking operational flexibility.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term growth in foundational digital infrastructure across the next decade. Identify specialized software developers focused on AI-driven automation or industrial NOS for acquisition. These firms offer unique intellectual property and address critical skill gaps. The signal to watch is a measurable acceleration in the commercial adoption of open-source NOS solutions by large enterprises.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-driven NOS Platform | Enhances network autonomy and operational efficiency for telecommunications providers. |
| Strategic Partnership: Hyperscale Cloud Provider | Extends network operating system reach into massive data center environments. |
| Acquisition of Specialist Firm: Edge Computing NOS Developer | Accelerates market penetration in latency-sensitive IoT applications and industrial sectors. |
| Geographic Expansion: Emerging 5G Markets | Captures demand from modernizing telecommunications infrastructure in Asia and Europe. |
| Platform Integration: Open-Source NOS Projects | Appeals to customers seeking reduced vendor lock-in and cost optimization. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by extensive primary research. This involved interviews with network architects, CTOs, IT procurement officers, and telecommunications engineers across key geographies. The analysis triangulated insights from these primary discussions with validated secondary data from SEC filings and government technology mandates. Both bottom-up and top-down approaches were employed for comprehensive market sizing.
Data-stream reconciliation across multiple sources informed the forecast framework, ensuring robust market projections. Segmentation dimensions modeled included deployment, solution type, end-user industry, and network technology supported across the analysis window. Compound annual growth rates were derived from historical trends and projected technology adoption rates. Key forecast inputs included global 5G network rollout schedules and hyperscale data center construction pipelines.
The model assumes a particular technology adoption path for disaggregated networking; alternative pathways for AI-driven automation would alter the outlook. Forecasts reflect assumptions concerning geopolitical stability and the pace of regulatory evolution. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Automotive Data Management Market