
 Datacenter Network Consulting and Integration Service Market | 2026-2036
Datacenter Network Consulting and Integration Service Market Size, Share, and Industry Trends Forecast 2026-2036
Datacenter Network Consulting and Integration Service Market Intelligence
Asset-light consulting models built on outcome-based contracting and leased engineering capacity is reconfiguring competitive economics for mid-tier service providers. Cisco Systems leverages its installed base of switching hardware to anchor recurring integration revenue streams across enterprise accounts. IBM sustains premium positioning through deep vertical expertise in regulated industries, while Accenture competes by bundling network consulting with broader cloud transformation programs.
Datacenter network consulting and integration services encompass the engineering, design, and deployment of switching fabrics, routing protocols, and traffic management systems operating at speeds from 100 Gbps to 800 Gbps, with primary purpose of ensuring deterministic latency, fault tolerance, and scalable east-west traffic flows for compute-intensive workloads. Software-defined networking and automation tools represent the fastest-expanding technology focus as enterprises displace legacy CLI-managed gear, while migration planning services command outsized margins due to scarcity of engineers certified across both traditional three-tier and modern spine-leaf architectures. Private datacenters and hybrid infrastructure deployments absorb the largest share of consulting hours, though edge computing sites are emerging as a high-velocity segment where radio access network convergence demands specialized integration skill sets.
FCC regulations governing network reliability reporting for communications infrastructure, alongside EU NIS2 requirements for critical entity security, are elevating compliance advisory from optional to mandatory line items in consulting contracts. ISO 27001 and IEC 62443 standards further shape procurement criteria by mandating documented security governance across network lifecycle management. Stakeholders must weigh whether to build captive integration capabilities or deepen reliance on specialized consultants as protocol complexity accelerates with quantum-safe cryptography transitions and AI-driven network operations tooling.
Market Dynamics
Protocol complexity acceleration from spine-leaf fabric deployments and quantum-safe cryptography transitions is fragmenting vendor ecosystems and forcing enterprises toward specialized integration partners rather than generalist IT consultants.
Growth Catalysts
- EU NIS2 Directive:Mandatory operational resilience mandates for critical digital infrastructure operators in Europe are converting compliance advisory from optional to mandatory contract line items.
- Algorithmic trading platforms:Financial services firms are expanding procurement of low-latency network integration services to support deterministic sub-microsecond execution environments.
- Spine-leaf architecture:Enterprise displacement of legacy three-tier topologies is creating scarcity premiums for engineers certified across both traditional and modern fabric designs.
Market Restraints
- Engineer scarcity:Limited supply of consultants holding dual certifications in CLI-managed legacy gear and API-driven automation tooling compresses project throughput.
- Optical component volatility:Supply concentration for 800 Gbps coherent transceivers among Asian photonics foundries exposes integration timelines to semiconductor cycle fluctuations.
- ISO 27001 audit burden:Documented security governance mandates across network lifecycle management extend sales cycles by requiring pre-contract compliance verification.
Strategic Opportunities
- Edge computing sites:Radio access network convergence at distributed compute nodes demands specialized integration skill sets currently underserved by metropolitan-focused consultancies.
- IEC 62443 adoption:Industrial cybersecurity standards for operational technology networks create advisory revenue streams in manufacturing and energy verticals previously ceding security to internal IT.
- Intent-based networking:Convergence of AI-driven operations tooling with software-defined fabrics enables outcome-based pricing models that align consultant compensation with latency and availability SLAs.
Industry Challenges
- Multi-generational integration:Hybrid environments requiring seamless interconnection between 100 Gbps legacy switches and 400/800 Gbps spine-leaf fabrics multiply test and validation cycles.
- Automation toolchain fragmentation:Incompatible orchestration platforms from competing infrastructure vendors force consultants to maintain redundant engineering competencies or risk vendor lock-in disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Datacenter Network Consulting and Integration Service Market |
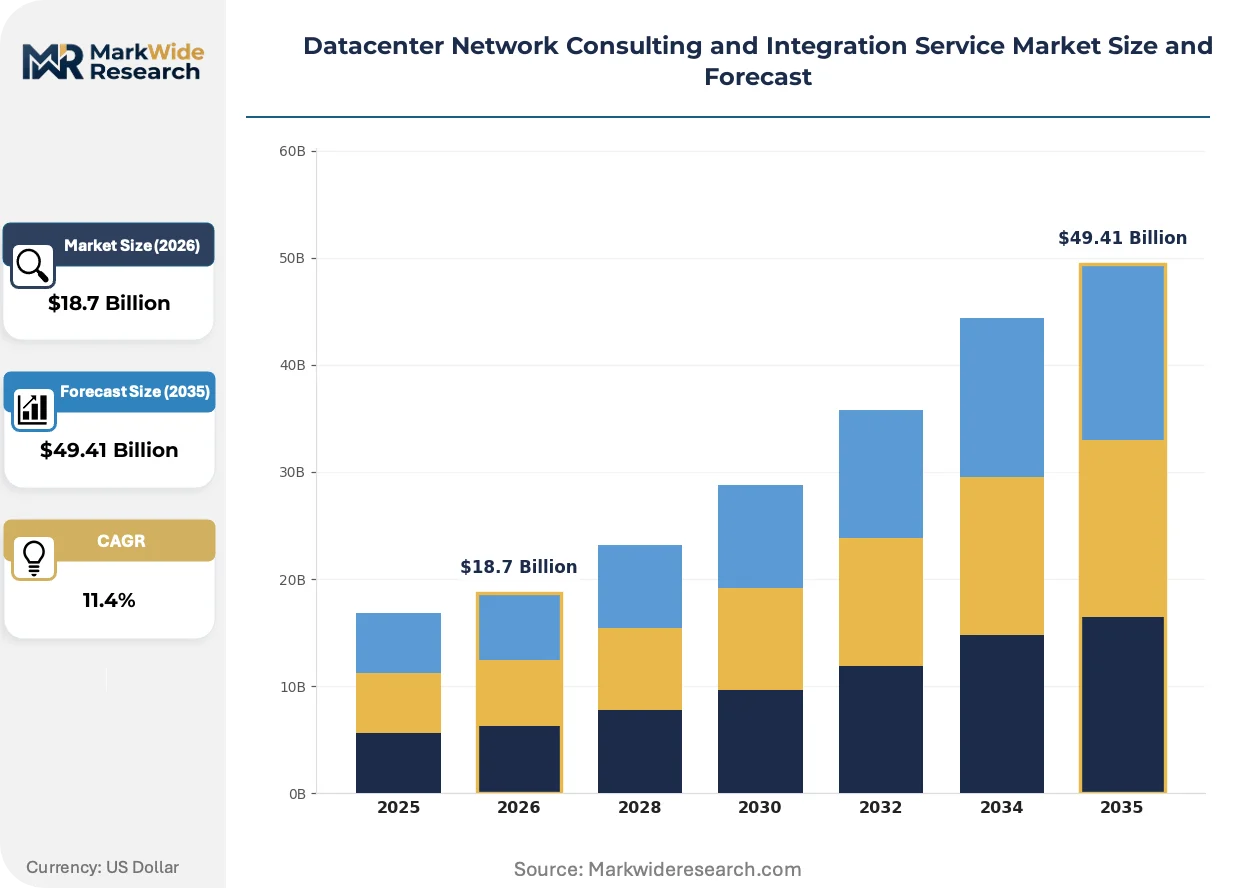
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
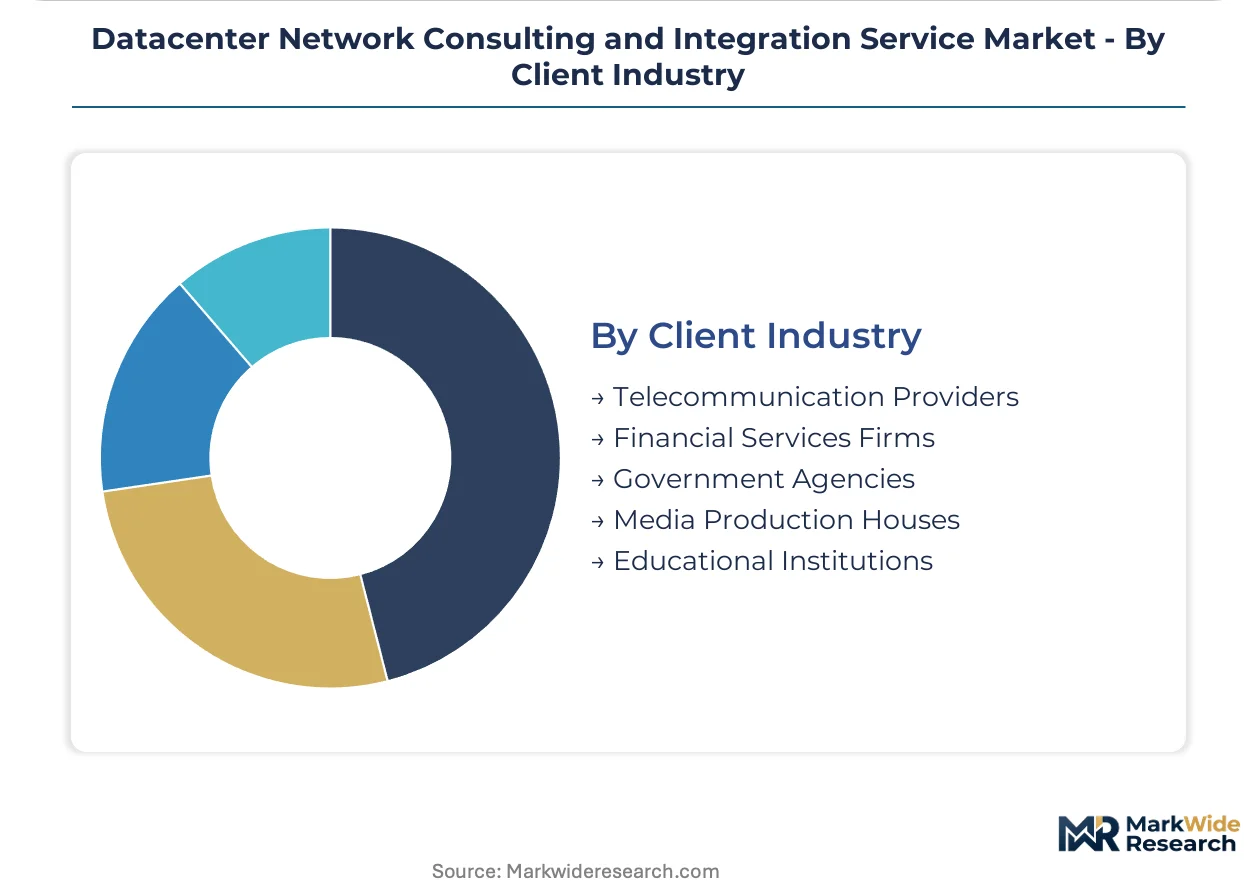
| Segmentation | Service Type: Network Architecture Design, Security Assessment, Performance Optimization, Migration Planning, Compliance Advisory Technology Focus: Software-Defined Networking, Network Function Virtualization, Cloud Connectivity, 5G Integration, Automation Tools Deployment Environment: Private Datacenters, Colocation Facilities, Edge Computing Sites, Hybrid Infrastructure, High-Performance Clusters Client Industry: Telecommunication Providers, Financial Services Firms, Government Agencies, Media Production Houses, Educational Institutions |
| Companies Covered | Cisco Systems, IBM, Hewlett Packard Enterprise, Arista Networks, Schneider Electric, Equinix, Accenture, Capgemini, Kyndryl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Datacenter Network Consulting and Integration Service Market Strategic Shifts & Innovations
Automation and policy abstraction are compressing traditional network engineering roles while elevating demand for cross-domain architects who bridge infrastructure operations with application performance engineering.
Software-defined networking controllers are migrating from pilot deployments to production fabric management. Large financial services institutions in Frankfurt and Singapore are completing full spine-leaf cutovers within eighteen-month windows. This migration from CLI-centric operational models to API-driven infrastructure is compressing headcount ratios in enterprise network teams while expanding integration contract values.
The EU AI Act's risk classification framework for automated decision-making systems is mandating explainability documentation for AI-driven network operations tools. Infrastructure operators deploying predictive traffic engineering must now maintain audit trails for algorithmic routing decisions. European datacenter operators are responding by embedding compliance specialists within integration project teams rather than treating documentation as post-deployment deliverables.
Enterprise buyers are unbundling hardware procurement from integration services, awarding multi-vendor fabric contracts to independent consultants rather than incumbent equipment suppliers. Channel partners in Germany and the Netherlands are repositioning as pure-play integration boutiques, shedding resale margins to capture higher-margin engineering hours. This disintermediation is most visible among regulated financial institutions seeking architectural independence from single-vendor roadmaps.
Datacenter Network Consulting and Integration Service Market Segmentation
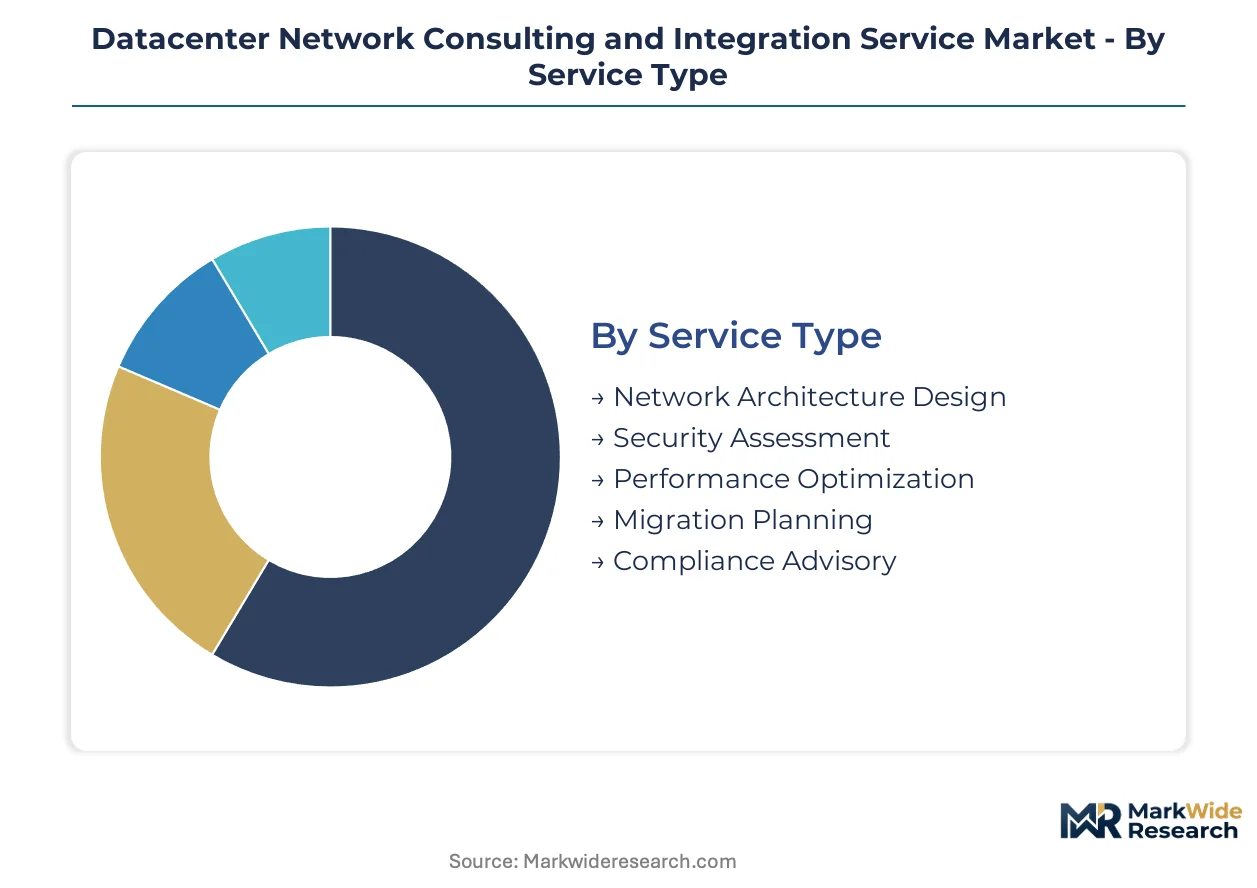
Consulting engagement models diverge sharply across service types and deployment environments, with procurement patterns shifting toward outcome-based contracts in high-velocity segments. Technology focus areas determine engineer certification requirements and margin structures, while client industry verticals impose distinct compliance burdens that reshape project staffing ratios.
Service Type:
Cost tier separates advisory engagements from implementation-heavy contracts, with premium pricing attaching to scarce technical competencies.
- Network Architecture Design:Spine-leaf fabric engineering and deterministic latency specification for algorithmic trading environments command day-rate premiums. Frankfurt's financial services cluster drives concentrated demand for sub-microsecond topology consulting.
- Migration Planning:Three-tier to spine-leaf cutover sequencing and traffic validation protocols absorb the largest share of billable hours across enterprise accounts. Scarcity of engineers dual-certified in CLI-managed legacy gear and API-driven automation sustains margin premiums.
- Security Assessment:ISO 27001 and IEC 62443 gap analysis for operational technology networks.
- Performance Optimization:East-west traffic engineering and congestion management for compute-intensive workloads.
- Compliance Advisory:EU NIS2 Directive and EU AI Act documentation mandates for critical infrastructure operators.
Migration Planning holds installed capacity. Compliance Advisory is rotating up the share rankings.
Technology Focus:
Application workload characteristics determine which automation layers enterprises prioritize in consulting procurement.
- Software-Defined Networking:Controller-based fabric management displacing CLI-centric operational models in production environments. Financial institutions in Singapore and Frankfurt are completing full spine-leaf cutovers within compressed eighteen-month windows.
- Automation Tools:Intent-based networking and AI-driven operations tooling enabling outcome-based pricing aligned with latency SLAs. Toolchain fragmentation across competing vendor ecosystems forces consultants to maintain redundant engineering competencies.
- Network Function Virtualization:Virtualized routing and security service chaining for cloud-native workloads.
- Cloud Connectivity:Multi-cloud backbone architecture and direct interconnect provisioning.
- 5G Integration:Radio access network convergence at distributed edge compute nodes.
Software-Defined Networking dominates current billings. Automation Tools is climbing the fastest.
Deployment Environment:
Volume concentration in private facilities contrasts with velocity advantages at distributed edge sites.
- Private Datacenters:Captive infrastructure deployments absorbing the largest share of consulting hours through multi-generational integration complexity. Hybrid interconnection between 100 Gbps legacy switches and 400/800 Gbps spine-leaf fabrics multiplies test and validation cycles.
- Edge Computing Sites:Distributed compute nodes demanding specialized radio access network convergence skill sets currently underserved by metropolitan-focused consultancies. Supply concentration for 800 Gbps coherent transceivers exposes integration timelines to semiconductor cycle fluctuations.
- Colocation Facilities:Cross-connect engineering and inter-datacenter latency optimization.
- Hybrid Infrastructure:Seamless workload portability across on-premises and cloud fabrics.
- High-Performance Clusters:RDMA over Converged Ethernet and GPU interconnect topology for AI training environments.
Private Datacenters anchor current revenue. Edge Computing Sites is gaining share fastest.
Client Industry:
Customer type determines procurement sophistication and contract structure preferences.
- Financial Services Firms:Algorithmic trading platforms and deterministic execution environments driving procurement of low-latency network integration. German banks are unbundling hardware procurement from integration services to secure architectural independence.
- Telecommunication Providers:5G core network slicing and subscriber plane function virtualization at national scale.
- Government Agencies:Classified facility accreditation and supply chain security verification mandates.
- Media Production Houses:Uncompressed video transport and real-time rendering farm connectivity.
- Educational Institutions:Research network backbone participation and campus SD-WAN deployment.
Financial Services Firms command premium pricing. Telecommunication Providers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in datacenter network consulting services favor net-importing financial centers over manufacturing-heavy economies. The United States and Germany absorb disproportionate shares of specialized integration capacity, while Singapore and Ireland function as regional service export hubs for Asia-Pacific and Europe respectively.
United States
Financial services firms in New York and Chicago are expanding procurement of low-latency network integration for algorithmic trading platforms. FCC regulations governing network reliability reporting for communications infrastructure elevate compliance advisory to mandatory contract status. Northern Virginia's datacenter corridor concentrates demand for spine-leaf fabric engineering at hyperscale facilities.
Germany
Frankfurt's financial services cluster drives concentrated demand for sub-microsecond topology consulting and deterministic latency specification. The EU NIS2 Directive mandates operational resilience requirements for critical digital infrastructure operators, converting compliance advisory from optional to mandatory line items. Bavaria's industrial automation sector is adopting IEC 62443 standards for operational technology network security assessments.
Singapore
Telecommunication providers are deploying 5G core network slicing and subscriber plane function virtualization at national scale. The country's national cybersecurity regulator enforces strict operational resilience mandates for critical infrastructure operators. Marina Bay and Changi datacenter zones attract regional headquarters of global consulting firms serving Southeast Asian financial institutions.
United Kingdom
London's financial services firms are unbundling hardware procurement from integration services to secure architectural independence from single-vendor roadmaps. The EU AI Act's risk classification framework for automated decision-making systems mandates explainability documentation for AI-driven network operations tools. Slough and Docklands datacenter clusters concentrate demand for hybrid infrastructure deployment expertise.
Japan
Enterprise buyers in Tokyo and Osaka are completing full spine-leaf cutovers within compressed eighteen-month windows. METI industrial policy promotes software-defined networking adoption in manufacturing and energy verticals. Osaka's growing datacenter cluster is emerging as a secondary hub for low-latency financial network architectures serving Asian markets.
Datacenter Network Consulting and Integration Service Market Key Industry Players
On the supply side, the industry is consolidating around three distinct tiers: hardware-anchored incumbents with installed base leverage, pure-play consulting boutiques with specialized engineering depth, and systems integrators bundling network services with broader transformation programs. Strategic archetypes include captive hardware ecosystems, outcome-based engineering boutiques, and cloud-native integration specialists. Dominant competitive moves encompass geographic expansion into edge computing markets and strategic partnerships between equipment vendors and automation software providers.
Within the hardware-anchored tier, Cisco Systems and Arista Networks occupy positions where switching hardware installed base generates recurring integration revenue attachment. IBM exemplifies the premium-positioned systems integrator archetype through deep vertical expertise in regulated industries. Accenture sits within the cloud-native transformation bundle segment, competing by integrating network consulting with broader enterprise modernization programs. Hewlett Packard Enterprise represents the hybrid infrastructure specialist archetype spanning both hardware supply and services delivery.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM |
| Hewlett Packard Enterprise |
| Arista Networks |
| Schneider Electric |
| Equinix |
| Accenture |
| Capgemini |
| Kyndryl |
| Others |
Cost & Logistics Intelligence
Frankfurt's datacenter corridor concentrates specialized engineering capacity for sub-microsecond network architectures, translating supply scarcity into premium day-rate pricing for spine-leaf fabric consultants serving algorithmic trading platforms.
Pricing Analysis
Industrial OEM buyers anchor project-based consulting contracts where pricing stratifies across premium, standard, and economy tiers based on engineer certification level and customization depth. Price differentiation rests on ISO 27001 compliance documentation and dual CLI-API automation credentials. Cost compression in mid-tier migration planning services is intensifying because engineer scarcity extends project timelines. Financial services firms in Germany exhibit lowest price sensitivity due to regulatory mandates, while educational institutions face procurement constraints.
Supply Chain Analysis
Extended payment terms from hyperscale datacenter operators are reshaping cash-flow dynamics for integration boutiques competing with hardware-anchored incumbents. Component sourcing draws from Taiwan, South Korea, and Japan for 800 Gbps coherent transceivers and photonics foundry output. Single-source vulnerability in Asian semiconductor manufacturing exposes project timelines to cycle fluctuations. Distribution runs through direct enterprise contracts and channel partnerships with colocation facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical engineer scarcity as training pipeline expansion and automation tooling adoption restore project throughput capacity.
For Market Incumbents: Harden installed-base leverage by embedding compliance specialists within integration teams to capture mandatory EU NIS2 advisory revenue. Deepen vertical expertise in IEC 62443-certified operational technology networks to defend against pure-play boutiques. Fortify channel control through outcome-based contracting models that align compensation with latency SLAs.
For New Entrants and Emerging Players: Establish a beachhead in edge computing radio access network convergence, a segment currently underserved by metropolitan-focused consultancies. Target manufacturing and energy verticals adopting industrial cybersecurity standards previously ceded to internal IT. Lead with intent-based networking expertise to differentiate from CLI-centric legacy competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hardware-anchored platforms with switching installed base generating integration attachment. Long-term viability favors boutiques with captive certification pipelines and outcome-based contract books. Monitor quantum-safe cryptography transition timelines as inflection indicator for specialized integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | Dual CLI-API credentials command scarcity premiums in migration planning contracts. |
| Edge Computing Geographic Expansion | Radio access network convergence skill sets capture underserved distributed compute demand. |
| Compliance Advisory Embedding | EU NIS2 and EU AI Act mandates convert documentation from optional to mandatory revenue. |
| Automation Toolchain Partnership | Intent-based networking alliances enable outcome-based pricing aligned with latency SLAs. |
| Vertical Specialization Acquisition | IEC 62443 expertise unlocks manufacturing and energy advisory revenue streams. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, customs records, and industry association reports. Network architects, datacenter operations directors, procurement officers at financial institutions, and channel sales heads at equipment vendors provided qualitative input. Bottom-up project pipeline analysis triangulates against top-down market sizing across service type, technology focus, deployment environment, and client industry dimensions.
Forecast inputs span spine-leaf migration velocity, automation tooling adoption curves, regulatory compliance mandate expansion, and edge computing deployment rates across the projection horizon. Segmentation modeling incorporates service type complexity tiers, certification scarcity premiums, and regional datacenter construction pipelines. CAGRs derive from engineer supply elasticity and contract value expansion trajectories.
Stress conditions across semiconductor cycle volatility, regulatory enforcement intensity, and automation displacement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about engineer training pipeline throughput and hyperscale facility buildout schedules. Macroeconomic contraction, accelerated quantum-safe cryptography mandates, or vendor consolidation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
South Korea Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Network Function Virtualization (NFV) Market
Data Center and Networking
Software Defined Video Networking Market
Data Center and Networking
Vietnam Data Center Networking Market