
 Saudi Arabia Data Center Server Market | 2026-2036
Saudi Arabia Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Data Center Server Market Insights
Saudi server manufacturing capacity is shifting toward localized assembly and regional distribution hubs. Dell Technologies leverages its direct-to-enterprise channel to sustain strong positions in government and BFSI verticals. Huawei Technologies Co. Ltd anchors significant infrastructure builds through partnerships with domestic cloud operators. Hewlett Packard Enterprise competes on liquid-cooled server designs optimized for the Kingdom's high-temperature operating environments.
A data center server is a high-performance computing device engineered with multi-socket processors, ECC memory, redundant power supplies, and hot-swappable storage bays, designed to process, store, and manage networked workloads for enterprise and cloud environments. Rack servers dominate enterprise deployments due to density-optimized form factors that maximize power usage effectiveness in constrained facility footprints. Blade server architectures command premium positioning in hyperscale and HPC installations where shared chassis infrastructure reduces cabling complexity and improves thermal management. Edge computing deployments represent the fastest-expanding technology segment as telecommunications operators distribute compute capacity closer to end users for latency-sensitive applications.
SFDA guidelines for medical data localization and NCA cybersecurity frameworks mandate domestic server residency for sensitive workloads, directly stimulating on-premises and colocation demand. The CITC spectrum and data center licensing regime shapes facility certification requirements that determine which server configurations qualify for critical infrastructure status. Stakeholders must monitor evolving sovereign cloud mandates and cooling efficiency standards as determinants of procurement specifications and vendor qualification criteria.
Market Dynamics
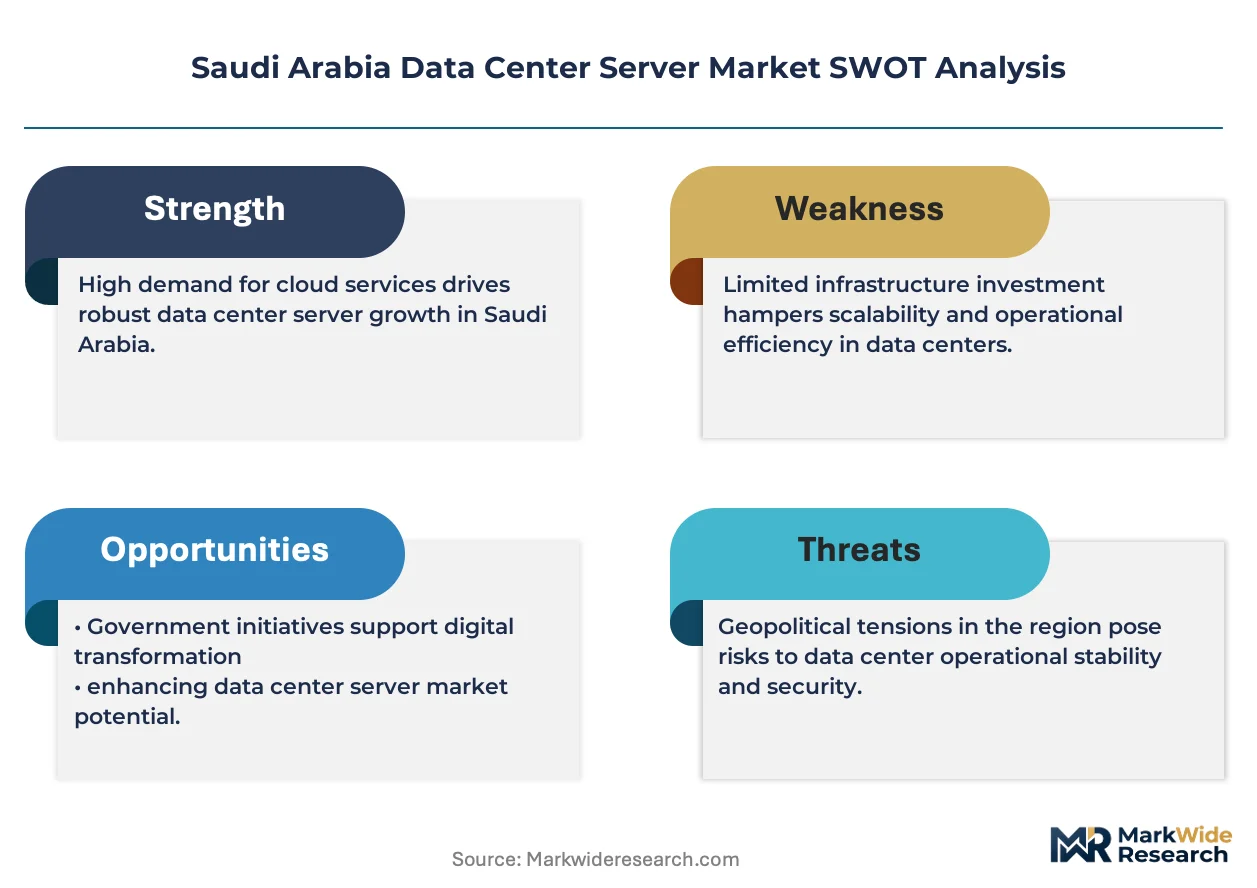
Sovereign data mandates from the National Data Management Office are restructuring procurement specifications across Saudi Arabia's data center server landscape, forcing vendors to certify hardware configurations for domestic residency compliance.
Growth Catalysts
- SFDA Medical Data Localization:Healthcare workloads must reside on Kingdom-certified servers, expanding colocation demand from hospital networks and pharmaceutical distributors.
- Smart City Edge Deployments:NEOM and Riyadh's urban digital infrastructure projects require distributed compute nodes with sub-10 millisecond latency specifications.
- Liquid Cooling Adoption:Ambient temperatures exceeding 45°C in Eastern Province facilities are accelerating immersion-cooled rack deployments for thermal efficiency compliance.
Market Restraints
- Semiconductor Supply Concentration:Advanced processor and memory module sourcing remains concentrated among East Asian foundries, exposing procurement timelines to geopolitical shipping disruptions.
- Specialized Technical Labor Scarcity:Certified data center engineers and liquid cooling technicians command premium wages that inflate facility operating expenditures.
- NCA Cybersecurity Certification Delays:Extended approval timelines for critical infrastructure server configurations compress deployment windows for time-sensitive sovereign cloud contracts.
Strategic Opportunities
- Eastern Province Industrial Clusters:Jubail and Ras Al-Khair petrochemical complexes present untapped demand for on-premises edge servers supporting predictive maintenance analytics.
- CITC Spectrum Licensing Expansion:New millimeter-wave allocations enable telecommunications operators to deploy mobile edge computing nodes for autonomous logistics applications.
- AI Training Workload Migration:Large language model fine-tuning requirements from government research institutes are creating demand for GPU-dense server configurations with localized Arabic-language data pipelines.
Industry Challenges
- Legacy Infrastructure Integration:Government entities operate heterogeneous server fleets spanning three generations of Intel and AMD architectures, complicating unified management platform deployments.
- Certification Timeline Compression:Rapidly evolving SFDA and NCA standards require vendors to recertify hardware configurations within 18-month windows, straining engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Data Center Server Market |
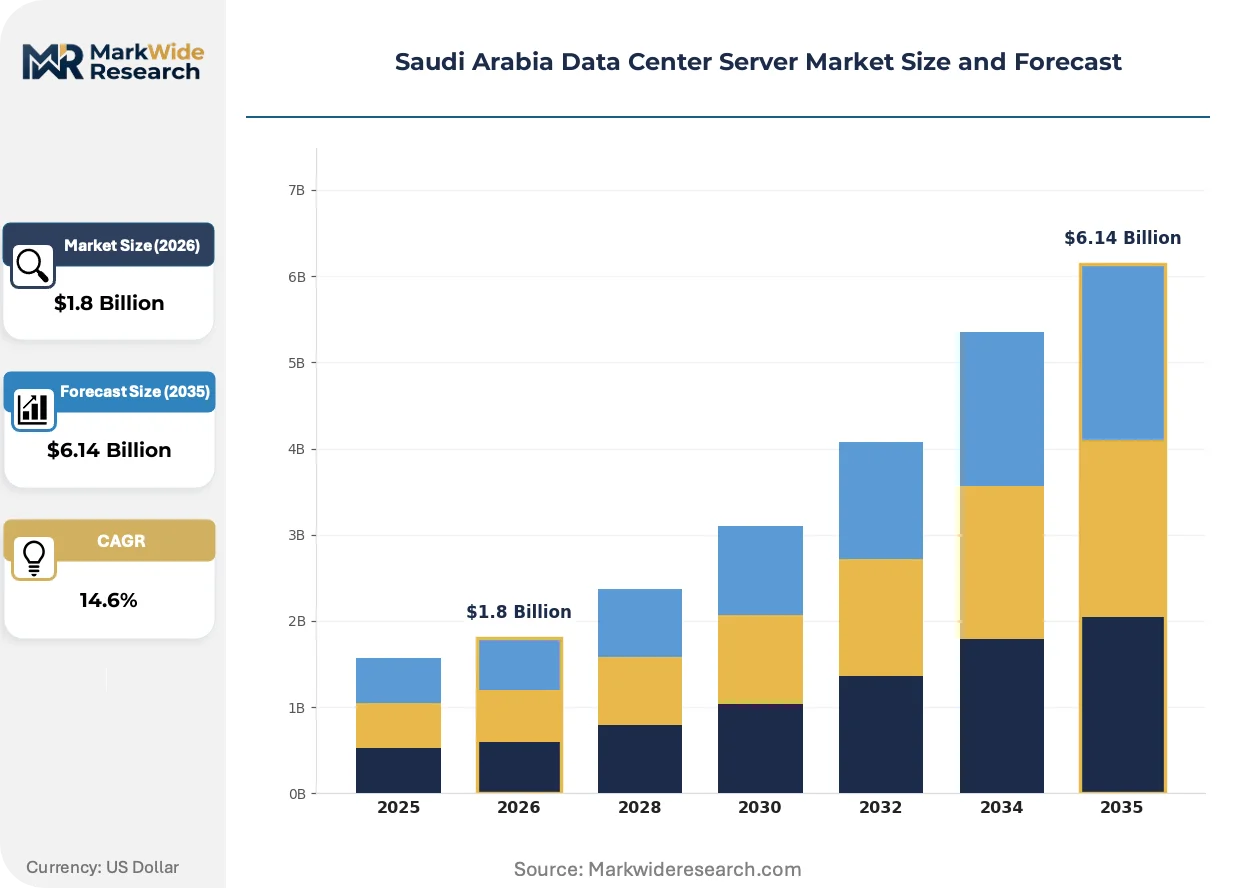
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Micro Servers End User: Telecommunications, BFSI, Government, Healthcare Technology: Virtualization, Cloud Computing, Edge Computing, HPC Deployment: On-Premises, Colocation, Hybrid, Managed Services |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, IBM Corporation, Lenovo Group Ltd, Cisco Systems Inc., Huawei Technologies Co. Ltd, Super Micro Computer Inc., Inspur Group, Quanta Computer Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Data Center Server Market Trends and Innovations
Liquid-cooled server architectures and sovereign cloud certification requirements are reconfiguring vendor qualification criteria across Saudi Arabia's data center procurement landscape.
Immersion cooling systems utilizing dielectric fluids are overtaking traditional air-cooled designs in Riyadh and Jeddah hyperscale facilities. Saudi Aramco's digital infrastructure division has standardized on single-phase immersion for new 50MW+ deployments. This thermal architecture is overtaking conventional raised-floor designs by enabling power densities exceeding 50kW per rack without mechanical refrigeration overhead.
CITC's updated Data Center Licensing Framework now mandates ISO 27001 and Tier III uptime certification for facilities hosting government cloud workloads. The regulation compresses competitive qualification to a handful of domestic operators with capital reserves for redundant electrical infrastructure. Western Region operators in Jeddah are responding by retrofitting existing facilities with concurrent maintainable power distribution systems.
Server procurement through systems integrators rather than direct OEM relationships is gaining traction among mid-tier enterprises in the Central Region. Local value-added resellers now bundle hardware with managed services and NCA compliance consulting, displacing traditional volume purchasing agreements. This channel evolution is most visible among BFSI institutions seeking turnkey sovereign data residency solutions without internal infrastructure expertise.
Saudi Arabia Data Center Server Market Segmentation
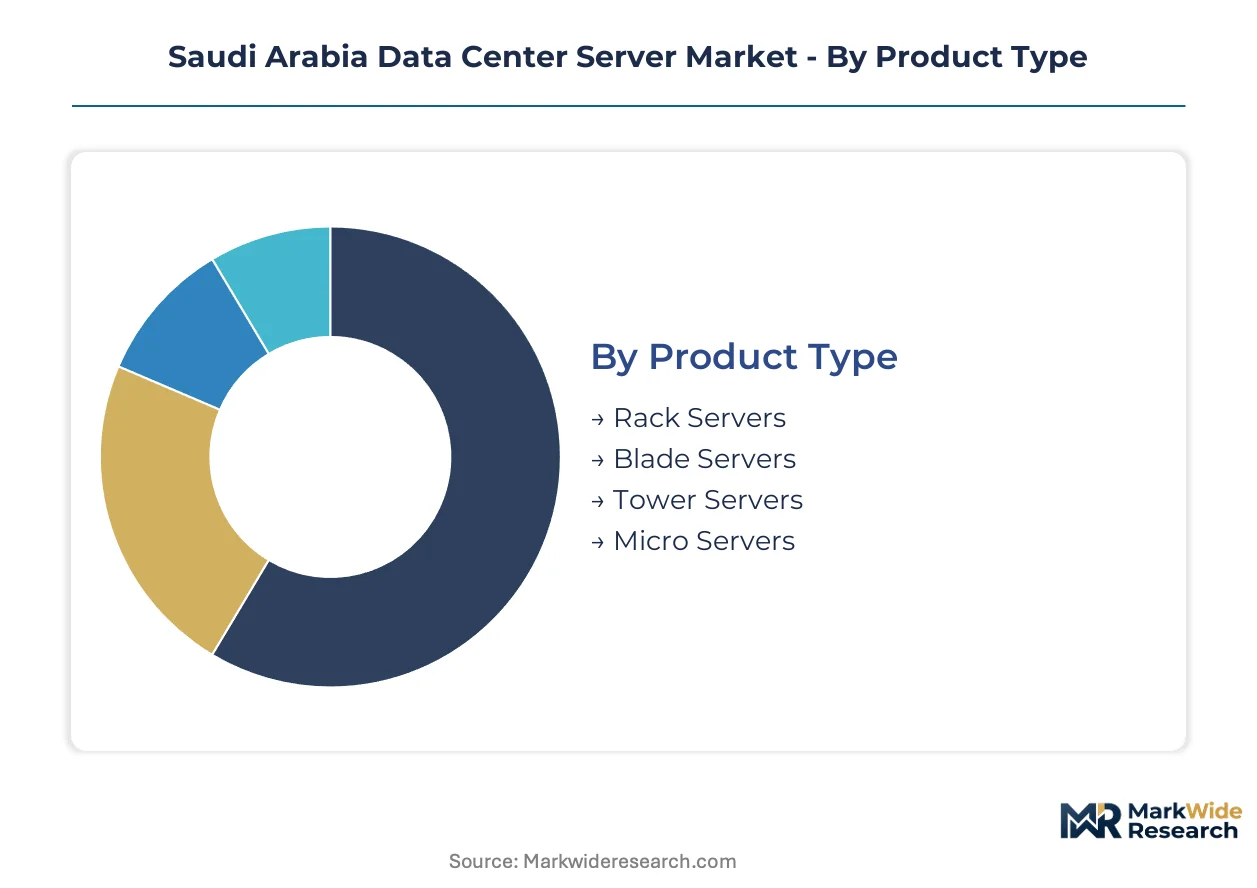
Procurement specifications in Saudi Arabia diver sharply across workload types, with sovereign data mandates and thermal constraints reshaping how buyers evaluate form factors and deployment architectures. Understanding segment-level decision drivers reveals where vendor qualification requirements tighten and where channel strategies must adapt.
Product Type:
Density requirements and cooling infrastructure availability dominate hardware selection across Riyadh and Jeddah facilities.
- Rack Servers:Standard 1U-4U enclosures with hot-swappable drive bays and redundant power supplies constitute the workhorse configuration for enterprise data halls. Demand concentrates in government ministries and BFSI institutions seeking certified hardware for National Data Management Office compliance without custom engineering.
- Blade Servers:Shared chassis architectures with midplane interconnects reduce cabling complexity and improve thermal uniformity in hyperscale deployments. NEOM's smart city infrastructure and Saudi Aramco's digital divisions specify blade systems for HPC clusters where space constraints outweigh per-unit cost premiums.
- Tower Servers:Standalone pedestal configurations serve remote branch offices and small healthcare clinics requiring on-premises medical data residency under SFDA guidelines without dedicated data hall construction.
- Micro Servers:Ultra-compact single-socket nodes target edge computing sites in Eastern Province industrial zones where physical footprint and power draw must minimize operational overhead.
Volume sits with rack servers; growth tilts toward blade servers.
End User:
Regulatory pressure intensity varies by vertical, directly mapping to procurement urgency and certification stringency.
- Telecommunications:CITC-licensed operators in Riyadh and Jeddah deploy distributed edge nodes to meet sub-10 millisecond latency specifications for 5G network slicing and autonomous logistics applications. STC and Mobily are expanding server procurement for mobile edge computing infrastructure.
- BFSI:SAMA regulatory requirements for financial data localization drive colocation demand from banks lacking internal sovereign cloud expertise. SABB and Al Rajhi Bank have migrated core workloads to certified domestic facilities.
- Government:National Data Management Office mandates require all sensitive workloads to reside on Kingdom-certified hardware, making this vertical the most certification-dependent procurement environment.
- Healthcare:SFDA medical data localization rules force hospital networks and pharmaceutical distributors to abandon offshore hosting, directly stimulating on-premises and colocation server demand.
Procurement volume clusters in telecommunications; regulatory urgency peaks in healthcare.
Technology:
Workload abstraction layers determine hardware utilization rates and facility certification complexity.
- Virtualization:Hypervisor-based server consolidation remains prevalent in legacy government data centers seeking to extend three-generation Intel and AMD fleet lifecycles without full hardware refresh.
- Cloud Computing:Multi-tenant infrastructure demands from domestic cloud operators are expanding GPU-dense configurations for Arabic-language AI training pipelines.
- Edge Computing:Distributed compute nodes positioned closer to end users than regional data centers are climbing the fastest as NEOM and Riyadh smart city projects mandate sub-10 millisecond response times.
- HPC:Liquid-cooled clusters for scientific computing and reservoir simulation serve Saudi Aramco and KAUST research institutes with specialized thermal and interconnect requirements.
Mature deployments favor virtualization; capex allocation shifts toward edge computing.
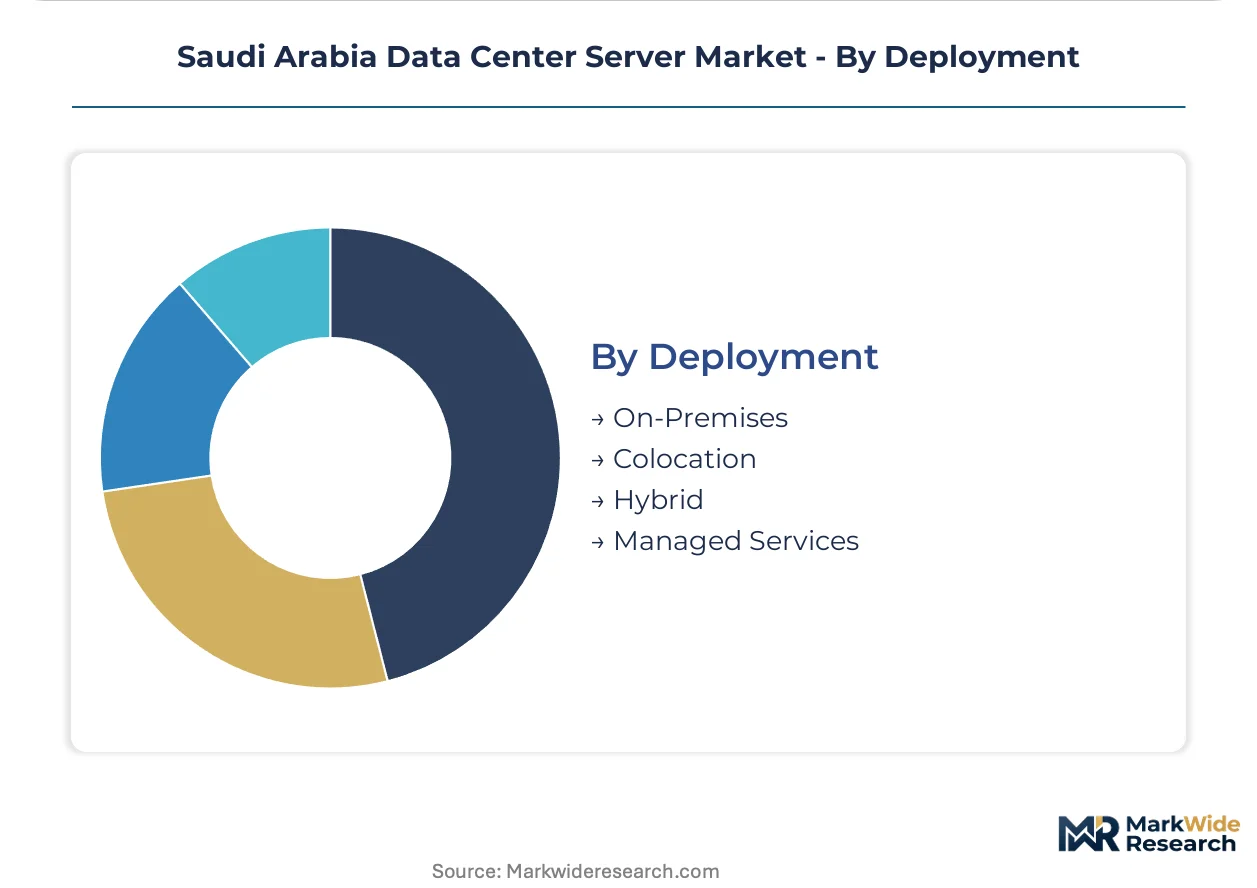
Deployment:
Capital availability and internal technical capacity determine whether buyers own, lease, or outsource infrastructure.
- On-Premises:Owned and operated facilities persist in defense and intelligence sectors where NCA cybersecurity frameworks mandate physical control over critical infrastructure.
- Colocation:Wholesale and retail space leasing dominates BFSI and healthcare verticals seeking sovereign data residency without facility construction expertise. Khurais and Sudair are emerging as colocation clusters.
- Hybrid:Split workload architectures combining on-premises sovereignty with burst capacity to domestic cloud are gaining traction among mid-tier enterprises in the Central Region.
- Managed Services:Turnkey infrastructure with bundled NCA compliance consulting displaces direct OEM purchasing for institutions lacking certified data center engineering staff.
Colocation captures current volume; managed services are expanding most quickly among mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in East Asia feed component supply chains that terminate in Riyadh and Jeddah assembly facilities. Domestic data center construction concentrates where CITC licensing and SFDA medical data localization intersect with ambient thermal stress.
Riyadh
Central Region ministries and BFSI headquarters drive rack server procurement for National Data Management Office compliance. CITC's Tier III certification requirements filter colocation entrants to operators with redundant electrical infrastructure. King Abdullah Financial District anchors sovereign cloud deployments from STC and Mobily.
Eastern Province
Jubail and Ras Al-Khair petrochemical complexes generate edge computing demand for predictive maintenance analytics. Ambient temperatures exceeding 45°C accelerate immersion-cooled rack adoption for thermal efficiency compliance. Saudi Aramco's digital infrastructure division standardizes on single-phase liquid cooling for 50MW-plus facilities.
Western Region
Jeddah's Red Sea port position supports import-dependent server assembly and regional distribution hub functions. SAMA-regulated banks lacking internal sovereign cloud expertise migrate core workloads to certified domestic colocation. Retrofit activity concentrates on concurrent maintainable power distribution upgrades.
NEOM Northwest
Smart city infrastructure mandates sub-10 millisecond latency specifications that distribute compute nodes closer to end users than regional data centers. NEOM's urban digital backbone requires GPU-dense configurations for Arabic-language AI training pipelines. Mobile edge computing infrastructure serves autonomous logistics applications across the linear city development.
Saudi Arabia Data Center Server Market Competitive Landscape
Global majors compete with regional champions across certification pathways and thermal engineering capabilities. The vendor base stratifies between full-stack systems integrators and component-specialized fabricators. Three archetypes dominate: direct-to-enterprise OEMs with sovereign cloud consulting capabilities, Asia-based scale manufacturers with cost-optimized rack configurations, and liquid-cooled engineering specialists targeting high-temperature operating environments. Competitive moves concentrate on strategic partnerships with domestic cloud operators and portfolio diversification into edge-optimized form factors.
Within the direct-to-enterprise tier, Dell Technologies and Hewlett Packard Enterprise occupy positions anchored by government and BFSI vertical relationships. Huawei Technologies Co. Ltd exemplifies the Asia-based scale manufacturer archetype through infrastructure build partnerships with domestic operators. These three represent divergent geographic origins and channel strategies while converging on NCA cybersecurity certification as a common qualification barrier.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Lenovo Group Ltd |
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd |
| Super Micro Computer Inc. |
| Inspur Group |
| Quanta Computer Inc. |
| Others |
Pricing and Supply Chain Analysis
Processor and memory module costs originating from East Asian foundries cascade through three distinct pricing tiers before reaching Saudi buyers, with NCA cybersecurity certification premiums separating government-grade configurations from standard enterprise deployments.
Pricing Analysis
Warranty and managed service bundling separates premium domestic cloud partnerships from unbundled direct OEM transactions. Three-tier pricing structure across certified sovereign, standard enterprise, and economy edge configurations reflects NCA compliance grade and thermal engineering complexity. Cost compression in economy edge tiers is intensifying because telecommunications operators are consolidating volume purchases through systems integrators. Government ministries exhibit lowest price sensitivity due to mandated domestic residency requirements, while mid-tier Central Region enterprises drive hardest bargain negotiations.
Supply Chain Analysis
Local-content rules under Saudi Arabia's National Data Management Office standards are reshaping sourcing patterns toward regional assembly hubs and domestic certification facilities. Semiconductor supply draws from Taiwan, South Korea, and China, with advanced processors and ECC memory modules constituting critical dependencies. Single-source vulnerability concentrates in leading-edge node fabrication, exposing procurement timelines to geopolitical shipping disruptions. Distribution runs through Jeddah's Red Sea port for import-dependent assembly, with Riyadh-based value-added resellers managing last-mile enterprise deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's data center server market is consolidating around NCA certification capabilities, with extended approval timelines forcing sub-scale vendors toward exit or acquisition.
For Market Incumbents: Acquire liquid-cooled engineering specialists with proven Eastern Province deployment records. Dell Technologies and Hewlett Packard Enterprise should deepen backward integration into immersion cooling component supply to defend against Huawei's cost-optimized rack configurations. Certification investment in 18-month recertification cycles represents essential defensive spend against regulatory timeline compression. For New Entrants and Emerging Players: Begin with Eastern Province industrial edge clusters where predictive maintenance analytics demand outpaces established vendor coverage. Jubail and Ras Al-Khair petrochemical complexes present the most penetrable geography, with micro server deployments for latency-sensitive sensor fusion offering entry wedge. Go-to-market execution should anchor on bundled NCA compliance consulting to displace direct OEM relationships among technical-staff-constrained buyers. For Investors and Strategic Acquirers: Distressed-cycle entries favor liquid-cooled engineering boutiques with active Eastern Province project pipelines and existing CITC facility relationships. Long-term viability hinges on sovereign cloud certification durability across regulatory regime transitions. Watch CITC spectrum licensing expansion pace as inflection indicator for mobile edge computing infrastructure capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Immersion Cooling Partnership | Saudi Aramco's 50MW-plus standardization creates reference architecture for high-temperature operating environments. |
| NCA Certification Fast-Track | Compressed 18-month recertification windows favor vendors with dedicated Kingdom-based compliance engineering. |
| Edge Computing Node Deployment | NEOM's sub-10 millisecond latency specifications mandate distributed compute capacity closer than regional data centers. |
| Systems Integrator Channel Control | Mid-tier BFSI institutions seek turnkey sovereign data residency without internal infrastructure expertise. |
| GPU-Dense Configuration Localization | Arabic-language AI training pipelines from government research institutes demand domestic server residency. |
Research Methodology
Independent corroboration across data center operators, systems integrators, and CITC licensing officials underwrites the qualitative findings. Primary interviews with facility engineering directors, procurement leads at domestic cloud operators, channel sales heads, and NCA cybersecurity certification specialists combined with secondary validation from CITC spectrum disclosures, SEC 10-K filings of listed OEMs, and hyperscaler capex announcements. Bottom-up server shipment aggregation and top-down infrastructure investment triangulation anchored volume estimates.
Rate-of-change decomposition across product type, end user vertical, technology layer, and deployment model dimensions structured the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Thermal engineering adoption curves, sovereign cloud mandate implementation timelines, and edge computing latency specification tightening informed industry-specific forecast inputs.
Underlying measurement precision varies by segment; rack server and colocation deployment estimates carry tighter precision than emerging edge computing configurations. Forecasts reflect documented assumptions regarding CITC licensing expansion pace and NCA certification timeline evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
New Zealand Data Center Networking Market
Data Center and Networking
Wide Area Network Optimization Market