
 Data Deduplication Tools Market | 2026-2036
Data Deduplication Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Data Deduplication Tools Market Outlook
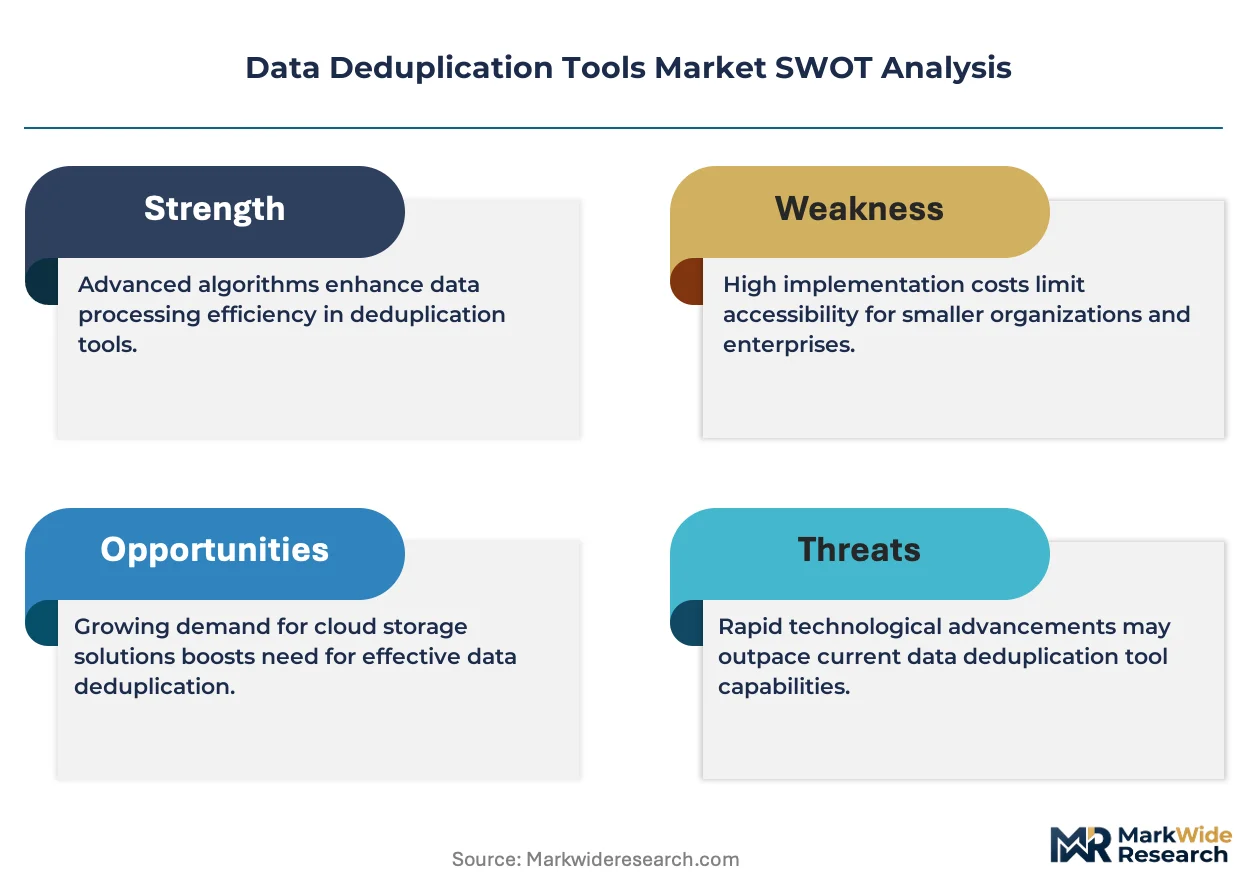
The EU Green Deal is decoupling data center energy intensity from storage growth, pushing enterprises toward compression and deduplication as carbon accounting tools. Rubrik leverages cloud-native architectures to sustain competitive positioning in hybrid environments. Veritas NetBackup anchors on-premises enterprise accounts with deep integration into legacy backup workflows.
Data deduplication tools eliminate redundant copies of information by storing unique data segments once and referencing them via pointers, typically achieving reduction ratios from 10:1 to 50:1 depending on data entropy and block size configuration. Their primary purpose is to shrink storage footprints, accelerate backup windows, and reduce network bandwidth for replication. Cloud-based deployments are capturing the fastest expansion as organizations exit owned infrastructure, while appliance-based solutions still dominate margin pools in regulated verticals requiring air-gapped retention. Large enterprises represent the deepest demand reservoir, though government agencies are tightening procurement specifications around sovereign data handling.
The EU AI Act, GDPR, and ISO 27001 standards collectively mandate audit trails, data minimization, and residency controls that directly expand deduplication budgets across European enterprises. In the United States, HIPAA and SEC recordkeeping rules impose retention densities that compression technologies must address to remain cost-compliant. Stakeholders should monitor how quantum-resistant encryption standards reshape inline deduplication throughput requirements before committing to next-generation hardware refresh cycles.
Market Dynamics
Storage infrastructure economics are fundamentally rewiring around energy accountability, with the EU Green Deal forcing carbon intensity metrics directly into procurement specifications for enterprise data systems. This regulatory compression is accelerating replacement cycles for legacy deduplication hardware.
Growth Catalysts
- GDPR audit mandates:European healthcare networks must maintain immutable data lineage for patient records, expanding deduplication budgets to ensure single-source-of-truth architectures.
- Automotive data lakes:German machinery and vehicle manufacturers generate petabyte-scale sensor telemetry that demands inline deduplication to control cloud egress costs.
- Hybrid cloud repatriation:Enterprises are retrieving cold archives from hyperscalers to on-premises object storage, requiring modern deduplication to compress rehydration bandwidth.
Market Restraints
- Inline processing latency:Real-time deduplication throughput caps constrain adoption in high-frequency trading environments where microsecond delays accumulate losses.
- Encryption key fragmentation:Post-quantum cryptography standards from NIST are forcing hardware refresh cycles before depreciation schedules complete.
- Specialized engineering scarcity:The talent pool for distributed systems optimization remains concentrated in Silicon Valley and Tel Aviv, inflating implementation costs elsewhere.
Strategic Opportunities
- India's data localization mandates:RBI and CERT-In directives are compelling multinational banks to build sovereign deduplication infrastructure within national boundaries.
- AI training pipeline optimization:Machine learning workloads are converging with deduplication to eliminate redundant training set copies across distributed GPU clusters.
- Japan's METI carbon accounting rules:Industrial conglomerates must report Scope 3 emissions from data center operations, creating preference for storage reduction technologies.
Industry Challenges
- ISO 27001 certification timelines:The gap between implementation and audit approval stretches 14-18 months, delaying revenue recognition for solution providers.
- Mainframe integration complexity:Financial institutions running IBM z/OS environments face pointer translation errors when bridging modern object stores with decades-old tape catalogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Deduplication Tools Market |
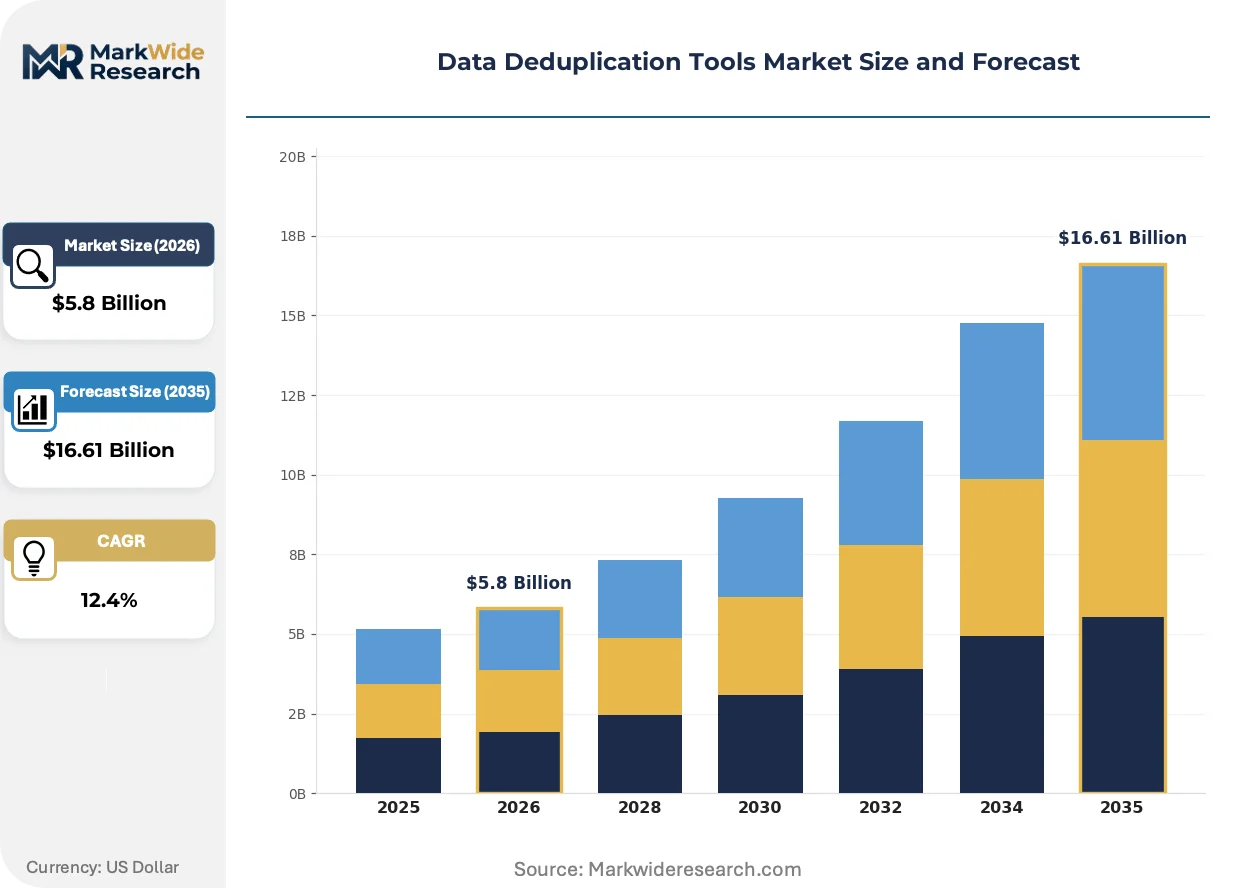
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $16.61 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Appliance, Cloud-based, Hybrid Deployment Model: On-premises, Public Cloud, Private Cloud, Managed Services End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Functionality: Real-time Deduplication, Scheduled Deduplication, Storage Optimization, Data Archiving |
| Companies Covered | Rubrik, Restic, Veeam Backup & Replication, Kopia, Duplicacy, Veritas NetBackup, BorgBackup, Duplicati, Commvault Complete Data Protection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Deduplication Tools Market Strategic Shifts
Computational storage is dissolving the boundary between processing and persistence, with deduplication engines migrating from host software into NVMe controller firmware. This architectural shift promises to halve CPU overhead while tightening latency bounds.
Erasure-coded object storage is converging with variable-block deduplication to enable cross-site resilience without 3x replication overhead. Media and entertainment studios with distributed rendering farms are adopting these fused architectures to shrink synchronization windows between Los Angeles, London, and Wellington facilities. The convergence is compressing total cost of ownership curves for multi-petabyte content repositories.
The EU AI Act's data minimization requirements are forcing training set hygiene protocols that deduplication vendors must certify. Organizations deploying generative models in Frankfurt and Amsterdam now require proof that duplicate synthetic data generations are eliminated before model ingestion. This regulatory pressure is expanding addressable market for governance-integrated deduplication suites.
Consumption-based licensing is displacing perpetual capacity purchases in enterprise storage procurement. German automotive suppliers now negotiate deduplication as metered utility tied to actual reduction ratios achieved, shifting vendor risk onto performance guarantees. This behavioral pivot is most pronounced in Bavaria's industrial corridor where CFOs demand operational expenditure treatment for infrastructure.
Data Deduplication Tools Market Segmentation
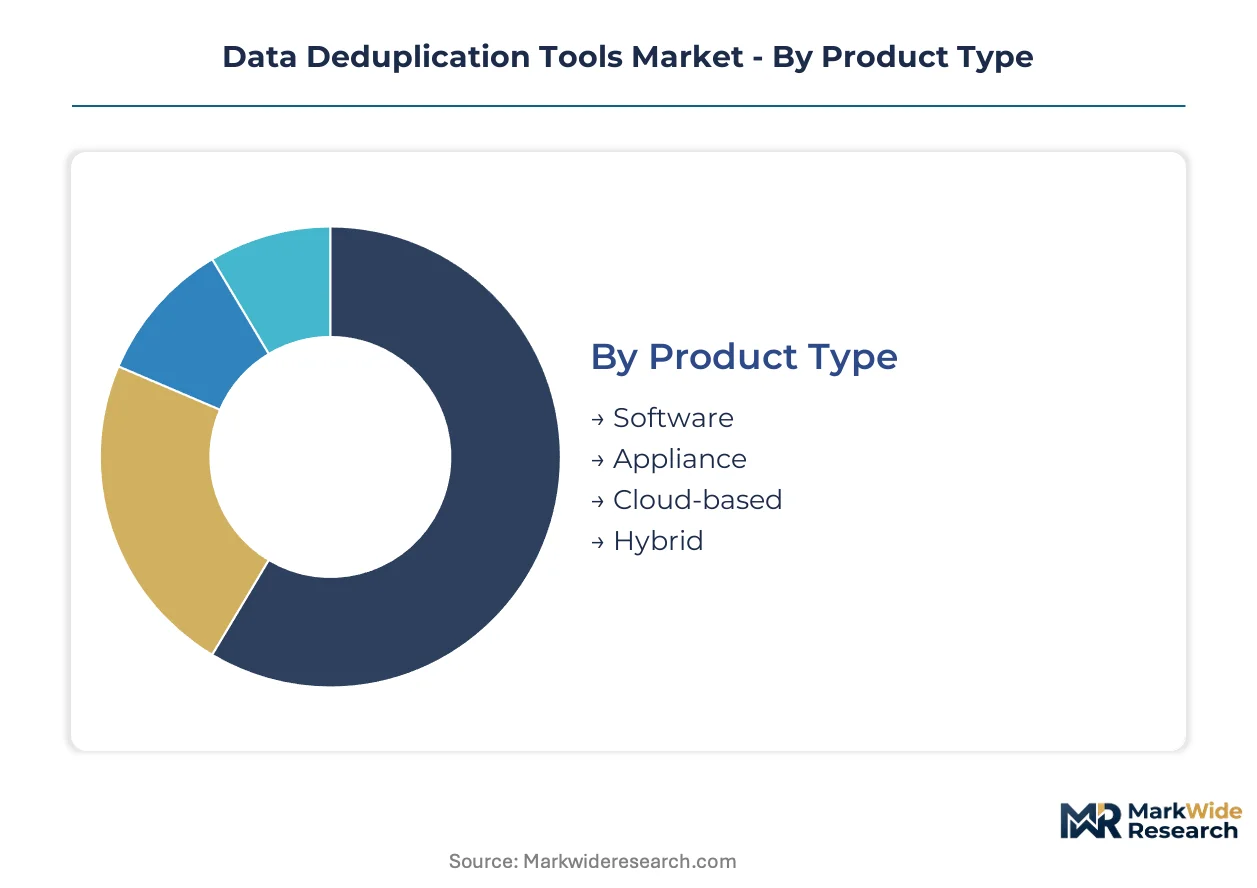
Deduplication architectures vary dramatically in capital requirements, from lightweight software agents to rack-scale appliances. Procurement decisions hinge on data gravity, compliance posture, and existing infrastructure commitments rather than reduction ratios alone.
Product Type:
Appliance deployments demand the heaviest upfront capital outlays, while cloud-native alternatives shift expenditure toward operational metering.
- Appliance:Purpose-built hardware integrating deduplication engines with high-density disk enclosures. German automotive suppliers in Bavaria favor these for air-gapped retention of sensor telemetry under GDPR audit mandates.
- Cloud-based:Fully managed services consuming deduplication as metered utility. Demand concentrates among US healthcare networks exiting owned data centers under HIPAA cost pressures.
- Software:Host-based agents deploying across commodity servers. European research institutions leverage these for flexible scaling across distributed GPU clusters.
- Hybrid:Unified control planes spanning on-premises and cloud repositories. Japanese industrial conglomerates adopt these to satisfy METI carbon accounting rules while maintaining local data sovereignty.
Appliance configurations absorb the bulk of installed capacity; cloud-based alternatives are expanding most quickly.
Deployment Model:
Control over encryption key custody and data residency drives deployment selection, with regulatory geography overriding cost optimization.
- On-premises:Infrastructure retained within enterprise facilities. US financial institutions running IBM z/OS environments require these for SEC recordkeeping compliance and mainframe integration.
- Managed Services:Third-party operated deduplication with SLA-guaranteed reduction ratios. Indian multinational banks deploy these to meet RBI data localization mandates without building captive expertise.
- Public Cloud:Native deduplication within hyperscaler object storage. Media studios in Los Angeles and London use these for distributed rendering farm synchronization.
- Private Cloud:Single-tenant infrastructure with dedicated deduplication controllers. EU healthcare networks select these for GDPR-compliant patient record consolidation.
On-premises retains the deepest installed base; managed services are climbing the fastest as sovereign data requirements proliferate.
End User:
Budget scale and compliance exposure create sharp segmentation in feature requirements and procurement processes.
- Large Enterprises:Multi-petabyte environments with dedicated storage engineering teams. German machinery manufacturers in Stuttgart drive demand for inline processing of industrial IoT streams.
- Government Agencies:Sovereign data handling with classified or citizen-record workloads. US federal and state entities specify FIPS 140-2 encryption and immutable audit trails.
- SMEs:Mid-scale data volumes without dedicated infrastructure staff. These organizations favor consumption-based licensing to convert capital expenditure to operational treatment.
- Educational Institutions:Research data repositories with episodic burst patterns. Universities across France and Switzerland leverage these for grant-funded genomics and climate modeling archives.
Large enterprises command the greatest revenue concentration; government agencies are gaining share fastest amid tightening procurement specifications.
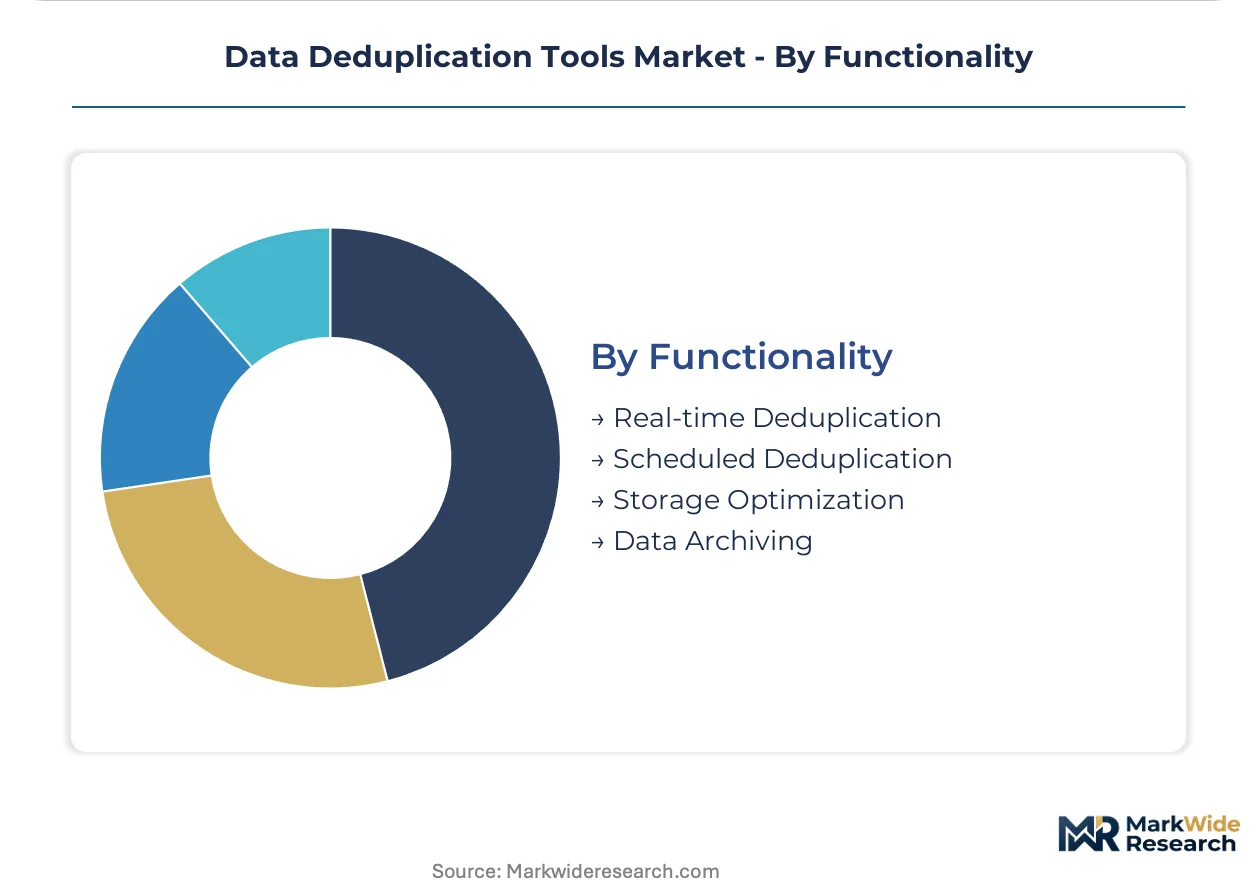
Functionality:
Processing latency tolerance and data access patterns determine which functional modes deploy across different workload types.
- Real-time Deduplication:Inline processing at data ingestion with microsecond latency bounds. High-frequency trading environments in Frankfurt and Chicago constrain adoption due to throughput caps.
- Storage Optimization:Capacity-focused reduction with post-process deduplication. Cloud service providers embed these into standard object storage tiers to minimize replication overhead.
- Scheduled Deduplication:Batch-mode processing during maintenance windows. Backup administrators in legacy enterprise environments prefer these for predictable resource consumption.
- Data Archiving:Long-term retention with compliance-indexed retrieval. Healthcare networks in Amsterdam and Frankfurt require these for EU AI Act training set hygiene certification.
Storage optimization carries the broadest deployment footprint; real-time deduplication is expanding most quickly at the latency-tolerant edge of AI training pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data deduplication tool production concentrates in US software corridors, while consumption spreads across German automotive clusters, Indian banking hubs, and Japanese industrial zones where data sovereignty regulations reshape procurement patterns.
United States
HIPAA compliance costs and SEC recordkeeping density drive healthcare and financial sector adoption. The FDA's digital health data guidelines expand audit trail requirements for patient record systems. Boston's medical research institutions deploy petabyte-scale deduplication for genomic archive consolidation.
Germany
Automotive sensor telemetry and machinery IoT streams generate compression-critical data volumes across Bavaria and Baden-Württemberg. The EU AI Act's training set hygiene mandates force proof of duplicate elimination before model ingestion. Stuttgart's vehicle manufacturers negotiate metered utility contracts tied to actual reduction ratios achieved.
India
RBI data localization directives and CERT-In sovereignty requirements compel multinational banks to build captive deduplication infrastructure. The central bank's cross-border data flow restrictions eliminate hyperscaler dependency for core banking archives. Mumbai's financial district hosts sovereign storage deployments by foreign institutions.
Japan
METI carbon accounting rules impose Scope 3 emissions reporting on data center operations, favoring storage reduction technologies. Industrial conglomerates face mandatory disclosure of energy intensity per petabyte stored. Tokyo's cloud service providers integrate deduplication into standard object storage tiers to minimize replication overhead.
United Kingdom
GDPR audit mandates and NHS patient record consolidation expand deduplication budgets for immutable data lineage. The Information Commissioner's Office tightens breach notification timelines, accelerating single-source-of-truth architectures. London's media studios adopt erasure-coded object storage with variable-block deduplication for distributed rendering synchronization.
Data Deduplication Tools Market Competitive Environment
The competitive structure tilts toward cloud-native specialists with hybrid control plane capabilities. Incumbent backup vendors retain deep enterprise accounts through legacy workflow integration, while open-source engines capture research and SME segments. Three archetypes dominate: appliance-anchored incumbents, cloud-native disrupters, and community-driven open-source projects. Consolidation pressure manifests through strategic partnerships bridging on-premises and hyperscaler environments, plus portfolio diversification into adjacent data governance suites.
Within the cloud-native tier, Rubrik exemplifies hybrid-architecture positioning, while Veritas NetBackup occupies the incumbent-anchored segment serving regulated verticals with air-gapped retention requirements. Among open-source alternatives, Restic and Kopia represent the community-driven archetype capturing academic and mid-market deployments without dedicated infrastructure staff.
| Leading Market Players |
|---|
| Rubrik |
| Restic |
| Veeam Backup & Replication |
| Kopia |
| Duplicacy |
| Veritas NetBackup |
| BorgBackup |
| Duplicati |
| Commvault Complete Data Protection |
| Others |
Value Chain & Pricing Dynamics
Appliance-versus-software tier divergence splits vendor economics between capital-heavy hardware margins and consumption-based SaaS recurring streams, with German automotive buyers in Bavaria negotiating metered utility contracts tied to actual reduction ratios while US healthcare networks under HIPAA cost pressures migrate toward operational expenditure treatment for cloud-native alternatives.
Pricing Analysis
Price erosion across appliance configurations traces to hyperscaler storage commoditization and the EU Green Deal's carbon intensity procurement mandates accelerating hardware replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates air-gapped retention systems with FIPS 140-2 certification from consumption-metered SaaS tiers and open-source community editions. Cost-down pressure on cloud-native alternatives accelerates because hyperscalers embed deduplication into standard object storage tiers at marginal cost. SMEs exhibit highest price sensitivity, seeking operational expenditure treatment, while government agencies demonstrate lowest sensitivity due to sovereign data handling mandates.
Supply Chain Analysis
Regional distribution centers in Silicon Valley, Tel Aviv, and Bangalore anchor specialist engineering talent pools for distributed systems optimization. Component manufacturing concentrates in Taiwan for NVMe controller firmware, South Korea for high-density disk enclosures, and Ireland for EU data residency compliance. Raw material dependencies include rare earth elements for magnetic storage media, advanced lithography equipment for controller fabrication, and specialized cooling systems for high-density appliances. Single-source vulnerability around post-quantum cryptography hardware accelerators from NIST-certified vendors creates procurement bottlenecks. Distribution runs through direct enterprise sales forces for appliance deployments and hyperscaler marketplaces for cloud-native consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's data minimization certification requirements erect a compliance moat that favors incumbent vendors with established audit trail architectures and ISO 27001 accreditation pathways.
For Market Incumbents: Deepen integration with legacy backup workflows to defend against cloud-native disrupters extracting enterprise accounts through hybrid control plane capabilities. Invest in quantum-resistant encryption hardware acceleration before NIST standardization completes depreciation cycles. Prioritize certification investment for EU AI Act training set hygiene protocols to capture governance-integrated deduplication demand in Frankfurt and Amsterdam. For New Entrants and Emerging Players: The premium-to-economy price-point gap in sovereign data handling creates entry opportunity for managed services targeting Indian multinational banks under RBI localization mandates. Target US healthcare networks exiting owned data centers as the most penetrable segment, offering consumption-based licensing with HIPAA-compliant audit trails. Pursue channel partnerships with hyperscaler marketplaces to bypass direct enterprise sales force buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by incumbent backup vendors seeking hybrid cloud capabilities and private equity roll-ups of regional managed services providers. Long-term viability hinges on quantum-resistant encryption throughput and AI training pipeline optimization integration. Watch NIST post-quantum cryptography standardization timelines as the critical inflection signal for hardware refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Encryption Integration | NIST standardization mandates hardware refresh cycles before depreciation schedules complete. |
| Sovereign Cloud Partnership | RBI and CERT-In directives compel captive infrastructure builds within Indian national boundaries. |
| AI Training Pipeline Optimization | Elimination of redundant training set copies across distributed GPU clusters expands addressable market. |
| Carbon Accounting Certification | METI Scope 3 emissions reporting creates preference for storage reduction technologies in Japan. |
| Mainframe Integration Modernization | IBM z/OS environments require pointer translation bridges to modern object stores for SEC compliance. |
Study Parameters
Independent corroboration across CTO interviews, IT procurement officer surveys, and platform engineer discussions underwrites the qualitative findings in this analysis. Primary fieldwork engaged storage engineering directors at German automotive suppliers, compliance officers at US healthcare networks, and sovereign infrastructure architects at Indian multinational banks. Secondary validation drew from hyperscaler capex disclosures, SEC filings of publicly traded backup vendors, EU regulatory impact assessments for the AI Act, and hospital procurement database extracts. Bottom-up sizing of deployment models and top-down reconciliation against aggregate storage capacity forecasts ensured methodological rigor.
Comparable-period anchoring to historical appliance shipment volumes and cloud-native subscription bookings established the forecast baseline across the projection horizon. Segmentation dimensions modeled include product architecture, deployment model, organization size tier, vertical industry, and regional regulatory cluster. CAGRs were derived from growth rate convergence analysis against storage capacity expansion curves and compliance spending elasticity estimates. Industry-specific inputs encompassed EU Green Deal carbon intensity metrics, GDPR audit mandate implementation timelines, and post-quantum cryptography hardware availability schedules.
Inputs from hyperscaler disclosure filings and regulatory comment periods were available through the study window; gaps in proprietary vendor pricing data introduce uncertainty bands around segment-level revenue allocations. Forecasts reflect documented assumptions regarding compliance timeline adherence and technology substitution elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Deduplication Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Europe Subscriber Data Management Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Enterprise Server Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Global Enterprise Networking Market