
 Japan Data Center Server Market | 2026-2036
Japan Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Server Market Insights
Japanese domestic server production is rebalancing toward liquid-cooled and high-density architectures as power constraints tighten in the Kanto region. NEC Corporation leverages its sovereign technology base to anchor government and critical infrastructure contracts. Fujitsu competes through its proprietary Arm-based processor roadmap, while Dell Technologies sustains broad enterprise penetration through channel depth and x86 ecosystem completeness.
Data center servers are enterprise-grade computing systems engineered for 24/7 operation in controlled environments, typically supporting processor TDP ratings exceeding 200W and redundant power configurations for mission-critical uptime. Rack servers occupy the dominant volume position across Japanese enterprise deployments due to standardization and space efficiency, while blade servers command premium positioning in hyperscale facilities where density and shared infrastructure reduce per-unit power overhead. ARM technology is gaining structural traction as domestic chip designers and cloud operators seek alternatives to x86 dependency for specific AI inference and storage workloads.
METI enforces stringent energy efficiency standards under its Top Runner program, directly influencing server procurement criteria for large-scale facilities. JIS standards and PMDA guidelines intersect with healthcare end-user requirements, creating compliance layers that favor established vendors with domestic certification capabilities. Stakeholders must monitor evolving carbon accounting rules and grid interconnection limits as these constraints increasingly determine where new compute capacity can physically locate.
Market Dynamics
METI's carbon neutrality mandates and Kanto region power grid constraints are forcing hyperscale operators toward liquid-cooled, high-density server architectures that maximize compute per square meter and per megawatt.
Growth Catalysts
- AI Inference Workload Expansion:Domestic cloud operators and financial services firms are deploying GPU-accelerated servers for real-time risk modeling and generative AI applications, driving procurement of H100 and successor architectures.
- METI Top Runner Standards:Mandatory energy efficiency benchmarks for data center equipment are accelerating replacement cycles of legacy air-cooled infrastructure in facilities exceeding 1,500 square meters.
- Osaka Metropolitan Cluster:Hyperscale developers are redirecting capacity expansion to Kansai region sites with superior grid interconnection and lower land costs compared to saturated Tokyo corridors.
Market Restraints
- Copper and Rare Earth Input Volatility:Server power distribution components and permanent magnet materials face price instability from concentrated Chinese refining capacity, compressing hardware margins.
- Kanto Power Interconnection Limits:TEPCO grid constraints cap new data center power allocations at 50 megawatts per site in Greater Tokyo, forcing developers toward multi-site fragmentation or geographic displacement.
- x86 Architecture Lock-in:Enterprise software licensing and operational tooling dependencies slow migration to Arm-based alternatives despite superior performance-per-watt profiles.
Strategic Opportunities
- Submarine Cable Landing Zones:New fiber optic infrastructure at Shima and Tanegashima creates edge compute positioning for transpacific latency-sensitive applications serving North American markets.
- Carbon Accounting Integration:METI's forthcoming Scope 3 disclosure requirements will advantage server vendors with verified supply chain emissions data and modular refurbishment programs.
- Quantum-Classical Hybrid Architectures:RIKEN and domestic semiconductor consortia are piloting cryogenic control electronics that position Japan for quantum computing co-location services.
Industry Challenges
- Liquid Cooling Technician Scarcity:Facility engineering talent with direct-to-chip and immersion cooling expertise remains concentrated among hyperscale operators, constraining enterprise adoption.
- JIS Certification Timelines:Electromagnetic compatibility and electrical safety testing for novel server form factors extends product launch windows by 4-6 months versus comparable EU or US approvals.
- Intergenerational Hardware Compatibility:Rack power density jumps from 10kW to 40kW per cabinet require wholesale electrical infrastructure replacement rather than incremental upgrades.
Report Scope
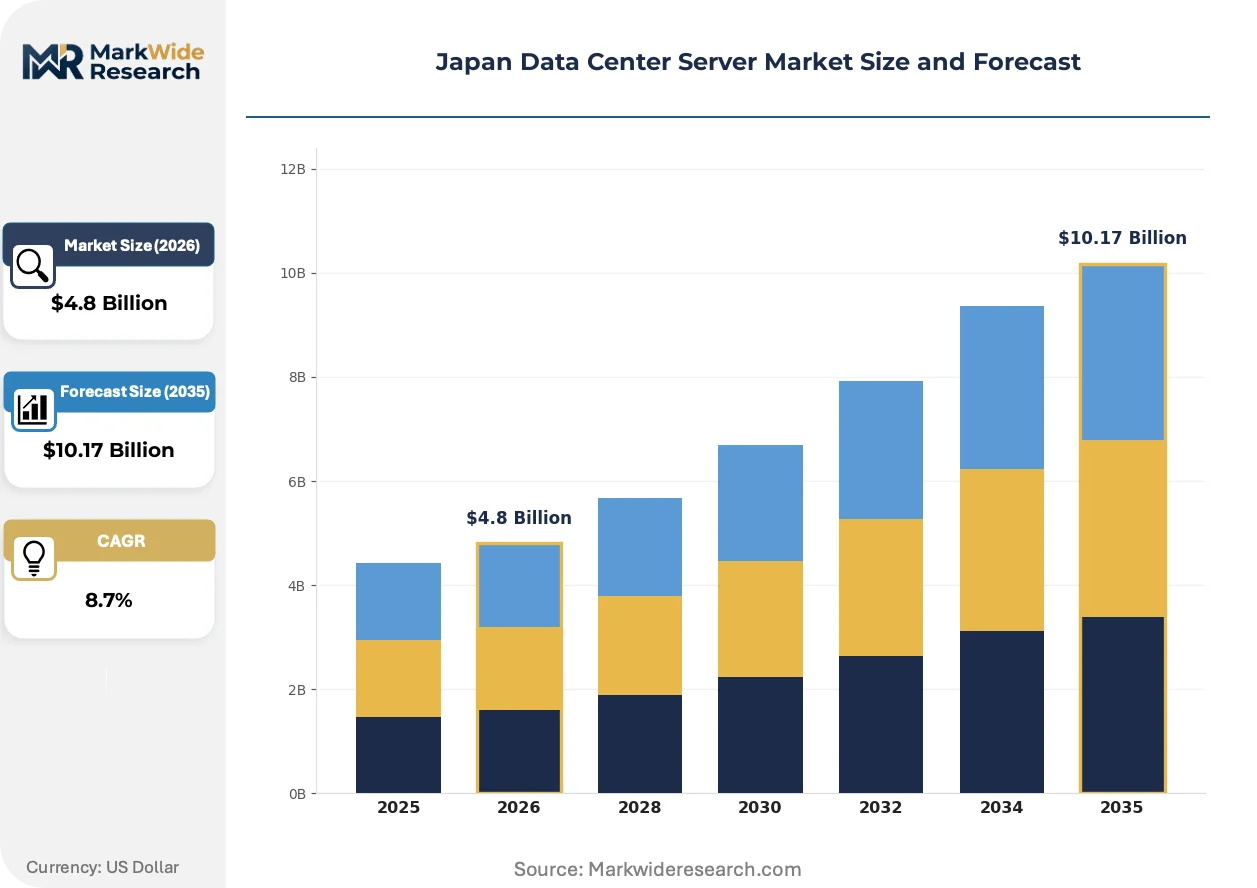
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Server Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Modular Servers End User: Telecom, BFSI, Healthcare, Government Technology: X86, ARM, RISC, SPARC Deployment: On-Premises, Colocation, Hybrid, Cloud |
| Companies Covered | NEC Corporation, Quanta Computer, Dell Technologies, NTT Global Data Centers, Cisco Systems, Hewlett Packard Enterprise, Lenovo Group Limited, Hitachi, Fujitsu, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Server Market Trends and Innovations
Liquid cooling infrastructure is transitioning from niche hyperscale deployment to standard enterprise specification as power densities exceed air-cooling thermal limits. Regulatory pressure and operational cost reduction are converging to accelerate architectural transformation.
Direct-to-chip liquid cooling is integrating high-performance computing infrastructure with facility water systems. Domestic semiconductor manufacturers and cloud operators are deploying cold plate architectures in new Osaka and Fukuoka facilities. This technology is integrating compute density gains with heat reuse applications for district heating networks.
METI's revised Data Center Energy Efficiency Guidelines impose granular power usage effectiveness reporting and renewable energy procurement targets on facilities above 3,000 square meters. Operators must now submit annual carbon reduction roadmaps to maintain operating licenses. Hyperscale campuses in Saitama and Chiba prefectures are responding with on-site solar generation and battery storage co-location.
Enterprise buyers are consolidating server procurement under managed infrastructure contracts that bundle hardware, maintenance, and energy optimization. Systems integrators with domestic service footprints are displacing direct OEM relationships in mid-market manufacturing and healthcare verticals. This pattern concentrates most visibly in pharmaceutical and medical device sectors where PMDA validation requirements favor established service providers with quality management certifications.
Japan Data Center Server Market Segmentation
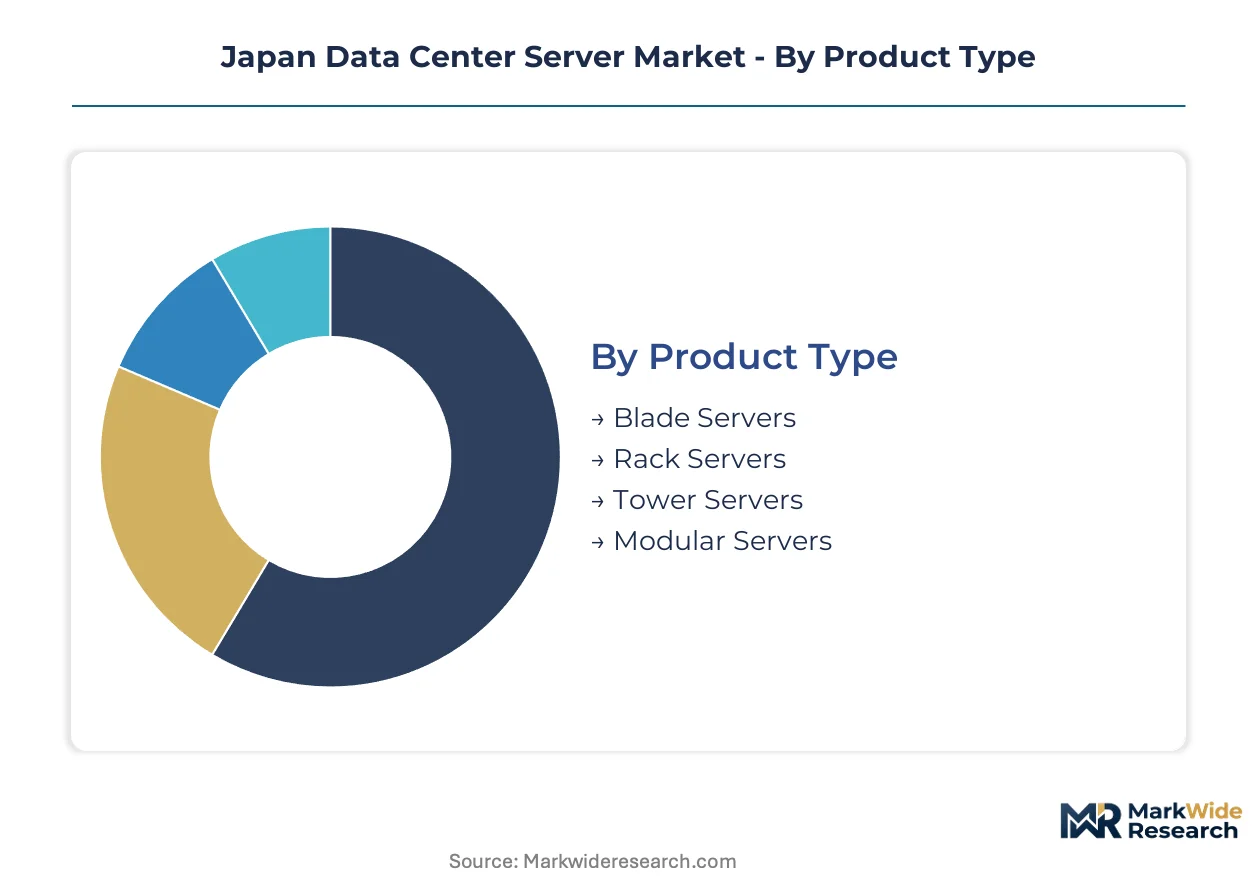
Server procurement patterns in Japan diverge sharply across infrastructure archetypes, with METI efficiency mandates and Kanto power constraints driving heterogeneous deployment strategies. Understanding segment-level technology requirements reveals where liquid cooling investments concentrate and which processor architectures align with sovereign compute priorities.
Product Type:
Physical form factor determines thermal management architecture and facility power density limits in Japanese data center construction.
- Rack Servers:Standardized 19-inch enclosures accommodate processor TDP ratings exceeding 200W with front-to-rear airflow patterns. Enterprise deployments across Osaka and Fukuoka prefectures favor this format for its interoperability with existing raised-floor facilities and straightforward maintenance access.
- Blade Servers:Shared infrastructure chassis reduce per-unit power overhead through consolidated cooling and power distribution. Hyperscale operators in Saitama and Chiba prefectures deploy blade architectures to maximize compute per square meter under TEPCO interconnection caps.
- Tower Servers:Vertical standalone units serve edge computing sites and small enterprise server rooms without raised-floor requirements. Regional manufacturing facilities in Aichi and Hiroshima prefectures utilize tower formats for localized ERP and quality control systems.
- Modular Servers:Containerized or skid-mounted configurations enable rapid deployment in secondary markets with limited construction timelines. Disaster recovery sites in Hokkaido and Kyushu leverage modular approaches for seismic resilience and geographic redundancy.
Mature deployment sits with rack servers. Newer deployment is concentrated in blade servers.
End User:
Regulatory compliance layers and workload characteristics shape procurement specifications across vertical markets.
- BFSI:Real-time risk modeling and algorithmic trading drive GPU-accelerated server procurement with sub-millisecond latency requirements. Tokyo-based financial institutions prioritize liquid-cooled H100-class infrastructure for generative AI applications.
- Telecom:5G core network functions and edge computing nodes require ARM-based servers for power efficiency at distributed radio access network sites. NTT and KDDI procurement patterns favor high-density rack configurations with redundant power supplies.
- Government:Sovereign cloud initiatives and critical infrastructure protection mandate domestic supply chain verification and JIS-certified electromagnetic compatibility. Defense and intelligence applications impose air-gapped deployment with specialized physical security.
- Healthcare:PMDA validation requirements for electronic medical record systems and medical imaging archives favor established vendors with quality management certifications. Pharmaceutical manufacturers deploy validated server environments for clinical trial data integrity.
Procurement volume concentrates in BFSI. Regulatory complexity peaks in healthcare.
Technology:
Processor architecture selection reflects performance-per-watt optimization and software ecosystem dependencies.
- X86:Dominant enterprise ecosystem with complete software compatibility and mature virtualization tooling. Legacy application portfolios and Microsoft-dependent workloads perpetuate x86 procurement despite superior ARM efficiency metrics.
- ARM:Fujitsu's proprietary processor roadmap and cloud operator interest in inference-optimized silicon are gaining structural traction. Domestic chip designers collaborate with hyperscale developers on custom ARM implementations for storage and AI inference.
- RISC:Reduced instruction set architectures serve specialized high-performance computing environments with predictable workload patterns. Academic and research institutions maintain RISC deployments for legacy scientific computing codes.
- SPARC:Oracle-dependent enterprise applications and legacy Solaris environments sustain limited procurement in financial services. Migration pressures accelerate as vendor support windows contract.
Volume leadership remains with x86. Architecture transition momentum favors ARM.
Deployment:
Infrastructure location strategy responds to grid interconnection limits, latency requirements, and capital structure preferences.
- Colocation:Third-party facility operators provide power, cooling, and physical security for enterprise-owned server deployments. Osaka metropolitan cluster expansion attracts colocation demand with superior TEPCO West interconnection capacity.
- Cloud:Hyperscale operator-managed infrastructure eliminates capital expenditure and operational complexity for variable workloads. Domestic cloud providers expand GPU-accelerated instance offerings for generative AI development.
- On-Premises:Enterprise-controlled facilities persist where data sovereignty, ultra-low latency, or specialized hardware requirements preclude outsourcing. Manufacturing execution systems and industrial control platforms retain on-premises deployment.
- Hybrid:Orchestrated workload placement across on-premises and cloud infrastructure balances cost, compliance, and performance objectives. Financial services firms deploy hybrid architectures for customer-facing applications with burst capacity to cloud.
Facility investment flows toward colocation. Workload portability drives hybrid architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication in Kyushu and Hokkaido underpins Japan's data center server supply chain, with advanced packaging capacity concentrating near raw material sources before distribution to metropolitan compute clusters.
Kanto/Tokyo
Hyperscale operators face TEPCO grid interconnection caps at 50 megawatts per site, forcing multi-site fragmentation across Saitama and Chiba prefectures. METI's Top Runner standards mandate granular PUE reporting for facilities exceeding 3,000 square meters. The Greater Tokyo corridor remains saturated despite liquid-cooled high-density deployments maximizing compute per square meter.
Kansai/Osaka
Superior grid capacity and lower land costs attract hyperscale expansion away from Tokyo constraints. Cloud operators deploy GPU-accelerated infrastructure for generative AI development with fewer power allocation restrictions. The Osaka metropolitan corridor hosts new direct-to-chip liquid cooling installations serving financial services and pharmaceutical workloads.
Chubu/Nagoya
Manufacturing execution systems and industrial control platforms sustain on-premises server demand across automotive and precision machinery sectors. Regional facilities prioritize x86 compatibility for legacy ERP integration over ARM efficiency gains. Toyota-supplier networks maintain localized compute for quality control and supply chain optimization.
Kyushu
Submarine cable landing zones at Tanegashima position the region for transpacific edge compute serving North American latency-sensitive applications. Fukuoka facilities leverage cooler ambient temperatures for reduced cooling overhead. Domestic semiconductor packaging capacity supports sovereign chip supply chain verification requirements.
Hokkaido
Disaster recovery sites exploit geographic redundancy and seismic resilience for critical infrastructure protection. Modular containerized deployments enable rapid capacity scaling without conventional construction timelines. Cold climate advantages reduce mechanical cooling energy consumption for secondary compute workloads.
Japan Data Center Server Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sovereign technology differentiation and liquid-cooled specialization. The vendor base stratifies across three maturity tiers: domestic incumbents with JIS certification capabilities, multinational OEMs with channel depth, and contract manufacturers serving hyperscale direct procurement. Competitive positioning depends on METI compliance integration, Arm-based processor roadmaps, and high-density thermal management expertise. Dominant moves include strategic partnerships with domestic cloud operators and geographic expansion toward Osaka metropolitan capacity.
Within the domestic incumbent tier, NEC Corporation and Fujitsu occupy positions anchored by sovereign technology bases and government contract access. NEC leverages its Tokyo-headquartered structure for critical infrastructure and defense applications requiring air-gapped deployment. Fujitsu represents the Arm-based alternative pathway through its proprietary processor development. Dell Technologies exemplifies multinational OEM penetration through x86 ecosystem completeness and enterprise channel density. Quanta Computer sits within the contract manufacturing archetype serving hyperscale direct procurement with high-volume rack and blade configurations.
| Leading Market Players |
|---|
| NEC Corporation |
| Quanta Computer |
| Dell Technologies |
| NTT Global Data Centers |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Lenovo Group Limited |
| Hitachi |
| Fujitsu |
| Others |
Pricing and Supply Chain Analysis
Liquid cooling infrastructure deployment is compressing server hardware margins while concentrating procurement leverage among hyperscale operators with direct-to-manufacturer volume commitments. This technology transition simultaneously elevates capital requirements for thermal management components and reduces supplier fragmentation as certification complexity favors established vendors.
Pricing Analysis
Warranty bundling and lifecycle service contracts differentiate server procurement tiers across Japanese enterprise buyers. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification grade and domestic assembly location versus import origin. Cost compression in standard-tier rack configurations is intensifying because TEPCO interconnection caps force multi-site deployments that fragment volume discounts. Small and mid-sized manufacturing enterprises exhibit highest price sensitivity, while financial services firms prioritize liquid-cooled premium tiers with comprehensive on-site service coverage.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for GPU-accelerated server chassis, while tier-one distributors serve enterprise mid-market procurement. Taiwan, South Korea, and China concentrate advanced semiconductor packaging and memory component manufacturing. Server power distribution units and cold plate assemblies draw from copper refining capacity concentrated in Chinese smelters. Single-source vulnerability in rare earth magnet supply for high-efficiency power supplies creates exposure to export restriction risks. Distribution runs through domestic systems integrators with JIS certification capabilities for healthcare and government verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's data center server market operates under pronounced supply constraints as TEPCO grid interconnection limits cap new facility power allocations, propping pricing power for certified vendors with guaranteed capacity access.
For Market Incumbents: To counter Arm-based processor encroachment from Fujitsu and domestic cloud operator collaborations, x86-dominant vendors should deepen backward integration into liquid cooling component supply and secure JIS certification pre-approval for next-generation high-density form factors. Channel control through exclusive systems integrator partnerships in Osaka and Fukuoka metropolitan corridors protects enterprise market share against direct hyperscale procurement. For New Entrants and Emerging Players: Cloud marketplace listings and direct digital procurement platforms offer lowest-friction entry paths for modular server and edge computing specialists. White-space concentration sits with validated healthcare server environments under PMDA quality management requirements, where incumbent service relationships create procurement inertia. Disaster recovery sites in Hokkaido and Kyushu present penetrable geography for containerized rapid-deployment configurations with seismic resilience specifications. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational OEMs seeking JIS certification capabilities and domestic government contract access. Long-term viability hinges on positioning for quantum-classical hybrid infrastructure as RIKEN consortia mature cryogenic control electronics. The signal to watch is METI's Scope 3 disclosure implementation timeline, which will strand vendors without verified supply chain emissions data.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Partnership | Direct-to-chip thermal collaborations with Osaka hyperscale operators secure anchor tenant status for new facilities. |
| Arm Processor Roadmap Investment | Domestic silicon design capabilities reduce x86 dependency for AI inference workloads in cloud deployments. |
| JIS Certification Pre-Approval | Accelerated electromagnetic compatibility testing shortens product launch windows versus standard regulatory timelines. |
| Osaka Metropolitan Expansion | Geographic diversification from TEPCO-constrained Tokyo corridors unlocks superior grid interconnection capacity. |
| Carbon Accounting Integration | Verified supply chain emissions data positions vendors for METI's forthcoming Scope 3 disclosure mandates. |
Research Methodology
Document review covered METI regulatory filings, TEPCO grid interconnection disclosure records, and hyperscaler capital expenditure announcements, complemented by interviews with data center facility engineers, server procurement managers at financial institutions, systems integrator technical directors, and semiconductor packaging specialists. Secondary validation drew from JIS standards documentation, PMDA quality management guidelines, and customs trade data for server component imports. Bottom-up facility capacity modeling and top-down enterprise IT spending analysis were triangulated against vendor shipment disclosures.
Unit shipment and revenue estimates across the projection horizon reflect segmentation by form factor, processor architecture, deployment model, and metropolitan corridor concentration. The analytical framework incorporated power density trajectories, liquid cooling adoption curves, and METI efficiency mandate compliance timelines. CAGRs were derived from regression analysis of historical procurement patterns against grid interconnection constraint projections and hyperscale expansion announcements.
The model holds under stable TEPCO interconnection allocation policies and continued METI Top Runner enforcement; deviation in renewable energy procurement cost curves or rare earth export restrictions would shift facility location economics and server technology roadmaps. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Edge Server Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Global Virtual Private Server Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Enterprise Server Market
Data Center and Networking
Data Warehousing Market