
 Freight Forwarding Software Market | 2026-2036
Freight Forwarding Software Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Forwarding Software Market Insights
Direct sales channels serving mid-sized freight forwarders is fragmenting as SaaS vendors bypass traditional reseller networks and sell through digital marketplaces. WiseTech leverages its integrated global trade platform to sustain R&D intensity across customs and compliance modules. Descartes anchors its position through geographic dominance in North American customs brokerage automation. CargoWise competes by extending its single-platform architecture into warehouse and transport management.
Freight forwarding software comprises digital platforms that automate shipment routing, documentation, customs filing, and carrier selection across multimodal supply chains, typically integrating EDI, API, and blockchain protocols for real-time data exchange. Its primary commercial purpose is to replace manual booking and tracking workflows with centralized visibility that reduces detention costs and accelerates customs clearance. Cloud-based deployment leads the product type dimension as forwarders abandon capital-intensive server infrastructure, while SaaS subscriptions capture the fastest expansion by converting perpetual licenses into recurring revenue streams. The end-user base tilts toward third-party logistics operators who aggregate fragmented shipper demand and require multi-tenant architectures to serve disparate client compliance requirements.
Regulatory scrutiny from the EU AI Act and GDPR shapes algorithmic transparency requirements for automated customs classification tools, while the U.S. FDA and FAA maintain jurisdiction over temperature-controlled pharmaceutical and aviation cargo documentation standards. REACH and RoHS compliance modules within European deployments force software vendors to embed chemical substance tracking at the SKU level. Stakeholders must weigh interoperability investments against the risk of proprietary platform lock-in as national customs authorities accelerate API-first modernization programs.
Market Dynamics
Cloud migration mandates under EU data sovereignty rules are forcing freight forwarders to re-architect their technology stacks, replacing on-premise customs engines with API-first platforms that embed real-time compliance validation.
Growth Catalysts
- Third-party logistics consolidation:Mid-sized 3PLs are aggregating fragmented shipper demand through multi-tenant SaaS architectures that automate carrier selection across multimodal corridors.
- EU AI Act transparency requirements:Automated customs classification tools must now embed algorithmic explainability modules, accelerating replacement of legacy rule-based tariff engines.
- Blockchain-EDI protocol convergence:Smart contract integration with existing EDI infrastructure is reducing documentation reconciliation delays at Rotterdam and Hamburg port clusters.
Market Restraints
- API standardization fragmentation:National customs authorities in Germany, Singapore, and the United States operate incompatible data exchange protocols, forcing vendors to maintain redundant integration layers.
- Capital intensity of compliance modules:REACH and RoHS chemical substance tracking at the SKU level requires continuous database subscription costs that squeeze margins for smaller forwarders.
- Talent scarcity in customs engineering:The specialized skill set combining tariff classification expertise with API development commands premium compensation that elevates vendor R&D burn rates.
Strategic Opportunities
- Pharmaceutical cold-chain digitization:FDA temperature-controlled documentation standards for aviation cargo create demand for sensor-integrated booking platforms that automate deviation alerts.
- India's customs modernization:DGFT's API-first national trade portal rollout offers first-mover advantage for vendors configuring multi-lingual compliance engines.
- Warehouse-transport convergence:Single-platform architectures that collapse WMS and TMS functionality into unified visibility dashboards are capturing forwarders seeking to eliminate swivel-chair workflows.
Industry Challenges
- Legacy system integration complexity:Decades-old AS/400-based freight management systems at established forwarders resist API connectivity, prolonging implementation timelines and inflating professional services costs.
- GDPR-EU AI Act dual compliance:Software vendors must simultaneously embed data localization controls and algorithmic transparency features, requiring parallel engineering tracks that strain product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Forwarding Software Market |
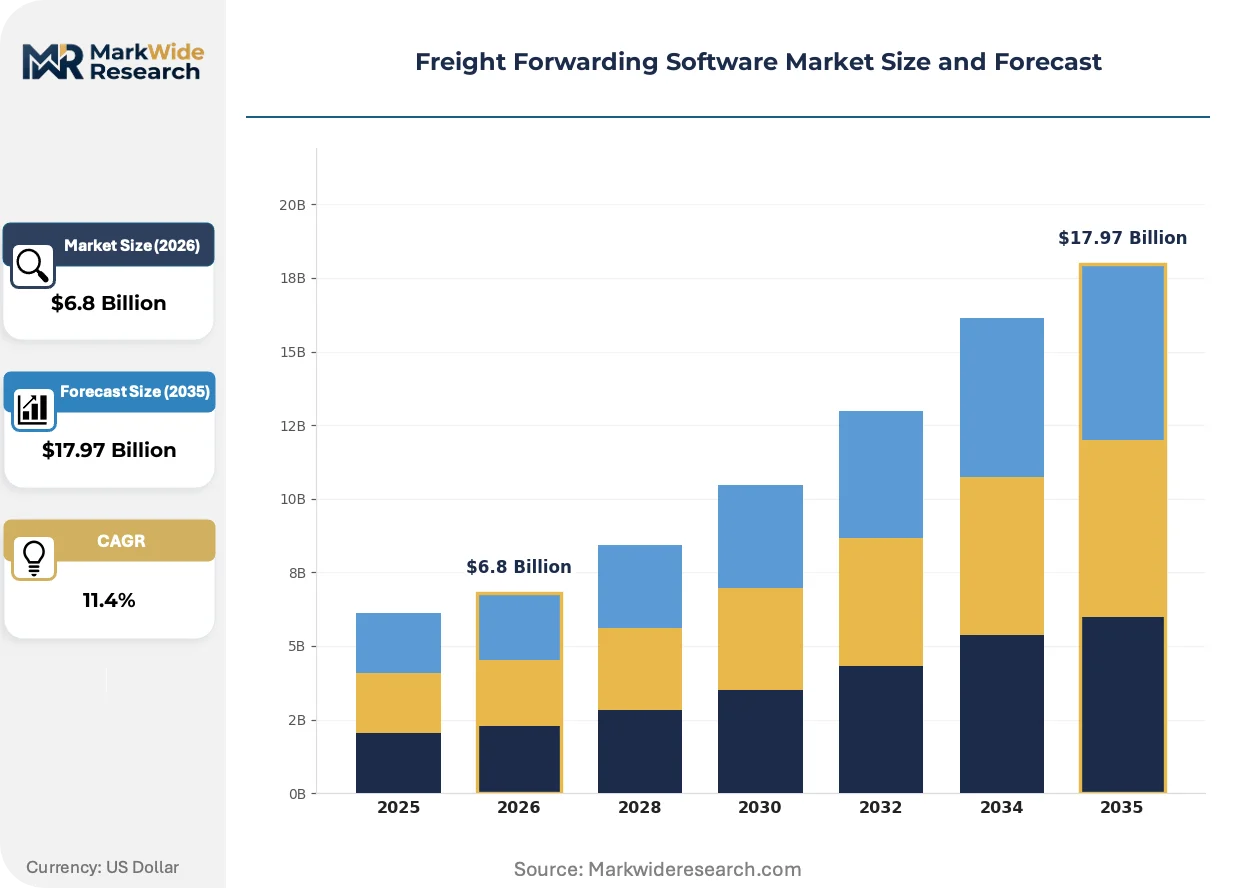
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, SaaS End User: Logistics Providers, Freight Brokers, E-Commerce, Third-Party Logistics Feature: Tracking and Visibility, Automated Billing, Customs Management, Analytics Deployment: Private Cloud, Public Cloud, Dedicated Server, Multi-Tenant |
| Companies Covered | WiseTech, Descartes, CargoWise, Magaya, Riege Software, Softlink, Akanea, Mercurygate, Logistaas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Forwarding Software Market Trends and Innovations
Real-time visibility platforms are compressing the traditional information asymmetry between shippers and carriers, transforming freight forwarding from a brokerage function into a data-integrated orchestration service.
API-first customs engines are collapsing the latency between declaration submission and duty calculation. Large 3PLs in the Benelux corridor are deploying these systems to replace batch-processed clearance workflows. The structural consequence is collapsing detention cost exposure at Antwerp and Rotterdam terminals.
REACH and RoHS compliance modules are forcing SKU-level chemical substance tracking into standard software configurations. European chemical shippers now reject platforms lacking embedded ECHA database connectivity. The segment most affected is specialty chemical forwarders serving German automotive suppliers, who are re-platforming to avoid customs holds.
Subscription pricing is displacing perpetual license structures across mid-market forwarders. Digital marketplaces now host SaaS vendor storefronts that bypass traditional reseller networks. This shift concentrates in the United States, where private-equity-backed 3PLs prioritize opex-light technology procurement to preserve acquisition multiples.
Freight Forwarding Software Market Segmentation
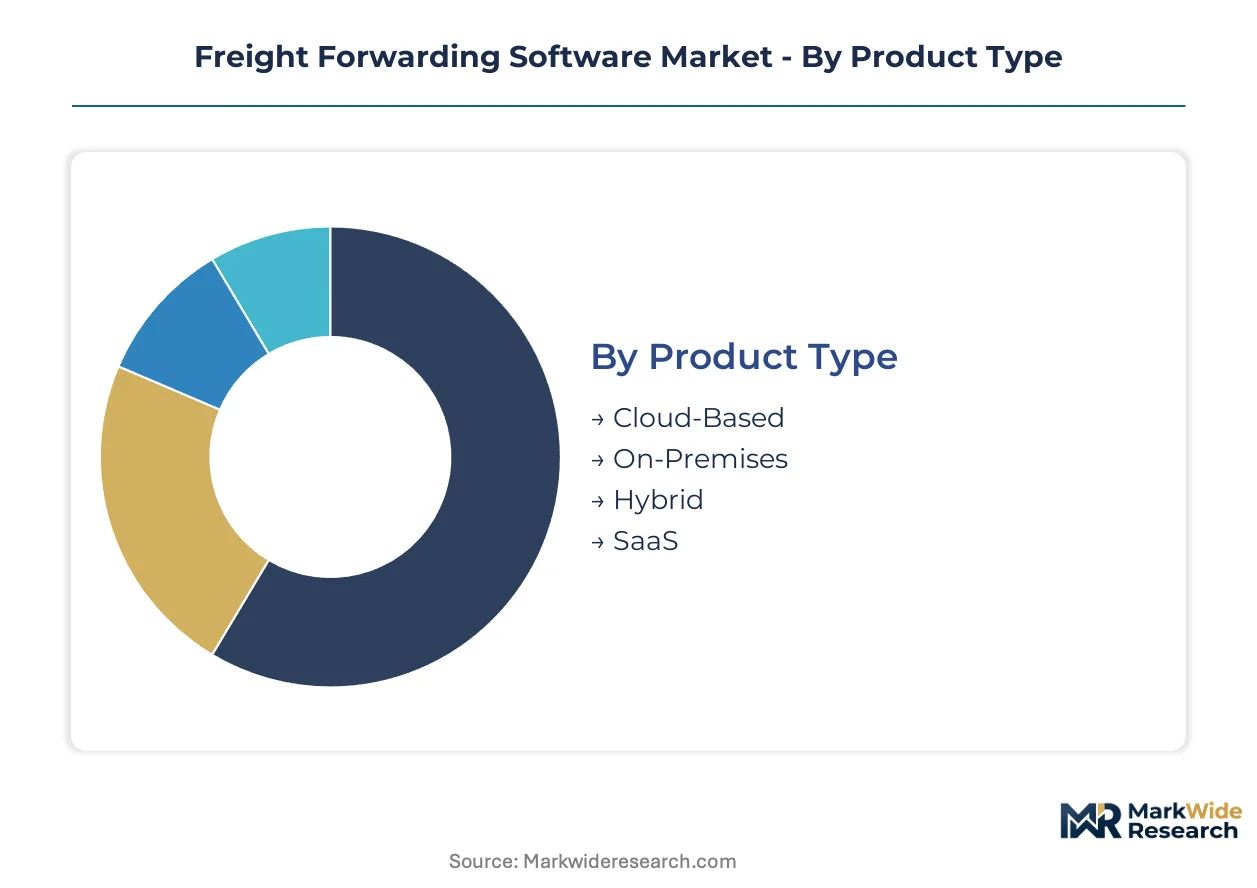
Freight forwarding software segments diverge sharply in procurement velocity. Cloud-native solutions refresh on 12-18 month cycles while on-premise deployments linger across seven-year amortization schedules. This temporal asymmetry shapes vendor R&D allocation and customer lifetime value calculations.
Product Type:
Cloud-based platforms turn over fastest as forwarders abandon capital-intensive infrastructure, while perpetual license models exhibit the longest replacement cycles in the category.
- Cloud-Based:Multi-tenant architectures with API-first customs engines eliminate server maintenance overhead. Third-party logistics operators in Germany and Singapore are consolidating onto these platforms to satisfy EU data sovereignty mandates while maintaining real-time carrier connectivity across Asian trade corridors.
- SaaS:Subscription pricing converts upfront license expenditure into recurring operational spend. Private-equity-backed 3PLs in the United States prioritize opex-light procurement structures that preserve acquisition multiples and accelerate technology refresh timelines.
- On-Premises:Legacy AS/400-dependent forwarders retain these deployments for tariff engine customization.
- Hybrid:Split configurations bridge sensitive customs data localization with cloud-based carrier APIs.
Cloud-based deployments anchor the volume base while SaaS gains share at the steepest rate.
End User:
Customer type determines platform complexity requirements and integration depth with downstream supply chain systems.
- Third-Party Logistics:Multi-tenant architectures serve disparate shipper compliance requirements through unified dashboards. Large 3PLs in the Benelux corridor deploy these systems to collapse detention cost exposure at Antwerp and Rotterdam terminals while managing REACH and RoHS chemical substance tracking for German automotive suppliers.
- Logistics Providers:Specialized forwarders demand SKU-level visibility for temperature-controlled pharmaceutical cargo under FDA aviation documentation standards.
- Freight Brokers:Intermediary-focused tools prioritize carrier rate comparison and automated tendering workflows.
- E-Commerce:Direct-to-consumer fulfillment drives demand for last-mile tracking integration and returns management modules.
Third-party logistics anchors the volume base while e-commerce gains share at the steepest rate.
Feature:
Functional modules compete for implementation priority based on measurable cost reduction versus compliance risk mitigation.
- Customs Management:Automated classification engines embed algorithmic explainability modules to satisfy EU AI Act transparency requirements. These systems replace legacy rule-based tariff engines at forwarders serving Hamburg and Rotterdam port clusters, collapsing declaration-to-duty latency.
- Tracking and Visibility:Real-time sensor integration supports FDA temperature-controlled documentation for pharmaceutical aviation cargo, automating deviation alerts that prevent customs holds.
- Automated Billing:Freight audit and payment modules reconcile carrier invoices against contracted rates.
- Analytics:Predictive demand forecasting tools optimize inventory positioning across multimodal corridors.
Customs management anchors the volume base while tracking and visibility gains share at the steepest rate.
Deployment:
Infrastructure configuration choices reflect data residency requirements against scalability imperatives.
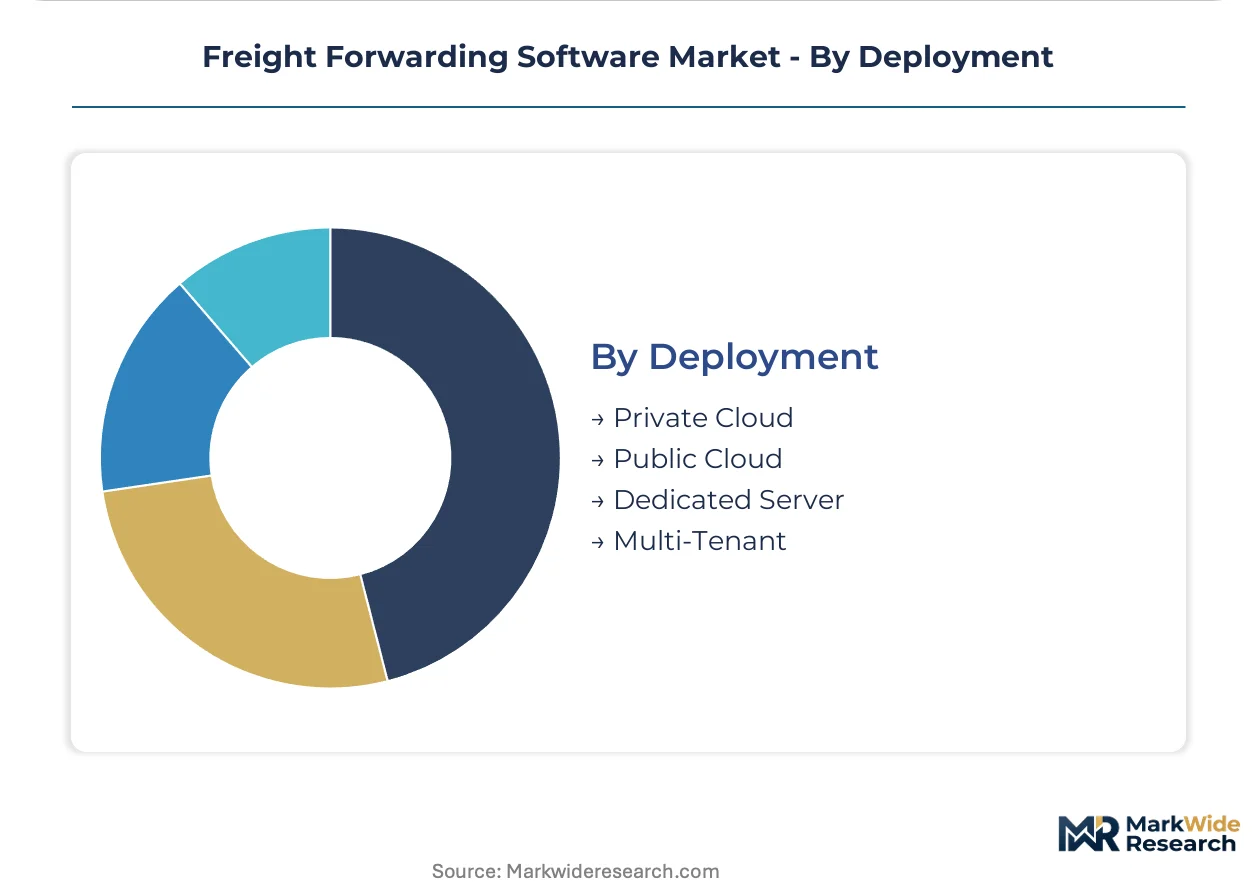
- Public Cloud:Shared infrastructure delivers elastic compute for seasonal volume spikes without capital commitment. Forwarders in the United States leverage these deployments to bypass server procurement cycles during peak retail shipping windows.
- Multi-Tenant:Single codebase instances serve multiple shipper clients from partitioned databases. European chemical forwarders require these architectures to isolate client data while sharing ECHA database subscription costs for REACH compliance.
- Private Cloud:Dedicated virtualized environments satisfy stringent data localization requirements.
- Dedicated Server:Physical hardware isolation supports maximum customization for legacy system integration.
Public cloud anchors the volume base while multi-tenant gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA documentation standards for temperature-controlled aviation cargo and EU AI Act algorithmic transparency rules anchor demand concentration in the United States and Germany, with Singapore serving as the critical node for Asian trade corridor digitization.
United States
Private-equity-backed third-party logistics operators prioritize opex-light SaaS procurement to preserve acquisition multiples. FDA temperature-controlled documentation standards for pharmaceutical aviation cargo drive sensor-integrated booking platform demand. Forwarders in the Chicago and Dallas logistics clusters are consolidating onto API-first customs engines to automate deviation alerts.
Germany
REACH and RoHS compliance modules force SKU-level chemical substance tracking into standard software configurations for automotive suppliers. ECHA database connectivity requirements from the EU Green Deal implementation accelerate legacy system replacement. Specialty chemical forwarders in the Hamburg port cluster are re-platforming to avoid customs holds on German automotive supply chains.
Singapore
Multi-tenant SaaS architectures serve fragmented shipper demand across Southeast Asian multimodal corridors. The country's trade facilitation mandates under ASEAN digital integration frameworks accelerate API-first customs engine adoption. Forwarders in the Tuas port zone deploy blockchain-EDI protocol convergence to reduce documentation reconciliation delays.
India
DGFT's API-first national trade portal rollout creates first-mover advantage for vendors configuring multi-lingual compliance engines. BIS standards for electronics and machinery imports drive demand for automated classification tools. Logistics operators in the Mumbai-Jawaharlal Nehru Port corridor are migrating from legacy AS/400 systems to cloud-native platforms.
United Kingdom
Post-Brexit customs complexity elevates demand for automated tariff classification engines that bridge EU and UK regulatory regimes. HMRC's phased digital customs transformation program forces re-architecture of legacy clearance workflows. Forwarders in the Felixstowe and Southampton port clusters invest in hybrid deployments to satisfy data localization requirements while maintaining continental connectivity.
Freight Forwarding Software Market Competitive Landscape
Integrated platform specialists and modular compliance vendors split the market into contrasting strategic camps. Consolidation pressure concentrates around vendors capable of embedding real-time customs validation across multimodal corridors. Two archetypes dominate: single-platform architects collapsing warehouse-transport functionality and API-first specialists anchoring customs brokerage automation. Dominant competitive moves include geographic expansion through reseller network bypass and portfolio diversification into cold-chain sensor integration.
Within the integrated platform tier, WiseTech and CargoWise occupy positions exemplifying single-architecture consolidation, while Descartes anchors the modular compliance specialist archetype through North American customs brokerage automation focus. These three entities represent the strategic poles around which mid-sized forwarders and third-party logistics operators cluster their procurement decisions, with each archetype commanding distinct R&D intensity profiles across customs and visibility modules.
| Leading Market Players |
|---|
| WiseTech |
| Descartes |
| CargoWise |
| Magaya |
| Riege Software |
| Softlink |
| Akanea |
| Mercurygate |
| Logistaas |
| Others |
Pricing and Supply Chain Analysis
The Hamburg port cluster anchors European supply capacity for customs engine development, with its concentration of specialized engineering talent translating into premium pricing power for algorithmic compliance modules serving German automotive supply chains.
Pricing Analysis
Geographic price spreads widen significantly between North American and European deployments, with EU data sovereignty mandates adding localization premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity and compliance module depth. Pricing pressure stems from subscription fatigue among mid-sized 3PLs evaluating multi-year SaaS commitments. Private-equity-backed operators in the United States exhibit lowest price sensitivity, prioritizing opex-light structures that preserve acquisition multiples.
Supply Chain Analysis
Contract manufacturing concentrates among specialized software development houses in India and Poland, with these centers handling API-first customs engine builds and multi-lingual localization layers. Core dependencies include cloud infrastructure from hyperscalers, ECHA database subscriptions for REACH compliance, and specialized customs engineering talent. Single-source vulnerability sits with tariff classification expertise pools concentrated in Benelux and Hamburg corridors. Distribution runs through direct digital marketplaces that bypass traditional reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight forwarding software represents an early-cycle expansion story as EU AI Act transparency mandates force replacement of legacy rule-based tariff engines across European port clusters.
For Market Incumbents: Pre-empt API standardization fragmentation by embedding algorithmic explainability modules before regulatory deadlines tighten. Consolidate position through geographic expansion into India's DGFT modernization corridor, where first-mover advantage in multi-lingual compliance engines remains unclaimed. Defensive R&D intensity should concentrate on cold-chain sensor integration as FDA documentation standards harden. For New Entrants and Emerging Players: Pursue warehouse-transport convergence as the most penetrable white space, where single-platform architectures that collapse WMS and TMS functionality remain undersupplied. Target specialty chemical forwarders serving German automotive suppliers, who are re-platforming to avoid customs holds. Lead with API-first customs engines that compress declaration-to-duty latency at Rotterdam and Hamburg terminals. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-tenant SaaS vendors serving fragmented 3PL demand across Asian trade corridors. Long-term viability over the next decade favors platforms with embedded ECHA database connectivity and REACH compliance modules. Monitor DGFT portal adoption curves as the critical inflection signal for Indian market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies WMS and TMS functionality into single-architecture visibility dashboards eliminating swivel-chair workflows. |
| API-First Customs Engine Development | Compresses declaration-to-duty latency at Rotterdam and Hamburg while satisfying EU AI Act transparency requirements. |
| Cold-Chain Sensor Integration | Automates FDA temperature-controlled deviation alerts for pharmaceutical aviation cargo documentation standards. |
| Geographic Expansion into India | Captures first-mover advantage from DGFT's API-first national trade portal rollout across Mumbai-JNPT corridor. |
| Acquisition of Specialist Compliance Vendors | Embeds REACH and RoHS SKU-level chemical substance tracking capabilities for German automotive supplier segments. |
Research Methodology
The analysis maps cloud-native deployments, SaaS subscriptions, on-premise legacy systems, and hybrid configurations, each validated through primary interviews with CTOs at third-party logistics operators, IT procurement officers at freight forwarders, platform engineers specializing in customs API development, and integration specialists managing EDI-blockchain protocol convergence. Secondary validation draws from SEC filings of listed software vendors, DGFT portal technical documentation, ECHA database subscription disclosures, and customs authority API specification releases. Bottom-up deployment counts triangulate against top-down vendor revenue segmentation.
Assumptions hold EU AI Act implementation timelines and FDA documentation standards fixed across the projection horizon, while varying cloud migration velocity by forwarder size tier and geographic regulatory intensity. Segmentation dimensions modeled include deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern. CAGRs derive from annualized subscription revenue trajectories and perpetual license conversion rates, with inputs from customs modernization program budgets and 3PL technology procurement disclosures.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting private-equity acquisition multiples or trade volume volatility at Rotterdam and Hamburg would shift the trajectory. Forecasts reflect assumptions around regulatory implementation cadence and API standardization convergence. Quarterly review of DGFT portal transaction volumes, ECHA database subscription renewals, and customs authority API release schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Tenant Billing System Market
Software & Services
Global Ad Server Software Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Sales Force Automation Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Network Documentation Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Clustering Software Market
Software & Services
Global Digital Experience Management Software Market