
 Sweden Data Center Networking Market | 2026-2036
Sweden Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Networking Market Insights
Market Context
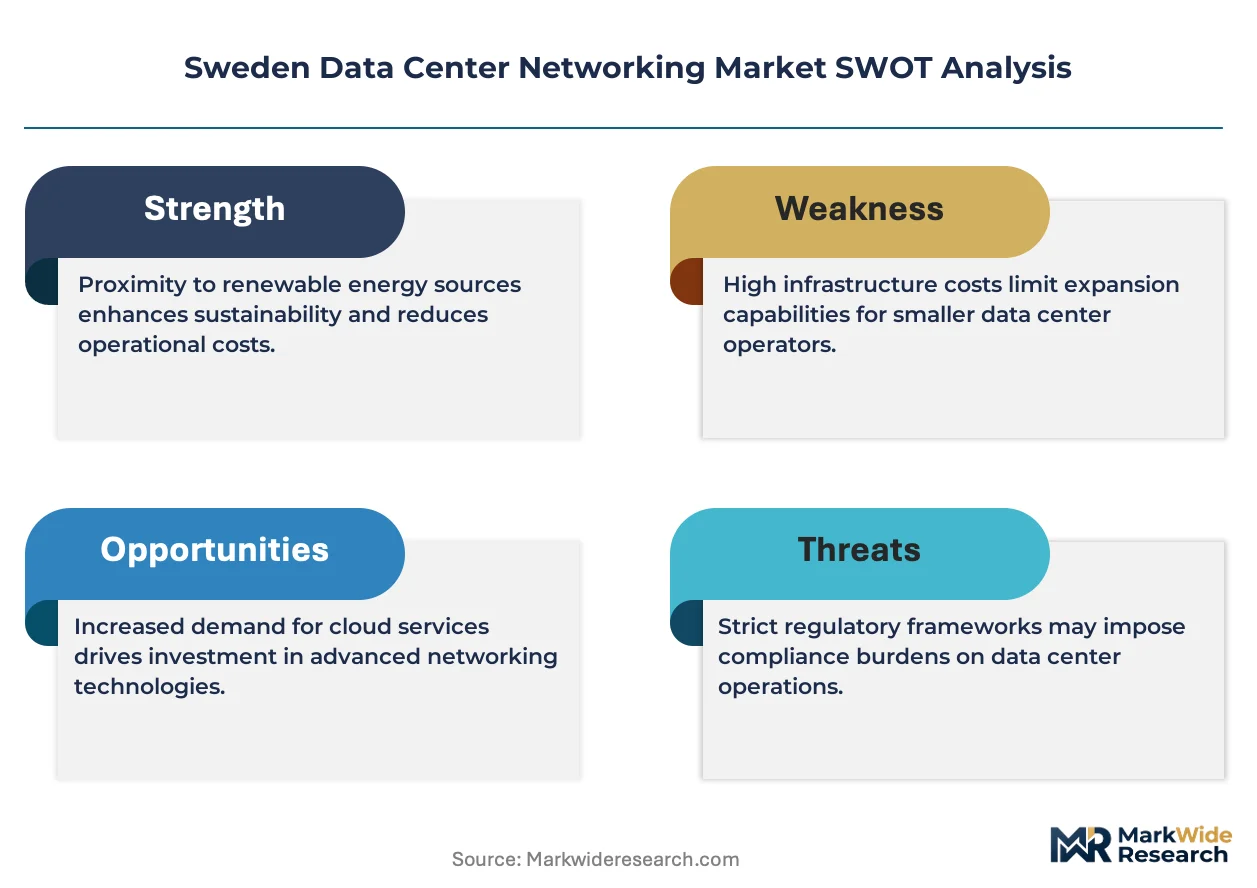
Sweden is fragmenting its data center networking landscape through distributed capacity builds in Luleå, Stockholm, and Gothenburg. Cisco Systems Inc anchors Nordic enterprise switching with deep channel relationships across Scandinavian system integrators. NVIDIA Corporation leverages its InfiniBand and Ethernet portfolio to dominate AI training cluster interconnects. Arista Networks Inc competes aggressively on cloud-scale leaf-spine architectures for Swedish hyperscale deployments.
Technical Definition and Segment Structure
Data center networking encompasses the switching, routing, and interconnect infrastructure that enables compute and storage resource communication within and between facilities, operating at speeds from 25 Gbps to 800 Gbps with sub-microsecond latency targets. Switching equipment commands the largest product type revenue pool as spine-leaf architectures displace legacy three-tier designs in Swedish facilities. IT companies represent the fastest-growing end user segment, outpacing telecommunications incumbents through insourced AI infrastructure build-outs. Consulting services within the service type dimension capture expanding margin pools as organizations navigate multi-vendor interoperability and sustainability compliance.
Regulatory Environment
Swedish data center operators face overlapping compliance obligations from GDPR data residency rules, EU Green Deal energy efficiency mandates, and CSRD sustainability disclosure requirements. BIS-aligned electrical safety standards and CE marking directives shape equipment procurement specifications for domestic installations. Stakeholders must monitor evolving EU AI Act infrastructure classifications and their downstream cabling and latency specifications.
Market Dynamics
Swedish data center networking infrastructure is fragmenting geographically as hyperscale operators distribute capacity across Luleå's renewable energy corridor, Stockholm's financial services cluster, and Gothenburg's emerging submarine cable landing zone, creating divergent latency and bandwidth requirements that reshape switching fabric procurement patterns.
Growth Catalysts
- EU AI Act infrastructure mandates:The classification of high-risk AI systems triggers data residency requirements that drive Swedish financial institutions toward sovereign colocation builds with dedicated interconnect fabrics.
- Hyperscale corridor concentration:Stockholm's emergence as a Nordic hyperscale hub concentrates demand for 400G/800G spine-leaf architectures and software-defined interconnect platforms.
- Immersion cooling adoption:Liquid-cooled server deployments in Luleå facilities require redesigned top-of-rack switching with modified thermal specifications and cable management systems.
Market Restraints
- Optical transceiver supply concentration:Dependency on Asian manufacturing clusters for 800G coherent optics creates lead time volatility and inventory risk for Swedish network build-outs.
- GDPR-CSRD compliance layering:Overlapping data residency, energy efficiency disclosure, and sustainability reporting obligations inflate procurement documentation burdens and extend vendor qualification cycles.
- Copper cabling substitution limits:Power consumption constraints in high-density AI training clusters restrict the use of passive copper DACs beyond three-meter reaches, forcing premature optical conversion.
Strategic Opportunities
- Gothenburg cable landing expansion:New submarine fiber routes connecting Sweden to continental Europe and the United Kingdom position the city's data centers as interconnection hubs requiring distributed switching fabrics.
- EU Green Deal energy efficiency incentives:Tax advantages for facilities achieving PUE targets below 1.2 accelerate demand for intelligent power-optimized switching with telemetry-driven workload placement.
- Converged Ethernet-InfiniBand fabrics:Unified networking for AI training and general-purpose workloads reduces Swedish hyperscale operators' need for parallel infrastructure investments.
Industry Challenges
- Sub-microsecond latency engineering scarcity:Swedish facilities lack sufficient specialists in RDMA tuning and congestion management for AI cluster interconnects, forcing reliance on vendor professional services.
- CE marking-BIS electrical safety alignment:Equipment procurement specifications must reconcile European conformity marking with Swedish national electrical standards, complicating multi-vendor interoperability testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Networking Market |
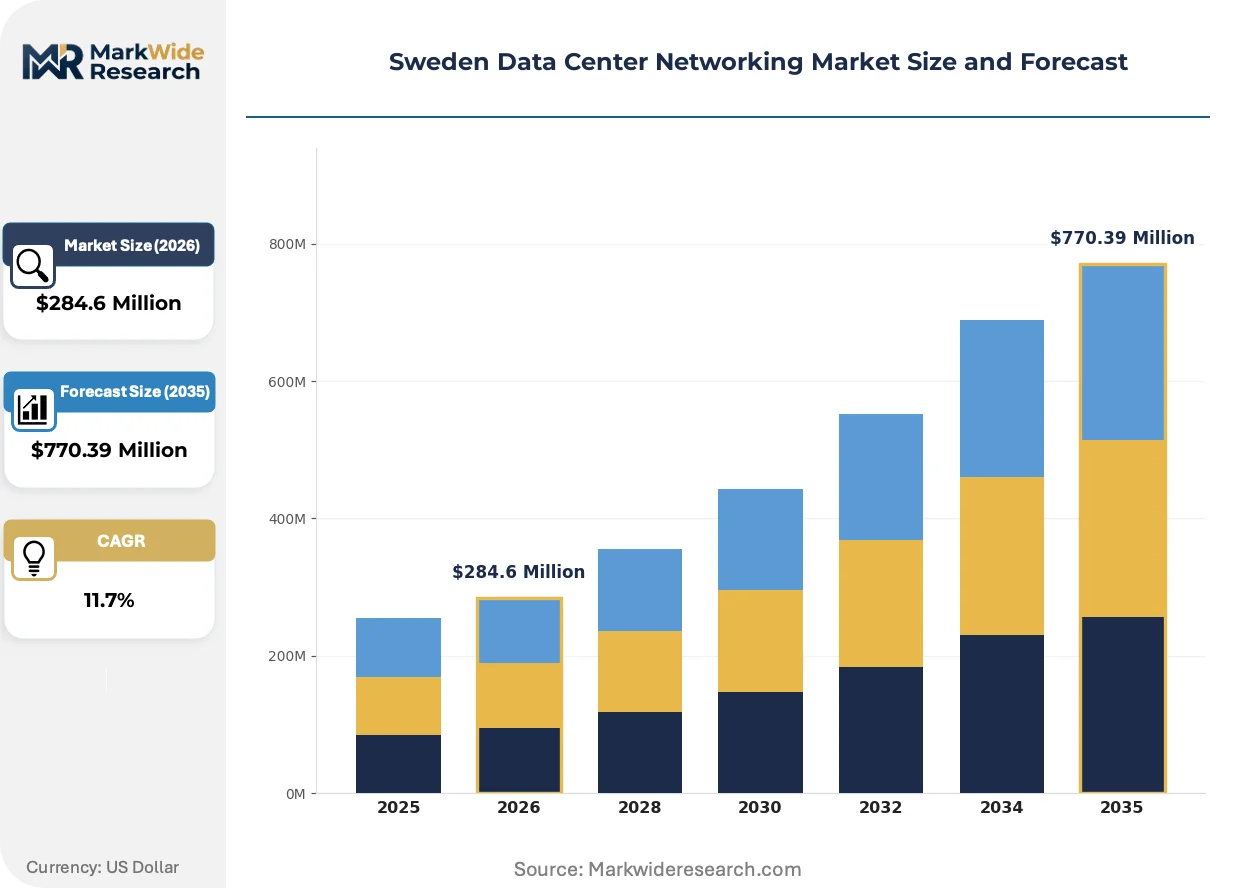
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $770.39 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switching Equipment, Routers, Firewalls, Network Cables Service Type: Installation Services, Maintenance Services, Consulting Services, Support Services Operating System: Linux, Windows, Unix, VMware End User: Telecommunications, IT Companies, Government Agencies, Educational Institutions |
| Companies Covered | Dell Inc, NVIDIA Corporation, Cisco Systems Inc, NEC Corporation, HP Development Company L P, Arista Networks Inc, IBM Corporation, VMware Inc, Huawei Technologies Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Networking Market Trends and Innovations
Silicon photonics integration and automated network provisioning are compressing deployment timelines while regulatory pressure on embodied carbon reshapes equipment refresh cycles across Swedish facilities.
Co-packaged optics technology is migrating from experimental hyperscale trials to mainstream enterprise adoption in Stockholm's financial services data centers. SEB and Nordea are piloting 51.2T switch silicon with integrated optical engines to reduce power-per-bit by forty percent. This migration from pluggable transceivers to co-packaged architectures is compressing the traditional three-year switching refresh cycle toward eighteen-month intervals for latency-sensitive trading infrastructure.
CSRD sustainability disclosure requirements now mandate Scope 3 emissions reporting for Swedish data center operators, forcing granular tracking of networking equipment embodied carbon. The directive compels procurement teams to weight manufacturer environmental product declarations alongside technical specifications. Swedish facility operators are responding by embedding circularity clauses into switching contracts requiring take-back programs and refurbishment guarantees.
Consumption-based network provisioning is displacing capital-intensive ownership models among mid-market Swedish enterprises. Colocation providers now offer switching fabric as a metered utility with bandwidth autoscaling, unbundling hardware procurement from operational expenditure. This shift is most visible in Gothenburg's emerging data center zone where pharmaceutical and automotive firms prefer operational flexibility over fixed infrastructure commitments.
Sweden Data Center Networking Market Segmentation
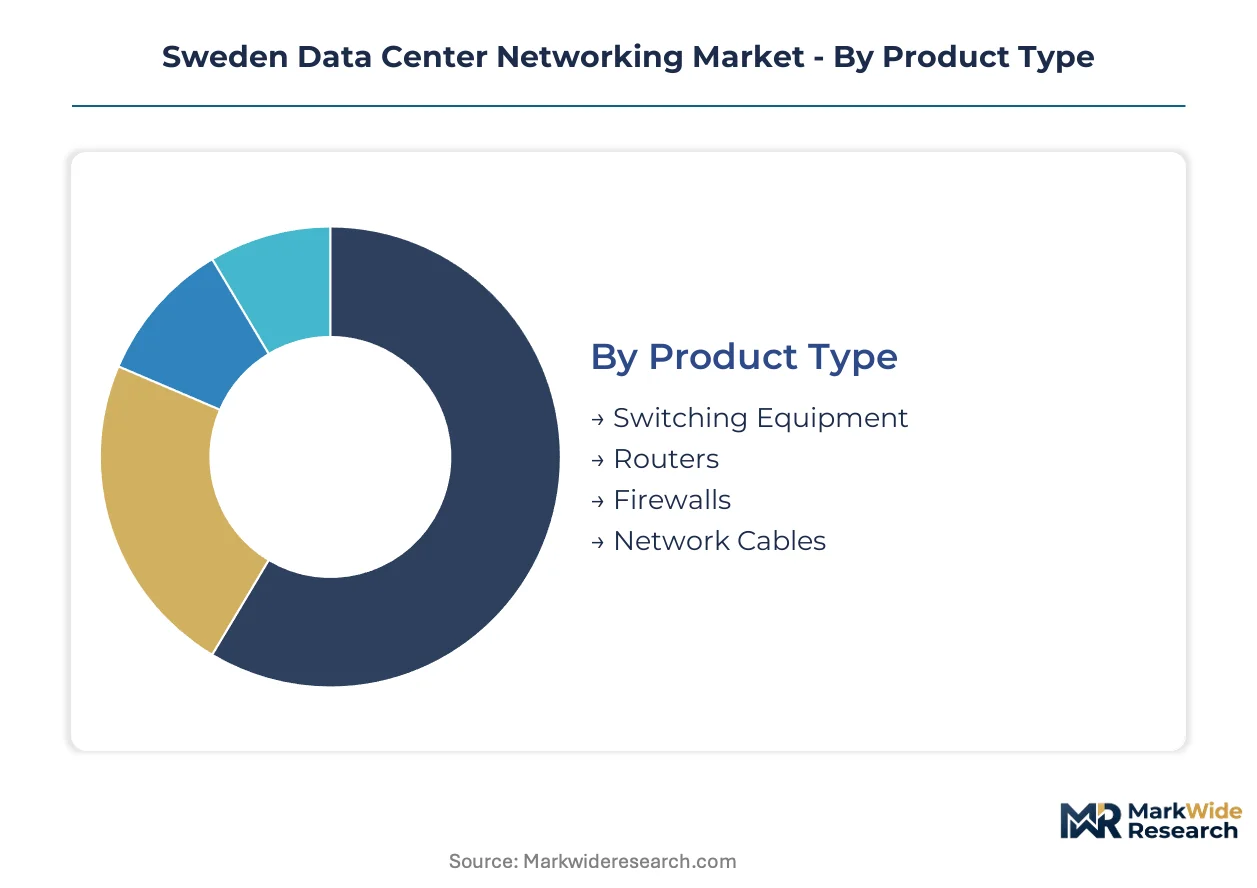
Swedish data center networking procurement diverges sharply across facility types and compliance mandates. Hyperscale operators in Stockholm prioritize spine-leaf switching fabrics with sub-microsecond latency, while distributed edge deployments in Gothenburg emphasize modular service delivery models.
Product Type:
Use cases span from AI training clusters demanding 800G spine-leaf architectures to legacy enterprise facilities refreshing three-tier designs with 25G top-of-rack switches.
- Switching Equipment:Spine-leaf and leaf-spine architectures displace legacy three-tier designs across Swedish hyperscale facilities. Stockholm's financial services corridor concentrates procurement of 400G/800G silicon with RDMA over Converged Ethernet for AI training clusters under EU AI Act data residency mandates.
- Routers:Border and core routing platforms manage inter-facility traffic across Sweden's geographically distributed data center triangle. Luleå's renewable energy corridor drives demand for power-optimized routing with telemetry integration to meet EU Green Deal PUE targets below 1.2.
- Firewalls:Next-generation firewall appliances secure east-west traffic within zero-trust architectures. Swedish government agencies mandate FIPS 140-2 validated modules for classified workload segmentation.
- Network Cables:Optical fiber dominates beyond three-meter reaches as passive copper DACs face power constraints in high-density AI clusters. Immersion cooling deployments in Luleå require modified cable management specifications.
The dominant share belongs to Switching Equipment, while Network Cables is closing the gap fastest.
Service Type:
Procurement patterns split between capital-intensive ownership among hyperscale operators and consumption-based utility models emerging in Gothenburg's pharmaceutical and automotive sectors.
- Installation Services:Structured cabling deployment and rack-and-stack integration for spine-leaf fabrics. Stockholm's SEB and Nordea trading infrastructure demands co-packaged optics installation with eighteen-month refresh cycles.
- Maintenance Services:Hardware replacement and firmware management under multi-year service contracts. Swedish operators embed circularity clauses requiring manufacturer take-back programs per CSRD Scope 3 disclosure mandates.
- Consulting Services:Multi-vendor interoperability architecture and sustainability compliance navigation. GDPR-CSRD layering inflates documentation burdens and extends vendor qualification cycles.
- Support Services:Technical assistance and break-fix coverage for heterogeneous networking estates. Mid-market enterprises in Gothenburg prefer metered utility models with bandwidth autoscaling.
Consulting Services commands the widest margin expansion, with Support Services gaining share through operational flexibility preferences.
Operating System:
Platform selection hinges on workload orchestration requirements and existing enterprise infrastructure footprints across Swedish facilities.
- Linux:Dominates cloud-native and AI training environments with kernel-bypass networking for RDMA workloads. NVIDIA's DOCA and open-source DPDK drive adoption in Stockholm hyperscale corridors.
- Windows:Persists in enterprise colocation facilities with Active Directory-integrated network policy management. Financial services firms maintain hybrid estates for legacy application compatibility.
- Unix:Retains presence in telecommunications carrier central offices with proven reliability for signaling infrastructure. Telia and Tele2 maintain Solaris and AIX deployments for SS7 and diameter routing.
- VMware:NSX-T microsegmentation extends across Swedish enterprise virtualized estates. Government agencies leverage VMware's sovereign cloud partnerships for GDPR-compliant workload placement.
Linux holds the installed base majority, with VMware expanding most quickly through microsegmentation attach rates.
End User:
Demand concentration varies from latency-sensitive trading infrastructure to sovereign cloud deployments with strict data residency requirements.
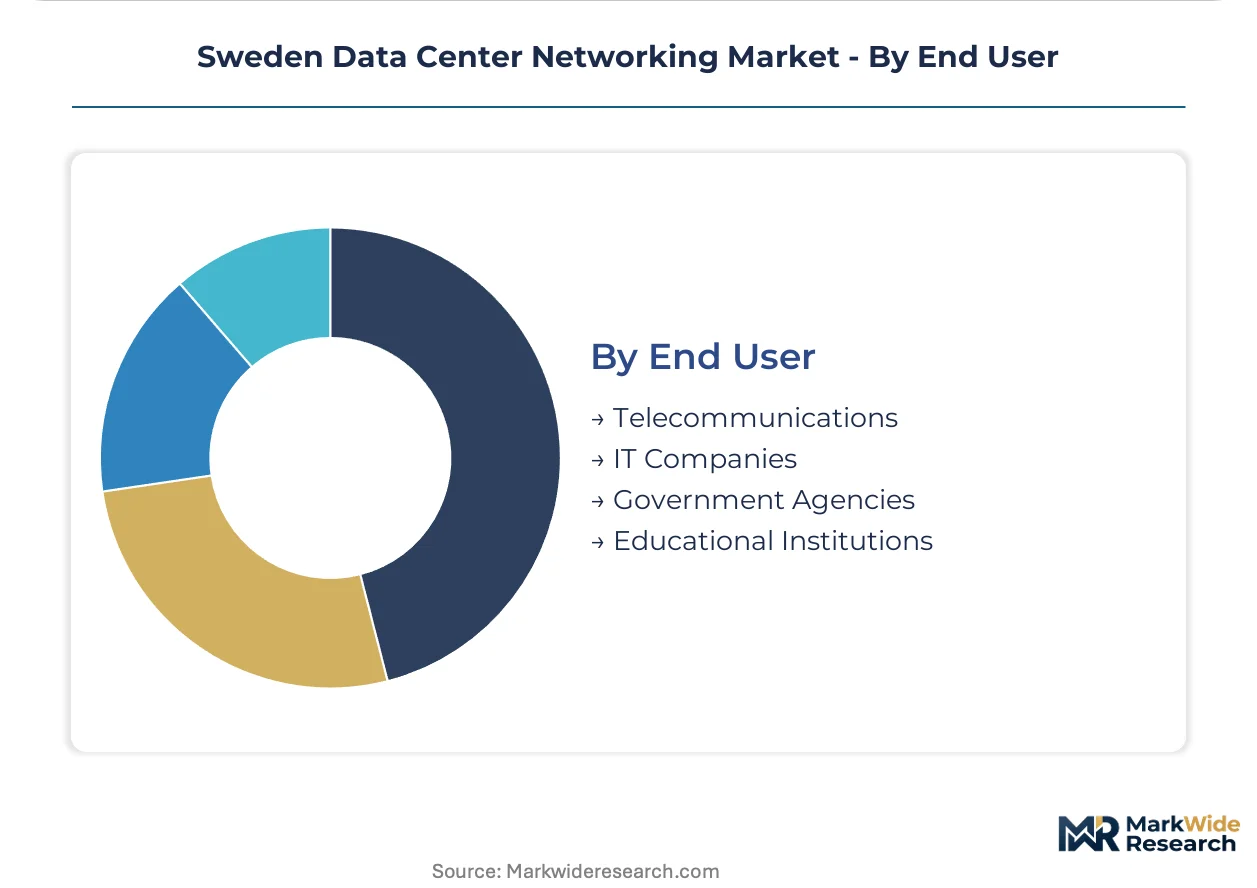
- IT Companies:Hyperscale operators and cloud providers build insourced AI infrastructure with 800G spine-leaf fabrics. Stockholm's corridor concentrates domestic demand for software-defined interconnects and automated provisioning platforms.
- Telecommunications:Incumbent carriers modernize central office infrastructure for edge computing workloads. Telia's distributed capacity builds across Luleå, Stockholm, and Gothenburg reshape metro optical requirements.
- Government Agencies:National and municipal entities deploy sovereign colocation under MSB cybersecurity frameworks. Classified systems mandate dedicated interconnect fabrics with FIPS-validated encryption.
- Educational Institutions:Universities operate research computing clusters with InfiniBand and high-bandwidth Ethernet. KTH Royal Institute and Chalmers drive adoption of converged fabrics for HPC-AI convergence.
IT Companies captures the largest revenue pool, with Government Agencies climbing the fastest on EU AI Act infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish Energy Agency efficiency mandates anchor Nordic data center networking demand as operators navigate overlapping EU AI Act and CSRD compliance obligations across distributed capacity zones.
Stockholm Metro
Financial services hyperscale concentration drives 400G/800G spine-leaf procurement for AI training clusters. SEB and Nordea trading infrastructure demands sub-microsecond latency switching under EU AI Act data residency classifications. The Kista Science City corridor concentrates domestic demand for software-defined interconnect platforms.
Luleå Renewable Energy Corridor
Facebook and Google legacy hyperscale footprints expand with immersion-cooled server deployments requiring modified thermal specifications for top-of-rack switching. EU Green Deal PUE targets below 1.2 accelerate intelligent power-optimized switching adoption. The Node Pole cluster anchors Sweden's carbon-negative data center positioning.
Gothenburg Cable Landing Zone
Submarine fiber routes to continental Europe and the United Kingdom position the city as an interconnection hub demanding distributed switching fabrics. Pharmaceutical and automotive firms prefer consumption-based network provisioning with bandwidth autoscaling. The Lindholmen Science Park cluster drives metered utility model adoption.
Sweden Data Center Networking Market Competitive Landscape
Capability concentration sits with specialized switching fabric architects; scale advantage sits with broad infrastructure conglomerates spanning compute, storage, and networking portfolios. The vendor base stratifies across three tiers: hyperscale-optimized specialists, full-stack infrastructure providers, and regional system integrators with deep channel relationships. Dominant competitive moves include converged Ethernet-InfiniBand fabric development and circularity-embedded service contracting under CSRD Scope 3 mandates.
Within the hyperscale-optimized tier, Arista Networks Inc and NVIDIA Corporation exemplify divergent architectural philosophies for AI cluster interconnects. Cisco Systems Inc anchors the full-stack infrastructure segment through Scandinavian system integrator channel density. These three entities collectively represent the competitive poles shaping procurement specifications across Stockholm's financial services corridor and Luleå's renewable energy zone.
| Leading Market Players |
|---|
| Dell Inc |
| NVIDIA Corporation |
| Cisco Systems Inc |
| NEC Corporation |
| HP Development Company L P |
| Arista Networks Inc |
| IBM Corporation |
| VMware Inc |
| Huawei Technologies Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Asian optical transceiver manufacturing determines both the premium-to-economy spread in 800G switching tiers and the elongated supply chain shape Swedish operators must navigate. Tariff exposure through Taiwan and South Korean component flows compresses margins on high-density spine-leaf deployments while forcing inventory pre-positioning that inflates working capital requirements.
Pricing Analysis
Stockholm commands a fifteen-to-twenty percent premium over Gothenburg for equivalent 400G switching fabrics due to financial services latency requirements and EU AI Act compliance premiums. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by RDMA certification grade and after-sales telemetry integration. Cost compression in economy-tier copper-DAC segments is intensifying because passive cabling faces three-meter reach constraints in AI clusters. Hyperscale operators exhibit lowest price sensitivity; mid-market pharmaceutical firms in Gothenburg demonstrate highest elasticity.
Supply Chain Analysis
Foxconn and Jabil Electronics hold dominant contract manufacturing capacity for 51.2T switch silicon and co-packaged optical engines. Geographic concentration centers on Taiwan, South Korea, and Malaysia for 800G coherent optics and advanced packaging substrates. Raw material dependencies span gallium arsenide wafers, rare-earth-doped fiber, and halogen-free PCB laminates. Single-source vulnerability in Taiwanese foundry capacity represents the primary structural risk. Distribution runs through Scandinavian system integrators with deep channel relationships into SEB, Nordea, and Telia procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Stockholm's hyperscale corridor operators as three financial institutions consolidate colocation procurement under sovereign AI infrastructure mandates. This consolidation fragments vendor pricing leverage and extends qualification cycles.
For Market Incumbents: Pre-empt Arista's cloud-scale leaf-spine momentum by embedding circularity clauses into switching contracts before CSRD Scope 3 disclosure mandates harden. Accelerate certification investment for BIS-aligned electrical safety standards to compress multi-vendor interoperability testing timelines. Defensive consolidation around NVIDIA's InfiniBand-Ethernet convergence roadmap protects against merchant silicon commoditization. For New Entrants and Emerging Players: Gothenburg's pharmaceutical and automotive mid-market represents the most penetrable entry point, with metered utility network provisioning preferred over capital-intensive ownership models. Luleå's immersion-cooled server deployments require redesigned top-of-rack switching with modified thermal specifications—a specification gap incumbent vendors have addressed slowly. Go-to-market through colocation provider channel partnerships bypasses direct hyperscale qualification barriers. For Investors and Strategic Acquirers: The market sits at a compliance-driven upgrade phase that favors specialist switching fabric architects with proven EU AI Act infrastructure deployments. Long-term viability over the next decade rests on silicon photonics integration capabilities and automated provisioning platform maturity. Acquisition targets should demonstrate co-packaged optics roadmaps and established take-back program infrastructure. Watch for inflection in 800G coherent optics lead times as a signal of supply constraint easing or tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Ethernet-InfiniBand Fabric Convergence | Unified networking reduces parallel infrastructure investments for Swedish hyperscale operators. |
| Circularity-Embedded Service Contracting | Take-back programs address CSRD Scope 3 disclosure mandates for networking equipment embodied carbon. |
| Co-Packaged Optics Migration | SEB and Nordea pilot 51.2T silicon with integrated optical engines to cut power-per-bit. |
| Intelligent Power-Optimized Switching | Telemetry-driven workload placement helps Luleå facilities achieve EU Green Deal PUE targets below 1.2. |
| Software-Defined Interconnect Platforms | Kista Science City corridor concentrates demand for automated network provisioning in financial services. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with data center infrastructure directors, network architects at Swedish financial institutions, procurement leads at hyperscale operators, and sustainability compliance officers; and secondary validation through SEC filings of Arista Networks and NVIDIA, EU AI Act implementation guidance, Swedish Energy Agency efficiency mandate documentation, and hyperscaler capex disclosures. Bottom-up equipment unit economics triangulated against top-down market sizing across switching, routing, and optical interconnect categories.
Forecast inputs considered deployment velocity across Stockholm's financial services corridor, Luleå's renewable energy zone, and Gothenburg's cable landing expansion. Segmentation dimensions modeled encompass product type, service type, operating system platform, and end-user vertical with regional facility type as an additional data center-specific dimension. CAGRs were derived from installed base refresh cycle compression and AI training cluster build-out trajectories. Industry-specific inputs included EU Green Deal PUE compliance timelines and EU AI Act infrastructure classification rollout schedules.
Stress conditions across optical transceiver supply lead times, CE marking-BIS alignment delays, and GDPR-CSRD documentation burden inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscale capacity distribution and sovereign colocation build-out pacing. Quarterly review of 800G coherent optics inventory positions and Swedish Energy Agency mandate enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Fog Networking Market