
 5G Edge Cloud Network and Services Market | 2026-2036
5G Edge Cloud Network and Services Market Size, Share, and Industry Trends Forecast 2026-2036
5G Edge Cloud Network and Services Market Outlook
South Korea is reconfiguring its national broadband infrastructure around distributed edge nodes. Nokia Corporation leverages its AirFrame server portfolio to anchor cloud RAN deployments across Seoul and Busan. Ericsson competes through integrated radio and compute platforms that sustain sub-ten-millisecond latency guarantees for enterprise customers. Huawei Technologies Co., Ltd. dominates equipment supply across Asia-Pacific through vertical integration into baseband silicon and edge server manufacturing.
5G Edge Cloud Network and Services denotes distributed compute and storage resources positioned at cellular network peripheries, typically within one to two hops of end-user devices and operating on virtualized infrastructure with NFV and SDN orchestration layers. These systems process data locally to reduce backhaul congestion and enable real-time applications including autonomous vehicle coordination and industrial robotic control. Multi-Access Edge Computing services capture the fastest expansion as telecommunications operators monetize latency-sensitive enterprise workloads. Cloud RAN installations represent the largest installed base but face margin pressure from commoditized radio hardware. Network Slicing generates premium pricing where carriers guarantee isolated quality-of-service tiers for automotive and industrial end users.
The Federal Communications Commission in the United States auctions millimeter-wave spectrum blocks that determine edge node density and capital deployment schedules for national carriers. South Korea's Ministry of Science and ICT enforces equipment certification standards that shape vendor eligibility for public 5G infrastructure tenders. The European Union's Cybersecurity Act and NIS2 Directive impose mandatory incident reporting and supply chain security reviews that filter market access for non-compliant equipment providers. Stakeholders must monitor spectrum allocation timelines and certification harmonization across jurisdictions to anticipate deployment windows and procurement eligibility.
Market Dynamics
Telecommunications operators are consolidating radio access network functions onto centralized cloud infrastructure, compressing hardware diversity and forcing equipment vendors to compete on software orchestration capabilities rather than proprietary silicon.
Growth Catalysts
- EU Cybersecurity Act certification:Mandatory baseline security standards for network equipment are filtering vendor pools and accelerating procurement of compliant edge infrastructure across member states.
- Smart manufacturing automation:German industrial facilities are deploying private 5G edge networks to coordinate real-time robotic control systems and predictive maintenance workflows.
- Millimeter-wave spectrum allocation:The FCC's auction of high-band frequencies is determining edge node density requirements and capital deployment timelines for national carriers.
Market Restraints
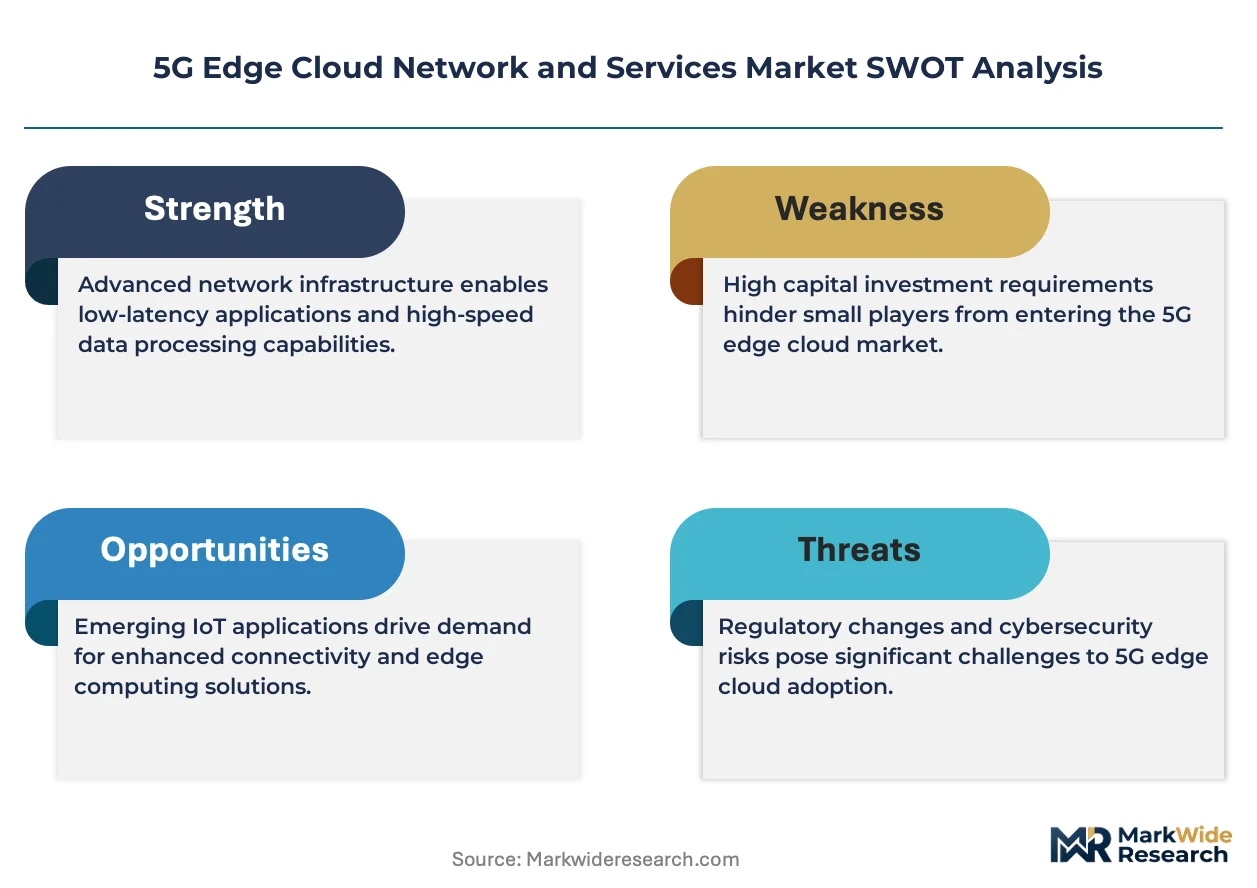
- Baseband processor supply concentration:Advanced silicon fabrication for 5G modems depends on a limited number of foundry operators, creating input bottlenecks during demand surges.
- Energy cost volatility:Edge data centers consume substantial power for cooling and compute, exposing operators to electricity price fluctuations that compress operating margins.
- Optical transport capacity limits:Fronthaul fiber requirements for Cloud RAN deployments exceed existing metro network density in secondary cities.
Strategic Opportunities
- Multi-Access Edge Computing services:Telecommunications operators are monetizing latency-sensitive enterprise workloads through distributed compute nodes positioned at cellular base stations.
- Network Slicing guarantees:Isolated quality-of-service tiers for automotive and industrial end users command premium pricing where carriers can enforce strict latency bounds.
- NFV-SDN convergence:Virtualized infrastructure with software-defined orchestration layers enables rapid service instantiation without hardware swaps.
Industry Challenges
- Cloud-native engineering talent scarcity:Operators struggle to recruit personnel skilled in Kubernetes orchestration and containerized network function deployment.
- Legacy 4G core integration:Interoperability requirements with existing packet cores complicate standalone 5G edge rollouts and extend testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Edge Cloud Network and Services Market |
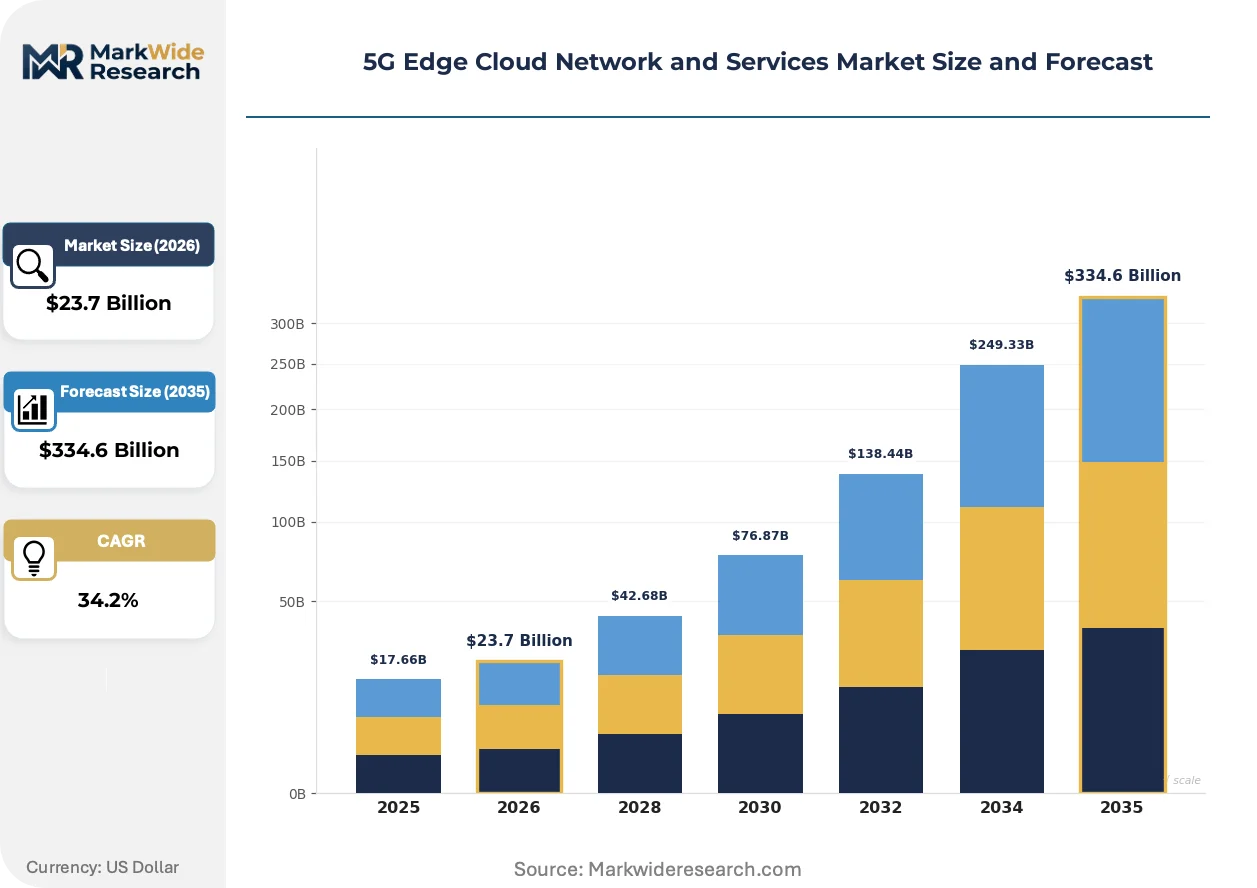
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $334.6 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Slicing, Multi-Access Edge Computing, Cloud RAN, Hybrid Cloud Technology: Virtualization, MEC, NFV, SDN End User: Telecommunications, Media & Entertainment, Automotive, Industrial Deployment Model: On-Premises, Cloud-Based, Edge Computing, Centralized |
| Companies Covered | Nokia Corporation, Ericsson, Huawei Technologies Co., Ltd., Cisco Systems, Inc., Dell Technologies Inc., Hewlett Packard Enterprise, IBM Corporation, Amazon Web Services, Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Edge Cloud Network and Services Market Strategic Shifts
Open RAN architectures are dismantling proprietary vendor lock-in by disaggregating radio hardware from baseband software, enabling multi-vendor deployments and shifting competitive advantage toward systems integrators.
Cloud-native network functions are collapsing the traditional boundary between radio access and core network infrastructure. Mobile operators in South Korea are migrating baseband processing to centralized edge data centers, reducing site-specific hardware requirements by half. This compression is enabling faster service deployment cycles and lowering total cost of ownership for dense urban coverage.
REACH chemical restrictions and RoHS substance limits are forcing equipment manufacturers to reformulate solder materials and flame-retardant compounds in printed circuit boards. European network infrastructure tenders now require full material disclosure documentation. Asian component suppliers are establishing dedicated compliance teams to maintain eligibility for EU public procurement contracts.
Enterprise buyers are consolidating vendor relationships around integrated platform providers rather than assembling multi-source radio and compute stacks. Automotive manufacturers in Germany now specify end-to-end latency guarantees in procurement contracts, penalizing suppliers for service degradation. This behavioral shift favors telecommunications operators with captive spectrum holdings over neutral host infrastructure providers.
5G Edge Cloud Network and Services Market Segmentation
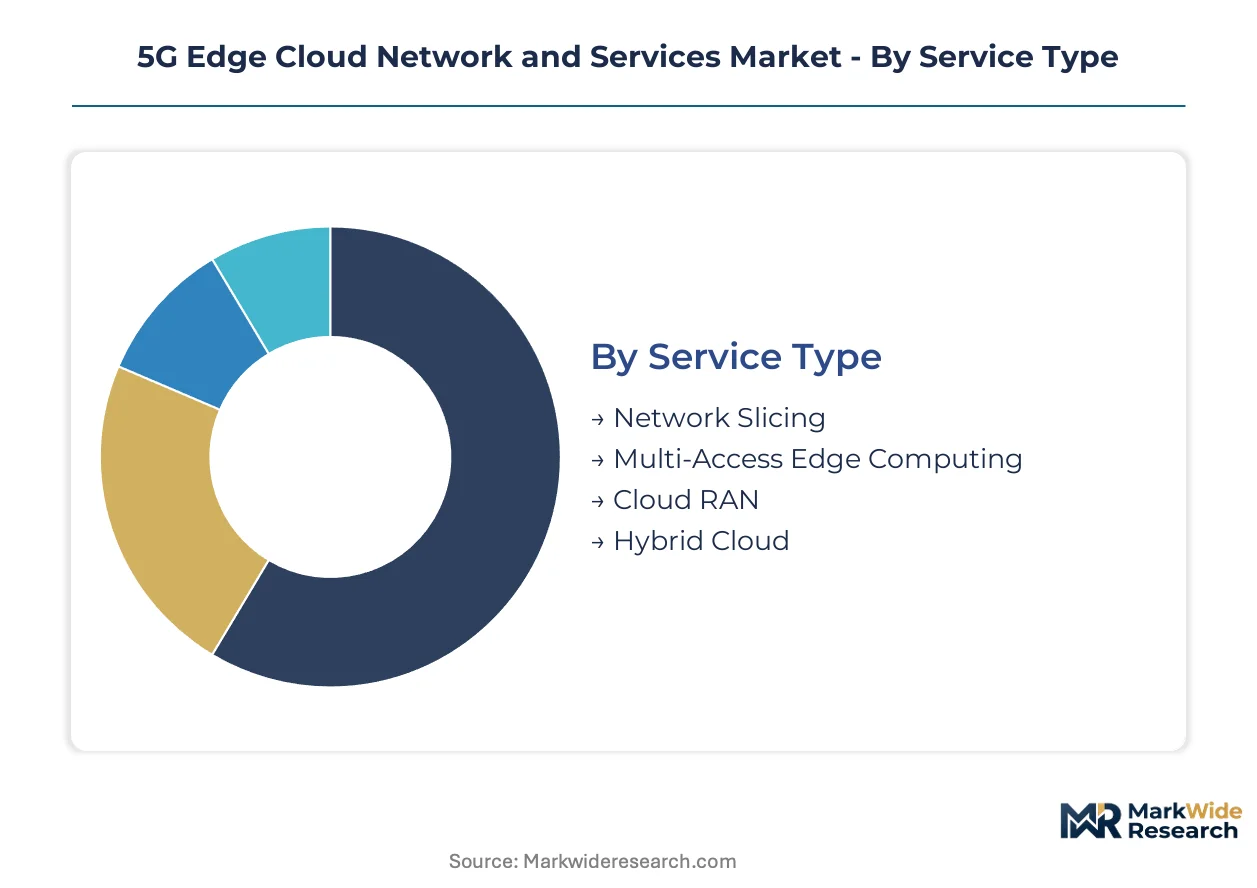
Segmentation in 5G edge cloud infrastructure reveals distinct service delivery models and technology stacks that command differentiated pricing. Procurement patterns vary sharply across deployment models, with on-premises installations requiring sustained field engineering support while cloud-based offerings scale through automated orchestration layers.
Service Type:
After-sales service intensity peaks with Network Slicing and Cloud RAN deployments, where carriers demand continuous latency monitoring and guaranteed service level enforcement.
- Network Slicing:Isolated virtual network instances with dedicated quality-of-service parameters for automotive and industrial clients. German automotive manufacturers specify end-to-end latency penalties in procurement contracts, forcing operators to maintain 24/7 network operations centers. By volume, Cloud RAN leads. By growth pace, Network Slicing is ahead.
- Multi-Access Edge Computing:Distributed compute nodes positioned at cellular base stations processing data within one to two hops of end-user devices. South Korean operators monetize MEC through low-latency gaming and industrial robotic control services in Seoul and Busan metropolitan clusters.
- Cloud RAN:Centralized baseband processing over fronthaul fiber connections reduces site-specific hardware requirements.
- Hybrid Cloud:Mixed deployment combining on-premises edge nodes with centralized cloud bursting for variable workloads.
Service type selection correlates directly with customer technical maturity and captive spectrum access.
Technology:
Cost tier separation is pronounced, with SDN and NFV implementations commanding premium pricing over basic virtualization layers due to orchestration complexity.
- Virtualization:Foundational compute abstraction enabling hardware-independent network function deployment. European operators under EU Cybersecurity Act mandates prioritize certified virtualization stacks for public infrastructure tenders.
- MEC:Multi-Access Edge Computing platforms anchor latency-sensitive application hosting at network peripheries. Expanding most quickly as telecommunications operators commercialize distributed compute for enterprise workloads.
- NFV:Network Functions Virtualization collapses proprietary hardware dependencies into software instances.
- SDN:Software-Defined Networking enables centralized traffic engineering across disaggregated transport layers.
Technology stack decisions lock in vendor relationships for multi-year refresh cycles.
End User:
Application requirements diverge sharply, with Industrial and Automotive segments demanding sub-ten-millisecond guarantees that Telecommunications and Media clients rarely specify.
- Telecommunications:Carrier internal infrastructure and wholesale edge capacity provisioning. SK Telecom and KT Corporation operate national edge cloud infrastructure supporting ultra-low latency services across South Korean territory.
- Industrial:Smart manufacturing facilities deploying private 5G edge networks for real-time robotic control and predictive maintenance workflows. German industrial automation clusters drive concentrated demand for isolated network slices with guaranteed throughput.
- Media & Entertainment:Content delivery and immersive streaming applications.
- Automotive:Connected vehicle coordination and autonomous driving safety systems.
End user procurement authority is shifting from IT departments to operational technology leads in manufacturing and transportation sectors.
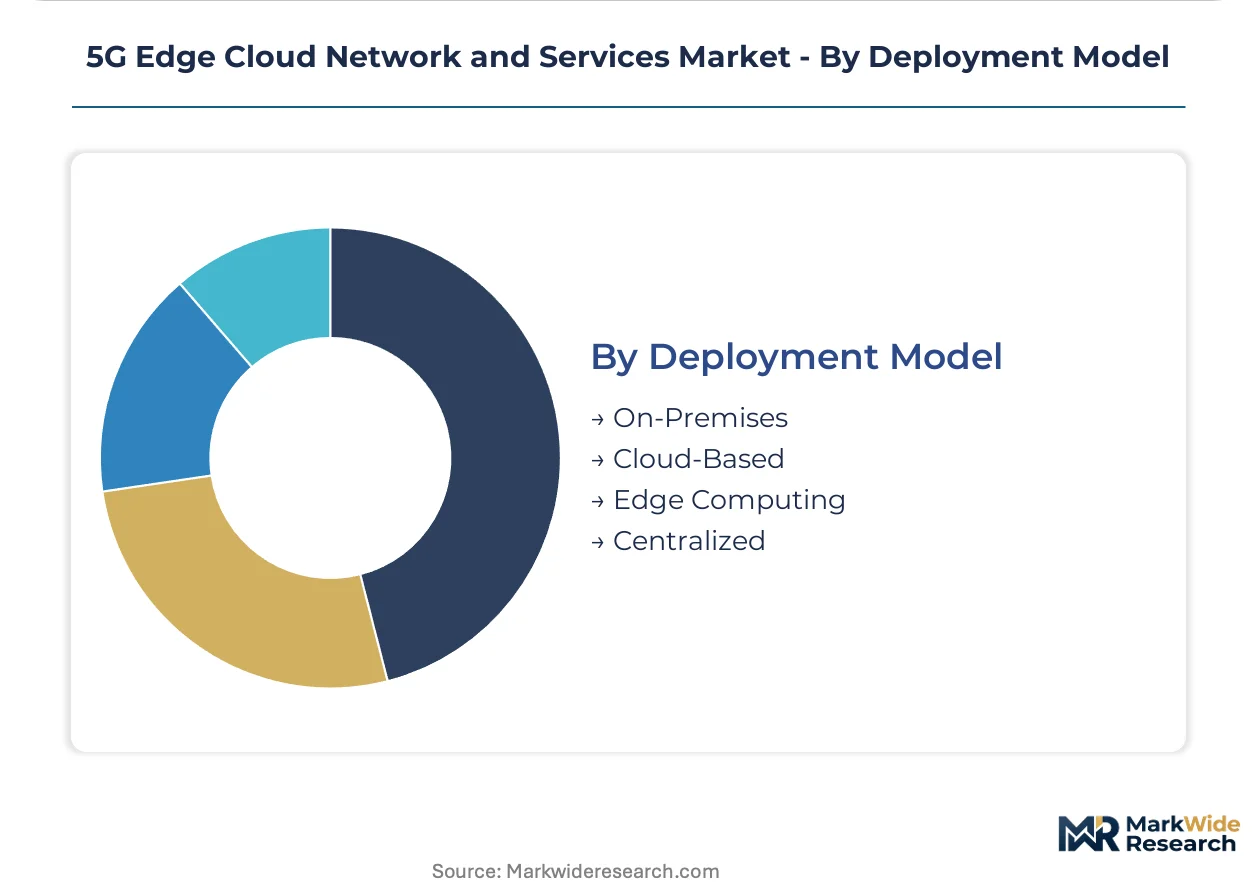
Deployment Model:
Customer type determines deployment architecture, with hyperscale cloud providers favoring centralized models while defense and financial sectors mandate on-premises sovereignty.
- On-Premises:Dedicated edge infrastructure within enterprise-controlled facilities meeting data residency requirements. European manufacturers under GDPR and NIS2 Directive provisions increasingly specify on-premises edge nodes for sensitive production data.
- Edge Computing:Distributed micro-data centers at cellular base stations or network aggregation points. Climbing the fastest as operators densify metropolitan coverage and enterprise customers demand proximity guarantees.
- Cloud-Based:Centralized hyperscale resources with edge caching layers.
- Centralized:Regional data hub architectures minimizing distributed hardware footprint.
Deployment model selection constrains vendor eligibility based on security certification scope and geographic service coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC auctions millimeter-wave spectrum blocks that determine edge node density and capital deployment schedules for national carriers. South Korea's Ministry of Science and ICT enforces equipment certification standards that shape vendor eligibility for public 5G infrastructure tenders. The European Union's Cybersecurity Act and NIS2 Directive impose mandatory incident reporting and supply chain security reviews that filter market access for non-compliant equipment providers.
United States
Telecommunications operators densify metropolitan edge infrastructure to support autonomous vehicle coordination and industrial robotic control applications. The FCC's spectrum allocation timelines directly determine carrier procurement windows and vendor selection cycles. Verizon and AT&T deploy cloud RAN architectures across Chicago, Dallas, and Atlanta metropolitan clusters.
Germany
Smart manufacturing facilities drive concentrated demand for private 5G edge networks with guaranteed latency bounds. The EU Cybersecurity Act mandates baseline security certification for network equipment, accelerating vendor compliance investments. Siemens and BMW operate industrial automation clusters in Bavaria and Baden-Württemberg deploying real-time predictive maintenance workflows.
South Korea
SK Telecom and KT Corporation monetize ultra-low latency services through national edge cloud infrastructure spanning Seoul and Busan. The Ministry of Science and ICT enforces equipment certification standards that shape vendor eligibility for public tenders. Gaming and industrial robotic control services anchor demand in Seoul and Busan metropolitan clusters.
China
Domestic equipment manufacturers leverage vertical integration into baseband silicon and edge server manufacturing to capture infrastructure contracts. MIIT spectrum policies and GB standards shape deployment architectures and vendor qualification requirements. Huawei anchors cloud RAN deployments across Beijing, Shanghai, and Shenzhen technology corridors.
Japan
NTT Docomo and SoftBank migrate baseband processing to centralized edge data centers, reducing site-specific hardware requirements. METI industrial digitization programs subsidize private 5G deployments for manufacturing automation. Automotive manufacturers in Toyota City and Nagoya specify end-to-end latency guarantees in procurement contracts.
5G Edge Cloud Network and Services Market Competitive Environment
Capability concentration sits with telecommunications equipment specialists; scale advantage sits with hyperscale cloud providers. The vendor base separates into three tiers: integrated radio-compute platform vendors, cloud-native infrastructure providers, and systems integrators. Strategic archetypes include spectrum-captive operators monetizing latency guarantees, software-centric challengers disaggregating proprietary hardware stacks, and hyperscalers extending centralized cloud architectures toward network peripheries. Dominant competitive moves encompass M&A activity consolidating orchestration software capabilities and strategic partnerships pairing radio access expertise with enterprise cloud distribution.
Among Nordic telecommunications equipment vendors, Nokia Corporation and Ericsson occupy positions anchoring cloud RAN deployments across advanced industrial economies. Huawei Technologies Co., Ltd. represents the vertically integrated archetype controlling baseband silicon through captive supply chains. These three companies exemplify divergent strategic postures: multi-vendor openness versus integrated hardware-software stacks versus end-to-end manufacturing control.
| Leading Market Players |
|---|
| Nokia Corporation |
| Ericsson |
| Huawei Technologies Co., Ltd. |
| Cisco Systems, Inc. |
| Dell Technologies Inc. |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's edge server manufacturing clusters anchor global capacity for 5G baseband silicon and radio unit assembly, with volume concentration translating directly into vendor pricing leverage across procurement cycles. Korean and German operators face premium quotes when sourcing from these hubs due to EU Cybersecurity Act compliance costs and Ministry of Science and ICT certification requirements that filter supplier pools.
Pricing Analysis
Seoul-to-Dallas price spreads of twenty to thirty percent separate premium latency-guaranteed network slices from commoditized cloud RAN capacity. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service intensity, with German automotive manufacturers specifying penalty clauses for latency violations. Cost compression in the standard tier is intensifying because radio hardware commoditization erodes vendor margins. Telecommunications carriers exhibit highest price sensitivity due to capex cycle pressures, while defense and financial sectors accept premiums for on-premises sovereignty.
Supply Chain Analysis
Advanced baseband processor fabrication draws from Taiwan, South Korea, and USA foundry capacity, with 5nm and 7nm node availability constraining edge node deployment timelines. Radio frequency components, optical fronthaul transceivers, and precision timing modules constitute critical input dependencies. Single-source vulnerability in leading-edge silicon exposes operators to allocation rationing during demand surges. Distribution runs through systems integrators and direct carrier procurement teams, with European tenders increasingly requiring full material disclosure documentation under REACH and RoHS substance limits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G edge cloud market represents a high-growth disruption as millimeter-wave spectrum allocation and EU Cybersecurity Act enforcement simultaneously unlock deployment windows and filter vendor eligibility.
For Market Incumbents: Harden software orchestration capabilities against Open RAN disaggregation threats by acquiring Kubernetes-native network function startups and consolidating multi-vendor integration expertise. Prioritize EU Cybersecurity Act pre-certification investments to maintain eligibility for German industrial automation tenders. Capacity expansion in Seoul and Busan metropolitan clusters captures Korean operator refresh cycles. For New Entrants and Emerging Players: Build out cloud-native orchestration platforms targeting mid-sized European manufacturers seeking private 5G edge alternatives to carrier-managed solutions. Industrial predictive maintenance applications in Bavaria and Baden-Württemberg offer the most penetrable white space. Go-to-market through systems integrators already embedded in Siemens and BMW supply chains accelerates reference customer acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-as-utility play because latency-sensitive enterprise workloads will migrate toward guaranteed-quality network slices as default architecture. Target acquisition profiles emphasize software-centric challengers with containerized network function deployment expertise. The signal to watch is FCC millimeter-wave auction participation rates as inflection indicator for carrier capex commitment.| Strategic Initiative | Industry Significance |
|---|---|
| NFV-SDN Platform Integration | Virtualized orchestration layers enable rapid service instantiation without hardware swaps across Seoul deployments. |
| Multi-Access Edge Computing Commercialization | KT Corporation monetizes distributed compute nodes for industrial robotic control in Busan metropolitan clusters. |
| EU Cybersecurity Act Certification Investment | Baseline security standards filter vendor pools and accelerate compliant edge infrastructure procurement across member states. |
| Open RAN Systems Integration Partnership | Disaggregated radio hardware from baseband software enables multi-vendor deployments shifting advantage toward integrators. |
| Cloud RAN Capacity Expansion | Centralized baseband processing over fronthaul fiber reduces site-specific hardware requirements by half in dense urban coverage. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with telecommunications carrier network planning executives, equipment vendor product managers, enterprise IT procurement officers, and systems integration specialists. Secondary validation drew from FCC spectrum auction records, EU Cybersecurity Act implementation guidance, Ministry of Science and ICT certification databases, and SEC filings of publicly traded infrastructure vendors. Bottom-up deployment forecasts were triangulated against top-down capex projections from national carrier guidance.
Calibration against historical 4G RAN rollout patterns and 5G millimeter-wave deployment trajectories informed the analytical framework across the analysis window. Segmentation dimensions modeled encompass service type, technology stack, end-user vertical, and deployment architecture. CAGRs were derived from volume-weighted average growth trajectories with adjustments for spectrum allocation timelines and regulatory certification delays. Fronthaul fiber density constraints and baseband processor foundry capacity served as industry-specific forecast inputs.
Stress conditions across energy cost volatility, optical transport capacity limits, and baseband silicon supply rationing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization and carrier consolidation patterns. Cross-checking against national spectrum auction participation rates and equipment vendor order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Poland Data Center Networking Market