
 Global Subscriber Data Management Market | 2026-2036
Global Subscriber Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Subscriber Data Management Market Outlook
North American telecom infrastructure spending is broadening the addressable base for subscriber data platforms. Hewlett Packard Enterprise leverages its edge-to-cloud portfolio to anchor large-scale deployments for carriers modernizing core networks. Oracle Corporation sustains deep integration between its subscriber databases and billing systems, a combination that dominates North American operator procurement cycles. Nokia Corporation competes through telco-specialized cloud-native software stacks that extend its traditional equipment relationships into recurring software revenue streams.
Subscriber Data Management encompasses the systems, protocols, and software architectures that consolidate, authenticate, and govern subscriber identity, service entitlement, and usage records across fixed and mobile networks. These platforms typically operate at sub-50 millisecond latency thresholds for authentication queries to ensure seamless handover and service continuity during peak traffic loads. Cloud-based deployment models are capturing the fastest expansion as operators migrate away from capital-intensive on-premises subscriber databases toward elastic infrastructure. Real-time solutions command concentrated R&D investment because 5G standalone core networks require instantaneous subscriber state synchronization across distributed network functions, while legacy systems retain residual revenue in emerging markets with slower modernization timelines.
The Federal Communications Commission shapes US market access through network reliability mandates and data breach notification requirements that elevate platform resilience standards. The European Union's GDPR and the EU AI Act impose cross-border data flow restrictions and automated decision-making transparency obligations that directly influence subscriber data architecture design. Stakeholders must monitor how divergent data localization regimes between the United States, European Union, and China reshape vendor qualification criteria and deployment topology decisions.
Market Dynamics
5G standalone core deployment is compressing subscriber data synchronization windows to sub-10 milliseconds, forcing operators to rebuild authentication architectures around stateless, geo-distributed functions rather than centralized legacy databases.
Growth Catalysts
- GDPR Article 44 cross-border transfer mechanisms:European operators are redesigning subscriber data topology to maintain EU data residency, triggering platform replacement cycles.
- Network slicing for enterprise IoT:Manufacturing and automotive verticals require isolated subscriber profiles with guaranteed quality-of-service parameters.
- India's Digital Personal Data Protection Act:Localization mandates are accelerating data center buildouts and indigenous platform procurement by Reliance Jio and Bharti Airtel.
Market Restraints
- Specialized engineering talent scarcity:Cloud-native subscriber data architects command premium compensation, constraining vendor scaling.
- Silicon supply concentration:Taiwan Semiconductor Manufacturing Company dominates high-performance networking chip fabrication for data plane acceleration.
- Interoperability friction with 3G/4G cores:Dual-mode operation requires maintaining parallel subscriber state databases, duplicating infrastructure overhead.
Strategic Opportunities
- Brazil's delayed 5G standalone migration:Legacy subscriber data platforms retain extended revenue lifecycles as operators phase modernization over 2027-2032.
- Edge subscriber data caching:Multi-access edge computing nodes are absorbing authentication functions previously centralized in regional data centers.
- Japan's METI data free flow with trust initiative:Cross-certification frameworks enable Japanese operators to export subscriber data platform configurations to Southeast Asian markets.
Industry Challenges
- Stateful container orchestration complexity:Kubernetes patterns optimized for stateless microservices fail at subscriber session persistence requirements.
- 3GPP specification version fragmentation:Operators deploy Release 16, 17, and 18 network functions simultaneously, multiplying data model translation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Subscriber Data Management Market |
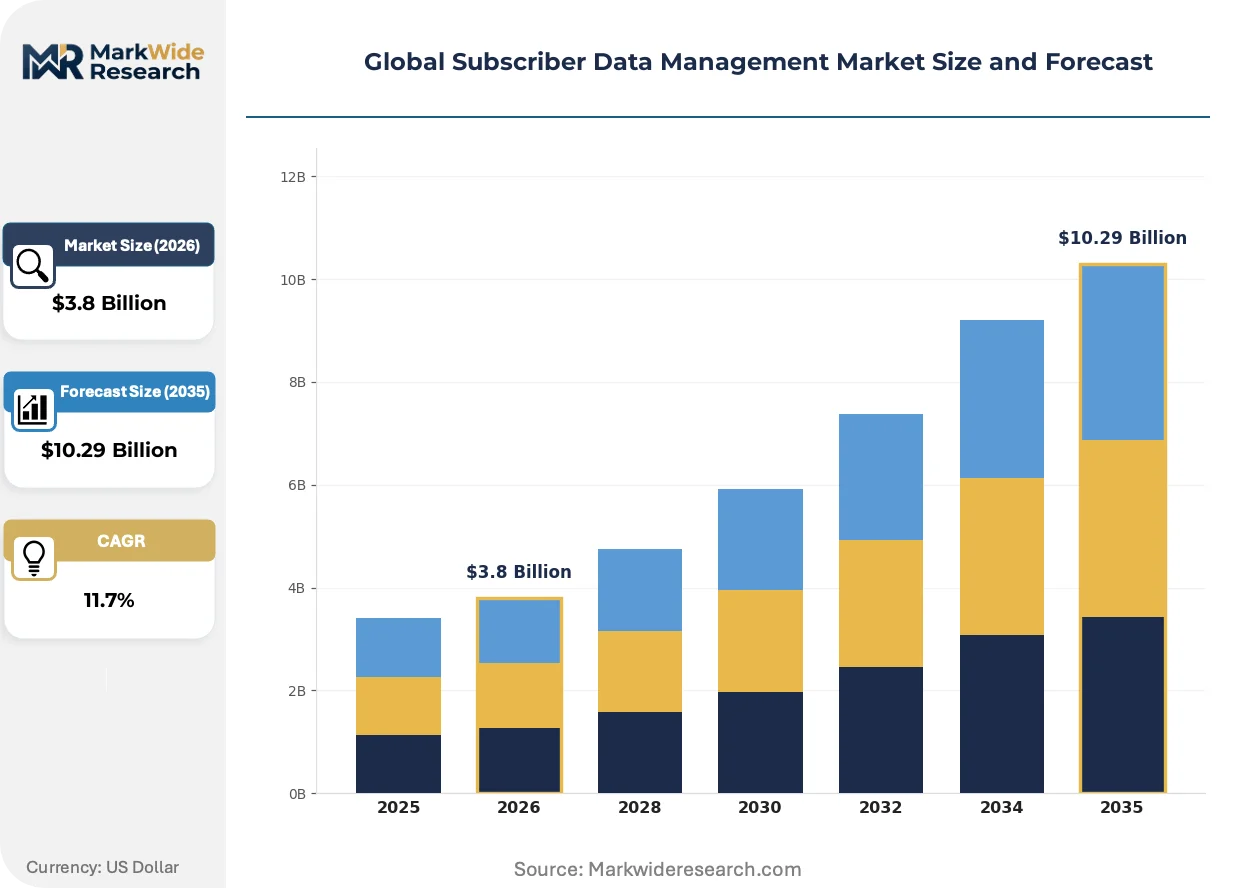
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Collection, Data Integration, Data Analytics, Data Governance Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Telecommunications, Retail, Financial Services, Healthcare Solution Type: Centralized Solutions, Distributed Solutions, Real-Time Solutions, Legacy Systems |
| Companies Covered | Hewlett Packard Enterprise, Oracle Corporation, Telefonaktiebolaget LM Ericsson, ZTE Corporation, Amdocs Limited, Nokia Corporation, Cisco Systems, Optiva Inc., Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Subscriber Data Management Market Strategic Shifts
Subscriber data platforms are transitioning from record-keeping systems to real-time decision engines that mediate service entitlement, network resource allocation, and privacy enforcement simultaneously.
Cloud-native subscriber data repositories built on Cassandra and ScyllaDB architectures are absorbing authentication query loads previously handled by proprietary hardware appliances. Tier-one carriers in Germany and South Korea have completed production migrations, compressing total cost of ownership curves and eliminating appliance refresh cycles. The technology is absorbing capital previously allocated to dedicated signaling transfer points.
The EU AI Act's automated decision-making transparency requirements are compelling operators to maintain explainable audit trails for subscriber profile modifications and service denials. European operators must deploy consent management layers with machine-readable logic disclosure. The regulation most affects predictive churn and fraud scoring algorithms deployed by French and Italian carriers.
Enterprise self-service portals are displacing traditional ticketing systems for subscriber data access requests and profile corrections. Manufacturing and logistics buyers in the United States now expect API-driven subscriber identity provisioning without operator intermediation. This pattern is most visible in Detroit automotive supply chain deployments where private 5G networks require instantaneous subscriber onboarding.
Global Subscriber Data Management Market Segmentation
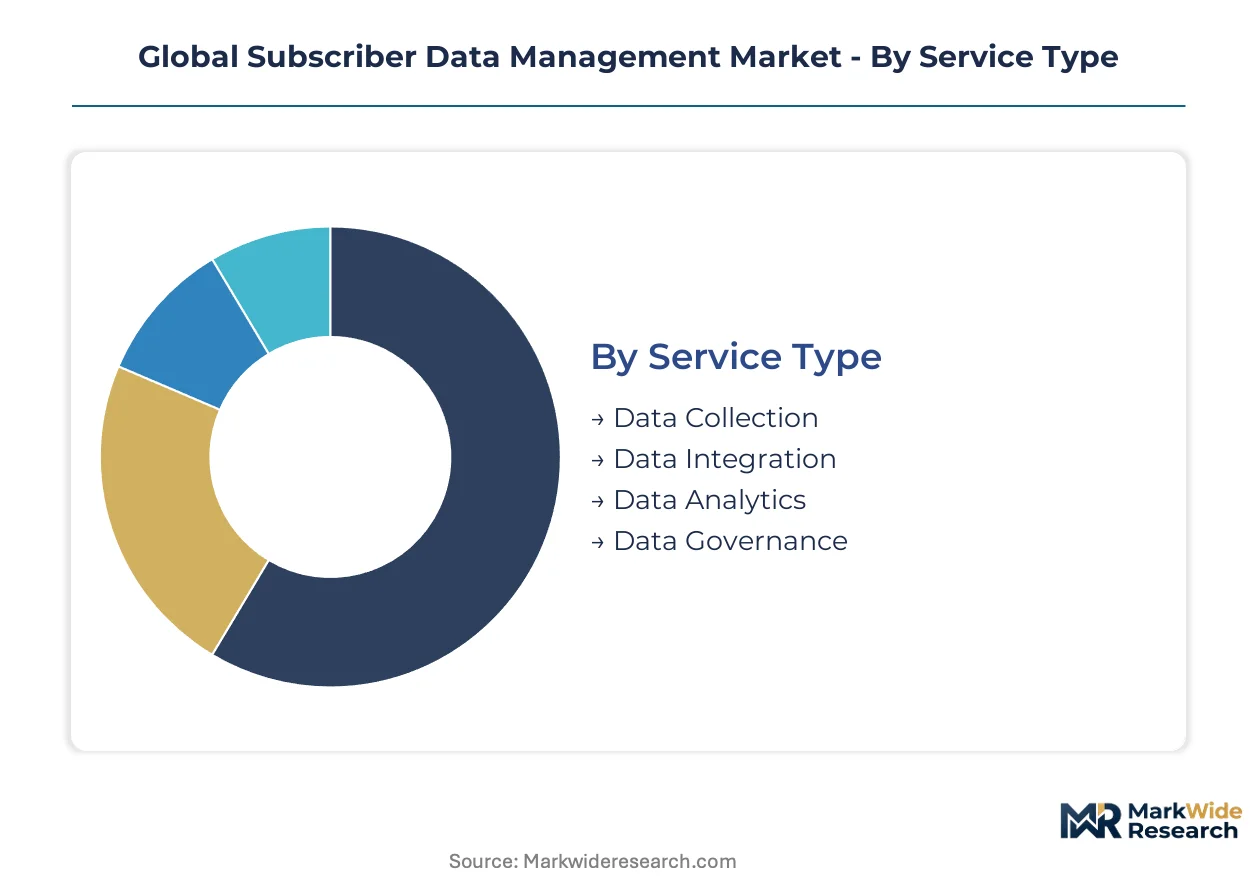
Subscriber data management platforms fragment across service architectures, infrastructure models, and operational contexts. Understanding where each segment integrates into standalone versus embedded deployments clarifies procurement patterns and vendor positioning.
Service Type:
Standalone data services operate independently of core network functions, while embedded modules integrate directly into billing and policy engines.
- Data Collection:Ingestion pipelines capture subscriber identity, location, and usage events from network probes and OSS/BSS interfaces. German and South Korean carriers deploy these as discrete layers above their 5G standalone cores, driven by real-time streaming requirements for network slicing.
- Data Integration:Master data management harmonizes subscriber records across CRM, billing, and network inventory systems. United States tier-one operators concentrate procurement here as they consolidate legacy databases into unified fabrics, constrained by the complexity of maintaining parallel 3G/4G state during migration.
- Data Analytics:Predictive models for churn and fraud scoring require explainable audit trails under EU AI Act transparency mandates.
- Data Governance:Consent management and retention policy enforcement address GDPR Article 44 cross-border transfer restrictions.
Volume placements concentrate in Data Integration; the faster expansion belongs to Data Analytics.
Deployment Model:
Cost tiering separates capital-intensive owned infrastructure from operational expenditure models with elastic scaling.
- Cloud-Based:Containerized subscriber data functions deploy across AWS, Azure, and Google Cloud regions with automated failover. European operators favor this model to satisfy data residency requirements through EU-sovereign cloud zones, though latency to distributed 5G core functions remains a design constraint.
- On-Premises:Dedicated hardware appliances in carrier-owned data centers maintain sub-10 millisecond synchronization for authentication state. Indian operators Reliance Jio and Bharti Airtel expand these deployments to comply with Digital Personal Data Protection Act localization mandates.
- Hybrid:Sensitive subscriber profiles remain on-premises while analytics workloads burst to public cloud.
- Edge Computing:Multi-access edge computing nodes cache authentication functions previously centralized in regional facilities.
Revenue concentrates in Cloud-Based deployments; steepest expansion trajectory belongs to Edge Computing.
End User:
Customer type determines latency thresholds, regulatory exposure, and integration complexity with existing enterprise systems.
- Telecommunications:Mobile network operators consume the majority of subscriber data platform capacity, with 5G standalone cores demanding stateless, geo-distributed architectures. United States FCC reliability mandates and breach notification requirements elevate resilience standards for this segment.
- Retail:Loyalty program operators and omnichannel commerce platforms deploy subscriber identity management for personalized engagement. GDPR consent layers and automated decision transparency obligations shape European retail procurement specifications.
- Financial Services:Know-your-customer and transaction monitoring systems integrate subscriber identity verification for mobile banking.
- Healthcare:HIPAA-covered entities in the United States apply subscriber data platforms to patient identity matching and care coordination.
Investment intensity peaks in Telecommunications; regulatory complexity drives fastest uptake in Financial Services.
Solution Type:
Maturity and migration status separate greenfield cloud-native deployments from maintained legacy estates.
- Centralized Solutions:Single-database architectures consolidate subscriber state in regional data centers, simplifying backup and compliance reporting. Brazilian operators retain these platforms through extended 5G standalone migration timelines.
- Distributed Solutions:Geo-replicated databases synchronize subscriber state across multiple availability zones with conflict-free replicated data types. Japanese carriers under METI data free flow with trust initiative export these configurations to Southeast Asian markets.
- Real-Time Solutions:In-memory data grids process authentication queries at sub-50 millisecond thresholds for seamless handover.
- Legacy Systems:Proprietary hardware appliances from previous-generation network cores persist in emerging markets with slower modernization cycles.
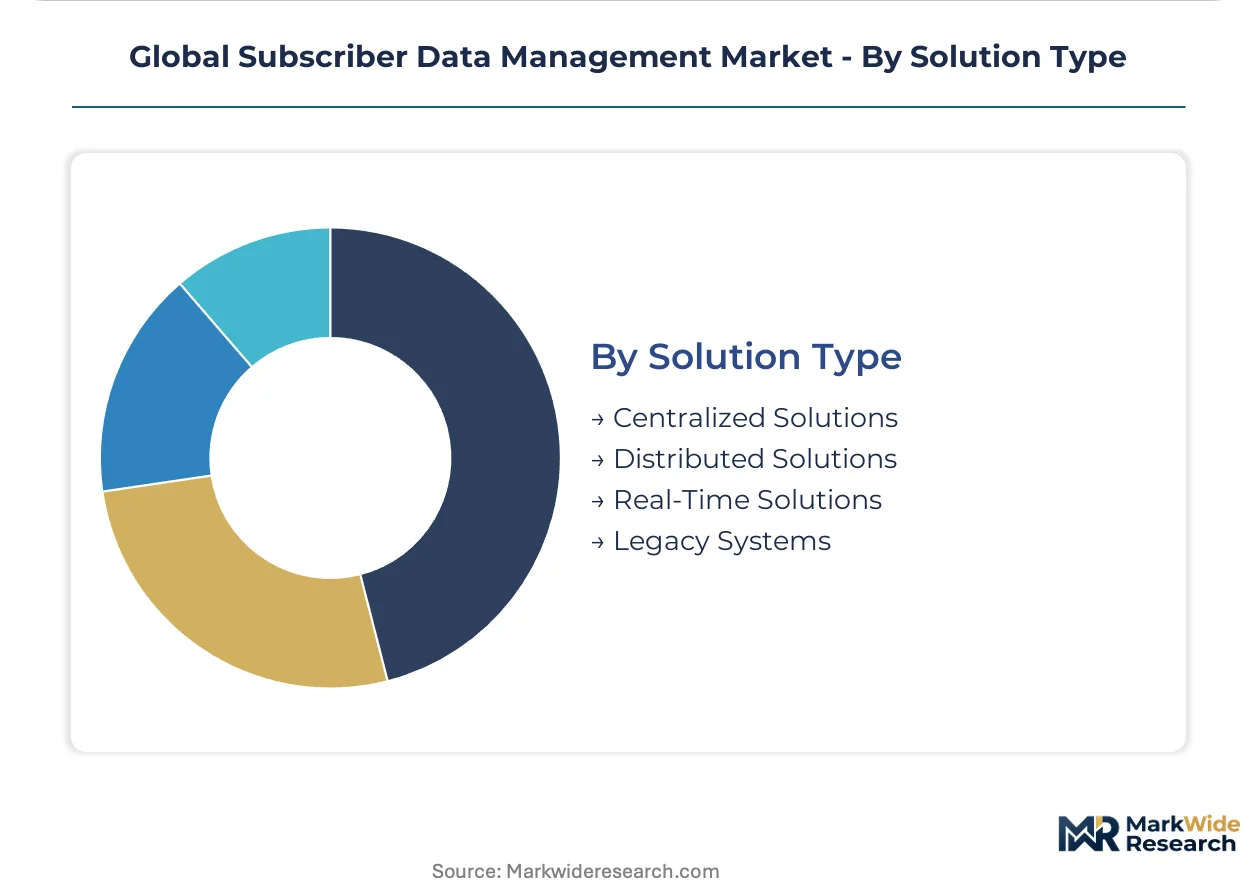
Installed base concentrates in Centralized Solutions; technology transition favors Real-Time Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure concentration anchors North American subscriber data platform development, while European data sovereignty requirements and Asian 5G deployment timelines reshape regional procurement patterns.
United States
Tier-one carriers consolidate legacy subscriber databases into unified data fabrics, driven by FCC network reliability mandates and breach notification requirements. The Federal Communications Commission elevates platform resilience standards through enforceable cybersecurity frameworks. Dallas-Fort Worth metroplex hosts major carrier data center clusters where edge subscriber data caching architectures are absorbing authentication functions from regional facilities.
Germany
Deutsche Telekom and Vodafone Deutschland complete production migrations to cloud-native subscriber data repositories, eliminating proprietary hardware refresh cycles. GDPR Article 44 cross-border transfer mechanisms force topology redesigns to maintain EU data residency. Munich and Berlin anchor the country's telco software development corridor, where explainable audit trail systems address EU AI Act automated decision transparency obligations.
India
Reliance Jio and Bharti Airtel expand on-premises deployments to comply with Digital Personal Data Protection Act localization mandates. The Telecom Regulatory Authority of India shapes infrastructure buildout timelines through spectrum allocation and interconnection regulations. Mumbai and Bangalore concentrate indigenous platform procurement activity, with data center construction accelerating to meet subscriber state synchronization requirements for 5G standalone cores.
Japan
NTT Docomo and KDDI export distributed subscriber data configurations to Southeast Asian markets under METI data free flow with trust initiative cross-certification frameworks. The Ministry of Economy, Trade and Industry enables regional technology transfer through standardized trust protocols. Tokyo-Osaka corridor hosts production deployments of geo-replicated databases with conflict-free replicated data types, synchronizing subscriber state across multiple availability zones.
Brazil
Legacy subscriber data platforms retain extended revenue lifecycles as operators phase 5G standalone modernization over 2027-2032. ANATEL spectrum auctions and infrastructure sharing rules delay core network replacement timelines. São Paulo anchors Latin America's largest telco equipment market, where centralized single-database architectures persist due to capital constraint and extended depreciation schedules on existing infrastructure.
Global Subscriber Data Management Market Competitive Environment
Global majors compete with regional champions across deployment scale and regulatory specialization, producing a tiered structure where cloud-native specialists challenge legacy equipment vendors. The vendor base separates into three strategic archetypes: telecom-originated equipment providers extending into software, enterprise IT vendors repurposing cloud portfolios for carrier workloads, and pure-play subscriber data specialists. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent policy control functions.
Within the telecom-originated tier, Nokia Corporation and Ericsson exemplify equipment-to-software transition strategies, occupying positions where traditional network relationships convert to recurring software revenue streams. Oracle Corporation and Hewlett Packard Enterprise represent enterprise IT vendor archetypes, with Oracle sustaining deep integration positioning between subscriber databases and billing systems while HPE leverages edge-to-cloud portfolio breadth for large-scale carrier modernizations. ZTE Corporation and Huawei Technologies anchor China-based vendor participation, though geopolitical qualification constraints limit addressable markets.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Oracle Corporation |
| Telefonaktiebolaget LM Ericsson |
| ZTE Corporation |
| Amdocs Limited |
| Nokia Corporation |
| Cisco Systems |
| Optiva Inc. |
| Huawei Technologies |
| Others |
Value Chain & Pricing Dynamics
Cloud-native containerization of subscriber data functions is compressing total cost of ownership curves while redistributing value capture toward software engineering talent pools in Germany, South Korea, and the United States. This architectural transition simultaneously eliminates proprietary hardware refresh cycles and elevates pricing power for vendors with proven stateless microservices deployments.
Pricing Analysis
Warranty and service bundling separates premium vendor tiers, with 24/7 sub-10 millisecond latency guarantees commanding substantial premiums over standard support packages. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth under GDPR Article 44 and EU AI Act compliance frameworks. Pricing pressure stems from hyperscaler cloud alternatives entering carrier procurement cycles, particularly AWS and Azure sovereign cloud zones. Tier-one telecommunications operators in North America exhibit lowest price sensitivity due to FCC-mandated reliability requirements, while emerging market carriers in Brazil and India face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements now pervade carrier procurement, with European operators mandating qualified secondary vendors for all subscriber data platform components to mitigate geopolitical qualification risks. Supply concentrates in Taiwan for high-performance networking chip fabrication, the United States for cloud-native software development, and India for indigenous platform engineering. Raw material dependencies include advanced silicon wafers, specialized memory modules, and precision timing components. Single-source vulnerability around Taiwan Semiconductor Manufacturing Company fabrication capacity represents the dominant structural risk. Distribution runs through direct vendor-to-carrier enterprise sales channels with systems integrator intermediation for complex multi-vendor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where GDPR Article 44 and the EU AI Act erect formidable barrier-to-entry moats, privileging vendors with established data residency architectures and explainable audit trail capabilities.
For Market Incumbents: Anchor defensive positioning through backward integration into edge computing infrastructure, capturing authentication caching functions that hyperscalers threaten to commoditize. Consolidate around unified data fabric deployments that absorb competitor point solutions during United States tier-one carrier modernization cycles. Threat substitution from cloud-native challengers demands certification investment in EU sovereign cloud qualifications.
For New Entrants and Emerging Players: Begin with Brazil's extended 5G standalone migration timeline, where legacy platform replacement cycles stretch through 2032 and incumbent attention concentrates elsewhere. Target manufacturing and automotive verticals deploying private 5G networks with API-driven subscriber identity provisioning requirements. Go-to-market leverage rests on enterprise self-service portal specialization displacing traditional operator ticketing systems.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native specialists possessing proven Cassandra and ScyllaDB production migrations given carrier capex rotation toward elastic infrastructure. Long-term viability over the next decade hinges on recurring software revenue conversion from equipment-originated vendors. Acquisition target archetype: telco-specialized software firms with METI cross-certification enabling Japanese-to-Southeast Asian technology transfer. Signal to watch: Indian Digital Personal Data Protection Act enforcement intensity accelerating indigenous platform procurement beyond current trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Deutsche Telekom and Vodafone Deutschland eliminated hardware refresh cycles through Cassandra-based subscriber data repositories. |
| Edge Computing Infrastructure Partnership | Dallas-Fort Worth carrier clusters absorb authentication functions from regional data centers into distributed MEC nodes. |
| Regulatory Compliance Certification | EU AI Act explainable audit trail requirements reshape French and Italian carrier algorithm procurement specifications. |
| Geographic Market Expansion | NTT Docomo exports geo-replicated database configurations to Southeast Asian markets under METI trust frameworks. |
| Vertical Integration into Silicon | Reliance Jio and Bharti Airtel build captive data center capacity to satisfy Digital Personal Data Protection Act localization mandates. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with network architects at tier-one carriers, procurement officers at European telecommunications operators, compliance leads navigating GDPR Article 44 implementations, and software engineering directors at cloud-native platform vendors. FCC enforcement actions, EU AI Act draft guidance documents, and TRAI spectrum allocation records provided regulatory trajectory validation. Bottom-up carrier deployment tracking and top-down infrastructure spending analysis were triangulated against vendor revenue disclosures.
Data-stream reconciliation across deployment model, service architecture, solution maturity, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived through logarithmic trend fitting across the projection horizon, with 5G standalone core deployment timelines, data localization mandate enforcement intensity, and cloud migration capex rotation serving as primary forecast inputs. Segmentation modeling incorporated network function virtualization penetration rates and edge computing node deployment trajectories as cross-cutting variables.
Underlying measurement precision varies by segment; cloud-based deployment models carry tighter precision than emerging edge computing configurations due to established vendor reporting patterns. Forecasts reflect assumptions around 3GPP specification convergence timelines and sovereign cloud zone certification velocity. Deviation in India's Digital Personal Data Protection Act enforcement intensity or Taiwan semiconductor supply continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
New Zealand Data Center Networking Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Enterprise Server Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Software Defined Video Networking Market