
 Network Connectivity Tester Market | 2026-2036
Network Connectivity Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Network Connectivity Tester Market Outlook
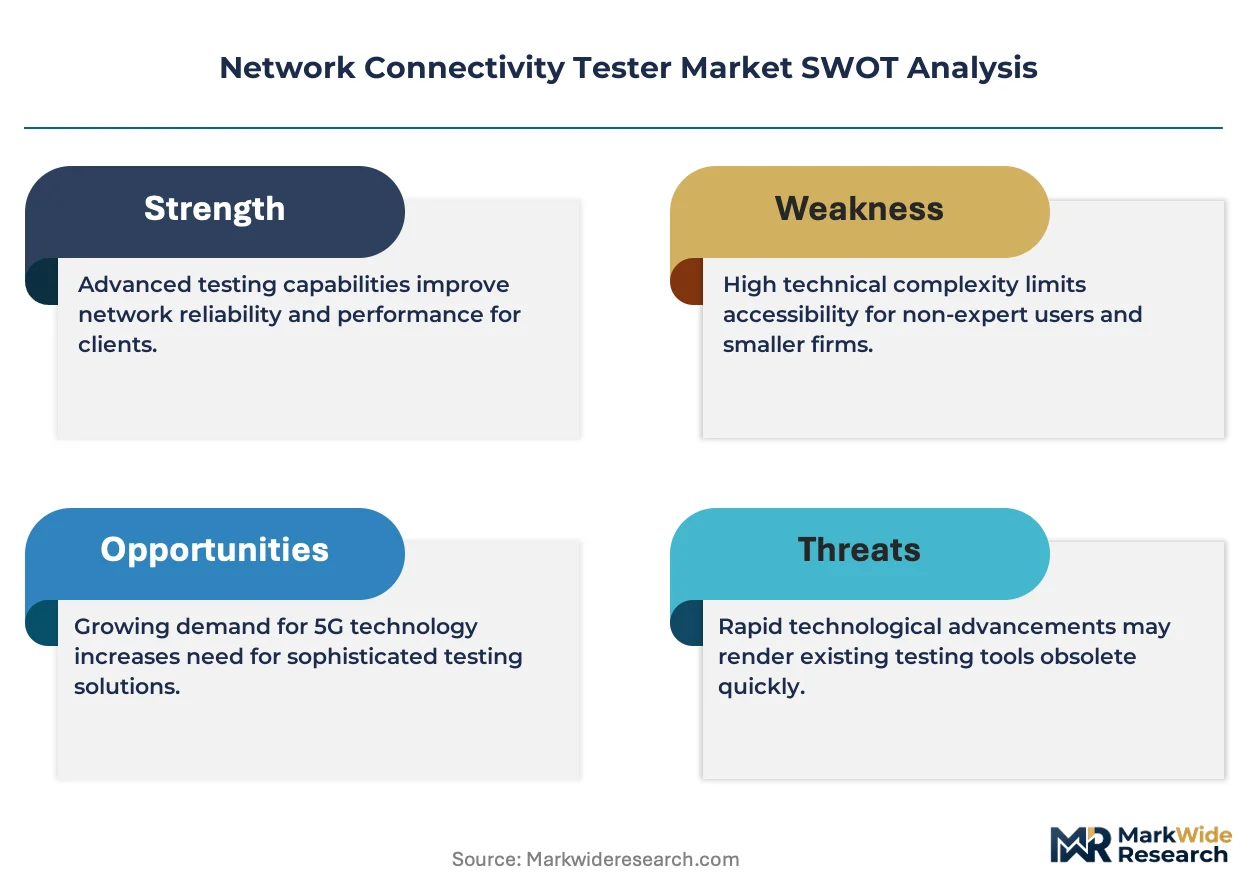
Data center infrastructure expansion is recalibrating procurement priorities across the Network Connectivity Tester Market. Fluke Networks dominates the cable certification segment with deep channel control in North American distribution. Keysight Technologies leverages its R&D intensity to anchor the high-speed Ethernet and optical test portfolio. VIAVI Solutions specializes in protocol analysis for service provider labs and field deployment teams.
A network connectivity tester is a portable or rack-mounted instrument that validates physical layer integrity, measures signal parameters such as insertion loss and return loss, and verifies protocol conformance across copper and fiber media. Its primary commercial purpose is to reduce mean time to repair and prevent costly network downtime in mission-critical environments. Cable testers and optical testers command the largest revenue pools today, while protocol analyzers represent the fastest-expanding margin segment as 400G and 800G deployments multiply. Enterprise networking applications sustain the broadest installed base, though data center verticals are displacing telecommunications as the primary growth vector for new unit demand.
The FCC enforces equipment authorization standards that shape product access for US-manufactured and imported testers, while the EU AI Act and CE marking requirements under the Radio Equipment Directive govern European market entry. Japan's METI sets technical conformity benchmarks for telecommunications instruments that influence regional product specifications. Stakeholders must monitor how evolving 800G standards and national broadband subsidy programs reshape certification requirements and procurement cycles.
Market Dynamics
The Network Connectivity Tester Market pivots on hyperscale data center buildouts for AI training clusters, which demand fiber qualification tools capable of certifying 800G optical links under extreme density constraints.
Growth Catalysts
- AI Infrastructure Scaling:Hyperscale operators in the United States and China are procuring fiber certification equipment to validate coherent optical links supporting machine learning workloads. This demand concentrates in facilities exceeding 100 megawatts of compute capacity.
- FCC Broadband Labeling Mandate:The Federal Communications Commission's transparency rules require ISPs to disclose actual versus advertised speeds, compelling enterprises to acquire validated test equipment for compliance documentation.
- 5G Backhaul Deployment:Mobile operators across Germany and Japan are installing millimeter-wave and sub-6 GHz infrastructure, driving field teams to adopt portable optical time-domain reflectometers for fiber-to-the-antenna verification.
Market Restraints
- Semiconductor Component Concentration:Specialized analog-to-digital converters and high-speed FPGAs for 400G+ test heads depend on fabrication facilities concentrated in Taiwan and South Korea, creating supply vulnerability.
- Calibration Infrastructure Costs:Maintaining traceability to national metrology institutes requires recurring capital outlays for reference standards that smaller service providers struggle to absorb.
- Optical Module Standard Fragmentation:The proliferation of form factors—QSFP-DD, OSFP, CPO—forces test vendors to engineer multiple adapter configurations, elevating non-recurring engineering expenses.
Strategic Opportunities
- India Data Center Buildout:The country's national electronics policy incentives and cloud sovereignty requirements are attracting hyperscale investment, creating demand for localized certification services and equipment partnerships.
- Co-Packaged Optics Integration:Convergence of silicon photonics with switch ASICs is expanding into new test scenarios requiring electrical-optical co-verification at the package level.
- Cloud-Managed Test Assets:Channel partners are deploying subscription-based fleet management platforms that enable enterprise customers to access calibrated equipment without capital ownership.
Industry Challenges
- Multi-Gigabit Protocol Expertise Gap:Field technicians lack training in PAM4 signaling analysis and forward error correction diagnostics required for 400G/800G troubleshooting.
- Legacy Copper Infrastructure Interoperability:Enterprises maintaining Category 6A plant alongside fiber upgrades require testers that seamlessly bridge both media without workflow fragmentation.
- Certification Timeline Compression:IEEE 802.3 standards for next-generation Ethernet are finalizing faster than test equipment vendors can complete compliance validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Connectivity Tester Market |
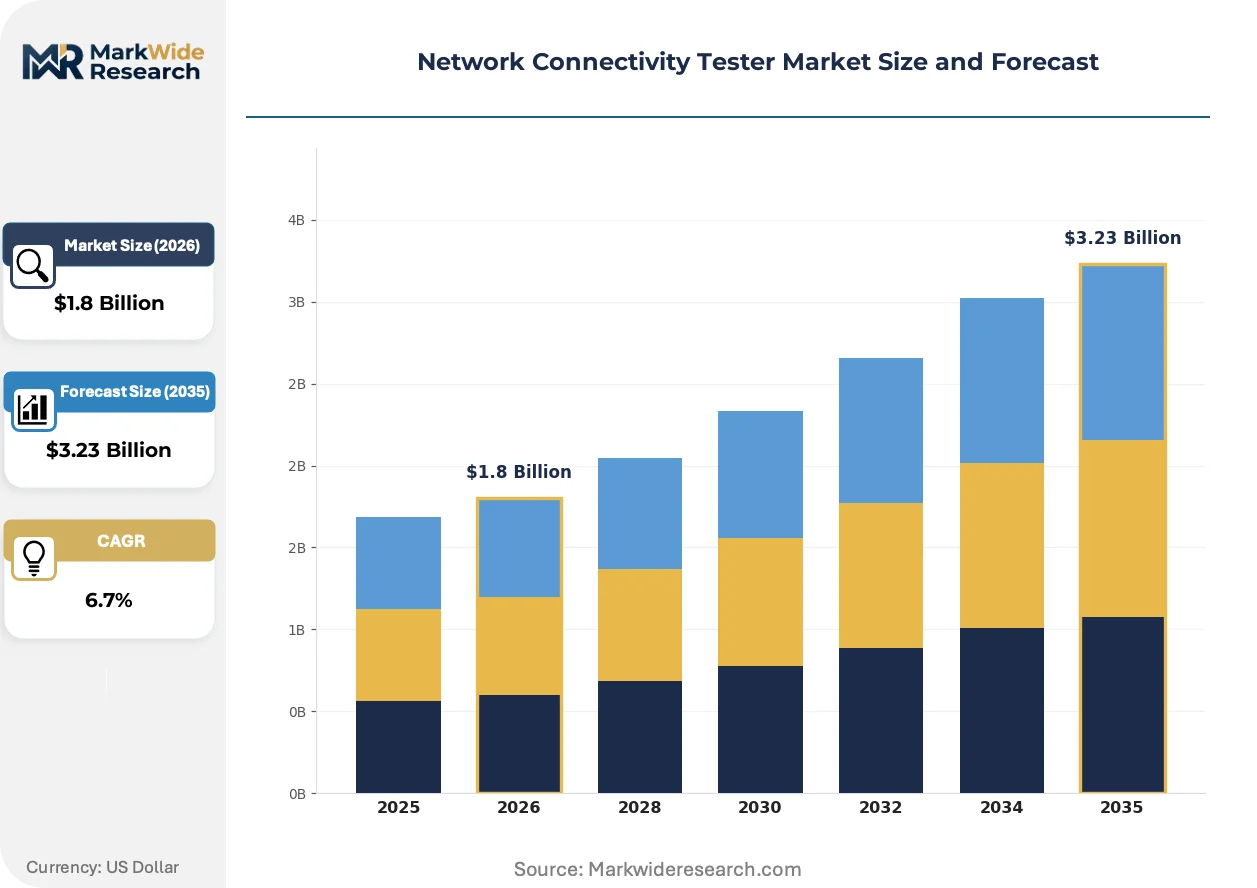
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Testers, Network Analyzers, Protocol Analyzers, Optical Testers Application: Enterprise Networking, Telecommunications, Data Centers, Industrial Automation End User: IT Departments, Government Agencies, Educational Institutions, Managed Service Providers Technology: Ethernet, Wi-Fi, LTE, MPLS |
| Companies Covered | Fluke Networks, Keysight Technologies, VIAVI Solutions, EXFO Inc., NetScout Systems, Anritsu Corporation, Spirent Communications, VeEX Inc., Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Connectivity Tester Market Strategic Shifts
Test equipment architecture is converging around software-defined measurement engines that decouple hardware acquisition from analytics processing, enabling faster adaptation to evolving physical layer standards.
Automated fiber inspection systems with machine-vision defect classification are expanding into data center deployment workflows. Colocation operators in Northern Virginia and Frankfurt are adopting these tools to eliminate human variability in connector cleanliness verification. The technology is compressing mean time to certify from hours to minutes per fiber pair.
Japan's METI technical conformity benchmarks for telecommunications instruments are tightening electromagnetic compatibility requirements for field-deployable testers. Manufacturers serving the Japanese market are redesigning shielding architectures and documentation packages to satisfy pre-market approval timelines. This regulatory friction is elevating compliance costs for entrants lacking established local certification partnerships.
Enterprise buyers are consolidating test equipment procurement through managed service contracts rather than capital purchase. Large financial services firms in London and Singapore are outsourcing fiber certification to specialized contractors who maintain calibrated asset pools. This behavior concentrates demand among channel partners with logistics networks capable of same-day equipment dispatch.
Network Connectivity Tester Market Segmentation
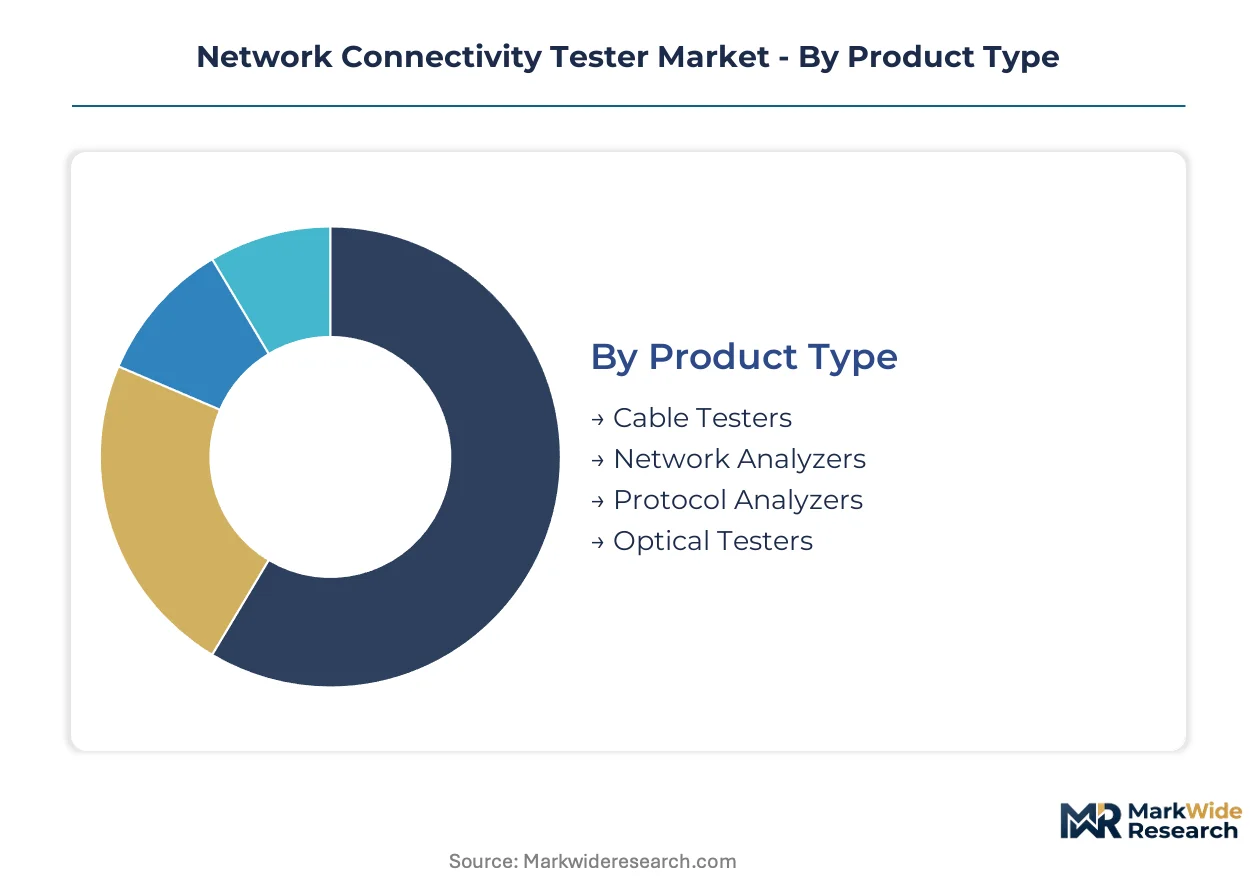
Network connectivity testers serve divergent operational requirements across physical layer verification, protocol conformance, and spectrum analysis. Segmentation reveals how procurement patterns split between capital-intensive certification equipment and portable troubleshooting tools.
Product Type:
Standardization dominates cable and optical testers where IEEE and IEC specifications dictate measurement algorithms, while protocol analyzers demand extensive customization for proprietary network stacks.
- Cable Testers:Instruments validate copper infrastructure integrity through insertion loss, return loss, and crosstalk measurements per TIA-568 standards. Data center buildouts in Northern Virginia and Frankfurt concentrate demand for Category 8 certification capability amid 25G/40G BASE-T deployment.
- Optical Testers:Fiber qualification equipment includes OTDRs, power meters, and inspection microscopes for single-mode and multimode plant. Hyperscale operators in the United States and China are procuring these tools to certify 800G coherent links in AI training clusters.
- Network Analyzers:Vector and scalar instruments characterize RF component behavior across frequency sweeps.
- Protocol Analyzers:Deep-packet inspection systems decode Ethernet, Fibre Channel, and InfiniBand traffic for conformance testing.
Leading the category by volume: Cable Testers. Growing fastest: Optical Testers.
Application:
Cost tier separation distinguishes enterprise networking's broad installed base from data centers' concentrated high-value procurement.
- Data Centers:Facilities exceeding 100 megawatts of compute capacity require automated fiber inspection and 400G/800G validation suites. FCC broadband labeling rules and similar transparency mandates in Germany and Japan are pushing colocation operators toward standards-compliant test documentation.
- Enterprise Networking:Distributed IT organizations maintain hybrid copper-fiber plant across campus and branch locations. Financial services firms in London and Singapore are outsourcing certification to managed service providers with calibrated asset pools.
- Telecommunications:Mobile operators deploy portable OTDRs for fiber-to-the-antenna verification in 5G backhaul buildouts.
- Industrial Automation:Manufacturing environments apply ruggedized testers for PROFINET and EtherCAT network validation.
Highest margin concentration: Data Centers. Broadest unit deployment: Enterprise Networking.
End User:
Customer type fragmentation separates self-sufficient IT departments from outsourced procurement through channel partners.
- Managed Service Providers:Specialized contractors maintain geographically distributed equipment fleets with cloud-managed calibration tracking. Same-day dispatch capabilities in metropolitan markets are winning procurement consolidation from large enterprises.
- IT Departments:Internal technical staff operate captive test assets for routine maintenance and troubleshooting. Semiconductor component concentration in Taiwan and South Korea creates supply vulnerability for organizations dependent on 400G+ test head procurement.
- Government Agencies:Public sector buyers prioritize traceability to national metrology institutes.
- Educational Institutions:Universities and technical colleges acquire entry-level certification equipment for workforce training programs.
Fastest procurement expansion: Managed Service Providers. Largest installed base maintenance: IT Departments.
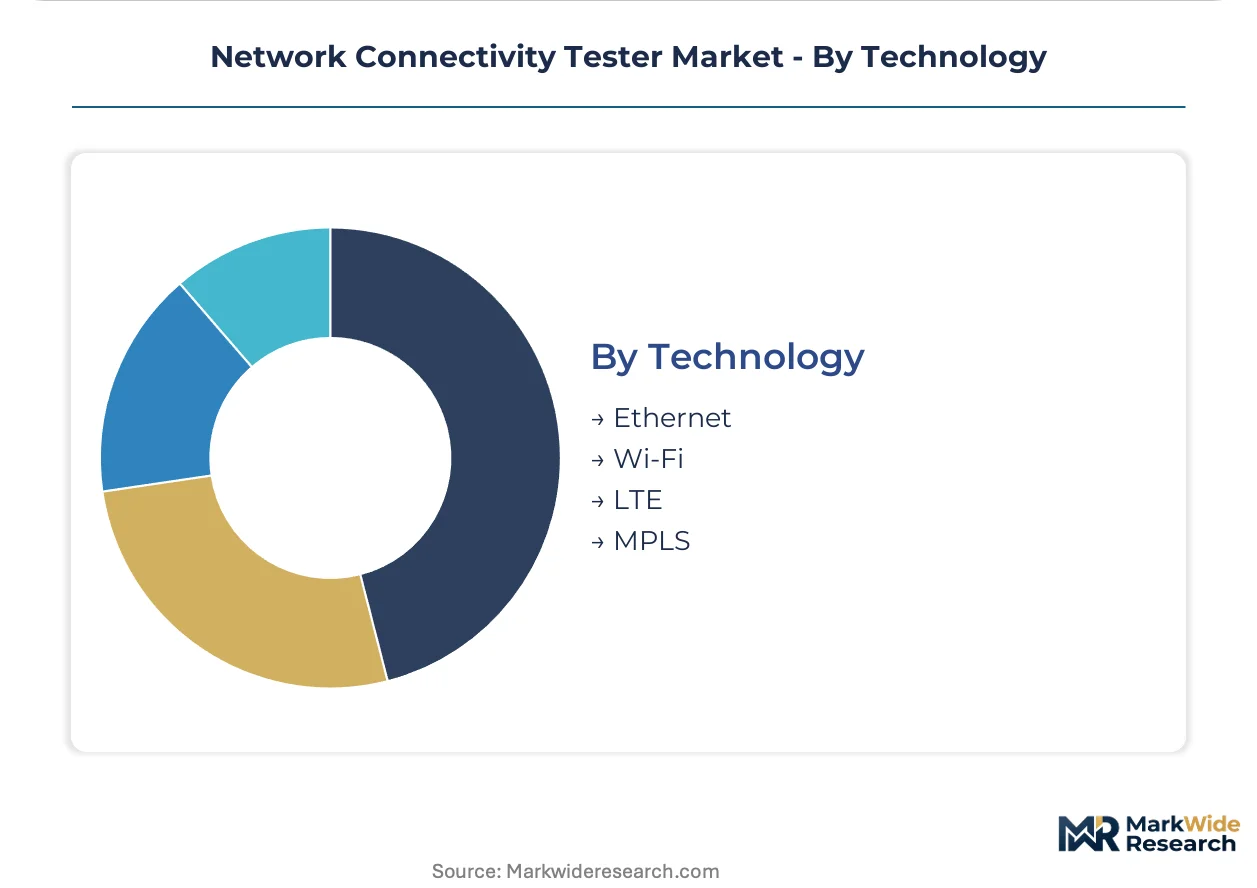
Technology:
Maturity gradient spans from established Ethernet certification to emerging LTE and MPLS test requirements.
- Ethernet:Dominant protocol spanning 10M to 800G with PAM4 signaling analysis requirements. IEEE 802.3 standards finalization timelines are compressing faster than test equipment vendors can complete compliance validation cycles.
- Wi-Fi:Wi-Fi 6E and Wi-Fi 7 spectrum analysis drives demand for 6 GHz band validation tools. Enterprise campus upgrades in Germany and Japan concentrate procurement for throughput and interference testing.
- LTE:Private cellular network deployments require drive-test and optimization equipment.
- MPLS:Service provider core networks sustain demand for label-switching path verification.
Deepest standardization: Ethernet. Steepest capability expansion: Wi-Fi.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Northern Virginia, Frankfurt, and Singapore concentrate hyperscale data center construction where fiber certification demand is accelerating fastest. Tax incentives and streamlined permitting in these zones are pulling procurement budgets away from traditional telecommunications hubs. This geographic recalibration is reshaping where test equipment vendors deploy technical sales resources.
United States
Hyperscale operators in Northern Virginia's Data Center Alley are procuring 800G optical test suites for AI training clusters exceeding 100 megawatts. The FCC's broadband labeling rules compel ISPs to acquire validated test equipment for speed disclosure compliance. Ashburn and Loudoun County facilities are driving the highest concentration of fiber qualification tool procurement in North America.
Germany
Frankfurt's banking and colocation sectors are adopting automated fiber inspection systems under EU AI Act transparency requirements for infrastructure documentation. The country's national broadband subsidy programs mandate standards-compliant certification for subsidy-eligible deployments. Bavarian industrial automation clusters are expanding PROFINET validation tool procurement alongside fiber upgrades.
China
MIIT technical conformity benchmarks for telecommunications instruments are tightening electromagnetic compatibility requirements for field-deployable testers. Hyperscale operators in Beijing and Shanghai are certifying coherent optical links for domestic AI infrastructure. Shenzhen manufacturing zones are driving demand for electrical-optical co-verification equipment in silicon photonics packaging.
Japan
METI technical conformity benchmarks are elevating shielding architecture requirements for test equipment serving 5G backhaul deployment. Mobile operators in Tokyo and Osaka are installing millimeter-wave infrastructure requiring portable OTDR verification. Yokohama's telecommunications equipment manufacturing corridor is concentrating R&D partnerships for next-generation Ethernet validation.
India
The country's national electronics policy incentives and cloud sovereignty requirements are attracting hyperscale investment in Mumbai and Hyderabad. TRAI quality of service mandates are pushing enterprises toward validated test documentation for leased line services. Karnataka's emerging data center corridor is creating demand for localized certification partnerships and equipment distribution.
Network Connectivity Tester Market Competitive Environment
Top-tier vendors anchor the premium certification segment, while mid-tier specialists occupy portable troubleshooting niches. The market structure reflects a bifurcation between capital-intensive cable certification platforms and subscription-managed field test fleets. Strategic archetypes include R&D-intensive instrumentation houses, channel-dominant certification specialists, and cloud-managed service aggregators. Competitive moves center on strategic partnerships for silicon photonics co-verification and geographic expansion into India's emerging data center corridor.
Within the R&D-intensive instrumentation tier, Keysight Technologies and Anritsu Corporation exemplify vendors leveraging deep measurement science for high-speed Ethernet portfolios. Fluke Networks anchors the channel-dominant certification specialist archetype with established distribution control in North American enterprise markets. VIAVI Solutions occupies a position bridging protocol analysis expertise with service provider lab relationships. These three companies represent distinct competitive vectors—measurement precision, distribution density, and protocol depth—that define strategic positioning across procurement segments.
| Leading Market Players |
|---|
| Fluke Networks |
| Keysight Technologies |
| VIAVI Solutions |
| EXFO Inc. |
| NetScout Systems |
| Anritsu Corporation |
| Spirent Communications |
| VeEX Inc. |
| Rohde & Schwarz |
| Others |
Value Chain & Pricing Dynamics
High-speed FPGA and specialized analog-to-digital converter costs cascade through Network Connectivity Tester Market tiers, with Taiwan-sourced silicon commanding premium pricing for 400G+ test heads while spot-market procurement of mature-node components enables economy-tier positioning for copper certification tools.
Pricing Analysis
Lead-time-driven pricing stratification separates hyperscale procurement from enterprise spot buying, with 800G optical test suites commanding substantial premiums for sub-90-day delivery while standard cable certification equipment trades at discounts through distributor inventory liquidation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling rather than hardware differentiation alone. Cost compression in the economy tier is intensifying because Chinese module vendors are flooding 10G/25G test adapter markets. Managed service providers exhibit lowest price sensitivity due to subscription model absorption, while educational institutions and small IT departments face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for 7nm and below FPGA fabrication, forcing test equipment vendors to absorb allocation volatility or redesign around larger process nodes with performance tradeoffs. Specialized optical engines draw from Japanese component houses, precision machined housings feed from German and Swiss suppliers, and final assembly concentrates in China and Mexico. Tariff exposure on Chinese-assembled units shipped to the United States is elevating landed costs and accelerating nearshoring pilot programs. Distribution runs through authorized channel partners with calibration service capabilities rather than direct OEM relationships for all but the largest hyperscale accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Network Connectivity Tester Market sits in a technology-transition phase where 800G PAM4 signaling analysis is displacing legacy NRZ-based troubleshooting workflows, rendering substantial portions of the installed base technically obsolete within a single procurement cycle.
For Market Incumbents: Anticipate margin erosion in copper certification segments by accelerating silicon photonics co-verification partnerships before Chinese optical component vendors achieve test-head integration. Defensive consolidation around cloud-managed test fleet platforms will preserve recurring revenue streams against emerging subscription-native entrants. Priority investment in automated fiber inspection machine-vision algorithms protects differentiation as hardware commoditizes. For New Entrants and Emerging Players: Software-defined measurement engines offer the most penetrable wedge, enabling rapid protocol adaptation without captive semiconductor fabrication. India's emerging data center corridor presents white-space opportunity for localized certification service partnerships under national electronics policy incentives. Go-to-market execution through hyperscale facility construction contractors bypasses entrenched Fluke Networks channel control in North American enterprise accounts. For Investors and Strategic Acquirers: IEEE 802.3ck standard finalization is the leading indicator that 800G test equipment demand inflection is approaching, with procurement lagging standard ratification by 12-18 months historically. Long-term viability favors vendors with R&D intensity sufficient to compress compliance validation cycles below standards development timelines. Acquisition targets should display established METI or MIIT pre-market approval partnerships for Asian market access. Signal to monitor: hyperscale capex guidance revisions for AI training cluster buildouts.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Co-Verification Partnership | Enables electrical-optical package-level testing for CPO switch architectures at hyperscale facilities. |
| Cloud-Managed Test Fleet Platform | Converts capital equipment procurement to subscription revenue with calibration logistics control. |
| Automated Fiber Inspection System Launch | Compresses certification timelines for Northern Virginia and Frankfurt colocation operators. |
| India Data Center Corridor Expansion | Captures localized demand from Mumbai and Hyderabad hyperscale construction under PLI incentives. |
| 800G Protocol Analyzer Development | Secures position in service provider lab validation for coherent optical link deployment. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for the Network Connectivity Tester Market analysis, supplemented by primary interviews with data center engineering directors, test equipment procurement managers, fiber certification contractors, and optical component supplier technical leads. SEC 10-K disclosures, FCC equipment authorization databases, IEEE standards committee documentation, and hyperscaler capital expenditure reports provided demand-side triangulation alongside bottom-up channel partner shipment estimates.
Granularity-level modeling deployed product type, application vertical, end-user archetype, and technology protocol as segmentation dimensions, with geographic demand further disaggregated by metropolitan data center cluster rather than national aggregates. Volume and value outputs across the analysis window reflect iterative reconciliation between vendor-reported bookings and end-user deployment schedules. CAGRs were derived from curve-fitting procedures against historical procurement patterns and forward infrastructure buildout announcements, with 800G adoption curves and AI training cluster power density assumptions as key sensitivity inputs.
Several conditions sit outside the modeled scope, including unforeseen IEEE standards timeline delays, geopolitical disruption of Taiwan semiconductor fabrication, and abrupt shifts in hyperscale capital allocation toward inference versus training infrastructure. Forecasts reflect documented assumptions about technology transition velocities and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
Nosql Market