
 APAC Data Center Networking Market | 2026-2036
APAC Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Data Center Networking Market Insights
Hyperscale facility construction across Singapore, Australia, and Japan is shifting capital allocation toward high-bandwidth switching fabrics and programmable network architectures. Cisco Systems leverages its merchant silicon partnerships to sustain router leadership across enterprise data centers in Australia and Southeast Asia. Arista Networks anchors cloud-grade Ethernet deployments through its specialized focus on 400G and 800G spine-leaf architectures for hyperscale operators. Huawei Technologies dominates domestic supply chains in China while extending its influence across ASEAN markets through integrated optical-electrical switching platforms.
APAC data center networking encompasses the interconnection hardware, control plane software, and transmission protocols that enable compute, storage, and application resources to communicate within and between facilities, typically operating at speeds from 100G to 800G with latency budgets under 10 microseconds for AI training clusters. Its primary purpose is to sustain workload mobility, disaster recovery, and real-time data synchronization across geographically distributed infrastructure. Ethernet switching captures the largest revenue pool among product types due to universal compatibility with cloud orchestration stacks, while InfiniBand technology leads growth trajectory as GPU-intensive AI factories proliferate across the region. Cloud service providers represent the most concentrated end-user segment, though government agencies in India and Australia are emerging as structurally significant buyers through sovereign cloud mandates.
China's MIIT enforces GB standards for data center power usage effectiveness that directly shape network equipment procurement specifications, while India's BIS certification requirements for telecommunications infrastructure create compliance thresholds for imported switching hardware. Japan's METI promotes JIS-aligned energy efficiency frameworks that influence network refresh cycles in Tokyo and Osaka facilities. Stakeholders must monitor how divergent national cybersecurity regimes across the region fragment vendor qualification pathways and reshape supply chain localization strategies.
Market Dynamics
AI training clusters across Southeast Asia are compressing network refresh cycles from five years to eighteen months as GPU density per rack doubles annually. This acceleration is forcing capital reallocation toward liquid-cooled switching fabrics and sub-microsecond latency architectures.
Growth Catalysts
- Hyperscale expansion:Cloud service providers in Singapore and Australia are commissioning multi-hundred-megawatt facilities that require 400G/800G spine-leaf architectures. These deployments pull optical transceiver demand upward.
- MEE dual carbon mandates:China's Ministry of Ecology and Environment enforces power usage effectiveness thresholds that favor energy-efficient optical-electrical switching platforms over legacy copper backplanes.
- Digital India infrastructure:Government cloud mandates through MeitY are driving greenfield construction in the Mumbai-Pune corridor with sovereign network requirements.
Market Restraints
- Merchant silicon concentration:Switching ASIC supply concentrates among three foundry sources, creating vulnerability for Arista and Cisco router roadmaps across ASEAN markets.
- Optical component volatility:Coherent DSP and laser supply from Chinese vendors faces export control friction, elevating lead times for 800G transceivers.
- InfiniBand-Ethernet tension:GPU cluster interconnect standards fragment procurement decisions, with NVIDIA's proprietary stack limiting multi-vendor interoperability.
Strategic Opportunities
- Indonesia's untapped capacity:Batam and Jakarta lack hyperscale presence relative to Singapore, creating first-mover positioning for submarine cable landing stations with integrated switching.
- Co-packaged optics convergence:Silicon photonics integration with switch ASICs promises 30% power reduction for AI training clusters in Japan and South Korea.
- PLI scheme tailwinds:India's production-linked incentive scheme for telecom equipment is attracting domestic assembly of switching hardware for government cloud deployments.
Industry Challenges
- Photonics integration talent scarcity:Co-packaged optics design requires rare skill sets combining silicon validation and fiber coupling physics, with APAC universities producing insufficient graduates.
- Multi-vendor interoperability testing:Disaggregated network operating systems from Dell, HPE, and white-box vendors create certification backlogs for hyperscale qualification labs.
- Legacy SONET/SDH migration friction:Financial services data centers in Hong Kong and Tokyo maintain TDM circuits that complicate packet-optical convergence timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Data Center Networking Market |
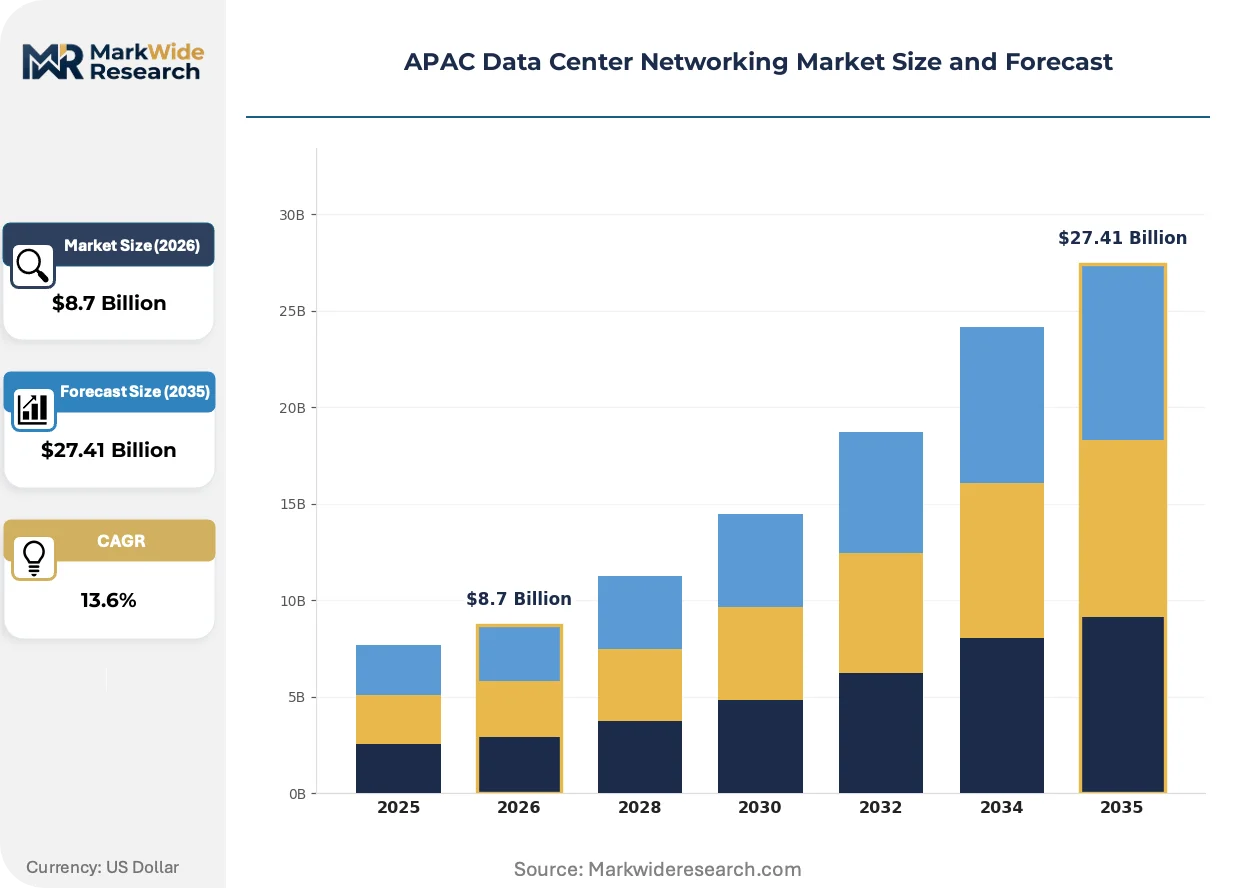
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Network Interface Cards, Load Balancers Technology: Ethernet, InfiniBand, Packet Switching, Optical Networking End User: Cloud Service Providers, Telecommunication Companies, Enterprises, Government Agencies Deployment: On-Premises, Hybrid, Modular, Edge |
| Companies Covered | Cisco Systems, Arista Networks, Hewlett Packard Enterprise, Juniper Networks, Huawei Technologies, H3C Holding Limited, NEC Corporation, Extreme Networks, Fortinet, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Data Center Networking Market Trends and Innovations
Programmable network fabrics are displacing fixed-function switching across APAC hyperscale facilities. This shift enables real-time topology reconfiguration for AI workload placement while complicating vendor support models.
Co-packaged optics is electrifying data center interconnect economics by collapsing optical engines directly onto switch ASIC substrates. Hyperscale operators in Singapore and Sydney are piloting 51.2Tbps silicon platforms with integrated photonics. This integration is compressing transceiver supplier margins while elevating foundry partnerships to strategic priority.
Japan's METI has aligned data center energy efficiency frameworks with JIS standards that mandate power usage effectiveness reporting for facilities exceeding 10MW. Operators in Tokyo and Osaka are responding with network equipment procurement clauses that prioritize idle-state power draw. This regulatory pressure is accelerating merchant silicon adoption over custom ASICs with inferior sleep-state performance.
Cloud service providers are consolidating switching procurement through direct-to-foundry contracts that bypass traditional distributor channels. This disintermediation concentrates in Australia's enterprise data center segment where Macquarie and NEXTDC operate captive qualification programs. The model transfers inventory risk from vendors to operators while demanding custom firmware branches that fragment software maintenance ecosystems.
APAC Data Center Networking Market Segmentation
APAC data center networking procurement patterns diverge sharply across product architectures, interconnect standards, and operational models. Buyers prioritize fundamentally different performance metrics depending on whether they operate GPU-intensive AI factories or legacy enterprise facilities.
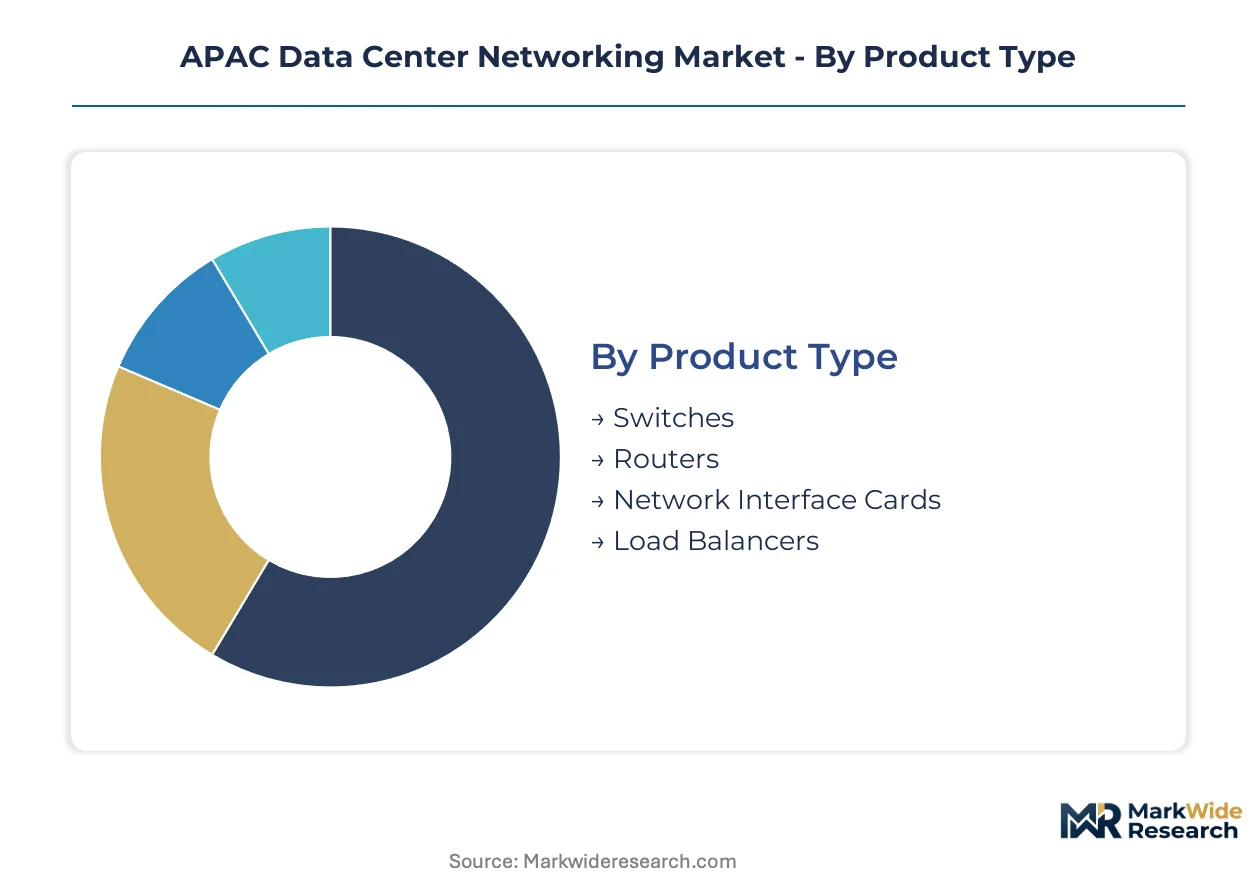
Product Type:
Capital allocation splits between high-port-density switching platforms and specialized traffic management hardware based on facility scale and workload mix.
- Switches:Spine-leaf architectures dominate hyperscale builds, with 400G and 800G port configurations now standard for new construction in Singapore and Sydney. Cloud service providers in these markets drive procurement volume through direct-to-foundry contracts that bypass traditional distribution channels.
- Routers:Border gateway and core routing platforms sustain inter-facility connectivity across geographically distributed infrastructure. Australia's enterprise data center segment relies heavily on merchant silicon-based routers for cost efficiency in multi-tenant environments.
- Network Interface Cards:SmartNICs and DPUs offload virtualization overhead from host CPUs in AI training clusters. Adoption concentrates in Japan and South Korea where GPU density per rack exceeds regional averages.
- Load Balancers:Application delivery controllers manage traffic distribution across distributed compute pools. Financial services data centers in Hong Kong maintain hybrid deployments combining hardware appliances with software-defined alternatives.
Switches lead volumes today; smart NICs are gaining share fastest.
Technology:
Interconnect protocol selection determines power budgets, latency floors, and vendor lock-in exposure for facility operators.
- Ethernet:Universal compatibility with cloud orchestration stacks sustains dominance across enterprise and cloud segments. India's Mumbai-Pune corridor deploys Ethernet exclusively for government cloud infrastructure under MeitY sovereign network mandates.
- InfiniBand:Sub-microsecond latency and native RDMA support make this mandatory for GPU-intensive AI training clusters. NVIDIA's proprietary stack limits multi-vendor interoperability, fragmenting procurement decisions across Southeast Asia.
- Packet Switching:MPLS and segment routing protocols enable traffic engineering across multi-tenant facilities. Australian operators leverage these capabilities for disaster recovery and workload mobility between Sydney and Melbourne facilities.
- Optical Networking:Coherent DWDM platforms collapse inter-facility distances with minimal signal regeneration. China's MIIT power usage effectiveness thresholds favor energy-efficient optical-electrical switching platforms over legacy copper backplanes.
Ethernet dominates installed base; optical networking is climbing the fastest.
End User:
Procurement scale and technical specifications vary dramatically based on institutional mission and regulatory exposure.
- Cloud Service Providers:Hyperscale operators commission multi-hundred-megawatt facilities requiring programmable network fabrics and real-time topology reconfiguration. These buyers drive 400G/800G spine-leaf adoption across Singapore, Australia, and Japan.
- Telecommunication Companies:Carrier-neutral facilities and 5G edge deployments demand converged packet-optical platforms. Tight integration with existing transport networks shapes vendor qualification pathways.
- Enterprises:Private cloud and colocation requirements prioritize operational simplicity over bleeding-edge performance. Australia's Macquarie and NEXTDC operate captive qualification programs that fragment software maintenance ecosystems.
- Government Agencies:Sovereign cloud mandates in India and Australia create structurally significant demand segments with localized supply chain requirements. India's PLI scheme for telecom equipment attracts domestic assembly of switching hardware for these deployments.
Cloud service providers anchor volume today; government agencies are expanding most quickly.
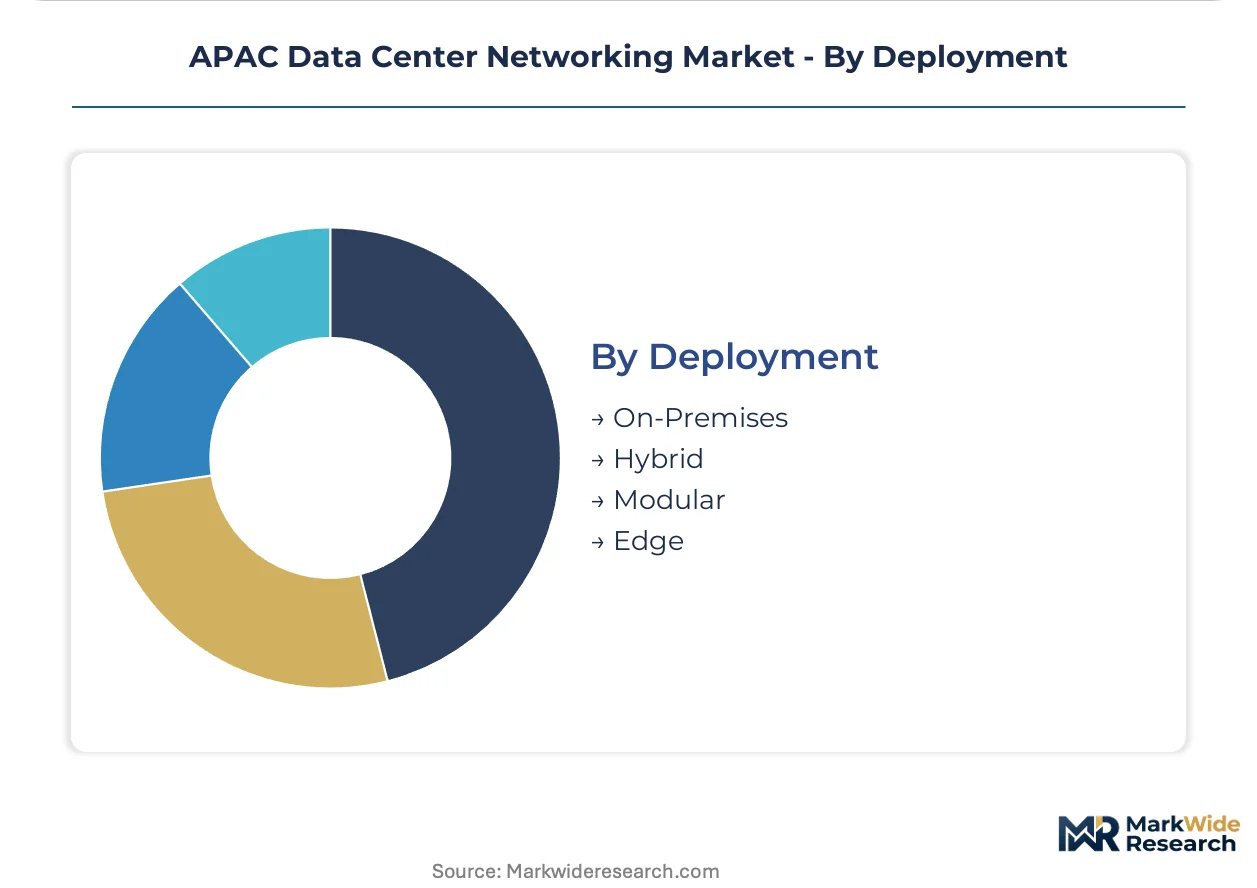
Deployment:
Physical architecture decisions cascade through power, cooling, and network topology design for facility operators.
- On-Premises:Captive data centers remain prevalent among financial institutions in Hong Kong and Tokyo with legacy SONET/SDH circuit requirements. These facilities complicate packet-optical convergence timelines.
- Hybrid:Split workload placement between owned infrastructure and colocation creates complex interconnection requirements. Japanese operators respond to METI energy efficiency frameworks with network equipment procurement clauses prioritizing idle-state power draw.
- Modular:Prefabricated data hall designs accelerate deployment timelines for capacity-constrained markets. Indonesia's Batam and Jakarta markets lack hyperscale presence, creating positioning opportunities for integrated switching deployments.
- Edge:Distributed micro-facilities support latency-sensitive applications across metropolitan footprints. 5G network densification in South Korea and Japan pulls compact switching platforms into cell tower aggregation points.
On-premises retains the largest footprint; edge deployments are accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting data center construction toward jurisdictions with favorable power pricing and streamlined permitting. China's MIIT efficiency mandates and India's PLI incentives create divergent cost-of-compliance environments that reshape network equipment procurement patterns across the region.
China
Dual carbon goals under MEE are accelerating optical-electrical switching deployments in hyperscale facilities. MIIT enforces GB standards for power usage effectiveness that directly shape router and switch specifications. The Yangtze River Delta hosts the densest concentration of AI training clusters, with Shanghai operators piloting 51.2Tbps silicon platforms.
India
MeitY sovereign cloud mandates are driving greenfield construction in the Mumbai-Pune corridor with localized network requirements. The PLI scheme for telecom equipment attracts domestic switching hardware assembly for government deployments. Maharashtra's data center operators are commissioning 400G spine-leaf architectures under strict BIS certification thresholds.
Japan
METI-aligned JIS energy efficiency frameworks mandate power usage effectiveness reporting for facilities exceeding 10MW. Network refresh cycles in Tokyo and Osaka prioritize idle-state power draw in procurement clauses. Kanto region operators are responding with merchant silicon adoption over custom ASICs.
Australia
Macquarie and NEXTDC operate captive qualification programs that fragment software maintenance ecosystems. Enterprise data centers in Sydney and Melbourne rely on merchant silicon-based routers for multi-tenant cost efficiency. The Sydney-Melbourne corridor sustains disaster recovery workload mobility through MPLS-enabled packet switching.
Singapore
Land scarcity and power constraints are compressing facility designs toward liquid-cooled switching fabrics with sub-microsecond latency. Cloud service providers commission multi-hundred-megawatt facilities requiring programmable network fabrics. The city-state's submarine cable landing stations anchor interconnection demand for 800G coherent optical platforms.
APAC Data Center Networking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized AI interconnect niches. The vendor landscape consolidates around three merchant silicon foundry relationships that constrain router and switch roadmaps. Strategic archetypes include cloud-grade Ethernet specialists, integrated optical-electrical platform providers, and enterprise-focused merchant silicon adopters. Competitive moves concentrate on direct-to-foundry contracting and co-packaged optics partnerships.
Among US-based network equipment providers, Cisco Systems and Arista Networks exemplify contrasting approaches to hyperscale engagement. Cisco leverages merchant silicon partnerships across enterprise data centers in Australia and Southeast Asia. Arista anchors cloud-grade Ethernet deployments through specialized spine-leaf architectures. Huawei Technologies occupies a distinct position, dominating domestic supply chains in China while extending influence across ASEAN markets through integrated switching platforms.
| Leading Market Players |
|---|
| Cisco Systems |
| Arista Networks |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Huawei Technologies |
| H3C Holding Limited |
| NEC Corporation |
| Extreme Networks |
| Fortinet |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics integration specialists concentrated in Japan and South Korea command wage premiums that compress pricing spreads between premium merchant silicon switches and standard copper-based alternatives across the APAC region. This labor-cost differential widens tier separation as foundry partnerships become the dominant procurement determinant for hyperscale operators.
Pricing Analysis
Distributor margins in traditional channel networks face compression as cloud service providers in Singapore and Australia execute direct-to-foundry contracts that bypass intermediary layers entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies around port density, with 800G spine-leaf configurations commanding substantial premiums over 400G equivalents. Pricing pressure stems from merchant silicon commoditization as Broadcom and Marvell expand ASIC availability to white-box vendors. Government agencies in India exhibit highest price sensitivity due to PLI scheme localization requirements, while Japanese hyperscale operators prioritize idle-state power efficiency over unit cost.
Supply Chain Analysis
Freight costs for optical transceivers from Chinese manufacturing hubs to Southeast Asian facilities have escalated as export control friction diverts shipments through alternative routing. Taiwan, China, and Malaysia anchor switching hardware assembly, with coherent DSP and laser components drawing from specialized Japanese and Korean suppliers. Single-source vulnerability concentrates in merchant silicon foundry relationships, where three dominant sources constrain router and switch roadmaps across ASEAN markets. Distribution runs through captive qualification programs operated by Australian data center providers, fragmenting traditional vendor-distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with China's MIIT power usage effectiveness mandates and India's PLI scheme creating structurally divergent procurement environments that reshape vendor positioning across the region.
For Market Incumbents: Anchor defensive positioning through deepening foundry partnerships that lock in merchant silicon allocation priority, while accelerating co-packaged optics R&D to offset white-box commodification threats. Cisco and Arista must secure captive 51.2Tbps switch ASIC supply agreements before emerging optical-electrical integrators capture hyperscale mindshare. Certification investment in India's BIS framework represents essential channel control for government cloud deployments. For New Entrants and Emerging Players: Begin with Indonesia's Batam and Jakarta corridor, where submarine cable landing station integration creates first-mover positioning absent incumbent hyperscale presence. Target sovereign cloud mandates in India's Mumbai-Pune corridor through domestic assembly partnerships under PLI scheme incentives. A go-to-market angle emphasizing liquid-cooled switching fabrics addresses Singapore's land-scarcity constraints while differentiating from established air-cooled portfolios. For Investors and Strategic Acquirers: Valuations sit cheapest among optical component specialists with silicon photonics design capabilities but limited foundry access, as capital markets underweight co-packaged optics convergence timing. The five-to-ten-year viability window favors acquisition targets possessing rare photonics integration talent combining silicon validation and fiber coupling physics. Watch NVIDIA's InfiniBand-Ethernet interoperability stance as the critical inflection signal determining merchant silicon switching demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Foundry Contracting | Bypasses distributor channels and transfers inventory risk to hyperscale operators in Australia. |
| Co-Packaged Optics Partnership | Collapses optical engines onto switch ASIC substrates for 30% power reduction in Japanese AI clusters. |
| Domestic Assembly Localization | Captures PLI scheme incentives for government cloud deployments across India's Maharashtra state. |
| Merchant Silicon Roadmap Lock | Secures ASIC allocation priority against white-box commodification threats in ASEAN markets. |
| Liquid-Cooled Fabric Development | Addresses Singapore's power-constrained facility designs with sub-microsecond latency architectures. |
Research Methodology
Coverage spans China, India, Japan, Australia, and Singapore, with primary inputs from each market combining structured interviews with hyperscale network architects, data center procurement officers, optical component engineering directors, and cloud platform infrastructure leads. Secondary validation draws from MIIT GB standard filings, METI JIS energy efficiency reports, MeitY sovereign cloud policy documents, and hyperscaler capital expenditure disclosures. Bottom-up equipment shipment analysis triangulates against top-down facility construction pipeline tracking.
Rate-of-change decomposition separates volume growth from unit price evolution across the projection horizon. Segmentation dimensions modeled include product architecture, interconnect protocol, end-user institution type, and deployment physical topology, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derive from facility construction timelines, GPU cluster density trajectories, and national digital infrastructure program schedules. Switch port speed migration curves and optical transceiver adoption rates serve as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen export control expansions affecting coherent DSP supply, abrupt InfiniBand-Ethernet standard convergence, and geopolitical disruptions to submarine cable landing station development. Forecasts reflect documented assumptions regarding merchant silicon foundry capacity expansion and national data center permitting velocity. A model refresh is warranted upon material change in China's dual carbon enforcement intensity or India's PLI scheme qualification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Network Function Virtualization (NFV) Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Enterprise Network Infrastructure Market