
 Mexico Data Center Networking Market | 2026-2036
Mexico Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Data Center Networking Market Insights
Mexico's Federal Law on Climate Change and associated energy efficiency mandates for large power consumers is broadening the addressable market for efficient networking gear. Cisco Systems Inc. leverages its extensive partner ecosystem to dominate enterprise switching deployments across Mexican data centers. Huawei Technologies Co. Ltd. competes aggressively on price-performance ratios in the fiber infrastructure layer. NVIDIA anchors the accelerated computing segment as AI training clusters proliferate in Mexico City and Monterrey facilities.
Mexico data center networking encompasses the switching, routing, and interconnect hardware that enables compute and storage resource communication within and between facilities, typically operating at speeds from 10 Gbps to 800 Gbps with latency budgets under 10 microseconds for high-performance computing environments. Ethernet technology leads current deployments due to its cost structure and interoperability, while InfiniBand segments command premium positioning in AI and HPC workloads where bandwidth and latency requirements are most stringent. Colocation deployment models concentrate margin pools as operators bundle managed networking services, whereas hybrid architectures are expanding fastest among enterprises balancing sovereignty requirements with cloud elasticity.
CRE, Mexico's federal energy regulator, enforces efficiency standards that directly shape cooling and power distribution investments, while NOM-001-SEDE electrical installation standards mandate grounding and surge protection specifications for networking equipment. The national telecommunications regulator IFT governs spectrum allocation and interconnection rules that affect wireless backhaul and edge connectivity strategies. Stakeholders must monitor how pending data localization requirements and cross-border fiber regulations reshape interconnection topology decisions.
Market Dynamics
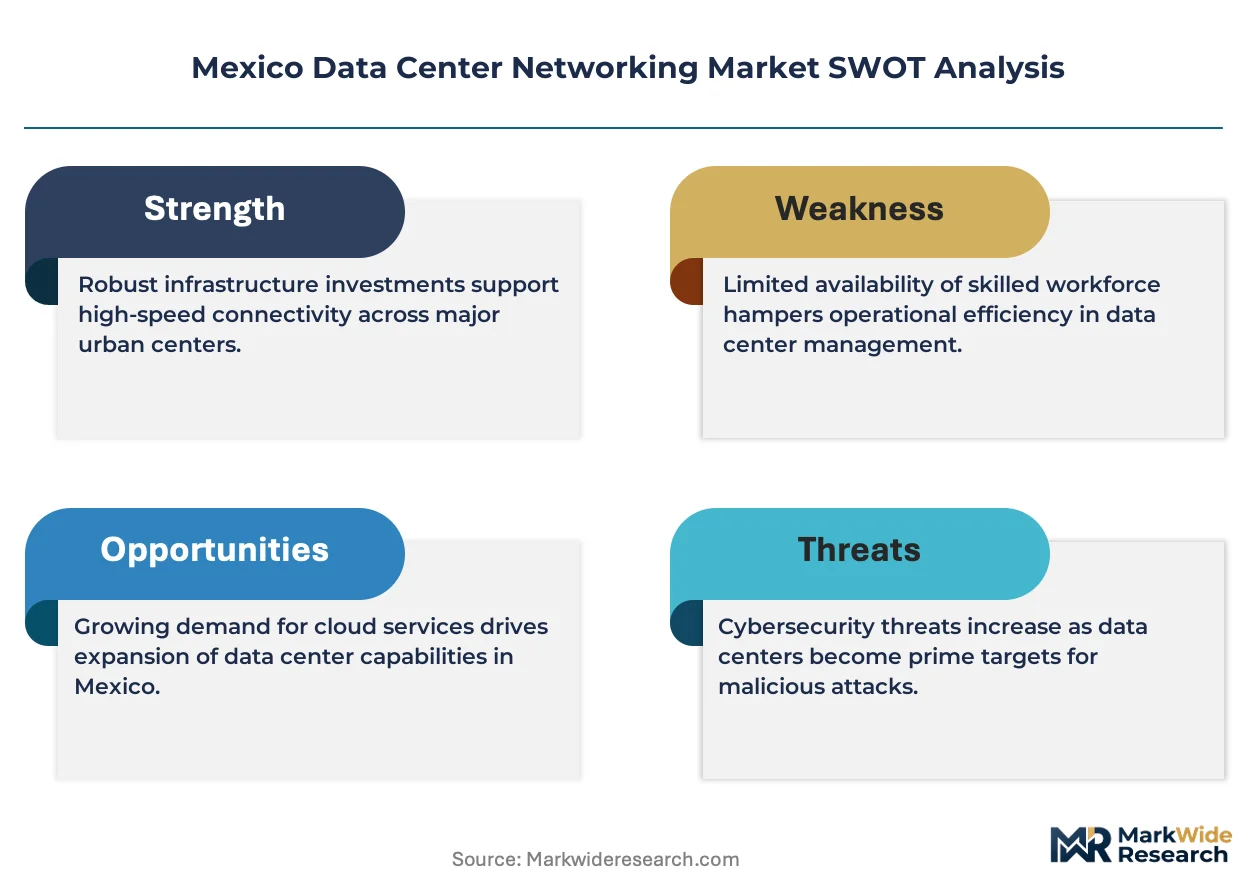
Hyperscale cloud providers are compressing procurement cycles for 800 Gbps switching fabrics while CRE efficiency mandates force simultaneous thermal and power redesigns. This dual pressure is restructuring vendor qualification timelines and facility certification pathways.
Growth Catalysts
- AI Training Clusters:GPU-intensive workloads in Mexico City and Monterrey facilities are driving demand for ultra-low-latency InfiniBand interconnects and high-radix Ethernet switches.
- NOM-001-SEDE Grounding Standards:Mexico's national electrical installation code is mandating surge protection specifications that favor certified networking equipment with enhanced reliability ratings.
- Querétaro-Bajío Fiber Density:Concentrated dark fiber availability and utility-scale land parcels are attracting multi-facility campus developments requiring scalable spine-leaf architectures.
Market Restraints
- Copper and Optical Component Volatility:Raw material costs for high-speed transceivers fluctuate with semiconductor foundry capacity constraints in Asian manufacturing hubs.
- Single-Source ASIC Dependency:Merchant silicon for 400G/800G switching relies on concentrated fabless design houses, creating supply vulnerability for Mexican system integrators.
- InfiniBand-Ethernet Protocol Friction:Divergent RDMA implementations between standards complicate heterogeneous cluster deployments and extend validation timelines.
Strategic Opportunities
- Guadalajara Metro Zone:Underdeveloped colocation capacity relative to Mexico City creates whitespace for edge networking deployments serving central-west manufacturing corridors.
- CRE Peak Demand Response Incentives:Mexico's federal energy regulator offers tariff structures rewarding facilities with intelligent power management and dynamic workload orchestration.
- Converged Liquid Cooling-Networking:Integration of coolant distribution units with switch thermal design enables higher port density in restricted floor space.
Industry Challenges
- Certified Fiber Splicing Shortage:NOM-001-SEDE compliance requires licensed technicians for high-voltage-adjacent installations, constraining deployment velocity.
- Legacy 10G/25G Infrastructure Stranding:Enterprise data centers face forklift upgrade costs as hyperscale-driven 100G/400G economics obsolete prior generation equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Data Center Networking Market |
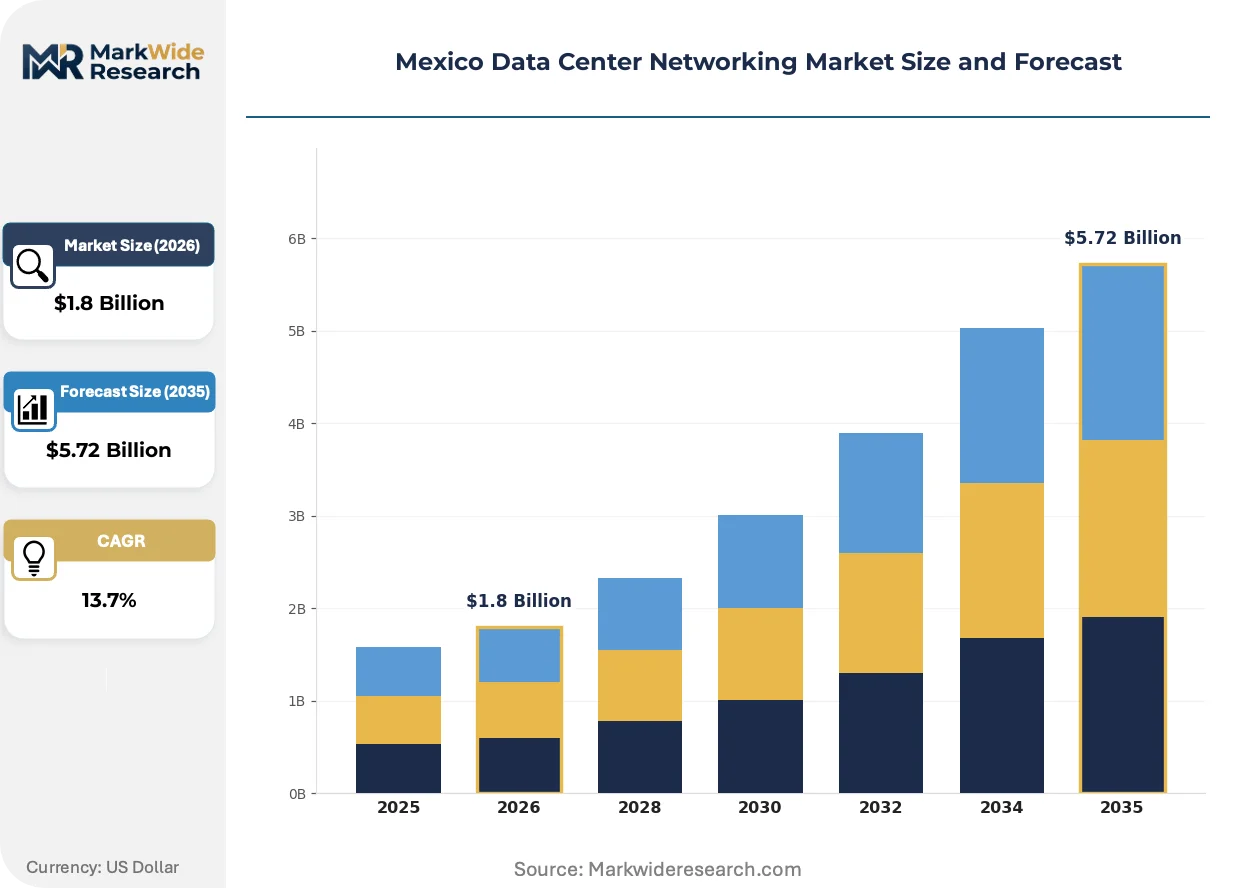
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Access Points Technology: Ethernet, Fibre Channel, InfiniBand, MPLS Deployment: On-premises, Cloud-based, Hybrid, Colocation End User: Telecommunication, BFSI, Retail, Government |
| Companies Covered | Cisco Systems Inc., Dell Inc., Huawei Technologies Co. Ltd., Schneider Electric, Eaton Corporation, Emerson Electric Co., NVIDIA, VMware Inc., Hewlett Packard Enterprise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Data Center Networking Market Trends and Innovations
Networking hardware architectures are fragmenting into disaggregated components as buyers reject monolithic chassis economics. This decomposition is redistributing value capture across the supply stack.
White-box switching platforms built on merchant silicon are modularizing procurement for Mexican colocation operators. Mid-tier facilities in Querétaro and Monterrey are adopting these open designs to bypass traditional vendor lock-in. The approach is compressing capital deployment timelines and enabling mix-and-match optical transceiver sourcing.
CRE efficiency auditing protocols now mandate real-time power usage effectiveness tracking for facilities above 500 kW contracted load. Mexico's federal energy regulator is embedding networking telemetry into compliance verification workflows. Colocation providers are responding by deploying intelligent rack-level power distribution units with embedded Ethernet management planes.
Enterprise buyers are unbundling managed networking services from colocation contracts and sourcing directly from specialized network-as-a-service providers. This disintermediation is pressuring traditional facility operators to expose bare-metal cross-connect pricing. The pattern is most pronounced among financial services tenants in Mexico City seeking sovereign control over encryption key management.
Mexico Data Center Networking Market Segmentation
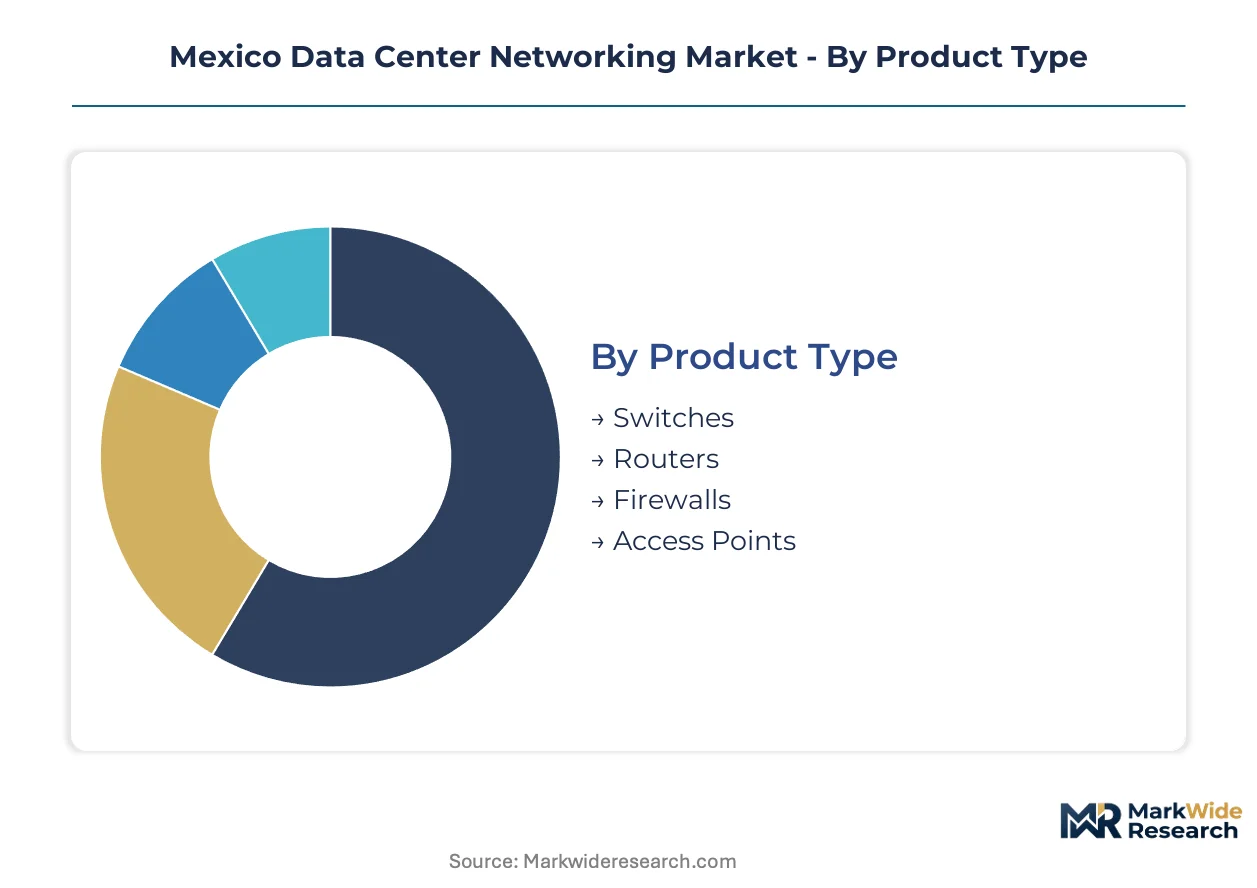
Segmentation in Mexico's data center networking market reveals how capital allocation, regulatory compliance, and workload specialization reshape procurement patterns. Buyers optimize across hardware generations, protocol standards, and facility ownership models to balance performance mandates against CRE efficiency requirements.
Product Type:
Capital intensity varies sharply across hardware categories, with high-port-density switching fabrics demanding the largest upfront infrastructure commitments.
- Switches:Spine-leaf architectures dominate hyperscale deployments in Querétaro, with 400G/800G radix configurations requiring substantial initial outlay for merchant silicon platforms. Demand concentrates among cloud providers building multi-facility campuses where NOM-001-SEDE grounding specifications favor certified chassis with integrated surge protection.
- Routers:Border gateway and core aggregation systems handle inter-facility traffic across Mexico's fiber corridors. Monterrey financial services hubs drive procurement for hardware with deep buffer architectures and MPLS segment routing capabilities.
- Firewalls:Next-generation platforms with TLS inspection throughput anchor security postures for BFSI tenants in Mexico City colocation facilities.
- Access Points:Wi-Fi 6E and emerging Wi-Fi 7 infrastructure serve edge compute zones within manufacturing-adjacent data centers in Guadalajara.
Most installed capacity flows through Switches. Expansion is steepest in Firewalls as sovereign data requirements harden perimeter security mandates.
Technology:
Protocol selection follows workload physics—bandwidth density and latency tolerance dictate where each standard gains traction.
- Ethernet:Dominant protocol across enterprise and cloud deployments, with RoCEv2 implementations narrowing the performance gap against specialized alternatives. Querétaro-Bajío hyperscale builds standardize on 100G/400G Ethernet for cost-engineered storage and general compute fabrics.
- InfiniBand:NVIDIA's end-to-end stack commands AI training clusters in Mexico City and Monterrey where sub-microsecond latency and adaptive routing justify premium economics. NDR 400G deployments are accelerating as GPU counts per rack exceed thermal and power densities addressable by Ethernet alternatives.
- Fibre Channel:Persists in legacy enterprise storage networks, particularly among BFSI institutions with sunk investment in SAN architectures.
- MPLS:Underpins managed WAN services for distributed enterprises requiring deterministic QoS across CRE-regulated facility footprints.
Volume leadership sits with Ethernet. InfiniBand is climbing the fastest as AI infrastructure investments concentrate in central and northern Mexico.
Deployment:
Ownership economics and sovereignty calculus fragment procurement authority across facility models.
- Colocation:Third-party operators bundle cross-connect and managed switching services, capturing margin pools through interconnection revenue. Querétaro campuses lead this segment with multi-tenant designs that amortize NOM-001-SEDE compliance costs across diverse tenant bases.
- Cloud-based:Hyperscale self-builds in Mexico City and Monterrey deploy custom networking stacks with disaggregated white-box switching, bypassing traditional vendor channels.
- On-premises:Enterprise captive facilities face stranded asset risk as 10G/25G generations obsolete against hyperscale-driven 100G/400G economics.
- Hybrid:Architectures balancing sovereignty requirements with cloud elasticity are expanding most quickly among retail and government segments navigating data localization pressures.
Revenue concentration favors Colocation. Hybrid deployments are gaining share fastest as regulatory uncertainty extends multi-environment strategies.
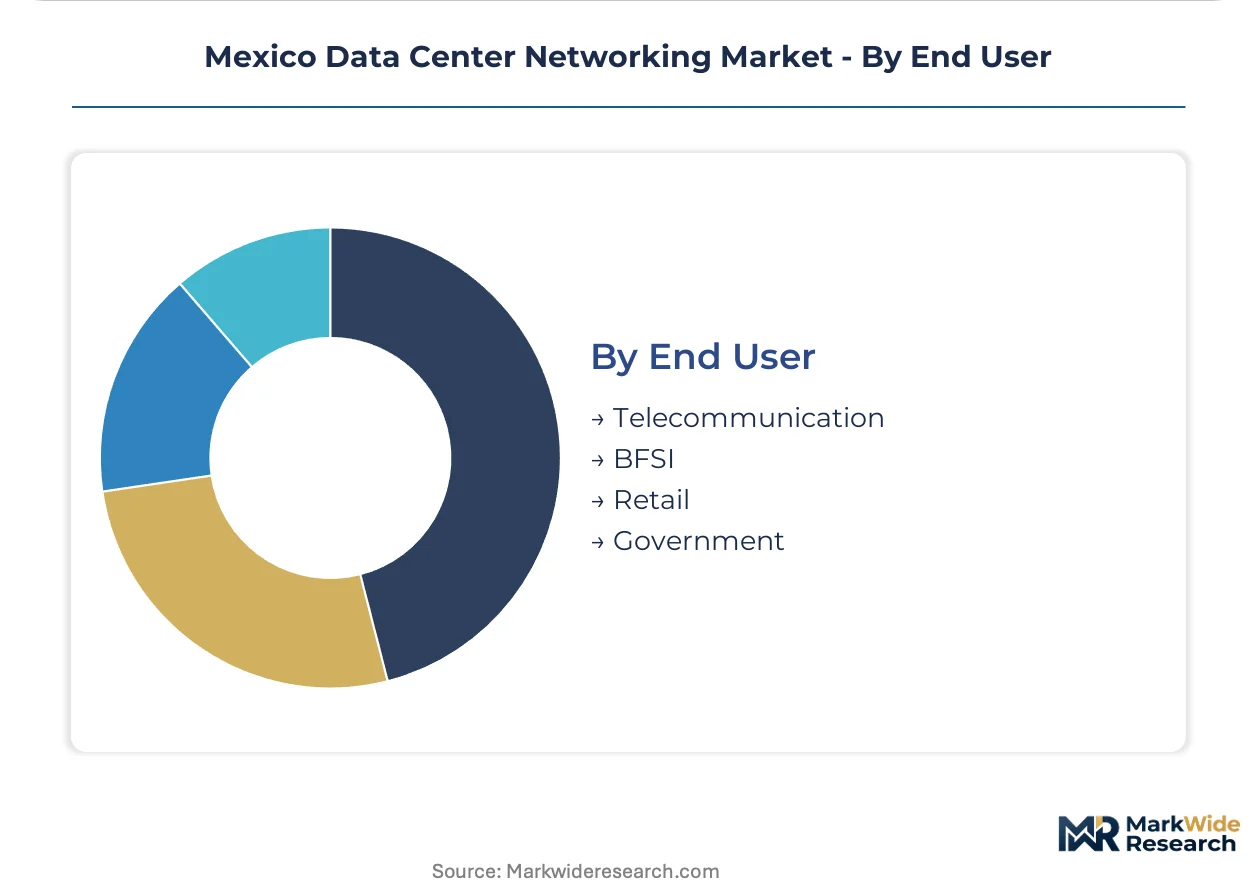
End User:
Vertical-specific compliance and latency requirements reshape networking specifications across buyer categories.
- Telecommunication:Carrier-neutral facilities and 5G core infrastructure drive demand for high-scale routing with segment routing and EVPN-VXLAN overlays. IFT interconnection rules govern peering arrangements that determine cross-connect pricing transparency.
- BFSI:Encryption key sovereignty and transaction latency mandates favor dedicated dark fiber and private switching infrastructure in Mexico City financial districts.
- Retail:Omnichannel workload distribution creates edge networking requirements across Guadalajara and central-west logistics corridors.
- Government:Federal data localization proposals are redirecting procurement toward domestic facility operators with certified supply chains and NOM-compliant installation practices.
Telecommunication commands the largest installed base. Government is expanding most quickly as pending localization requirements accelerate sovereign infrastructure commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's data center networking infrastructure traces its modern lineage to the 2010s when Querétaro's aerospace and automotive clusters created demand for industrial-grade connectivity. Federal energy efficiency mandates and state-level investment incentives subsequently channeled hyperscale builds toward specific geographic corridors.
Mexico City Metro
Financial services tenants and AI training clusters drive demand for ultra-low-latency InfiniBand and high-radix Ethernet fabrics. CRE peak demand response incentives reward facilities with intelligent power management systems. The Santa Fe and Tlalnepantla sub-markets concentrate multi-tenant colocation campuses requiring scalable spine-leaf architectures.
Nuevo León
Monterrey's manufacturing base and cross-border logistics generate edge networking requirements for industrial IoT and enterprise hybrid cloud. NOM-001-SEDE electrical installation standards mandate surge protection specifications favoring certified networking equipment. The Apodaca and Escobedo industrial corridors attract campus-style data center developments with dedicated fiber backhaul.
Jalisco
Guadalajara's underdeveloped colocation capacity relative to Mexico City creates whitespace for edge networking deployments. IFT interconnection rules govern spectrum allocation affecting wireless backhaul strategies. The Zapopan technology corridor and El Salto logistics zone concentrate emerging facility developments serving central-west manufacturing.
Bajío Region
Querétaro anchors the corridor where fiber connectivity density and utility-scale land availability attract hyperscale builds. NOM-001-SEDE compliance costs amortize across multi-tenant designs with diverse tenant bases. The Querétaro-San Luis Potosí highway corridor enables multi-facility campus architectures with dark fiber interconnects.
Northern Border States
Cross-border data flows and nearshoring manufacturing create demand for border-adjacent networking infrastructure. Pending data localization requirements reshape interconnection topology decisions for facilities serving US enterprise tenants. Tijuana and Ciudad Juárez sub-markets concentrate edge deployments bridging latency requirements between jurisdictions.
Mexico Data Center Networking Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Mexico's data center networking supply stack. The vendor ecosystem organizes around three strategic tiers: integrated platform providers with end-to-end portfolios, specialized component suppliers focused on optical or power infrastructure, and merchant silicon-based white-box assemblers. Market structure reflects consolidation at the switching layer alongside fragmentation in cooling and power distribution accessories. Dominant competitive moves include strategic partnerships between facility operators and equipment vendors, plus geographic expansion through certified installer networks addressing NOM-001-SEDE compliance requirements.
Within the integrated platform tier, Cisco Systems Inc. and Dell Inc. occupy positions spanning enterprise switching through hyperconverged infrastructure. NVIDIA exemplifies the accelerated computing specialist archetype as GPU-intensive workloads proliferate. Huawei Technologies Co. Ltd. represents the price-competitive infrastructure alternative in fiber and transport layers. These three anchors illustrate how vendor selection in Mexico balances interoperability requirements against total cost of ownership considerations under federal energy efficiency mandates.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Dell Inc. |
| Huawei Technologies Co. Ltd. |
| Schneider Electric |
| Eaton Corporation |
| Emerson Electric Co. |
| NVIDIA |
| VMware Inc. |
| Hewlett Packard Enterprise |
| Others |
Pricing and Supply Chain Analysis
Optical transceiver commodity indices for 400G/800G coherent modules cascade through Mexican system integrator pricing tiers, compressing margins on certified NOM-001-SEDE equipment while amplifying cost advantages for merchant silicon white-box assemblers sourcing directly from Asian foundries.
Pricing Analysis
Three-tier pricing structure across premium InfiniBand fabrics, standard enterprise Ethernet, and economy-grade legacy 10G/25G equipment dominates procurement patterns. Price differentiation rests on NOM-001-SEDE certification grade and volume scale commitments from hyperscale cloud operators. Cost compression in mid-tier switching is intensifying because merchant silicon commoditization erodes chassis vendor premiums. Enterprise captive facilities exhibit highest price sensitivity due to stranded asset exposure, while AI training cluster operators prioritize latency performance over unit economics.
Supply Chain Analysis
NOM-001-SEDE licensed technician certification gates deployment velocity for high-voltage-adjacent fiber installations, constraining qualified installer availability across Mexican facilities. Merchant silicon supply concentrates in Taiwan, South Korea, and the United States. Raw material dependencies span III-V semiconductor substrates, precision optical components, and copper alloy interconnects. Single-source ASIC vulnerability from concentrated fabless design houses creates supply risk for Mexican integrators. Distribution runs through certified channel partners with CRE compliance expertise rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's data center networking market represents a late-cycle quality story as AI training workload specifications displace commodity Ethernet with premium InfiniBand and high-radix switching requirements.
For Market Incumbents: Acquire certified fiber splicing technician networks to secure NOM-001-SEDE deployment capacity against emerging white-box assemblers. Consolidate position in Querétaro-Bajío corridor through CRE-efficient spine-leaf architecture bundling. Defensive moves must address merchant silicon commoditization threatening traditional chassis margins. For New Entrants and Emerging Players: Mid-market colocation operators in Guadalajara metro zone present the most penetrable buyer archetype for edge networking deployments. White-box switching platforms with open management planes unlock procurement authority unbundling from incumbent vendor relationships. Go-to-market leverage centers on CRE peak demand response incentive optimization as a bundled service. For Investors and Strategic Acquirers: Asymmetric upside sits with converged liquid cooling-networking specialists addressing thermal density constraints in restricted Mexican floor space. Five-to-ten year viability favors vendors with backward integration into optical component supply. Watch for inflection in federal data localization proposal progression as sovereign infrastructure commitment signal.| Strategic Initiative | Industry Significance |
|---|---|
| NOM-001-SEDE Certification Investment | Licensed technician networks unlock high-voltage-adjacent deployment velocity in Querétaro corridor. |
| Merchant Silicon Platform Development | White-box switching bypasses traditional vendor lock-in for Mexican colocation operators. |
| CRE Efficiency Integration Partnership | Intelligent power management bundling captures federal tariff incentive structures. |
| InfiniBand Fabric Specialization | AI training cluster demand in Mexico City and Monterrey justifies premium positioning. |
| Guadalajara Metro Zone Expansion | Underdeveloped colocation capacity creates whitespace for edge networking deployments. |
Research Methodology
Bottom-up colocation operator and hyperscale cloud deployment modeling reconciled against top-down merchant silicon supply tracking forms the analytical core. Primary interviews with data center facility engineers, network architects at cloud providers, CRE compliance officers, and certified NOM-001-SEDE installation contractors combine with secondary validation from IFT spectrum allocation records, CRE efficiency audit protocols, SEC filings of listed networking vendors, and hyperscaler capital expenditure disclosures. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of switching port shipments and fiber deployment permits extrapolation across the projection horizon. Segmentation dimensions modeled include product type, protocol technology, deployment ownership model, and vertical end-use category. CAGRs derive from slope analysis of historical penetration curves adjusted for AI workload inflection and regulatory compliance cost trajectories. Forecast inputs incorporate CRE peak demand tariff structures and pending data localization proposal status.
Underlying measurement precision varies by segment; hyperscale cloud and colocation deployments carry tighter precision than enterprise captive facilities with opaque procurement. Forecasts reflect assumptions about NOM-001-SEDE enforcement consistency and merchant silicon supply continuity. Model refresh is warranted upon material change in federal data localization legislation or CRE efficiency mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
SDN Orchestration Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
China Data Center Networking Market