
 Data Warehousing Market | 2026-2036
Data Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Data Warehousing Market Analysis
Modular unbundling of compute from storage is rebalancing buyer choice in data warehousing. Snowflake leverages separation of storage and compute billing to attract workload-specific procurement. Oracle anchors large enterprise accounts with integrated database-to-warehouse pipelines. Teradata sustains on-premises loyalty through workload-optimized appliance configurations.
A data warehouse is a centralized repository designed for query and analysis of structured, semi-structured, and unstructured data, typically supporting petabyte-scale storage with columnar indexing and massively parallel processing architectures. Its primary commercial purpose is to enable historical analytics, regulatory reporting, and business intelligence across disparate operational systems. Cloud-based deployment captures the fastest expansion as enterprises exit capital-intensive data center commitments. The BFSI end-user segment dominates current spending due to Basel III liquidity reporting and anti-money-laundering analytics requirements. In-memory technology represents a concentrated margin pool for vendors serving sub-second decisioning workloads in capital markets.
The US CLOUD Act and Europe's GDPR create divergent data residency obligations that shape multi-cloud architecture decisions. HIPAA in healthcare and SEC recordkeeping rules in financial services impose retention and auditability standards that filter vendor selection. Stakeholders must monitor evolving sovereignty requirements as national data-localization statutes proliferate beyond established transatlantic frameworks.
Market Dynamics
Separation of compute and storage billing is restructuring procurement economics across data warehousing, forcing incumbents to abandon bundled appliance pricing and migrate toward consumption-based models.
Growth Catalysts
- Real-time risk analytics:Basel III liquidity reporting mandates from the European Banking Authority and US SEC are compelling financial institutions to modernize data infrastructure for sub-second decisioning.
- Cloud migration deadlines:Europe's GDPR data residency requirements and the US CLOUD Act cross-border access provisions are accelerating platform replacement cycles in regulated industries.
- Hyperscaler availability zone expansion:Dense geographic coverage of low-latency cloud regions in the United States is reducing data gravity concerns for latency-sensitive workloads.
Market Restraints
- Data egress cost volatility:Cloud providers impose steep bandwidth charges for inter-platform data movement, locking enterprises into single-vendor architectures.
- Specialized talent scarcity:Shortages of platform-specific data engineers familiar with massively parallel processing query optimization constrain migration velocity.
- On-premises sunk cost:Enterprises with depreciated Teradata and Oracle appliance investments face write-down pressure that delays cloud transitions.
Strategic Opportunities
- Healthcare analytics under HIPAA:The US healthcare sector remains underpenetrated for cloud-native warehousing due to historical compliance caution, creating first-mover advantages for certified platforms.
- AI-ready data pipelines:Convergence of vector database indexing with traditional warehouse architectures is opening new workloads for unified analytics platforms.
- India's data localization mandate:The country's Digital Personal Data Protection Act is forcing global enterprises to deploy in-country infrastructure, benefiting regional cloud providers.
Industry Challenges
- Multi-cloud query federation:Enterprises struggle to maintain consistent performance across Snowflake, Databricks, and BigQuery environments without vendor-specific optimization.
- Skillset displacement:Traditional ETL engineering expertise loses value as platforms automate pipeline orchestration, forcing workforce retraining investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Warehousing Market |
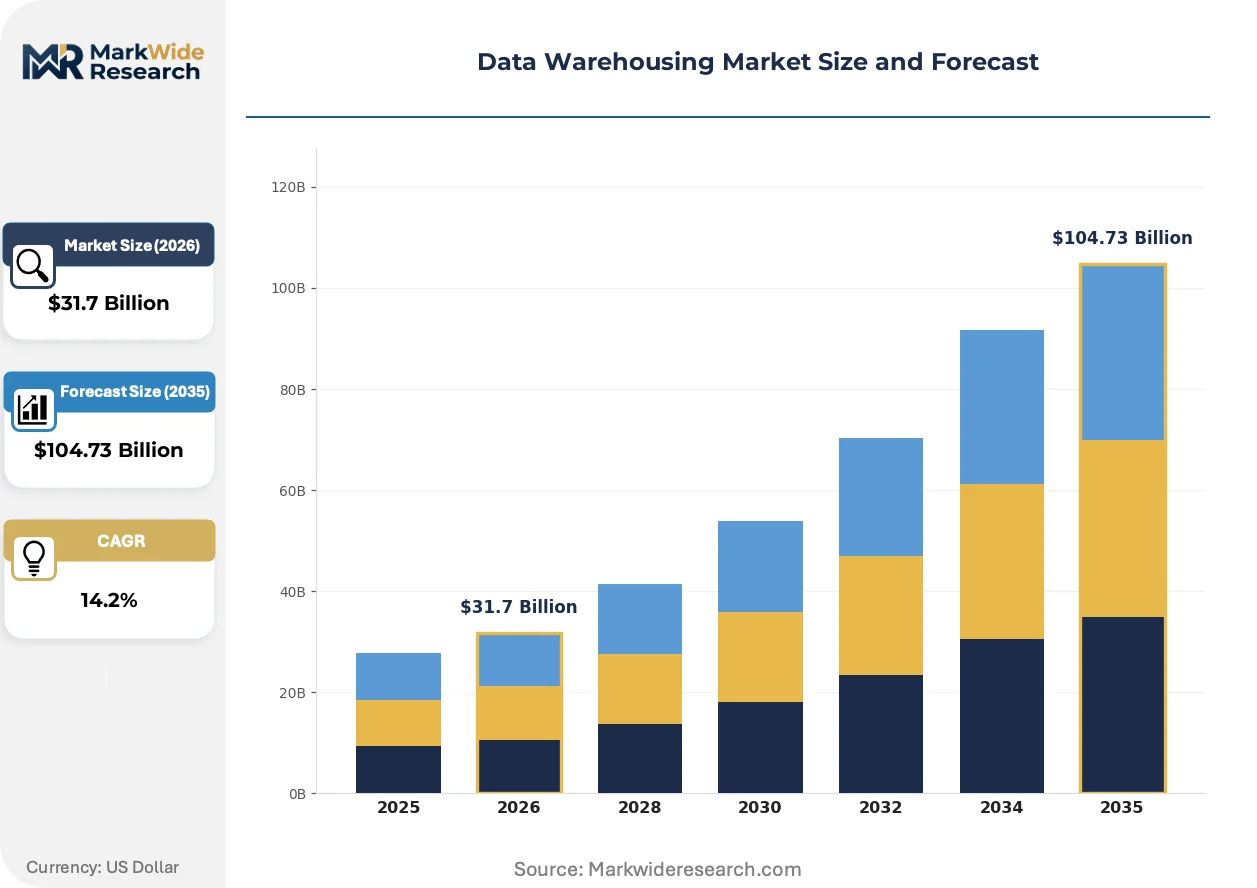
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $104.73 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Retail, Healthcare, BFSI, Manufacturing Solution: Data Integration, Data Migration, Business Intelligence, Data Governance Technology: SQL, NoSQL, Hadoop, In-Memory |
| Companies Covered | Snowflake, Amazon Redshift, Google BigQuery, Microsoft Azure Synapse, Databricks, Teradata, Oracle, IBM, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Warehousing Market Emerging Trajectories
Query processing architectures are fragmenting across specialized engines, with vendors racing to embed machine learning inference directly within storage layers.
Serverless query execution is decentralizing workload management from provisioned clusters toward auto-scaling compute pools. Capital markets firms at Goldman Sachs and JPMorgan Chase are piloting this for overnight risk batch jobs. The shift is compressing idle capacity costs and collapsing the distinction between development and production environments.
The EU AI Act's risk-based classification system is mandating audit trails for high-stakes automated decisions. Financial services firms must now maintain immutable query logs and model lineage documentation. Germany's BaFin and France's AMF are already inspecting warehouse metadata schemas for compliance readiness.
Consumption-based contracts are displacing three-year enterprise license agreements in procurement negotiations. Retail and logistics buyers now negotiate monthly commit levels with burst pricing for seasonal peaks. This pattern is most pronounced in the United States, where CFOs prioritize OpEx flexibility over capital efficiency metrics.
Data Warehousing Market Segmentation
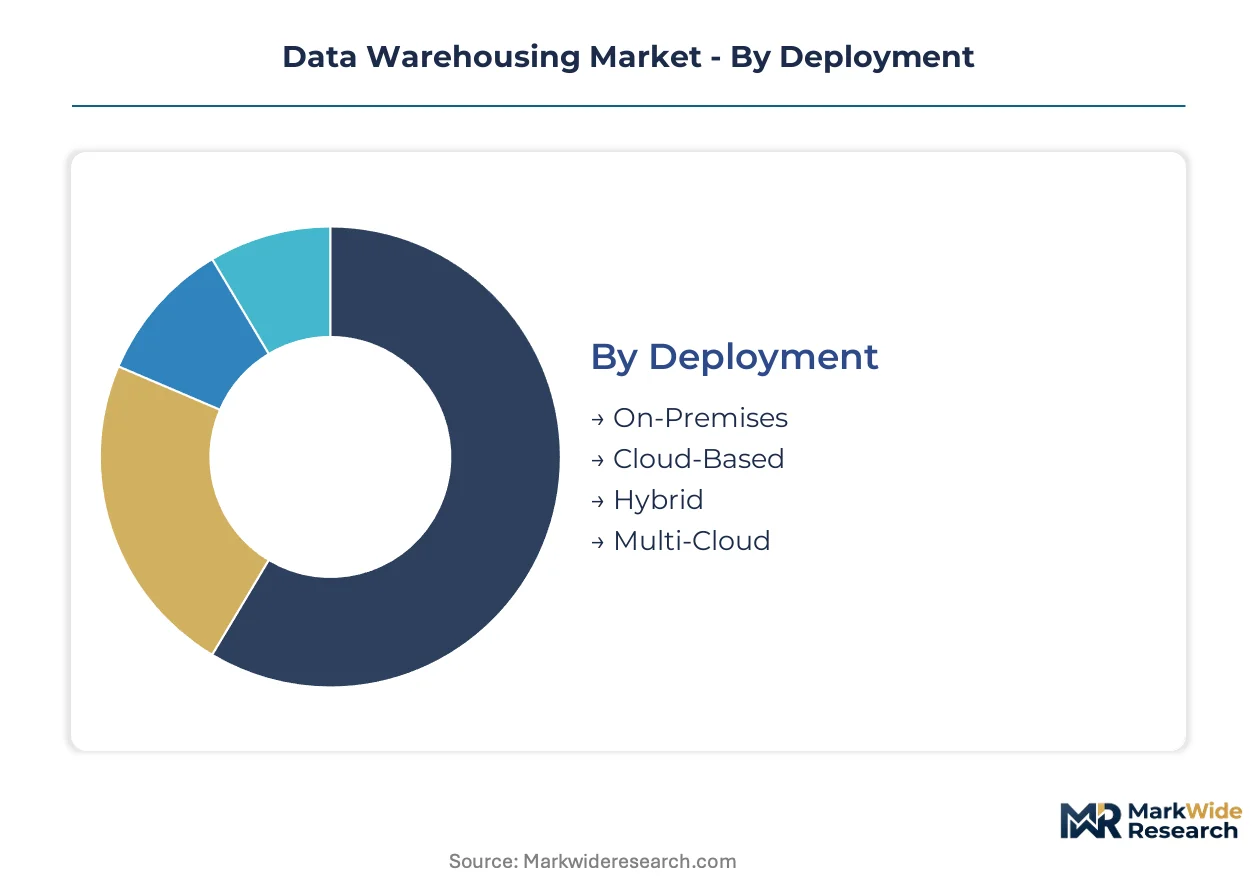
Segmentation in data warehousing reveals how compliance burdens, workload characteristics, and infrastructure economics fragment procurement decisions. Buyers prioritize different capabilities based on whether they face SEC recordkeeping rules, HIPAA audit requirements, or GDPR residency mandates.
Deployment:
HIPAA-covered entities and financial institutions under SEC 17a-4 face divergent certification paths for each deployment mode, with cloud-native architectures requiring HITRUST or SOC 2 Type II attestation that on-premises appliances bypass through physical control documentation.
- Cloud-Based:Separation of storage and compute billing enables workload-specific procurement without capital commitment. Demand concentrates in capital markets firms modernizing for Basel III liquidity reporting, where sub-second decisioning requirements favor elastic scaling over provisioned clusters.
- On-Premises:Teradata and Oracle appliance configurations retain loyalty in regulated enterprises with depreciated infrastructure and internal audit teams trained on physical access controls. Manufacturing firms with latency-sensitive shop-floor analytics sustain this segment despite cloud migration pressure.
- Hybrid:Blends residency-sensitive workloads on-premises with burst capacity in cloud regions, common among BFSI entities navigating GDPR extraterritoriality concerns.
- Multi-Cloud:Architectures spanning AWS, Azure, and GCP reduce vendor lock-in but impose data egress cost management discipline.
Leading the category by volume: Cloud-Based. Growing fastest: Multi-Cloud.
End User:
Cost tier differentiation separates enterprises with dedicated compliance officers from mid-market buyers prioritizing OpEx flexibility over certification depth.
- BFSI:Basel III mandates from the European Banking Authority and US SEC drive petabyte-scale investments with immutable query logging for model lineage. Goldman Sachs and JPMorgan Chase pilot serverless execution for overnight risk batch jobs.
- Healthcare:HIPAA audit trails and FDA 21 CFR Part 11 electronic record requirements filter vendor selection toward HITRUST-certified platforms, with cloud-native penetration lagging other sectors due to historical compliance caution.
- Retail:Seasonal demand volatility favors consumption-based contracts with monthly commit levels and burst pricing for peak periods.
- Manufacturing:Shop-floor IoT integration and supply chain traceability requirements concentrate demand in hybrid deployments balancing edge latency with centralized analytics.
Dominating procurement value: BFSI. Expanding most quickly: Healthcare as compliance barriers ease.
Solution:
Application maturity varies from commoditized ETL automation to emerging AI-ready pipeline requirements that embed vector indexing alongside traditional warehouse schemas.
- Data Integration:Automated pipeline orchestration is displacing traditional ETL engineering expertise, forcing workforce retraining investments as platforms absorb transformation logic.
- Business Intelligence:Convergence with machine learning inference layers opens new workloads for unified analytics platforms serving real-time decisioning in capital markets.
- Data Migration:Cloud exit from depreciated Teradata and Oracle appliances dominates project pipelines, constrained by specialized talent scarcity in massively parallel processing query optimization.
- Data Governance:EU AI Act audit trail mandates from Germany's BaFin and France's AMF elevate metadata schema inspection to regulatory priority.
Highest attach rate to new deployments: Data Integration. Steepest expansion trajectory: Data Governance.
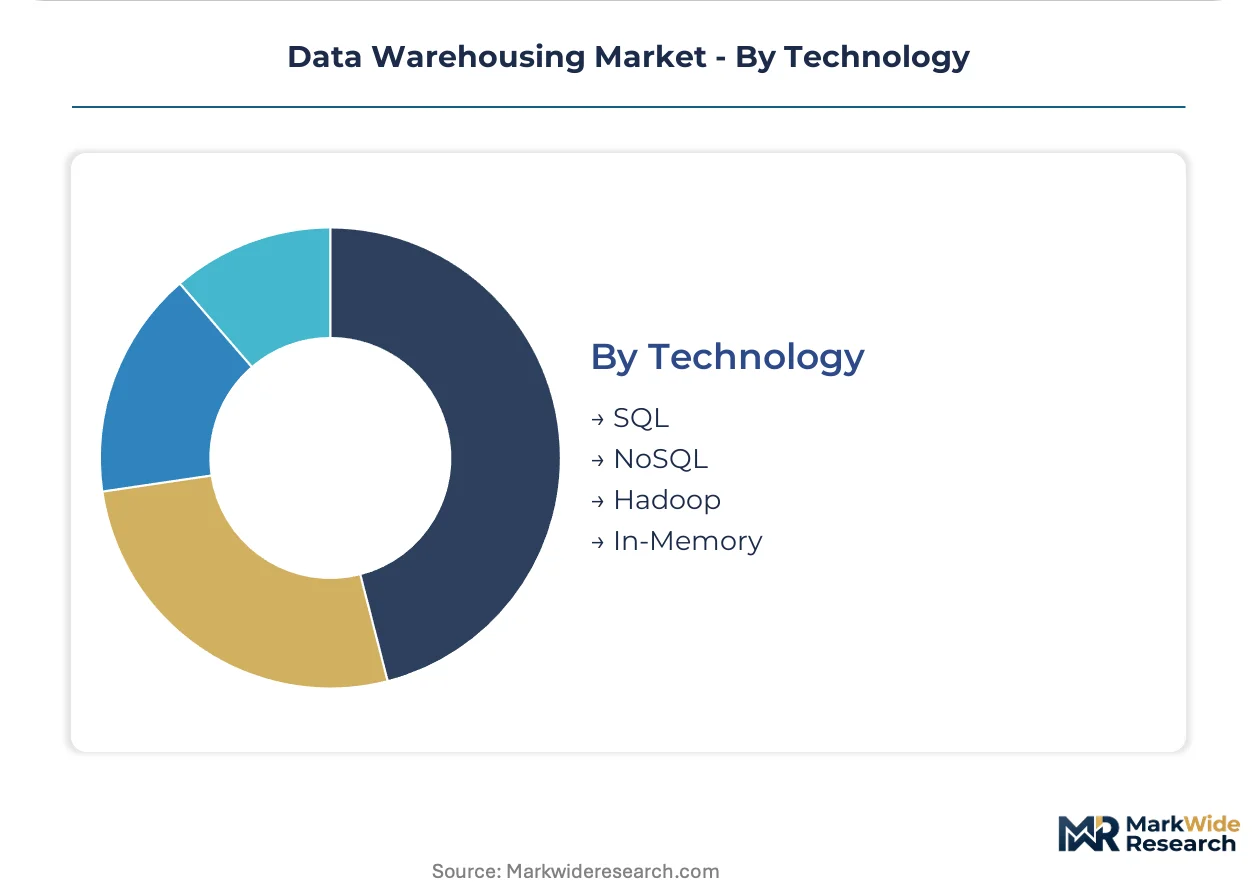
Technology:
Margin concentration follows performance tier differentiation, with in-memory commanding premium pricing for sub-second workloads while SQL standardization drives commoditization pressure.
- In-Memory:Columnar storage with sub-millisecond access latency serves high-frequency trading and real-time risk analytics in capital markets, representing a concentrated margin pool for specialized vendors.
- SQL:Massively parallel processing query optimization across ANSI-standard dialects enables workload portability but limits vendor differentiation to execution engine efficiency.
- NoSQL:Document and graph extensions accommodate semi-structured data pipelines from IoT and clickstream sources.
- Hadoop:Legacy batch processing architectures face displacement from cloud-native object storage query engines.
Commanding premium pricing: In-Memory. Standardizing fastest: SQL.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India scheme and Special Economic Zones in Bengaluru and Hyderabad are concentrating cloud infrastructure investment and data engineering talent pools for warehouse modernization projects.
United States
Capital markets firms at Goldman Sachs and JPMorgan Chase pilot serverless query execution for overnight risk batch jobs. The SEC's 17a-4 recordkeeping rules mandate immutable audit trails that filter vendor selection toward platforms with query logging capabilities. New York City's financial district and Seattle's cloud engineering corridor host the densest concentration of data warehouse procurement teams.
Germany
BaFin inspectors scrutinize metadata schemas for EU AI Act compliance readiness among Frankfurt-based banking groups. The country's central bank liquidity reporting requirements under Basel III drive petabyte-scale investments in sub-second decisioning infrastructure. Munich's automotive headquarters and Berlin's fintech clusters sustain hybrid deployment demand balancing GDPR residency with cloud burst capacity.
United Kingdom
The Financial Conduct Authority's operational resilience rules compel London-based insurers to modernize legacy Teradata appliances for real-time risk analytics. Post-Brexit data adequacy negotiations with Brussels create uncertainty in cross-border warehouse architectures. The City of London and Edinburgh's pension fund administration centers anchor concentrated procurement for regulatory reporting workloads.
India
The Digital Personal Data Protection Act forces global enterprises to deploy in-country infrastructure, benefiting regional cloud providers and hyperscaler Mumbai and Hyderabad availability zones. RBI guidelines on data localization for payment systems accelerate domestic warehouse construction. Bengaluru's enterprise software corridor and Gurgaon's banking back-offices drive specialist hiring in massively parallel processing query optimization.
Japan
METI's data free flow with trust initiative shapes multi-cloud architecture decisions for Tokyo-headquartered trading houses navigating cross-border analytics. The country's pharmaceutical regulator mandates GxP-compliant audit trails that elevate data governance platform selection criteria. Osaka's manufacturing IoT deployments and Fukuoka's emerging fintech district sustain demand for edge-integrated hybrid warehouse configurations.
Data Warehousing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement negotiations, with the former leveraging integrated database-to-warehouse pipelines and the latter exploiting separation of storage and compute billing. The market structure tilts toward consolidation as hyperscalers absorb workload-specific demand while legacy appliance vendors defend depreciated installed bases. Three archetypes dominate: cloud-native consumption-based platforms, integrated enterprise software suites, and workload-optimized on-premises configurations. Competitive intensity concentrates in M&A activity targeting AI-ready pipeline capabilities and strategic partnerships embedding vector database indexing alongside traditional warehouse schemas.
Within the cloud-native tier, Snowflake and Databricks exemplify the consumption-based billing model that attracts workload-specific procurement from capital markets firms. Teradata occupies a position representing legacy appliance loyalty among regulated enterprises with internal audit teams trained on physical access controls. Oracle anchors the integrated suite archetype through database-to-warehouse pipeline bundling that reduces procurement friction for large enterprise accounts.
| Leading Market Players |
|---|
| Snowflake |
| Amazon Redshift |
| Google BigQuery |
| Microsoft Azure Synapse |
| Databricks |
| Teradata |
| Oracle |
| IBM |
| SAP |
| Others |
Supply Flow & Price Mechanics
Massively parallel processing query optimization specialists concentrated in Bengaluru and Hyderabad drive labor-cost differentials that widen pricing-tier spreads between certified enterprise deployments and mid-market consumption-based contracts.
Pricing Analysis
Short lead-time premiums for immediate cloud region availability and spot inventory discounts for reserved capacity shape procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels separates HITRUST-certified platforms with dedicated compliance officers from self-service deployments. Cost compression in the standard tier intensifies because hyperscalers automate pipeline orchestration. Healthcare providers under HIPAA audit requirements show least price sensitivity, while retail logistics buyers prioritize OpEx flexibility and negotiate burst pricing for seasonal peaks.
Supply Chain Analysis
Regional distribution centers for hyperscaler availability zones follow hub-and-spoke patterns radiating from Northern Virginia, Frankfurt, and Mumbai. Infrastructure supply concentrates in the United States, Ireland, and Singapore for low-latency cloud regions. Raw material dependencies include specialized silicon for in-memory processing, high-bandwidth optical interconnects, and enterprise-grade storage arrays. Single-source vulnerability in GPU-accelerated query processing creates bottleneck risk. Distribution runs through direct hyperscaler procurement channels and systems integrators serving regulated enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Warehousing Market functions as a cost-of-compliance story where EU AI Act audit trail mandates create a barrier-to-entry moat for platforms with immutable query logging and model lineage documentation.
For Market Incumbents: Acquire vector database indexing capabilities to defend against AI-native entrants automating pipeline orchestration. Consolidate workload-optimized appliance loyalty among regulated enterprises by embedding EU AI Act metadata schema inspection tools. Prioritize certification investment in HITRUST and SOC 2 Type II attestation to maintain procurement friction for cloud-native challengers. For New Entrants and Emerging Players: Serverless query execution architectures offer a technology-first wedge into capital markets overnight risk batch jobs where Goldman Sachs and JPMorgan Chase pilot elastic scaling. Target healthcare analytics under HIPAA, the most underpenetrated segment for cloud-native warehousing due to historical compliance caution. Pursue consumption-based contracts with monthly commit levels as the go-to-market angle to bypass three-year enterprise license agreement incumbency. For Investors and Strategic Acquirers: Re-rating potential sits with AI-ready pipeline specialists given convergence of vector database indexing with traditional warehouse architectures. Long-term viability centers on platforms serving sub-second decisioning workloads in Basel III liquidity reporting environments. Watch for India's Digital Personal Data Protection Act enforcement as an inflection indicator forcing global enterprises toward in-country infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding vector database indexing alongside traditional warehouse schemas opens AI-ready workloads for unified analytics platforms. |
| Strategic Partnership | Collaborations with systems integrators trained on physical access controls sustain on-premises loyalty among regulated enterprises. |
| Acquisition of Specialist Firm | Buying massively parallel processing query optimization talent pools in Bengaluru accelerates migration velocity for cloud exits. |
| Geographic Expansion | Hyperscaler availability zone buildout in Mumbai and Hyderabad captures India's data localization mandate procurement. |
| Product Launch | Serverless query execution releases compress idle capacity costs for capital markets overnight risk batch jobs. |
Methodological Framework
Independent corroboration across primary interviews with data platform engineers, IT procurement officers, compliance officers at HIPAA-covered entities, and capital markets risk infrastructure leads underwrites the qualitative findings. Secondary validation draws from SEC 17a-4 recordkeeping guidance, EU AI Act implementation documents, BaFin inspection protocols, and hyperscaler capex disclosures. Bottom-up deployment mode sizing and top-down end-user spending estimates triangulate market dimensions.
Rate-of-change decomposition separates baseline growth from regulatory acceleration and technology substitution effects across the analysis window. Segmentation dimensions modeled include deployment mode, end-user vertical, solution type, and technology tier alongside regional adoption patterns shaped by data residency mandates. CAGRs derive from fitted growth curves against observed procurement velocity. Forecast inputs incorporate Basel III liquidity reporting deadlines and cloud migration mandates under GDPR and the US CLOUD Act.
Several conditions sit outside the modeled scope, including unannounced national data-localization statutes, hyperscaler pricing regime shifts, and breakthrough query engine architectures. Forecasts reflect documented assumptions about regulatory enforcement continuity and talent pool expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
South Korea Data Center Networking Market
Data Center and Networking
Chile Data Center Networking Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Global Cloud Content Delivery Network Market