
 Global Data Fabric Market | 2026-2036
Global Data Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Fabric Market Foresight
Multi-source data integration is broadening as enterprises abandon monolithic warehouse architectures for distributed mesh patterns. IBM Corporation leverages its Watson knowledge graph stack to anchor enterprise deployments across regulated industries. Oracle Corporation sustains competitive pressure through deep database-to-cloud integration, while Denodo Technologies specializes in data virtualization layers that decouple physical storage from logical access.
Data fabric denotes an architectural layer that automates data integration, governance, and orchestration across heterogeneous environments through active metadata and embedded AI-driven policy engines. The architecture typically enforces semantic consistency via knowledge graphs while enabling self-service data consumption without replication. Cloud-native deployment configurations now attract the fastest investment velocity as organizations retire on-premises maintenance burdens. Data governance and security offerings command premium positioning because regulatory exposure directly ties to audit-ready lineage and access controls. Real-time analytics use cases dominate operational workloads, though data virtualization for master data management is gaining traction among multinational enterprises with fragmented ERP estates.
The EU AI Act and GDPR impose strict requirements on training data provenance and automated decision transparency, compelling European enterprises to deploy governed data fabrics with embedded lineage tracking. In the United States, HIPAA and SEC cybersecurity disclosure rules shape healthcare and financial services procurement criteria, while China's NMPA and GB standards govern pharmaceutical data localization requirements. Stakeholders must evaluate metadata interoperability standards and regulator-specific certification pathways before committing to vendor architectures.
Market Dynamics
Hybrid cloud complexity is forcing enterprises to abandon monolithic data warehouses for distributed mesh architectures that automate integration across fragmented estates. The shift toward active metadata and embedded AI governance engines is compressing deployment timelines and reshaping vendor selection criteria.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy governed data fabrics with embedded lineage tracking to satisfy automated decision transparency requirements. Financial services firms face audit-ready provenance obligations.
- Real-time analytics workloads:Fortune 500 companies in the United States are investing in cloud-native fabrics to unify operational and analytical data without replication latency.
- Knowledge graph semantic layers:Healthcare and pharmaceutical organizations use graph-based consistency engines to reconcile fragmented ERP estates across multinational subsidiaries.
Market Restraints
- Specialized talent scarcity:Data engineering and metadata architecture expertise concentrates in technology hubs, inflating implementation costs for mid-market enterprises.
- Cloud egress fee volatility:Hyperscaler data transfer pricing creates unpredictable total cost of ownership for hybrid deployments spanning multiple platforms.
- Legacy system entrenchment:Decades-old on-premises data warehouses resist virtualization without expensive middleware layers and extended migration timelines.
Strategic Opportunities
- India's digital public infrastructure:The country's account aggregator framework and data empowerment architecture create demand for consent-aware fabric deployments in banking and insurance.
- Edge-to-cloud orchestration convergence:Manufacturing and logistics operators combine IoT stream processing with centralized governance for distributed supply chain visibility.
- Japan's METI data free flow initiatives:Cross-border data trust frameworks incentivize governed fabric architectures that satisfy both localization and interoperability requirements.
Industry Challenges
- Multi-cloud policy synchronization:Security teams struggle to enforce consistent access controls across AWS, Azure, and GCP environments without vendor lock-in.
- ISO 27001 and SOC 2 certification timelines:Audit preparation for metadata governance platforms extends sales cycles by six to twelve months in regulated industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Fabric Market |
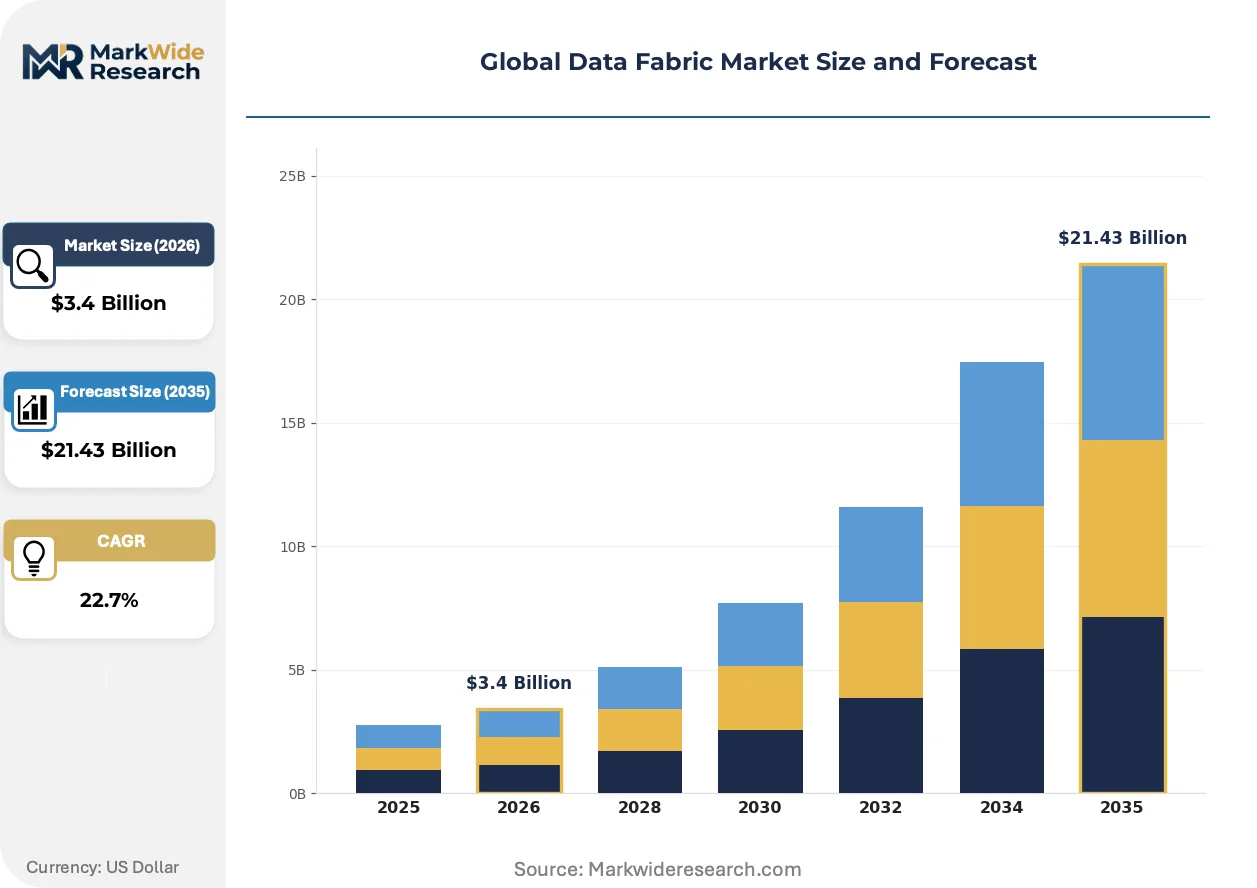
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Native, Hybrid Cloud, Multi-Cloud Solution/Offering: Data Integration, Data Governance, Data Orchestration, Metadata Management, Data Security Use Case: Real-Time Analytics, Data Virtualization, Master Data Management, Data Warehousing End User Industry: Telecommunications, Banking, Insurance, Energy, Government |
| Companies Covered | IBM Corporation, Oracle Corporation, Hewlett Packard Enterprise Company, SAP SE, NetApp Inc, Denodo Technologies, TIBCO Software Inc, Amazon Web Services, Cloudera Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Fabric Market Shifts & Advancements
Active metadata intelligence is displacing passive catalog approaches as the central nervous system of enterprise data architecture. Vendors are embedding machine learning directly into integration pipelines to automate schema discovery and policy enforcement.
Knowledge graphs with automated ontology management are electrifying semantic consistency across heterogeneous data sources. Pharmaceutical companies deploying these systems reduce master data reconciliation cycles from months to days. The technology is compressing time-to-insight for drug safety signal detection and regulatory submission preparation.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for high-stakes automated decisions. European healthcare providers and credit scoring agencies must maintain complete training data provenance records. Germany and France are seeing accelerated procurement of lineage-native fabric architectures to satisfy national regulator interpretations of the delegated acts.
Consumption-based pricing for data virtualization services is displacing perpetual license models in enterprise procurement. Chief data officers in the United States are unbundling storage costs from compute and governance layers to align spending with actual query volumes. This shift is most visible in financial services, where seasonal reporting spikes previously forced overprovisioning of on-premises infrastructure.
Global Data Fabric Market Segmentation
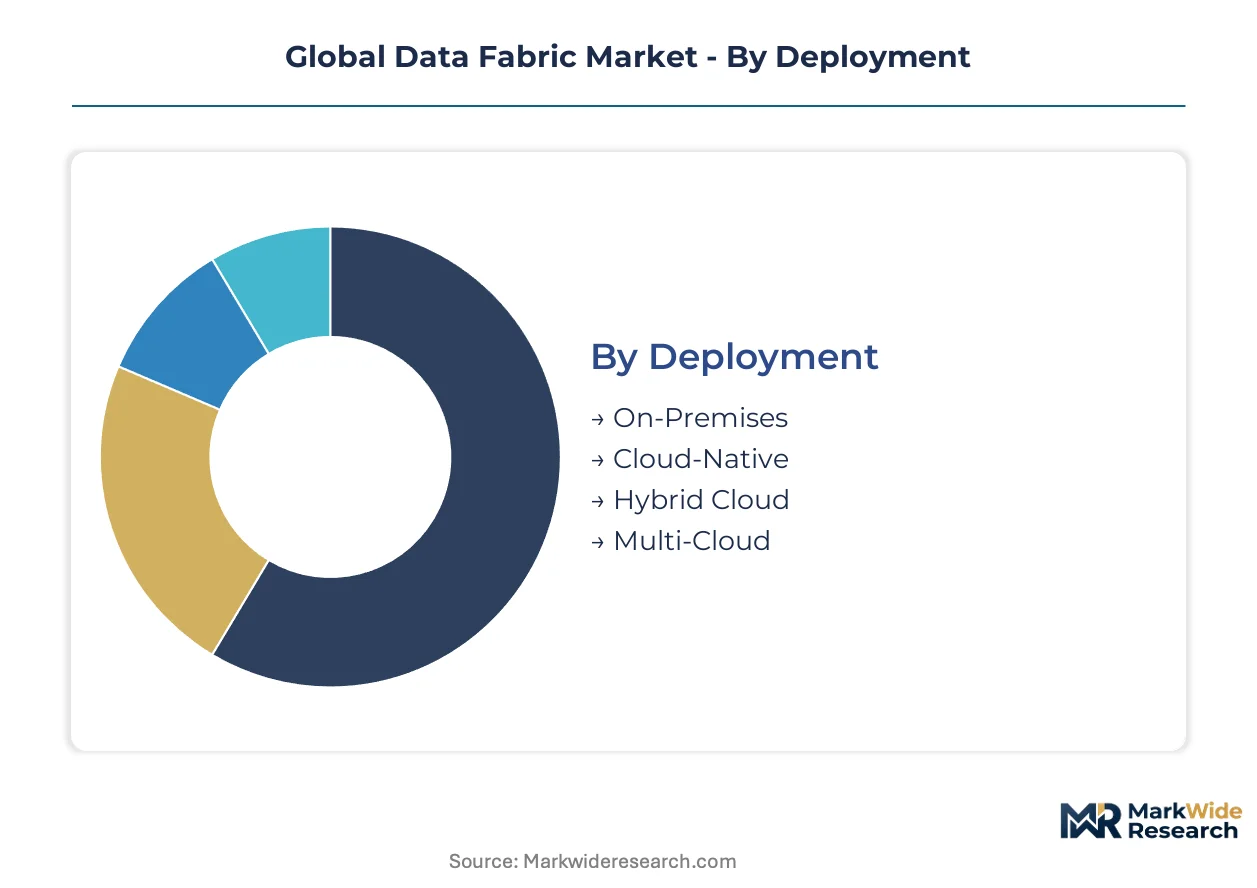
Data fabric architectures fragment across deployment topologies, functional layers, and operational use cases. Each segmentation dimension reveals distinct procurement patterns and integration complexity trade-offs.
Deployment:
Cloud-native configurations now anchor standalone implementations while hybrid and multi-cloud deployments embed fabric layers within existing infrastructure estates.
- On-Premises:Legacy installations persist in defense and classified government facilities where air-gapped security mandates physical data sovereignty. Banking regulators in Switzerland and Saudi Arabia require localized ledger storage for systemic risk monitoring.
- Cloud-Native:Containerized microservices architectures automate elastic scaling across Kubernetes orchestration layers. Fortune 500 enterprises in the United States prioritize consumption-based pricing and zero-downtime schema evolution.
- Hybrid Cloud:Split workloads synchronize sensitive on-premises transaction processing with cloud-based model training pipelines. German automotive manufacturers use this topology to satisfy GDPR data localization while accessing GPU clusters.
- Multi-Cloud:Policy abstraction layers prevent vendor lock-in across AWS, Azure, and GCP environments simultaneously. Volume placements concentrate in Cloud-Native; the faster expansion belongs to Multi-Cloud.
Cost stratification separates perpetual license commitments from metered consumption models.
Solution/Offering:
Functional modules range from infrastructure plumbing to governance control planes that command premium positioning.
- Data Integration:ETL/ELT pipeline automation with schema-on-read flexibility for unstructured sources. Demand clusters in telecommunications operators consolidating subscriber data across acquired subsidiaries.
- Data Governance:Embedded policy engines enforce lineage tracking and access certification for EU AI Act compliance. European banking supervisors mandate automated provenance documentation for credit scoring algorithms.
- Data Orchestration:Workflow scheduling across distributed compute clusters with dependency-aware execution. Energy utilities deploy these layers to synchronize smart meter ingestion with demand forecasting models.
- Metadata Management:Active catalog systems with automated business glossary propagation and impact analysis. Insurance carriers in Japan use METI-aligned frameworks for cross-border data trust verification.
- Data Security:Encryption key lifecycle management and dynamic data masking for field-level protection. HIPAA-covered entities in the United States require audit-ready access logs for OCR investigation response.
Procurement bundles concentrate in Data Integration; the steepest expansion trajectory belongs to Data Governance.
Use Case:
Operational workloads prioritize latency minimization while analytical patterns emphasize semantic consistency across fragmented sources.
- Real-Time Analytics:Sub-second query response on streaming operational data without ETL latency penalties. Investment banks in the United Kingdom deploy these fabrics for pre-trade risk limit monitoring.
- Data Virtualization:Logical data layers decouple physical storage from query execution without replication. Pharmaceutical companies reduce master data reconciliation cycles across multinational ERP estates.
- Master Data Management:Golden record consolidation for customer, product, and supplier domains with automated stewardship workflows. Volume placements concentrate in Real-Time Analytics; the fastest climb belongs to Data Virtualization.
- Data Warehousing:Modernized lakehouse architectures retiring legacy on-premises appliances through gradual migration paths.
Customer maturity separates early adopters from compliance-driven late entrants.
End User Industry:
Regulatory exposure intensity determines governance feature prioritization across vertical procurement.
- Telecommunications:Subscriber 360 platforms unifying OSS/BSS data for churn prediction and network optimization. India's TRAI mandates consent-aware data sharing through account aggregator frameworks.
- Banking:Real-time fraud detection fabrics integrating core banking, payments, and external threat intelligence. SEC cybersecurity disclosure rules shape vendor selection criteria for systemically important institutions.
- Insurance:Actuarial model governance with embedded lineage for Solvency II and state regulator examination readiness.
- Energy:Grid modernization integrating AMI data with distributed energy resource management systems. FERC Order 2222 compliance drives interoperability requirements for virtual power plant aggregation.
- Government:Citizen service platforms with classified data segmentation and FedRAMP authorization boundaries. Volume placements concentrate in Banking; the sharpest expansion belongs to Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler concentration anchors North American data fabric innovation, while European regulatory pressure and Asia-Pacific digital infrastructure investments reshape deployment patterns across three continents.
United States
Fortune 500 financial services firms and cloud hyperscalers drive cloud-native fabric adoption for real-time analytics workloads. SEC cybersecurity disclosure rules and HIPAA audit requirements shape procurement criteria for systemically important institutions. New York's investment banking cluster deploys sub-second risk monitoring fabrics, while Seattle's cloud engineering base advances Kubernetes-orchestrated metadata management.
Germany
Automotive manufacturers and industrial conglomerates demand hybrid cloud topologies that synchronize on-premises transaction processing with cloud GPU clusters. GDPR data localization mandates and national regulator interpretations of EU AI Act delegated acts accelerate lineage-native architecture procurement. Munich's automotive engineering corridor and Frankfurt's financial services hub concentrate deployment activity for governed data fabrics.
China
Pharmaceutical multinationals and state-owned enterprises navigate NMPA data localization requirements through governed fabric architectures. GB standards and dual carbon goals influence metadata interoperability specifications for cross-border data flows. Shanghai's biotech manufacturing base and Shenzhen's cloud infrastructure cluster drive demand for semantic consistency engines across fragmented ERP estates.
India
The account aggregator framework and data empowerment architecture create consent-aware fabric demand in banking and insurance sectors. RBI guidelines and TRAI data sharing mandates shape vendor selection for subscriber 360 platforms. Mumbai's financial services district and Bangalore's SaaS engineering base concentrate implementation of distributed mesh patterns for telecommunications operators.
Japan
Cross-border manufacturing supply chains and insurance actuarial operations require METI-aligned data trust frameworks. METI data free flow initiatives incentivize governed architectures satisfying both localization and interoperability requirements. Tokyo's insurance headquarters corridor and Osaka's precision manufacturing cluster deploy knowledge graph semantic layers for multinational ERP reconciliation.
Global Data Fabric Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors integrate active metadata engines with hyperscaler infrastructure. The vendor base organizes into three tiers: legacy enterprise software houses with database-to-cloud integration capabilities, cloud-native specialists in data virtualization layers, and hyperscalers embedding fabric services within platform ecosystems. Portfolio diversification and technology licensing represent the primary competitive vectors, with incumbents extending Watson knowledge graph stacks and challengers decoupling physical storage from logical access.
Within the legacy integration tier, IBM Corporation and Oracle Corporation exemplify database-centric archetypes that anchor enterprise deployments across regulated industries. Denodo Technologies occupies a specialist position in virtualization-native architectures, representing the decoupled-access archetype that reduces master data reconciliation cycles. These three entities collectively illustrate the competitive spectrum from deep infrastructure integration to semantic layer abstraction.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Hewlett Packard Enterprise Company |
| SAP SE |
| NetApp Inc |
| Denodo Technologies |
| TIBCO Software Inc |
| Amazon Web Services |
| Cloudera Inc |
| Others |
Supply & Pricing Matrix
Fortune 500 financial services procurement teams concentrate purchasing power for cloud-native fabric deployments, driving adoption of consumption-based SaaS pricing that unbundles storage from compute and governance layers. This buyer concentration compresses margins for perpetual license vendors while rewarding metered-service providers with elastic scaling architectures.
Pricing Analysis
Service bundling separates vendors offering embedded lineage tracking and automated policy enforcement from stripped-down integration-only tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by governance depth, with premium tiers commanding positioning for EU AI Act compliance mandates. Pricing pressure stems from hyperscaler-native alternatives embedding fabric services at marginal cost. Mid-market enterprises exhibit highest price sensitivity, while systemically important banks prioritize audit-ready provenance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from European banking supervisors mandate multi-cloud qualification across AWS, Azure, and GCP environments to prevent vendor lock-in. Software engineering talent concentrates in the United States, India, and Germany, with cloud infrastructure provisioning drawing from hyperscaler data center networks spanning Ireland, Singapore, and Virginia. Single-source vulnerability runs through active metadata engine development, where specialized expertise limits qualified supplier pools. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active metadata intelligence is displacing passive catalog approaches as the central architectural nervous system, with knowledge graph semantic layers replacing legacy ETL pipelines for master data reconciliation. This technology-transition phase compresses deployment timelines and reshapes vendor selection criteria toward AI-native governance engines.
For Market Incumbents: Deploy knowledge graph stack extensions to anchor enterprise deployments against cloud-native challengers. Deepen backward integration into Kubernetes orchestration layers to control elastic scaling economics. Invest in ISO 27001 and SOC 2 certification acceleration to shorten audit-driven sales cycles in European banking and US healthcare verticals.
For New Entrants and Emerging Players: Begin with India's account aggregator framework and data empowerment architecture, where consent-aware fabric demand outpaces established vendor presence. Target telecommunications operators consolidating subscriber data across acquired subsidiaries, a segment showing sharpest expansion trajectory. Pursue channel partnerships with systems integrators specializing in GDPR and EU AI Act compliance to bypass direct enterprise sales barriers.
For Investors and Strategic Acquirers: The window for entry favors virtualization-native specialists with semantic layer abstraction capabilities over database-centric legacy integrators. Long-term viability centers on vendors decoupling physical storage from logical access, as consumption-based pricing displaces perpetual licenses. Watch for inflection when European national regulators issue delegated act interpretations of EU AI Act training data provenance requirements, which will accelerate lineage-native architecture procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Knowledge Graph Stack Extension | Watson-based semantic layers anchor regulated industry deployments against cloud-native alternatives. |
| Consumption-Based Pricing Transition | Metered service models align spending with query volumes for seasonal financial reporting workloads. |
| Multi-Cloud Policy Abstraction | Prevents vendor lock-in across AWS, Azure, and GCP environments for European banking compliance. |
| Edge-to-Cloud Orchestration Convergence | Combines IoT stream processing with centralized governance for manufacturing supply chain visibility. |
| Certification Acceleration Investment | ISO 27001 and SOC 2 readiness shortens audit-driven sales cycles by six to twelve months. |
Research Methodology
Multi-period observation of vendor pricing model transitions and procurement pattern shifts anchored the trend analysis, supplemented by interviews with chief data officers, cloud platform engineers, regulatory compliance leads, and systems integration specialists. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act delegated act drafts, hyperscaler capex disclosures, and Gartner enterprise data management spending surveys. Bottom-up deployment topology modeling triangulated against top-down regulatory compliance spending estimates.
Input-output matrices mapped solution module demand across deployment configurations, functional layers, and end-user industries throughout the forecast period. Segmentation dimensions included cloud-native versus hybrid topologies, governance versus integration functional emphasis, and banking versus telecommunications vertical concentration. CAGRs derived from elasticity-adjusted adoption curves incorporating compliance mandate effective dates and technology replacement cycle timing. Industry-specific inputs encompassed EU AI Act risk classification implementation schedules and India's account aggregator framework rollout velocity.
Underlying measurement precision varies by segment; cloud-native deployment projections carry tighter precision than legacy on-premises migration estimates due to visible hyperscaler consumption data. Forecasts reflect assumptions regarding regulatory enforcement consistency and talent availability for metadata architecture roles. Deviation in EU AI Act delegated act interpretation timing or NMPA data localization enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Global Virtual Private Network Market