
 Global Navigation Satellite System (GNSS) Market | 2026-2036
Global Navigation Satellite System (GNSS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Navigation Satellite System (GNSS) Market Analysis
The capability gap between chip-scale module producers and full-stack positioning service providers is unwinding across the competitive landscape. Qualcomm Technologies leverages its integrated modem-GNSS silicon to dominate smartphone socket share, while Trimble anchors the high-precision surveying and construction segment through specialized hardware and correction services. Hexagon AB extends its reach by combining sensor fusion software with Leica Geosystems hardware, creating differentiated positioning ecosystems that smaller competitors struggle to replicate.
Global Navigation Satellite System refers to satellite constellations and augmentation infrastructure that transmit radio signals enabling receivers to determine position, velocity, and time with meter- to centimeter-level accuracy depending on service grade and correction methods. These systems serve commercial, military, and consumer applications requiring geospatial awareness, from autonomous navigation to precision timing for telecommunications networks. GPS technology occupies the most mature position with broadest device compatibility, while BeiDou integration is gaining traction fastest in Asia-Pacific industrial deployments as Chinese terminal manufacturers expand export volumes. The military end-user segment concentrates the highest margin pools due to encrypted signal requirements and anti-jam specifications, though commercial applications generate substantially larger unit volumes across logistics and precision agriculture.
The FCC in the United States mandates interference protection for GPS signals through spectrum management rules, while the EU's Radio Equipment Directive imposes cybersecurity and resilience standards on GNSS-enabled equipment sold within member states. Japan's MIC coordinates QZSS augmentation service deployment to enhance GPS availability in urban canyons and mountainous terrain. Stakeholders must monitor evolving spectrum allocation debates and multi-constellation interoperability mandates as these regulatory choices will determine which receiver architectures achieve market access across major economies.
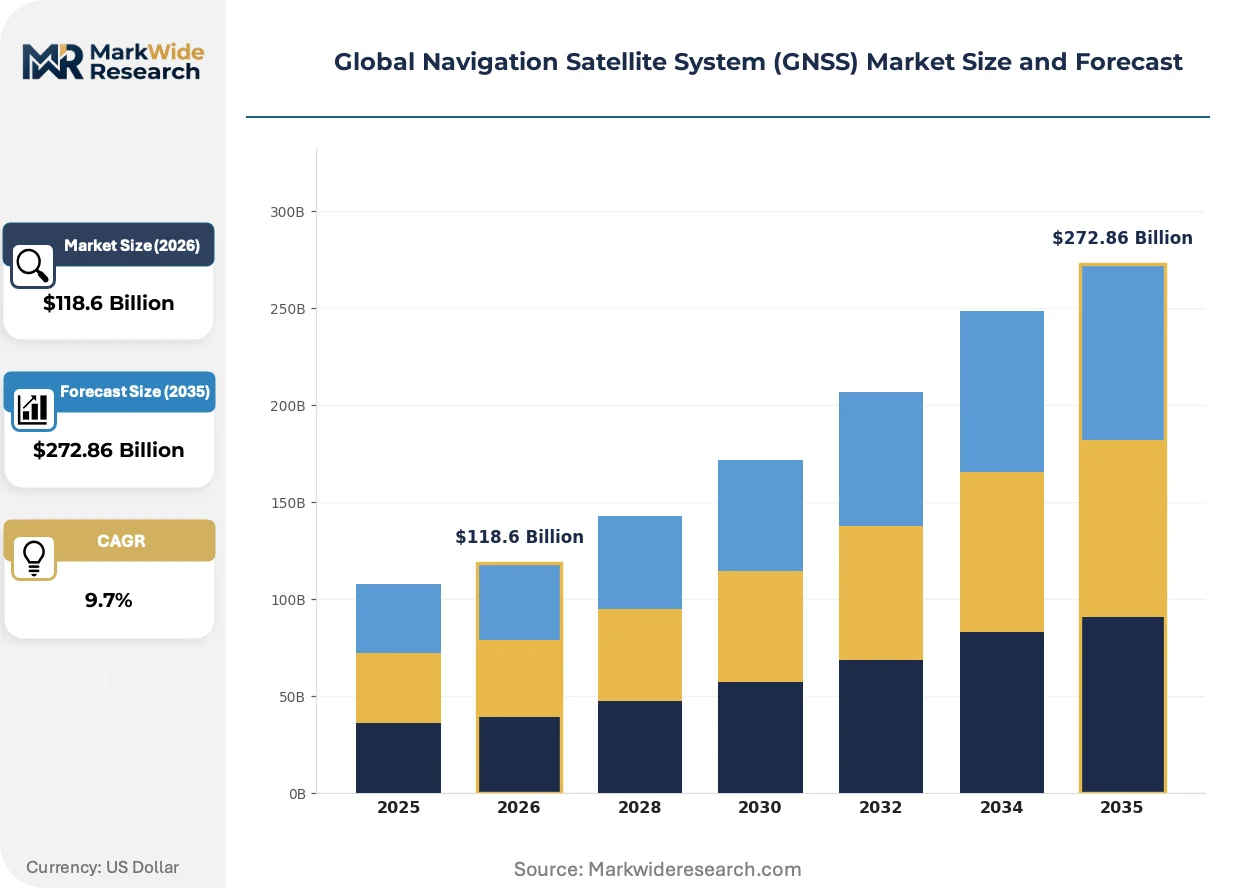
Market Dynamics
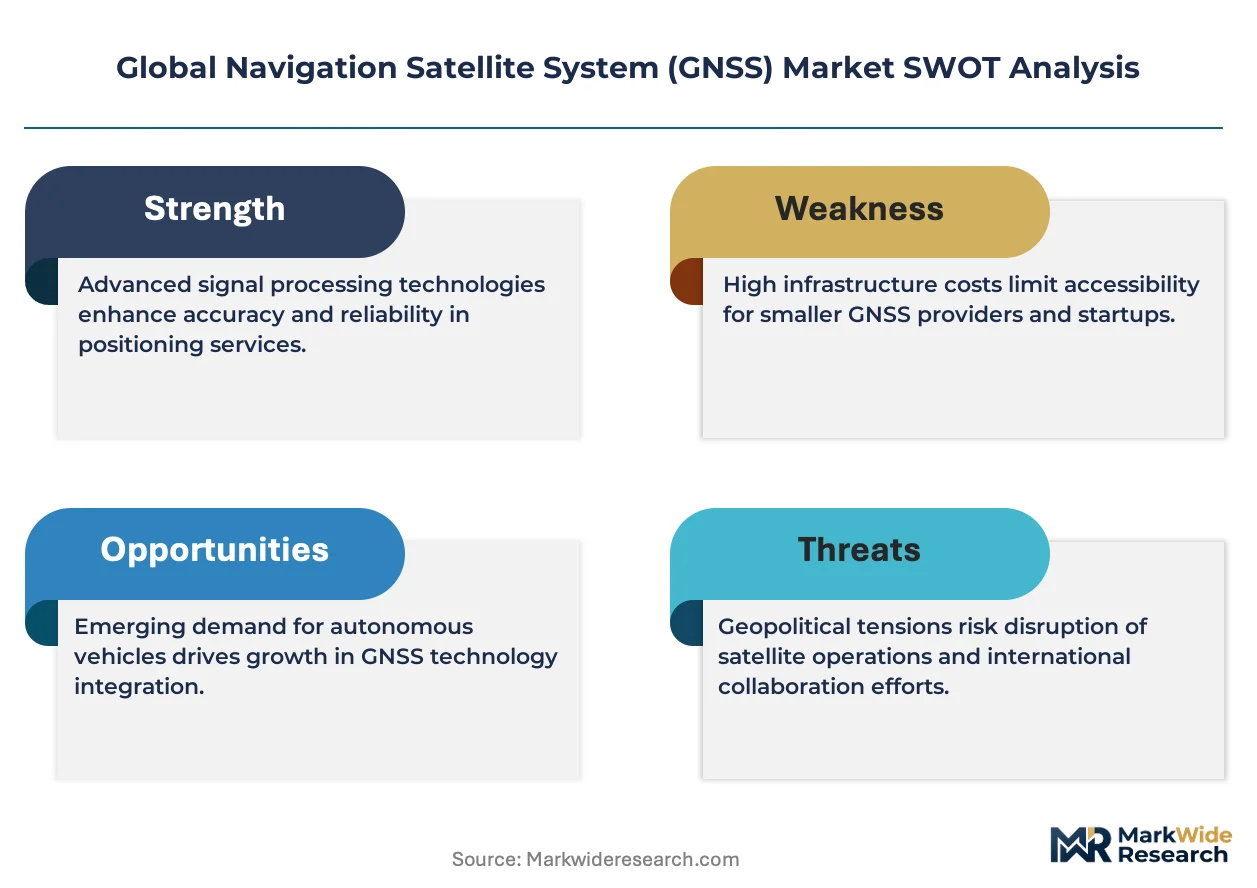
The GNSS market is reshaping around multi-constellation interoperability mandates and cybersecurity certification requirements that are fragmenting receiver architectures across major economies. Military procurement specifications for anti-jam capabilities and encrypted signal access are compressing supplier margins while elevating technical barriers to entry.
Growth Catalysts
- EU Radio Equipment Directive cybersecurity mandates:Resilience standards for GNSS-enabled equipment are forcing hardware redesigns that favor established vendors with certification expertise. German automotive fleets are accelerating multi-constellation receiver deployment to meet these requirements.
- Japan's QZSS augmentation infrastructure:The MIC-coordinated service expansion is creating precision agriculture demand clusters in mountainous terrain where GPS availability was previously unreliable. Domestic terminal manufacturers are scaling production to capture this pull.
- Chip-scale integration advances:Modem-GNSS silicon convergence is reducing bill-of-materials costs for smartphone and IoT device manufacturers. This process innovation is expanding addressable markets for location-aware consumer electronics.
Market Restraints
- High-precision component supply concentration:Specialized atomic clock and RF front-end manufacturing clusters in select East Asian economies create geopolitical exposure for Western receiver assemblers.
- Spectrum interference vulnerability:Adjacent-band 5G deployments in the United States threaten GPS signal integrity in urban environments, forcing expensive filtering hardware upgrades.
- Optical and inertial navigation substitutes:Lidar-visual-inertial odometry systems are capturing indoor and dense-urban positioning applications where satellite visibility degrades.
Strategic Opportunities
- Indian precision agriculture penetration:The country's farming sector remains underpenetrated by RTK-guided equipment, creating whitespace for correction service providers. The PLI scheme for electronics manufacturing offers domestic assembly incentives.
- Sensor fusion software convergence:Integration of GNSS with IMU and camera inputs is enabling lane-level navigation for autonomous last-mile delivery vehicles in Japanese and German urban deployments.
- Telecom timing synchronization demand:5G network densification is creating new demand for GNSS-disciplined oscillators in base station infrastructure across multiple continents.
Industry Challenges
- RF systems engineering talent scarcity:The specialized skill set for low-noise amplifier and antenna design is concentrating at legacy defense contractors, constraining commercial vendor hiring pipelines.
- Multi-constellation certification timelines:Receiver qualification for simultaneous GPS, Galileo, BeiDou, and GLONASS operation extends product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Navigation Satellite System (GNSS) Market |
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $272.86 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Agriculture, Automotive, Surveying Technology: GPS, GLONASS, Galileo, BeiDou End User: Government, Commercial, Military, Consumer Service Type: GNSS Data Processing, GNSS Integration, Positioning Services, Navigation Services |
| Companies Covered | Qualcomm Technologies, Trimble, Texas Instruments, Broadcom, STMicroelectronics, MediaTek, Hexagon AB, L3Harris Technologies, Garmin International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Navigation Satellite System (GNSS) Market Emerging Trajectories
Dual-frequency receiver architectures are displacing legacy single-band designs across precision applications, while regulatory cybersecurity mandates are fragmenting hardware roadmaps. The competitive landscape is bifurcating between commodity chip-scale modules and specialized high-precision systems.
Multi-frequency L1/L5/E5a reception is displacing single-frequency positioning in agricultural and surveying equipment. John Deere and Trimble are retrofitting their precision agriculture fleets with these receivers to achieve centimeter-level accuracy without RTK dependency. The technology is displacing subscription-based correction services in cost-sensitive emerging markets.
The EU's Radio Equipment Directive cybersecurity certification is mandating secure boot and anti-tamper hardware for all GNSS-enabled devices sold in member states. Industrial IoT and automotive OEMs are redesigning product lines to incorporate trusted execution environments. German and French regulators are enforcing these standards most aggressively, creating a two-tier market with non-compliant equipment locked out.
Buyer procurement patterns are compressing toward integrated positioning-service bundles rather than discrete hardware purchases. Construction and logistics fleets in Japan are demanding guaranteed accuracy SLAs from vendors, shifting risk onto solution providers. This behavior is most pronounced in autonomous vehicle trials where operators penalize position-availability failures financially.
Global Navigation Satellite System (GNSS) Market Segmentation
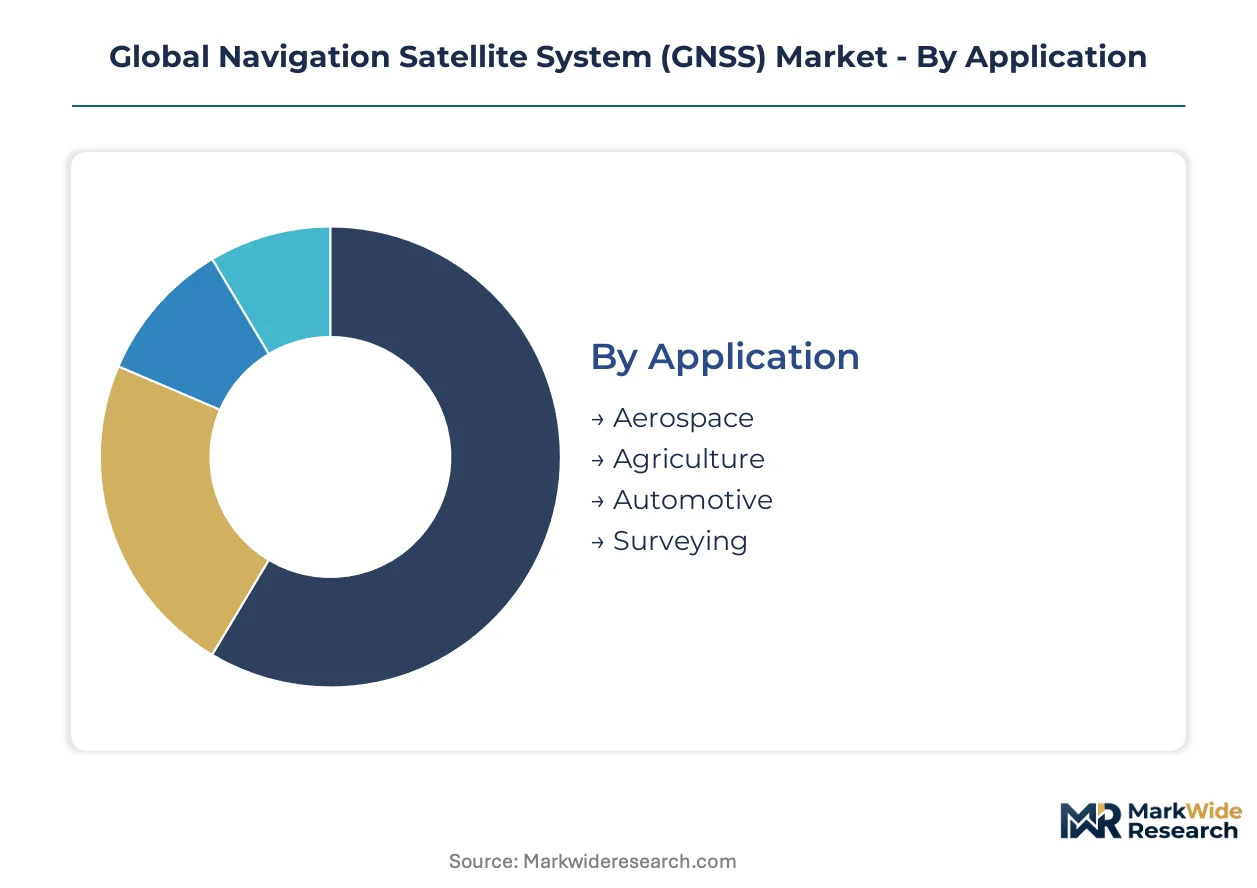
GNSS market segmentation reveals how positioning requirements fragment across precision grades, constellation dependencies, and security classifications. Each dimension carries distinct substitution vulnerabilities and margin structures that reshape competitive positioning.
Application:
Optical-inertial navigation substitutes threaten satellite-dependent segments most aggressively in dense urban and indoor environments, forcing GNSS vendors to defend core value propositions through augmentation and sensor fusion.
- Aerospace:Flight management systems demand aviation-certified multi-constellation receivers with integrity monitoring and fault detection. Demand concentrates in commercial airframe retrofits across Germany and Japan as airlines modernize fleets to meet EU Radio Equipment Directive resilience standards. Anti-jam specifications for military aviation sustain premium pricing tiers.
- Agriculture:Autosteering and variable-rate application systems require centimeter-level accuracy via RTK or PPP-RTK correction services. Japanese precision farming clusters in mountainous terrain drive QZSS-augmented receiver deployment, displacing subscription-based correction models with dual-frequency L1/L5 architectures.
- Automotive:Lane-level navigation for autonomous fleets mandates multi-frequency reception with cybersecurity-certified secure boot hardware.
- Surveying:Geodetic-grade receivers with tilt compensation and IMU fusion address construction staking and cadastral mapping.
Agriculture retains volume leadership; automotive holds the steepest expansion curve.
Technology:
Cost tier stratification separates legacy single-constellation modules from premium multi-system architectures, with certification complexity determining accessible market tiers.
- GPS:The mature L1 C/A and L5 civil signal infrastructure dominates consumer electronics and legacy industrial installations. Broad device compatibility sustains installed base dominance across United States logistics and timing applications, though L-band interference from adjacent 5G spectrum forces filtering hardware upgrades in urban deployments.
- BeiDou:B1I/B1C and B2a signal sets achieve fastest industrial penetration through Chinese terminal manufacturer export expansion. Asia-Pacific precision agriculture and construction equipment integration accelerates as domestic assemblers leverage cost-optimized chip-scale modules.
- GLONASS:FDMA signal architecture provides cold-start acquisition advantages in high-latitude regions.
- Galileo:E1/E5a open service and commercial authentication signals drive EU regulatory compliance requirements.
GPS retains volume leadership; BeiDou holds the steepest expansion curve.
End User:
Margin concentration varies sharply across security classification tiers, with encrypted signal access creating defensible supplier positions.
- Military:M-code and PRS signal access demands anti-jam antenna arrays and assured PNT hardware. United States DoD procurement specifications compress supplier margins while elevating technical barriers through NSA certification requirements. Geopolitical supply chain controls on atomic clock components concentrate risk.
- Commercial:Fleet management, precision agriculture, and construction generate largest unit volumes across logistics and surveying segments. Japanese and German automotive OEMs mandate cybersecurity-certified receivers under EU Radio Equipment Directive and national type-approval frameworks.
- Government:Civil infrastructure timing and emergency response systems require resilience-hardened architectures.
- Consumer:Smartphone and wearable integration drives commodity chip-scale module volumes through modem-GNSS silicon convergence.
Commercial retains volume leadership; military holds the steepest margin expansion curve.
Service Type:
Customer procurement patterns compress toward integrated bundles that shift availability risk onto solution providers.
- Positioning Services:RTK network subscriptions and PPP-RTK correction streams deliver centimeter-level accuracy without dedicated base stations. Japanese construction fleets demand guaranteed accuracy SLAs, forcing Trimble and Hexagon to underwrite position-availability failures financially.
- Navigation Services:Turn-by-turn routing and traffic-enhanced guidance concentrate in automotive OEM contracts and smartphone platform integrations.
- GNSS Data Processing:Post-processed kinematic solutions and precise point positioning software serve surveying and geodetic applications.
- GNSS Integration:Sensor fusion middleware combining satellite signals with IMU, camera, and lidar inputs enables lane-level autonomy.
Navigation Services retains volume leadership; GNSS Integration holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. Germany prioritizes automotive-grade cybersecurity certification, Japan drives precision agriculture through QZSS augmentation, the United States concentrates military procurement, China accelerates BeiDou industrial exports, and India cultivates domestic assembly incentives.
Germany
Autonomous vehicle fleets and industrial IoT deployments create dual demand streams for multi-constellation receivers. The KBA enforces EU Radio Equipment Directive cybersecurity standards through national type-approval frameworks, mandating secure boot architectures. Stuttgart and Munich automotive clusters are retrofitting production lines for resilience-hardened GNSS modules.
Japan
Mountainous terrain precision agriculture and urban canyon navigation drive QZSS-augmented receiver adoption. The MIC coordinates augmentation service expansion to enhance GPS availability where satellite visibility degrades. Nagoya manufacturing clusters are scaling domestic terminal production to capture agricultural demand pull.
United States
Military assured-PNT procurement and commercial logistics timing applications sustain dual demand tracks. The FCC mandates GPS interference protection through spectrum management rules governing adjacent-band 5G deployments. Defense contractor concentrations in California and Arizona anchor anti-jam receiver development programs.
China
Industrial equipment exports and domestic infrastructure timing drive BeiDou B1I/B2a signal adoption fastest among Asia-Pacific deployments. The MIIT coordinates constellation interoperability standards through national GB certification frameworks. Shenzhen and Shanghai terminal manufacturers are expanding chip-scale module export volumes.
India
Underpenetrated precision agriculture and emerging telecom timing synchronization create whitespace for correction service providers. The PLI scheme for electronics manufacturing offers domestic assembly incentives for receiver production. Karnataka and Tamil Nadu industrial corridors are attracting GNSS module fabrication investments.
Global Navigation Satellite System (GNSS) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the GNSS competitive structure. Qualcomm Technologies and Hexagon AB occupy the integrated positioning ecosystem space, combining silicon with service layers, while Trimble anchors specialized high-precision hardware. The specialist tier fragments across chip-scale module producers, correction service operators, and sensor fusion software vendors. Competitive moves concentrate on M&A for correction network assets and strategic partnerships for multi-constellation certification expertise.
Within the integrated ecosystem tier, Qualcomm Technologies exemplifies modem-GNSS silicon convergence, while Hexagon AB represents sensor fusion software combined with hardware distribution. Among precision specialists, Trimble occupies a position anchoring high-precision surveying and construction segments. These three companies illustrate how capability bundling separates leaders from commodity module competitors.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| Trimble |
| Texas Instruments |
| Broadcom |
| STMicroelectronics |
| MediaTek |
| Hexagon AB |
| L3Harris Technologies |
| Garmin International |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with East Asian foundries lock in atomic clock and RF front-end supply while fixing component costs for receiver assemblers navigating EU Radio Equipment Directive compliance cycles. These arrangements concentrate procurement power among vendors with certification expertise, compressing margins for smaller players unable to secure similar terms.
Pricing Analysis
Project-based hardware sales with recurring correction service subscriptions dominate commercial segments, while military procurement runs through multi-year indefinite-delivery contracts. Pricing stratifies across cybersecurity-certified premium tiers, dual-frequency standard tiers, and single-frequency economy modules. Cost compression in commodity chip-scale segments is intensifying because modem-GNSS silicon convergence reduces differentiation headroom. Fleet operators in logistics and construction exhibit highest price sensitivity, whereas military buyers prioritize signal assurance over unit economics.
Supply Chain Analysis
Inventory buffers for specialized atomic clock components extend lead times to 26-32 weeks, constraining receiver production scheduling. Manufacturing concentrates in China, Taiwan, and South Korea for chip-scale modules, with precision RF front-end fabrication anchored in Japan and Germany. The chain draws from rubidium oscillator substrates, GaAs amplifier wafers, and ceramic antenna substrates. Single-source vulnerability for space-qualified atomic clocks creates geopolitical exposure. Distribution runs through authorized component distributors serving Tier 1 automotive and aerospace OEMs directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in sensor fusion software and QZSS-augmented precision agriculture creates runway for positioning-service bundling ahead of mainstream autonomous vehicle deployment.
For Market Incumbents: Secure correction network infrastructure in Japan and Germany through acquisition or exclusive partnership, insulating against optical-inertial navigation substitutes in dense urban environments. Prioritize backward integration into secure boot hardware to meet EU Radio Equipment Directive mandates faster than modular competitors. For New Entrants and Emerging Players: Anchor in India's underpenetrated precision agriculture sector, where RTK-guided equipment penetration remains below comparable Asian markets. Pursue correction service provider partnerships rather than hardware manufacturing, leveraging PLI scheme incentives for domestic assembly without capital-intensive fab investments. For Investors and Strategic Acquirers: Multi-constellation certification consultancies with NSA and EU cybersecurity authority relationships represent the most defensible acquisition targets. Long-term viability hinges on regulatory compliance moats widening faster than silicon integration commoditizes positioning hardware. Monitor German KBA type-approval timelines as inflection indicator for which receiver architectures achieve market access.| Strategic Initiative | Industry Significance |
|---|---|
| Correction Network Acquisition | Locks in recurring revenue from Japanese construction fleets demanding accuracy SLAs. |
| Cybersecurity Certification Investment | Accelerates EU Radio Equipment Directive compliance ahead of KBA enforcement deadlines. |
| Sensor Fusion Software Development | Enables lane-level navigation contracts with Stuttgart autonomous vehicle trials. |
| Multi-Constellation Receiver Qualification | Expands addressable market across GPS, Galileo, BeiDou, and GLONASS interoperability mandates. |
| Domestic Assembly Partnership | Captures PLI scheme incentives in Karnataka and Tamil Nadu industrial corridors. |
Methodological Framework
Operator-level perspectives from GNSS receiver procurement managers, automotive platform engineers, precision agriculture fleet operators, and defense contractor program managers anchored the qualitative base. Primary interview findings triangulated against secondary sources including FCC spectrum allocation dockets, EU Radio Equipment Directive implementation guidance, Japan MIC QZSS service bulletins, and SEC filings from positioning technology vendors. Bottom-up unit demand modeling across smartphone, automotive, and industrial equipment channels converged with top-down market sizing from constellation operator service revenue disclosures.
Sensitivity analysis around 5G interference scenarios and BeiDou export penetration rates tested forecast robustness across the projection horizon. Segmentation dimensions modeled include application precision grade, constellation dependency, security classification, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and emerging use case adoption curves. Industry-specific inputs incorporated QZSS augmentation coverage expansion timelines and EU cybersecurity certification backlog estimates.
Material uncertainties — spectrum reallocation decisions, export control expansions on atomic clock technology, and autonomous vehicle regulatory approvals — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding multi-constellation receiver qualification timelines and correction service pricing trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Coherent Radar Market