
 Space Oscillator Market | 2026-2036
Space Oscillator Market Size, Share, and Industry Trends Forecast 2026-2036
Space Oscillator Market Analytics
The EU Green Deal's orbital debris mitigation guidelines is rebalancing procurement criteria toward longer-lifecycle oscillator designs with verified end-of-life disposal plans. SiTime Corporation leverages MEMS fabrication expertise to compete in radiation-tolerant product tiers. Microchip Technology anchors defense-grade supply chains through in-house qualification protocols. Vectron International differentiates via heritage qualification records on geostationary satellite programs.
A space oscillator generates precise frequency references through quartz crystal, atomic, MEMS, or optical resonator architectures, typically achieving stability measured in parts per billion to enable navigation signal coherence and payload synchronization across orbital thermal extremes. Quartz oscillators dominate current satellite bus deployments due to proven radiation tolerance and supply chain maturity, while MEMS oscillators attract redesign interest for smallsat volume constraints where size and power budgets tighten. Optical oscillators occupy emerging scientific payloads where femtosecond timing precision enables interferometric measurements.
NASA's Goddard Space Flight Center enforces GSFC-STD-7000 reliability standards that dictate thermal vacuum screening protocols, while the FCC's orbital debris rules shape mission lifetime specifications affecting oscillator redundancy architectures. ESA's ECSS-Q-ST-60-02C qualification framework constrains European supplier material selections and traceability documentation. Stakeholders must monitor evolving ITU spectrum allocation proceedings and national space traffic management regulations that will determine constellation density limits and corresponding oscillator volume forecasts.
Market Dynamics
Radiation-hardened MEMS oscillators are compressing qualification timelines for low Earth orbit constellations, forcing quartz heritage suppliers to accelerate redesign cycles or cede volume to semiconductor fabrication approaches.
Growth Catalysts
- Artemis Program Procurement:NASA's lunar infrastructure buildout is generating sustained demand for timing devices qualified to GSFC-STD-7000 thermal vacuum standards, with prime contractors consolidating oscillator specifications across crewed and robotic missions.
- REACH Material Compliance:The EU Green Deal's orbital debris mitigation guidelines are mandating verified end-of-life disposal plans, favoring oscillator designs with extended operational lifecycles and traceable material provenance.
- Optical Frequency Combs:Femtosecond-precision interferometric payloads for gravitational wave detection and deep-space navigation are opening scientific instrument tiers beyond traditional telecom timing applications.
Market Restraints
- Quartz Crystal Supply Concentration:High-purity synthetic quartz feedstock production clusters in limited geographic corridors, exposing oscillator manufacturers to single-source fragility for radiation-tolerant resonator blanks.
- ECSS Qualification Burden:ESA's ECSS-Q-ST-60-02C framework imposes multi-year material traceability documentation requirements that extend European supplier lead times relative to alternate qualification pathways.
- Atomic Clock Substitution:Chip-scale atomic reference technologies are encroaching on precision tiers historically served by oven-controlled crystal oscillators in navigation payload applications.
Strategic Opportunities
- Indian Constellation Expansion:ISRO's commercial launch cost advantages are attracting regional smallsat operators seeking domestic oscillator procurement channels outside established US and European supply chains.
- Dual-Use Technology Convergence:Defense-grade radiation tolerance specifications and commercial volume manufacturing economics are converging through MEMS fabrication process transfers from terrestrial telecom applications.
- Clean Space Incentive Alignment:ESA's debris mitigation certification is creating preferential procurement scoring for oscillator suppliers with demonstrated passive deorbit mechanism integration and verified radiation tolerance degradation curves.
Industry Challenges
- Radiation Effects Modeling Talent:The specialized workforce capable of predicting total ionizing dose and single-event upset behavior in resonator architectures remains concentrated within national laboratory and heritage defense contractor environments.
- ITAR Classification Complexity:US State Department jurisdiction determinations for space-qualified timing components create licensing friction that delays non-US payload integrator access to precision frequency references.
- Heritage Qualification Transfer:Geostationary satellite program performance records do not automatically translate to low Earth orbit thermal cycling profiles, forcing redundant qualification campaigns for constellation-scale deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Oscillator Market |
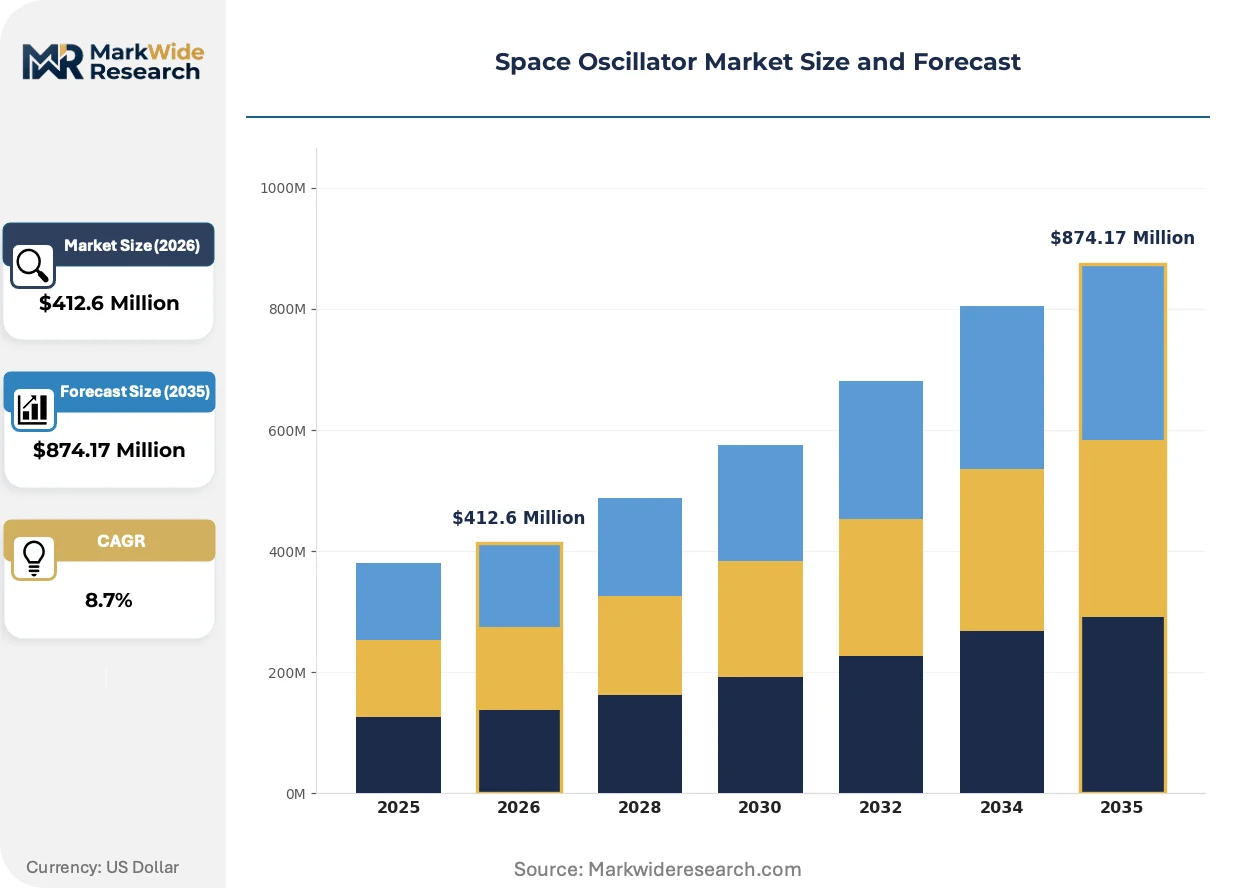
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quartz Oscillators, Atomic Oscillators, MEMS Oscillators, Optical Oscillators Technology: Satellite Communications, Space Navigation, Remote Sensing, Scientific Research Application: Aerospace, Defense, Telecommunications, Earth Observation End User: Government, Private Sector, Research Institutions, Space Agencies |
| Companies Covered | SiTime Corporation, Microchip Technology, Vectron International, Abracon Holdings, Bliley Technologies, Rakon Limited, Murata Manufacturing, Seiko Epson Corporation, Nihon Dempa Kogyo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Oscillator Market Evolving Landscape
Silicon MEMS fabrication is disrupting oscillator architectures across orbital applications, compressing form factors and power budgets while forcing qualification framework updates to accommodate non-quartz resonator physics.
MEMS-based temperature-compensated oscillators are overtaking legacy quartz designs in smallsat bus applications where volume constraints dominate payload integration tradeoffs. Constellation operators deploying hundreds of units annually are prioritizing semiconductor-scale manufacturing economics over individual unit heritage records. This displacement is compressing supplier margins on radiation-tolerant quartz products while expanding addressable volume for foundry-capable timing device manufacturers.
FCC orbital debris rules are reshaping mission lifetime specifications and oscillator redundancy architectures for US-licensed spacecraft. The regulation mandates verifiable disposal mechanisms that extend hardware qualification obligations across full operational lifecycles. Prime contractors are responding by consolidating oscillator supplier selections around vendors with demonstrated end-of-life performance degradation documentation.
Buyer concentration among Space Force payload integrators and NASA prime contractors is consolidating procurement authority around qualified vendor lists with pre-negotiated technical specifications. Traditional distribution channels serving research and smaller commercial satellite builders are losing share to direct manufacturer relationships with tier-one system integrators. This channel compression is most visible in the US market where national security launch certification requirements create structural barriers to new oscillator supplier entry.
Space Oscillator Market Segmentation
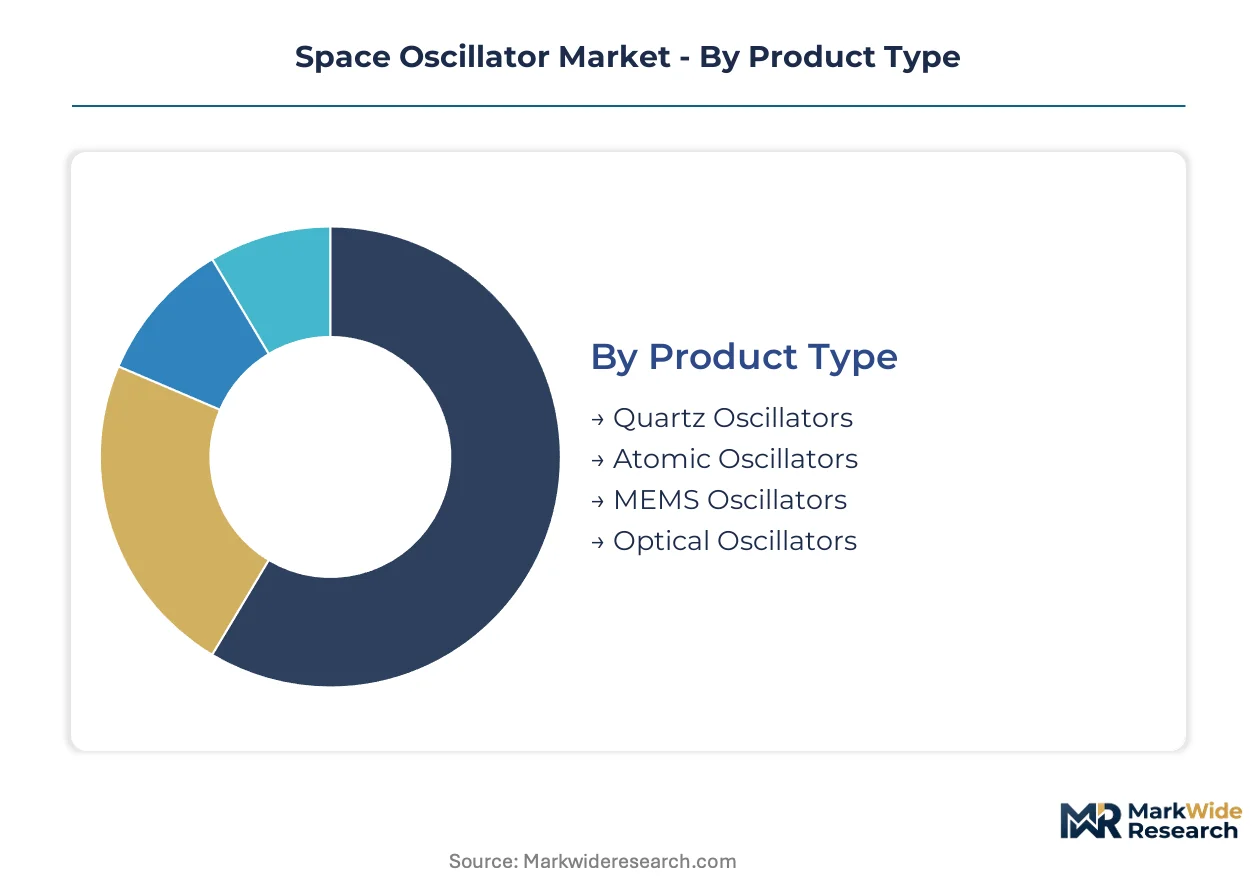
Segmentation in space oscillators reveals how qualification burdens and fabrication economics concentrate procurement decisions across resonator architectures. Each dimension—product type, technology, application, and end user—carries distinct certification requirements that reshape supplier competitive positions.
Product Type:
Supply concentration in high-purity synthetic quartz feedstock constrains oscillator architecture economics and radiation-hardening capabilities.
- Quartz Oscillators:Piezoelectric crystal resonators achieve parts-per-billion frequency stability through temperature-compensated or oven-controlled architectures. NASA Artemis contractors and Space Force payload integrators in the United States concentrate procurement around GSFC-STD-7000 qualified quartz units due to heritage radiation tolerance records.
- MEMS Oscillators:Silicon micromachined resonators leverage semiconductor fabrication economies to compress form factors for smallsat volume constraints. Low Earth orbit constellation operators prioritize MEMS redesigns where size and power budgets tighten, though qualification frameworks lag quartz heritage maturity.
- Atomic Oscillators:Rubidium or cesium vapor cell references deliver superior long-term stability for navigation payloads requiring extended coherence.
- Optical Oscillators:Femtosecond frequency combs enable interferometric precision for gravitational wave detection and deep-space navigation scientific instruments.
Quartz oscillators absorb the bulk of installed capacity; MEMS oscillators are expanding most quickly.
Technology:
End-use performance specifications determine resonator selection across orbital thermal cycling and radiation exposure profiles.
- Satellite Communications:Frequency references maintain signal coherence across transponder chains and ground link synchronization. Geostationary satellite programs demand oven-controlled crystal oscillators with verified degradation curves under total ionizing dose exposure.
- Space Navigation:Timing precision directly determines positioning accuracy for GPS augmentation and autonomous spacecraft guidance. Chip-scale atomic references encroach on traditional crystal oscillator tiers in navigation payload applications.
- Remote Sensing:Synthetic aperture radar and multispectral imagers require stable local oscillators for coherent signal processing.
- Scientific Research:Interferometric instruments for gravitational wave detection and fundamental physics experiments demand femtosecond optical frequency comb precision.
Satellite communications commands the largest share of procurement volume; space navigation is climbing the fastest as constellation density increases.
Application:
Customer procurement authority concentrates around defense certification requirements and commercial launch cadence economics.
- Aerospace:Crewed and robotic spacecraft platforms specify oscillators to GSFC-STD-7000 thermal vacuum screening protocols. NASA prime contractors consolidate supplier selections around vendors with demonstrated end-of-life performance documentation.
- Defense:Radiation-hardened timing devices support encrypted communications and precision guidance in contested orbital environments. Space Force payload integrators drive buyer concentration through qualified vendor lists with pre-negotiated technical specifications.
- Telecommunications:Constellation-scale deployments prioritize semiconductor-scale manufacturing economics over individual unit heritage records.
- Earth Observation:Smallsat builders seek domestic procurement channels outside established supply chains as launch costs compress.
Aerospace absorbs the bulk of high-reliability procurement; telecommunications is gaining share fastest through constellation volume.
End User:
Procurement channel structure fragments between direct manufacturer relationships and traditional distribution serving research builders.
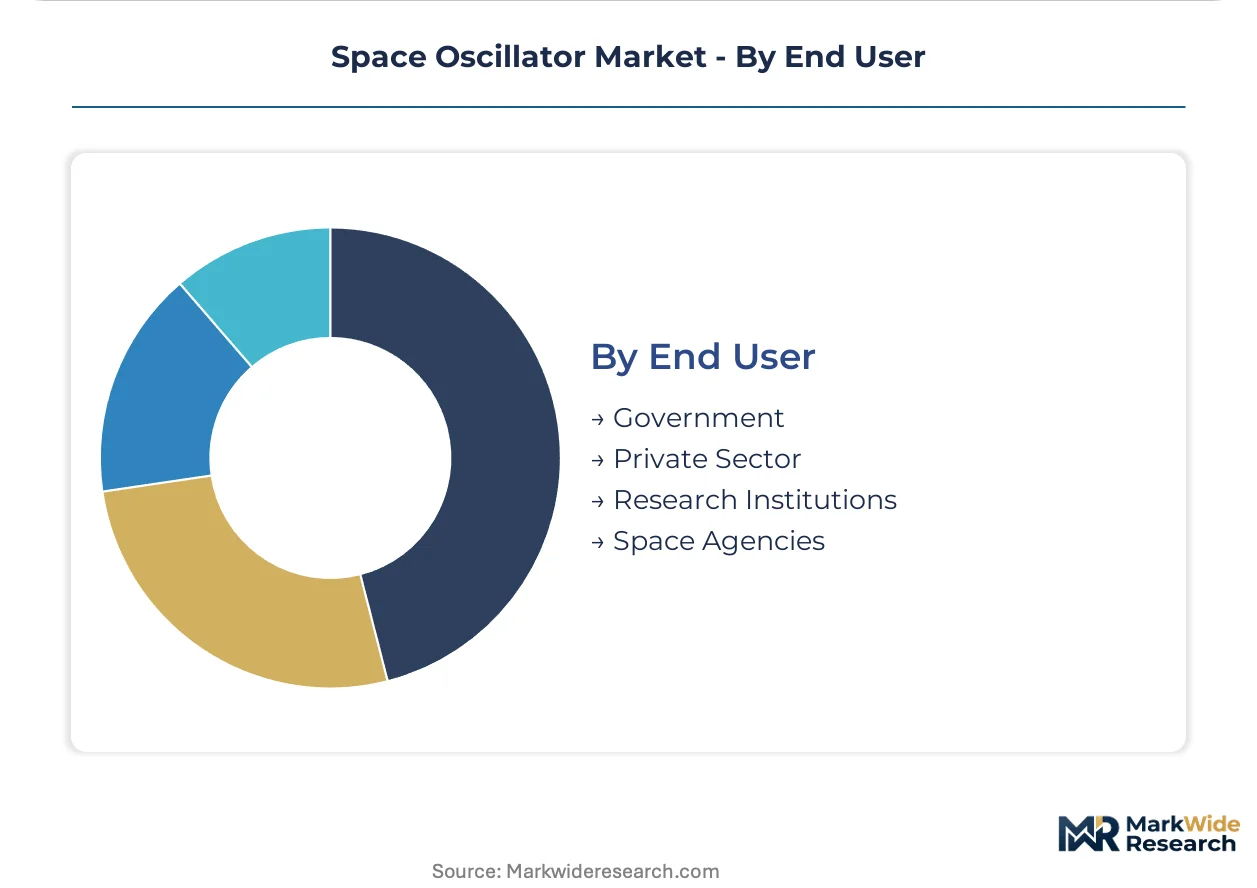
- Government:National security launch certification requirements create structural barriers to new supplier entry in the United States. FCC orbital debris rules mandate verifiable disposal mechanisms that extend hardware qualification obligations.
- Private Sector:Commercial constellation operators deploying hundreds of units annually prioritize foundry-capable manufacturers. Channel compression favors direct relationships with tier-one system integrators over traditional distribution.
- Research Institutions:Scientific instrument builders source optical frequency combs and specialized references for interferometric payloads.
- Space Agencies:ESA's Clean Space initiative tightens material traceability requirements and debris mitigation certification scoring for European suppliers.
Government procurement absorbs the bulk of qualified vendor volume; private sector demand is expanding most quickly through constellation deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of radiation-hardened timing devices concentrates in the United States and Japan, while procurement demand clusters around NASA Artemis contractors and European constellation operators. The geographic mismatch between fabrication capacity and mission specification authority shapes supplier competitive positioning across qualification frameworks.
United States
NASA's Goddard Space Flight Center anchors qualification protocol development through GSFC-STD-7000 thermal vacuum screening standards. The FCC's orbital debris rules mandate verifiable disposal mechanisms that extend hardware qualification obligations across full operational lifecycles. Colorado Springs and Los Angeles metropolitan areas concentrate Space Force payload integrators consolidating procurement authority around qualified vendor lists.
Japan
Seiko Epson Corporation and Nihon Dempa Kogyo anchor precision resonator fabrication clusters in Nagano and Tokyo prefectures. METI standards coordination with JAXA mission requirements shapes domestic qualification pathways for low Earth orbit deployments. The Kanto region concentrates MEMS foundry investment targeting constellation-scale manufacturing economics.
Germany
European Space Agency procurement through its Clean Space initiative tightens material traceability requirements for orbital hardware. REACH compliance obligations intersect with ECSS-Q-ST-60-02C qualification frameworks to extend supplier documentation burdens. Bavaria's aerospace corridor around Munich hosts payload integrators serving ESA scientific and navigation missions.
India
ISRO's commercial launch cost advantages attract regional smallsat operators seeking domestic oscillator procurement channels outside established supply chains. The country's national space regulator coordinates spectrum allocation proceedings that will determine constellation density limits. Bengaluru's aerospace cluster concentrates emerging demand from private constellation builders.
United Kingdom
UK Space Agency funding for national satellite programs generates procurement demand aligned with ESA debris mitigation guidelines. The country's national spectrum regulator participates in ITU proceedings shaping orbital slot allocation and corresponding timing device volume forecasts. Harwell's space cluster hosts payload developers integrating optical frequency references for scientific instruments.
Space Oscillator Market Competitive Landscape
The competitive structure tilts toward heritage-qualified quartz suppliers defending position against MEMS fabrication specialists. Consolidation pressure concentrates around NASA and Space Force procurement channels where qualified vendor lists create structural barriers to new entry. Three archetypes dominate: semiconductor-scale MEMS manufacturers, defense-grade heritage suppliers with in-house qualification protocols, and precision optical instrument builders serving scientific payloads. M&A activity targets radiation effects modeling talent pools, while strategic partnerships transfer terrestrial telecom fabrication processes to space-qualified product tiers.
Among semiconductor fabrication specialists, SiTime Corporation and Microchip Technology exemplify the MEMS-driven competitive vector displacing legacy quartz architectures. Vectron International occupies a position within the heritage qualification tier, anchoring supplier credibility through geostationary satellite program records. These three companies represent the dominant competitive archetypes reshaping procurement patterns across low Earth orbit constellation deployments and deep-space mission specifications.
| Leading Market Players |
|---|
| SiTime Corporation |
| Microchip Technology |
| Vectron International |
| Abracon Holdings |
| Bliley Technologies |
| Rakon Limited |
| Murata Manufacturing |
| Seiko Epson Corporation |
| Nihon Dempa Kogyo |
| Others |
Value Network & Pricing Analysis
Family-owned precision resonator specialists in Japan and heritage defense contractors in the United States anchor supply-side discipline through captive qualification protocols and long-term offtake relationships with constellation operators. Their ownership structures insulate pricing from quarterly earnings pressure while embedding GSFC-STD-7000 certification costs into multi-year contract structures.
Pricing Analysis
Cost-down pressure on radiation-tolerant quartz units accelerates because MEMS foundries are transferring terrestrial telecom fabrication economics into space-qualified tiers. Pricing stratifies across GSFC-STD-7000 certified heritage grades, ECSS-Q-ST-60-02C compliant European tiers, and emerging MEMS alternatives with abbreviated qualification records. Volume scale drives differentiation most sharply: constellation operators deploying hundreds of units annually extract steep discounts from foundry-capable manufacturers, while single-mission scientific payloads absorb premium pricing for documented end-of-life degradation curves. Small satellite builders exhibit highest price sensitivity; NASA Artemis prime contractors demonstrate lowest sensitivity due to mission-critical timing requirements and pre-negotiated vendor list structures.
Supply Chain Analysis
Qualification gating through GSFC-STD-7000 and ECSS-Q-ST-60-02C frameworks concentrates supply authority among heritage suppliers with multi-year material traceability documentation. High-purity synthetic quartz feedstock production clusters in Japan and the United States; MEMS fabrication capacity centers on Taiwan and South Korea. Resonator blanks, ceramic packaging substrates, and radiation-hardened semiconductor components constitute critical input dependencies. Single-source vulnerability in synthetic quartz feedstock exposes oscillator manufacturers to geographic concentration risk. Distribution runs through direct manufacturer relationships with tier-one system integrators, compressing traditional distribution channels serving research and smaller commercial satellite builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where ESA's ECSS-Q-ST-60-02C qualification framework and NASA's GSFC-STD-7000 standards erect barrier-to-entry moats protecting incumbent suppliers with amortized certification infrastructure.
For Market Incumbents: Deploy backward integration into high-purity synthetic quartz feedstock to defend against MEMS substitution threats in low Earth orbit constellation tiers. Accelerate radiation effects modeling talent acquisition from national laboratory environments to compress qualification timelines for emerging optical frequency comb architectures. Lock in long-term offtake agreements with Space Force payload integrators before channel consolidation completes. For New Entrants and Emerging Players: Enter via ISRO's commercial launch ecosystem in India, where domestic procurement channels outside established US and European supply chains remain underdeveloped. Target smallsat bus applications where volume constraints prioritize semiconductor-scale manufacturing economics over heritage qualification records. Pursue strategic partnerships with terrestrial telecom MEMS foundries to transfer fabrication processes into radiation-tolerant product tiers. For Investors and Strategic Acquirers: Distressed-cycle entries favor radiation effects modeling specialists with defense contractor pedigrees in the United States, where ITAR classification complexity delays non-US competitor access. Long-term viability hinges on positioning for dual-use technology convergence where defense-grade specifications and commercial volume economics align through MEMS process transfers. Watch for FCC orbital debris rule enforcement tightening as the inflection signal driving end-of-life performance documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation Effects Modeling Acquisition | Captures scarce talent pools from national laboratories to accelerate qualification timelines. |
| MEMS Fabrication Process Transfer | Leverages terrestrial telecom economies to compress form factors for constellation volume. |
| End-of-Life Performance Documentation | Aligns with FCC debris rules to secure preferential scoring on prime contractor vendor lists. |
| Synthetic Quartz Feedstock Integration | Reduces single-source exposure in resonator blank supply concentrated in Japan. |
| Clean Space Certification Investment | Captures ESA procurement preference through verified passive deorbit mechanism integration. |
Research Methodology
Multi-period observation of constellation deployment cadence, qualification framework evolution, and procurement channel structure anchored the trend analysis, supplemented by interviews with oscillator program managers at prime contractors, radiation effects physicists at national laboratories, procurement officers within Space Force payload integration teams, and supply chain directors at MEMS foundry operators. Secondary validation drew from NASA technical standards repositories, ESA ECSS qualification documentation, FCC orbital debris rulemaking dockets, and customs trade data on high-purity quartz imports. Bottom-up unit economics triangulated against top-down market sizing across resonator architectures.
Segment-weighting applied product type, technology, application, and end user dimensions with additional stratification by qualification tier heritage. CAGRs were derived from installation base projections tied to constellation density limits under ITU spectrum allocation proceedings and national space traffic management regulations. Forecast inputs incorporated thermal vacuum screening protocol updates, material traceability documentation burdens, and radiation tolerance degradation curve verification requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ITU spectrum reallocation or unilateral debris mitigation rule tightening. Model assumptions reflect documented qualification timelines, foundry capacity expansion plans, and procurement consolidation patterns. A model refresh is warranted upon material change in FCC enforcement posture on orbital debris disposal verification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Sensors Market
Space
Space As a Service Market
Space
Space Wheel Market
Space
Space Launch Services Market
Space
Near Space Robotics Market
Space
Space Transportation Market
Space
Africa Space Propulsion System Market
Space
Space-Based Smart Sensors Market
Space
Space Propulsion Systems Market
Space
Space in Orbit Refueling Market
Space
Asteroid Mining Market
Space
Space Battery Market
Space
Asia-Pacific Space Logistics Market
Space
Africa Space Electronics Market
Space
India Space Electronics Market
Space
France Space Electronics Market