
 Land-Based Situational Awareness Systems Market | 2026-2036
Land-Based Situational Awareness Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Land-Based Situational Awareness Systems Market Foresight
The pool of cleared systems engineers with multi-sensor fusion expertise is collapsing across European defense hubs, forcing primes to restructure hiring pipelines and training cycles. BAE Systems plc sustains competitive depth through captive radar development and long-term UK Ministry of Defence service contracts. Thales Group leverages its pan-European footprint to anchor integrated command-and-control programs across multiple NATO members. Elbit Systems Ltd. specializes in thermal imaging and AI-driven target recognition, occupying a distinct tier in border surveillance tenders.
Land-based situational awareness systems encompass integrated hardware-software platforms that collect, process, and distribute real-time environmental data through radar arrays, electro-optical sensors, and networked communication nodes operating across VHF to millimeter-wave bands. These systems fuse multi-source intelligence to generate unified operating pictures for decision-makers monitoring terrestrial domains. Surveillance systems lead current procurement volumes as legacy camera networks undergo phased replacement with AI-enhanced video analytics. Sensor systems represent the fastest-expanding segment, driven by demand for passive acoustic and seismic arrays that reduce electromagnetic signatures. Communication systems command elevated margins where military-grade encryption and anti-jam protocols differentiate vendor offerings.
The EU AI Act imposes conformity requirements on automated threat-detection algorithms deployed in public safety and border applications, reshaping product development roadmaps for vendors serving European end users. REACH and RoHS frameworks restrict hazardous substances in sensor manufacturing, elevating compliance costs for non-European suppliers seeking CE-marked access. NATO STANAG interoperability standards further condition market participation, mandating common data formats and interface protocols across allied force structures. Stakeholders must weigh dual-use technology export controls against commercial expansion into law enforcement and emergency services segments where regulatory thresholds differ.
Market Dynamics
Integrated sensor-to-shooter networks are forcing prime contractors to restructure engineering pipelines around NATO interoperability mandates and the EU AI Act's conformity requirements for automated threat detection.
Growth Catalysts
- EU AI Act compliance:Automated threat-detection algorithms deployed in border applications must meet conformity standards, accelerating platform modernization across European defense procurement.
- Passive acoustic arrays:Military end users prioritize electromagnetic signature reduction, driving demand for seismic and acoustic sensor systems that operate without active emissions.
- Poland:Border protection investments and critical infrastructure resilience programs concentrate procurement volumes for integrated command-and-control platforms.
Market Restraints
- Specialized engineering talent scarcity:The collapsing pool of cleared systems engineers with multi-sensor fusion expertise extends hiring cycles and inflates labor costs across European hubs.
- REACH and RoHS compliance:Hazardous substance restrictions in sensor manufacturing elevate costs for non-European suppliers seeking CE-marked market access.
- Legacy camera networks:Phased replacement timelines for outdated surveillance infrastructure compress near-term revenue recognition for vendors.
Strategic Opportunities
- Emergency services convergence:Dual-use technology applications in law enforcement and emergency response segments offer commercial expansion paths with lower regulatory thresholds than defense-only markets.
- AI-driven target recognition:Thermal imaging platforms integrating machine learning algorithms create differentiation in border surveillance tenders requiring reduced false-positive rates.
- Germany:Federal prioritization of critical infrastructure protection generates sustained demand for networked communication nodes with military-grade encryption.
Industry Challenges
- Multi-sensor fusion expertise gap:Defense primes struggle to staff integrated hardware-software development teams capable of unifying radar, electro-optical, and acoustic data streams.
- NATO STANAG certification timelines:Common data format and interface protocol mandates extend product validation cycles before allied force deployment.
- Millimeter-wave integration complexity:Fusing VHF through millimeter-wave band communications into unified operating pictures demands specialized RF engineering capabilities in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land-Based Situational Awareness Systems Market |
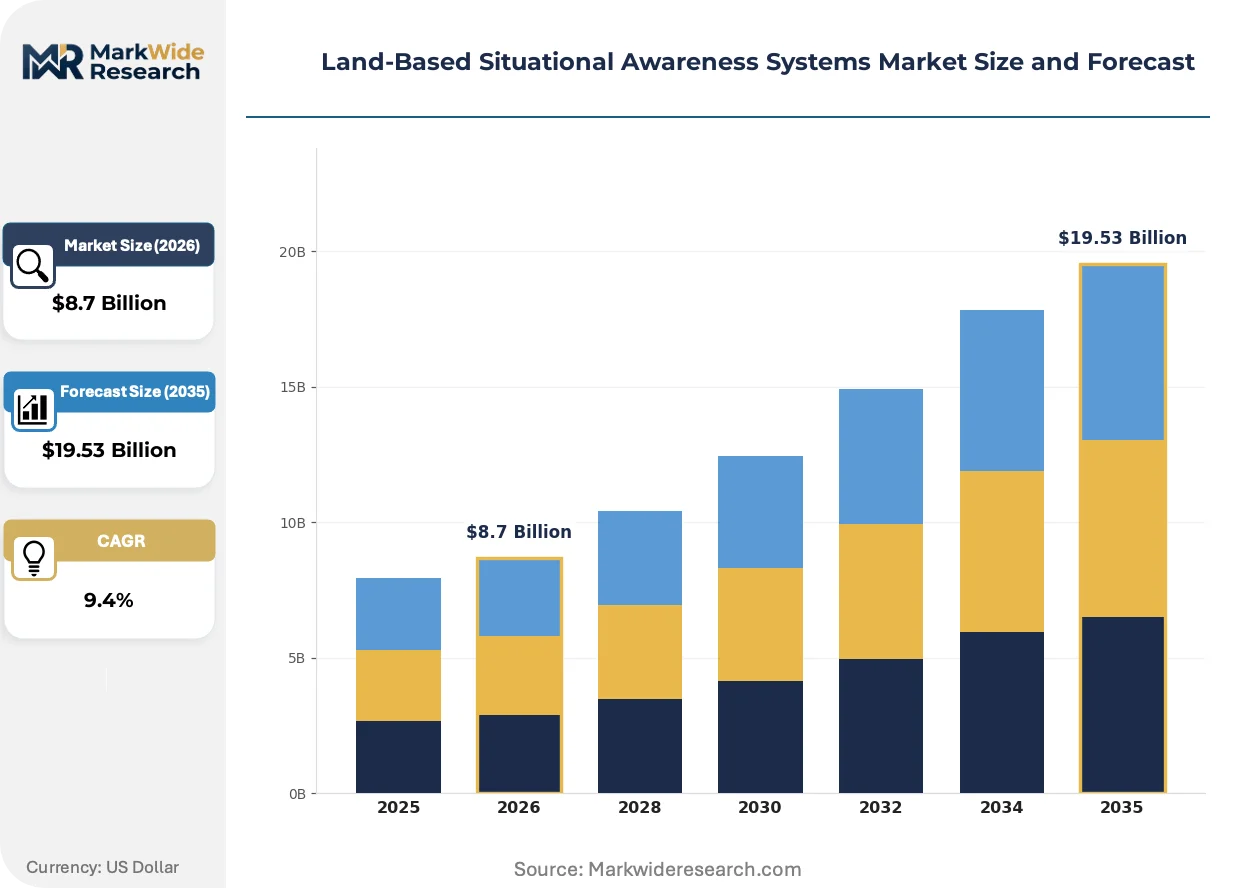
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Radar Systems, Sensor Systems, Communication Systems End User: Military, Defense, Law Enforcement, Emergency Services Technology: Wireless Communications, AI Analytics, IoT Solutions, Cloud Computing Application: Borders Protection, Critical Infrastructure, Public Safety, Natural Disaster Management |
| Companies Covered | Leonardo S.p.A., Thales Group, Elbit Systems Ltd., BAE Systems plc, Safran SA, HENSOLDT, RTX Corporation, L3Harris Technologies, Indra Sistemas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land-Based Situational Awareness Systems Market Shifts & Advancements
Real-time environmental data processing is compressing decision cycles for terrestrial domain monitoring, reshaping how sensor arrays communicate with command nodes and how vendors architect system-level offerings.
AI-enhanced video analytics is supplanting rule-based motion detection in legacy surveillance networks. Border agencies and critical infrastructure operators are adopting machine learning inference at the edge to reduce bandwidth consumption and latency. This shift is compressing procurement evaluation criteria toward algorithm accuracy benchmarks rather than hardware specifications alone.
The EU AI Act imposes conformity assessment requirements on automated threat-detection systems deployed in public safety applications. Vendors must document algorithmic transparency and bias mitigation measures before CE marking. European end users are conditioning contract awards on demonstrated compliance, forcing product development roadmaps to prioritize explainable AI architectures.
Service contract unbundling is fragmenting traditional platform-plus-support procurement models. Defense ministries are separating sensor hardware acquisition from software maintenance and algorithm update subscriptions. France and Germany exhibit the most advanced unbundling, with multi-year performance-based agreements replacing single-source system purchases.
Land-Based Situational Awareness Systems Market Segmentation
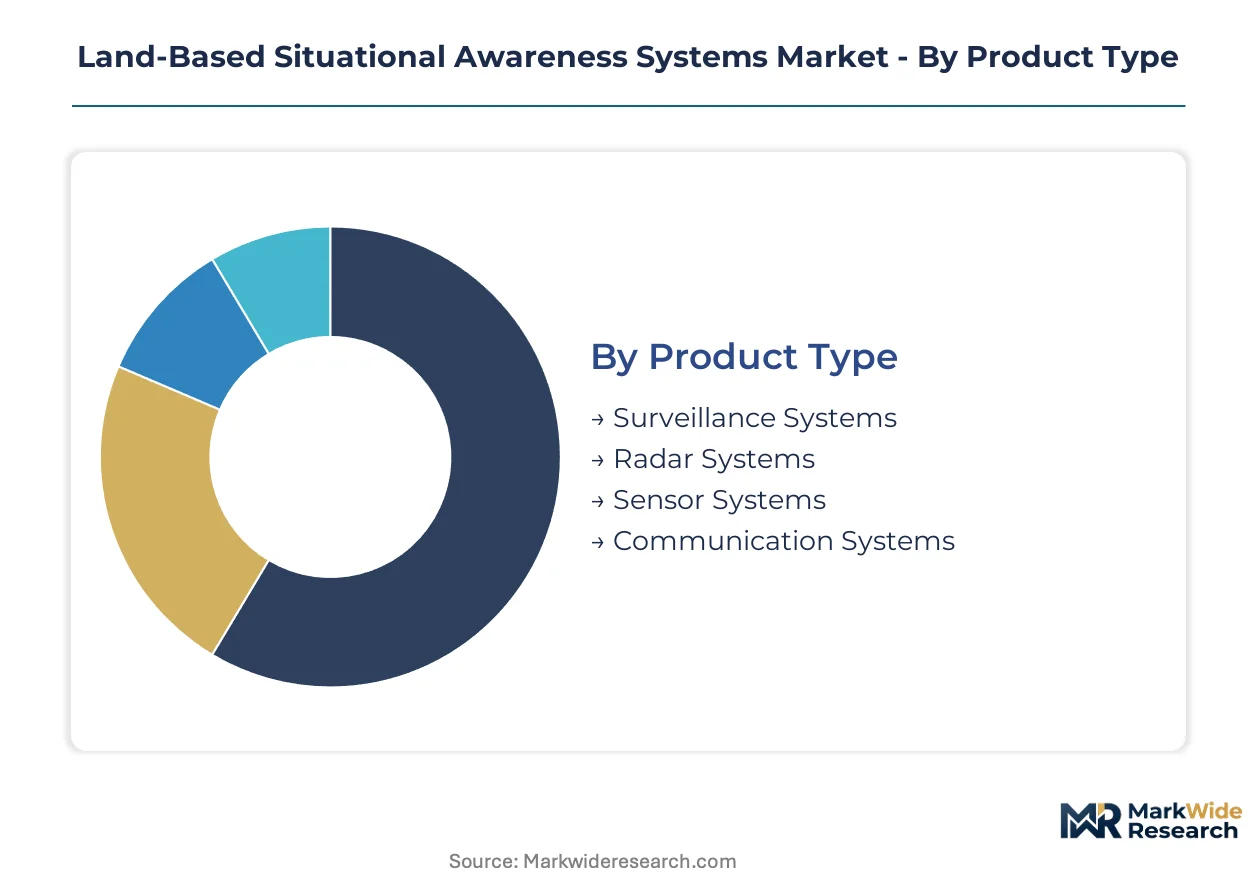
Segmentation in land-based situational awareness systems reveals how procurement priorities diverge across threat environments and operational doctrines. Each dimension—product architecture, end-user mission, technology stack, and deployment scenario—carries distinct specification requirements and certification pathways that reshape vendor competitive positioning.
Product Type:
Geographic demand spreads unevenly across product categories, with surveillance and radar systems concentrated in NATO border states while sensor systems find traction in electromagnetic signature-conscious deployments.
- Surveillance Systems:Integrated electro-optical and infrared camera networks with AI-enhanced video analytics fuse multi-spectrum imagery into unified monitoring feeds. Procurement concentrates in Poland and Germany where legacy camera infrastructure replacement programs prioritize automated threat detection compliant with EU AI Act conformity standards.
- Sensor Systems:Passive acoustic and seismic arrays detect ground vibrations and sound signatures without electromagnetic emissions, reducing detection vulnerability. French and UK defense ministries prioritize these for forward operating base perimeter security where radio silence is mission-critical.
- Radar Systems:Ground-based radar arrays operating across VHF to millimeter-wave bands provide all-weather detection of personnel and vehicle movement.
- Communication Systems:Military-grade encrypted nodes with anti-jam protocols integrate disparate sensor feeds into command networks.
Surveillance systems hold the largest share; momentum sits with sensor systems.
End User:
Cost tier stratification separates defense-grade platforms from commercially adapted alternatives, with military specifications commanding 3-4x price multiples over law enforcement equivalents.
- Military:Integrated sensor-to-shooter networks demanding NATO STANAG interoperability and hardened electromagnetic resilience. Procurement volumes concentrate in Germany, France, and Poland as these states modernize land force situational awareness capabilities.
- Defense:Critical infrastructure protection and territorial defense applications with moderated hardening requirements versus frontline military systems.
- Law Enforcement:Border patrol and urban surveillance deployments where EU AI Act algorithmic transparency requirements condition vendor selection more heavily than military specifications.
- Emergency Services:Natural disaster response and search-and-rescue coordination platforms with commercial-grade encryption and rapid deployability priorities.
Military end users dominate procurement value; law enforcement exhibits the steepest expansion trajectory as border agencies automate threat detection.
Technology:
Application maturity varies sharply, with wireless communications representing established infrastructure while AI analytics adoption accelerates under regulatory compliance pressures.
- AI Analytics:Machine learning inference engines processing sensor feeds at the edge for real-time threat classification and reduced bandwidth consumption. EU AI Act conformity documentation requirements reshape vendor development roadmaps toward explainable architectures.
- Wireless Communications:Mesh networking protocols and software-defined radio platforms operating across contested spectrum environments.
- IoT Solutions:Distributed sensor networks with low-power wide-area connectivity for perimeter monitoring and environmental sensing.
- Cloud Computing:Centralized data fusion and long-term intelligence storage with military-grade encryption and sovereign data residency requirements.
Wireless communications anchors installed base; AI analytics is gaining share fastest as European procurement mandates automated detection capabilities.
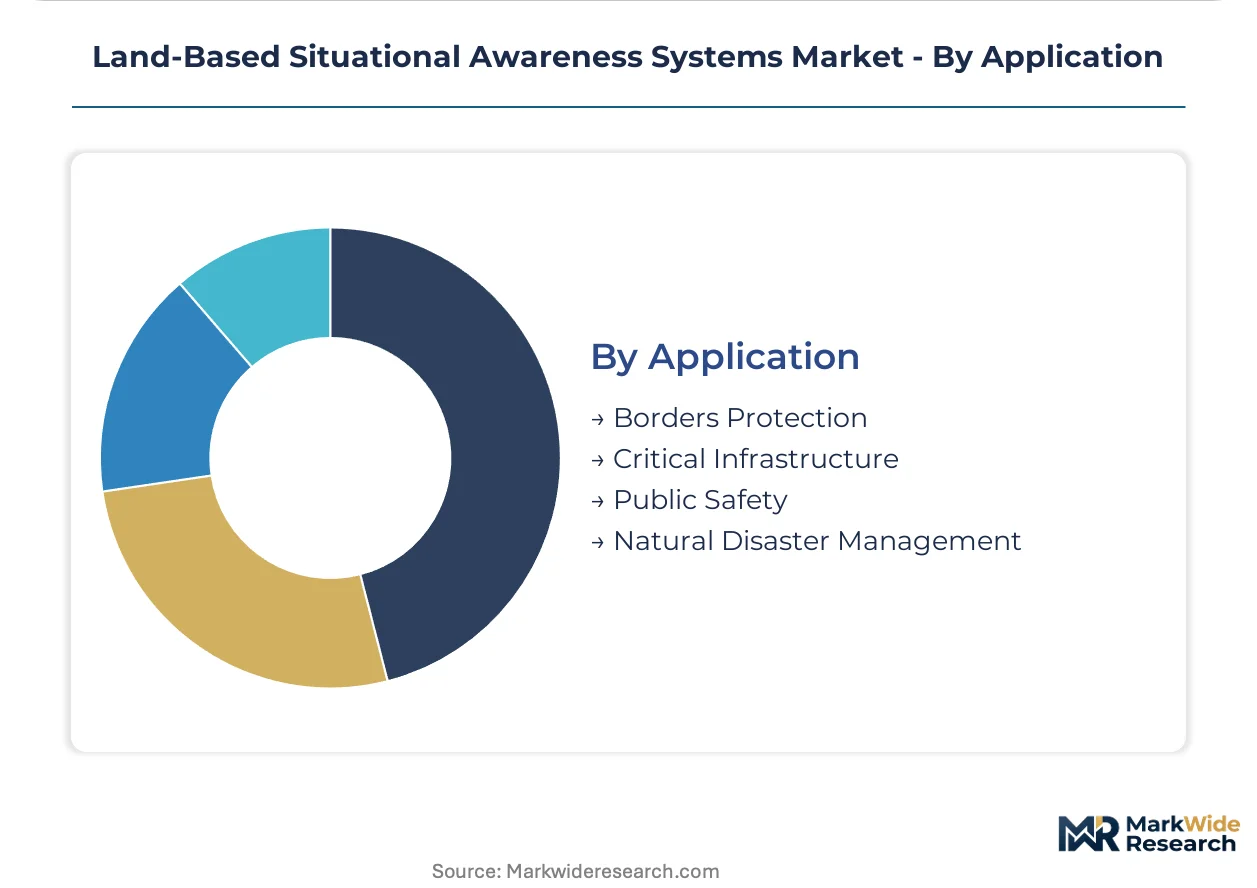
Application:
Customer risk profiles differentiate specification intensity, with borders protection demanding highest sensor density while natural disaster management prioritizes rapid deployment over persistent coverage.
- Borders Protection:Continuous perimeter surveillance integrating radar, electro-optical, and seismic sensors with automated anomaly detection. Polish and German federal investments concentrate procurement volumes for integrated command-and-control platforms.
- Critical Infrastructure:Power grid, transportation hub, and communications facility monitoring with cyber-physical security integration.
- Public Safety:Urban area monitoring and event security with law enforcement coordination protocols and civilian privacy safeguards.
- Natural Disaster Management:Rapidly deployable sensor networks for earthquake, flood, and wildfire response with satellite backhaul and battery-independent power.
Borders protection commands largest procurement allocation; natural disaster management is climbing the fastest as climate adaptation funding expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European procurement patterns, with NATO STANAG interoperability standards conditioning cross-border defense integration. Military end users in Germany, France, and Poland are accelerating platform modernization as border protection investments concentrate procurement volumes for integrated command-and-control systems.
Germany
Federal prioritization of critical infrastructure protection generates sustained demand for networked communication nodes with military-grade encryption. The EU AI Act's conformity assessment requirements reshape vendor selection criteria toward documented algorithmic transparency. Defense industrial clusters in Bavaria and Baden-Württemberg concentrate radar and electro-optical system development for NATO interoperability.
France
Service contract unbundling fragments traditional platform-plus-support procurement models, with multi-year performance-based agreements replacing single-source system purchases. The EU Green Deal's defense adaptation provisions influence energy resilience specifications for forward operating base systems. The Île-de-France and Provence-Alpes-Côte d'Azur regions host integrated command-and-control program development for multiple NATO members.
Poland
Border protection investments and critical infrastructure resilience programs concentrate procurement volumes for integrated sensor-to-shooter networks. NATO interoperability standards accelerate platform modernization requirements for allied force structure integration. Warsaw and the eastern border regions drive demand for passive acoustic and seismic arrays reducing electromagnetic signatures.
United Kingdom
Long-term Ministry of Defence service contracts sustain competitive depth for primes with captive radar development capabilities. REACH and RoHS frameworks restrict hazardous substances in sensor manufacturing, elevating compliance costs for non-European suppliers. The South East and South West England defense hubs specialize in multi-sensor fusion expertise for terrestrial domain monitoring.
Italy
Pan-European platform integration programs leverage national industrial capacity for electro-optical and infrared system development. The EU AI Act's automated threat-detection conformity standards condition product roadmaps for border surveillance tenders. The Lombardy and Lazio regions concentrate AI-driven target recognition technology development for reduced false-positive rate requirements.
Land-Based Situational Awareness Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around defense primes possessing captive sensor development and long-term government service relationships. The upper tier commands premium positioning through NATO STANAG certification depth and multi-decade ministry contracts. Strategic archetypes include pan-European platform integrators, national champions with ministry-captive relationships, and thermal imaging specialists occupying border surveillance niches. Dominant competitive moves center on restructuring engineering pipelines around interoperability mandates and unbundling service contracts into performance-based subscription models.
Among European defense primes, Thales Group and BAE Systems plc exemplify the integrated leader archetype through pan-European footprint and ministry-captive positioning respectively. Elbit Systems Ltd. occupies a distinct specialist tier in thermal imaging and AI-driven target recognition applications. These three anchors demonstrate how competitive depth derives from either geographic breadth across NATO members or deep national service relationships rather than product differentiation alone.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Thales Group |
| Elbit Systems Ltd. |
| BAE Systems plc |
| Safran SA |
| HENSOLDT |
| RTX Corporation |
| L3Harris Technologies |
| Indra Sistemas |
| Others |
Supply & Pricing Matrix
Ninety-to-one-hundred-twenty-day lead times for millimeter-wave RF components concentrate pricing power with German and French captive radar manufacturers, while REACH compliance costs for non-European suppliers compress margins at the standard tier. This inventory-to-pricing linkage rewards primes with backward integration into sensor fabrication and penalizes assemblers dependent on cross-border component flows.
Pricing Analysis
German communication systems command 40-60% premiums over Polish equivalents due to military-grade encryption certification and sovereign data residency guarantees. Three-tier pricing structure across NATO-certified, CE-marked, and commercial-grade levels separates defense ministry contracts from law enforcement tenders. Cost compression in the commercial tier intensifies as Chinese electro-optical suppliers seek CE marking pathways. Military end users exhibit lowest price sensitivity where STANAG interoperability mandates single-source qualification.
Supply Chain Analysis
Strategic stockpiling of gallium nitride substrates and indium phosphide wafers dominates inventory strategy as defense primes buffer against single-source vulnerability in compound semiconductor supply. Manufacturing concentrates in Germany, France, and the United Kingdom for radar array fabrication, with Israel and the United States feeding thermal imaging sensor modules. Supply chain risk centers on tariff exposure for Chinese-origin rare earth magnets in gimbal motors. Distribution runs through ministry-captive service contracts rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm update subscriptions and performance-based maintenance agreements expand at double the rate of hardware unit sales, converting capital expenditure procurement into recurring revenue streams for platform vendors.
For Market Incumbents: Compound defensive positioning through captive development of multi-sensor fusion software stacks and exclusive NATO STANAG certification pipelines. Threat from emerging AI-native entrants with edge-computing architectures demands accelerated explainable AI roadmaps. Priority lever: vertical integration into passive acoustic array manufacturing to reduce electromagnetic signature solution dependency on external suppliers. For New Entrants and Emerging Players: Differentiate on EU AI Act conformity documentation as a first-mover advantage in law enforcement border surveillance tenders. White-space targets include emergency services rapid-deployment networks and critical infrastructure cyber-physical integration. Poland offers the most penetrable geography given concentrated procurement volumes and limited incumbent service contract lock-in. Go-to-market angle: algorithm-accuracy benchmarking against legacy rule-based motion detection systems. For Investors and Strategic Acquirers: Carve-out targets emerge from national champions divesting non-core electro-optical divisions amid service contract unbundling pressures. Long-term viability favors primes with ministry-captive relationships spanning multiple NATO members. Acquisition archetype: mid-cap specialists with demonstrated STANAG certification depth and AI-driven target recognition IP. Signal to watch: EU AI Act enforcement actions creating compliance-driven consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Unbundling | Performance-based algorithm subscriptions replace single-source hardware purchases in France and Germany. |
| EU AI Act Compliance Investment | Documented bias mitigation and explainable AI architectures become mandatory for CE-marked border systems. |
| Passive Sensor Manufacturing Scale-Up | Seismic and acoustic array production reduces electromagnetic signature vulnerability for forward bases. |
| NATO STANAG Certification Pipeline | Common data format validation accelerates allied force integration and locks out non-compliant vendors. |
| Multi-Sensor Fusion R&D Expansion | Unified radar-electro-optical-acoustic processing addresses collapsing cleared engineering talent pools. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, systems engineering directors, and border agency technology leads; and secondary validation against NATO STANAG documentation, EU AI Act regulatory filings, and national defense ministry budget appropriations. Bottom-up triangulation cross-checked vendor-reported program values with top-down market sizing from customs trade data and component shipment records.
Across the modeling period, forecasts employed segment-level CAGRs derived from procurement pipeline analysis across surveillance, sensor, radar, and communication system categories, with technology stack adoption curves for AI analytics and wireless communications. Industry-specific inputs included EU AI Act implementation timelines and NATO interoperability mandate acceleration patterns.
Material uncertainties — defense budget reallocation shocks, REACH substance restriction expansions, and STANAG standard revision cycles — sit outside the modeled envelope. Forecasts reflect assumptions about sustained European border protection investment and allied force modernization continuity. Revision becomes warranted when EU AI Act enforcement stringency or NATO collective defense spending commitments cross threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Integrated 3D Radar Market