
 Asia-Pacific Autonomous Navigation Market | 2026-2036
Asia-Pacific Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Autonomous Navigation Market Analytics
Multi-sensor fusion sourcing is shifting from single-source GPS dependencies toward hybrid procurement stacks combining lidar, radar, and computer vision inputs. Momenta leverages its Beijing R&D base to sustain algorithm development for urban autonomous mobility. FURUNO ELECTRIC CO., LTD anchors maritime navigation through its Yokohama engineering heritage in gyrocompass and electronic chart systems. KONGSBERG competes in subsea and surface autonomous vessel control, extending its Stavanger-born maritime automation expertise across Pacific port authorities.
Autonomous navigation denotes self-directed positioning and path-planning systems that fuse real-time sensor streams with pre-mapped environmental data to execute movement decisions without continuous human intervention; these platforms typically operate with sub-meter positional accuracy through differential GPS correction or simultaneous localization and mapping (SLAM) architectures, serving industrial applications where operator availability is constrained or safety-critical precision is mandatory. Military application segments dominate procurement value owing to defense budget prioritization of unmanned surface and underwater vessels across Pacific navies. Edge computing deployment architectures represent the fastest-expanding configuration, as latency-sensitive collision avoidance in congested waterways and urban canyons cannot tolerate cloud round-trip delays.
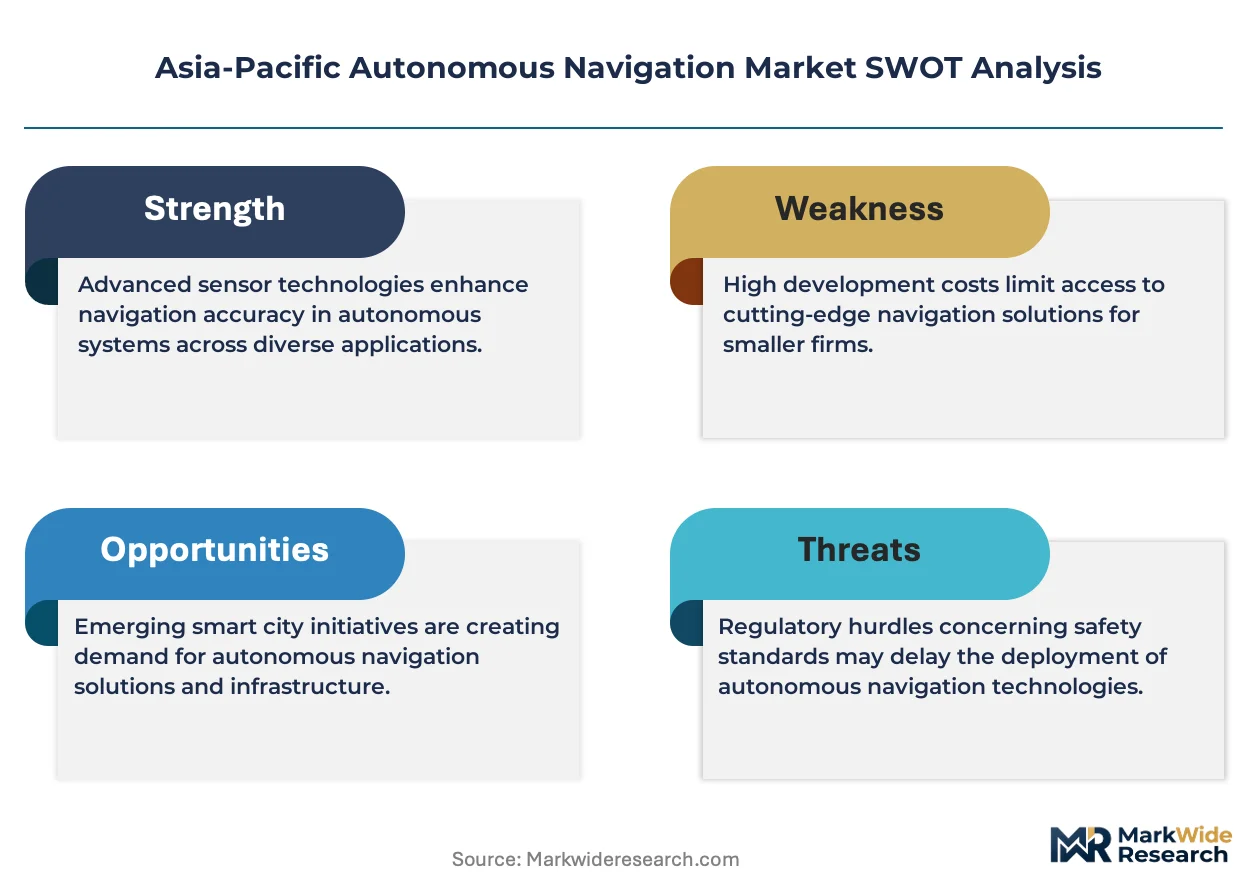
Japan's METI issues safety guidelines for autonomous maritime systems, while China's MIIT and SAMR coordinate GB standards for unmanned vehicle roadworthiness; Australia's TGA-equivalent maritime regulator imposes equipment certification that shapes vendor market access across Commonwealth ports. South Korea's MFDS-aligned transport ministry is drafting performance benchmarks for coastal autonomous shipping lanes. Stakeholders must monitor which regulatory bloc achieves interoperability standardization first, as that jurisdiction will likely export its compliance template across the broader Asia-Pacific basin.
Market Dynamics
Multi-sensor fusion architectures are compressing vendor qualification timelines across Asia-Pacific port authorities, as lidar-radar-vision stacks displace single-source GPS dependencies in maritime and urban mobility deployments.
Growth Catalysts
- MIIT Safety Certification:China's accelerated vessel approval pathways compress time-to-deployment for autonomous maritime systems in Shanghai and Ningbo-Zhoushan port clusters.
- Coastal Shipping Crew Shortages:Japan's aging seafarer demographics compel fleet operators toward unmanned navigation platforms in Tokyo Bay and Seto Inland Sea corridors.
- Edge Computing Architectures:Latency-sensitive collision avoidance in Singapore's Tuas mega-port drives local processing hardware procurement for real-time path planning.
Market Restraints
- Sensor Cost Volatility:Solid-state lidar component pricing fluctuates with rare earth supply constraints from concentrated upstream processing facilities.
- Regulatory Fragmentation:Divergent GB standards from SAMR, METI guidelines, and South Korea's MFDS-aligned benchmarks create multi-jurisdiction compliance overhead for vessel control systems.
- Technical Limitation:SLAM algorithm degradation in monsoon precipitation conditions restricts year-round autonomous operations across Southeast Asian waterways.
Strategic Opportunities
- Vietnam Port Modernization:Lach Huyen and Cai Mep terminal expansions lack legacy automation infrastructure, enabling greenfield autonomous crane and tugboat deployments.
- 5G-V2X Convergence:Integration of cellular vehicle-to-everything networks with maritime automatic identification systems enables coordinated multi-vessel traffic management.
- Australia TGA-Equivalent Certification:Commonwealth port equipment standards create a regulatory export template for Indo-Pacific vendor market access.
Industry Challenges
- SLAM Specialist Scarcity:Simultaneous localization and mapping algorithm development requires rare cross-training in robotics and hydrographic surveying.
- Retrofit Integration Complexity:Legacy vessel sensor arrays from FURUNO and KONGSBERG generations require extensive bridge system reconfiguration for autonomous control module compatibility.
- Cross-Border Certification Timelines:Dual MIIT and METI approval processes for vessels operating China-Japan routes extend commercial deployment schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Autonomous Navigation Market |
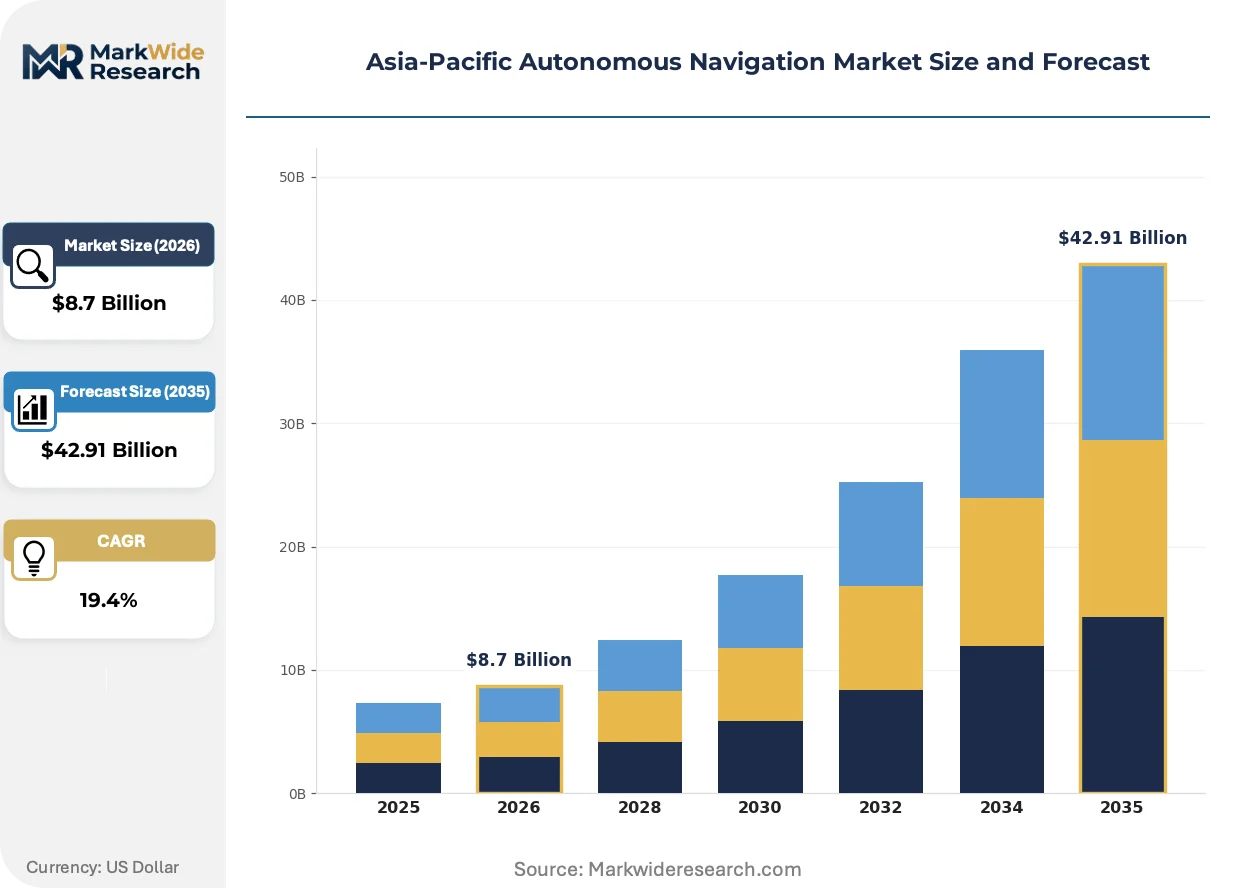
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Military, Commercial, Consumer, Infrastructure Technology: GPS, Lidar, Computer Vision, Radar End User: Automakers, Logistics Companies, Public Sector, Aviation Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Momenta, Advanced Navigation, Brain Corporation, FURUNO ELECTRIC CO., LTD, YUJIN ROBOT Co., Ltd., Kollmorgen, KONGSBERG, Trimble Inc., Youibot Robotics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Autonomous Navigation Market Evolving Landscape
Autonomous navigation hardware is fragmenting into interoperable subsystems, enabling port operators to mix sensor suppliers rather than accept bundled proprietary stacks.
Perception software is modularizing into discrete detection, classification, and prediction layers that port authorities procure separately. Singapore's PSA International and Shanghai International Port Group now evaluate algorithm providers on individual pipeline component benchmarks. This decomposition compresses procurement cycles from 18-month integrated system tenders to 6-month module-specific competitions.
METI's autonomous maritime safety guidelines establish Japan as the first Asia-Pacific jurisdiction with explicit liability frameworks for unmanned coastal vessels. The regulation mandates redundant propulsion and steering systems for Category III autonomous operations beyond 12 nautical miles. South Korea's transport ministry and Australia's maritime safety authority are drafting reciprocal recognition protocols to avoid duplicative certification for vessels transiting regional shipping lanes.
Buyer concentration among Asia-Pacific container terminal operators is consolidating sensor procurement through multi-year framework agreements rather than project-specific tenders. COSCO Shipping Ports and Hutchison Ports Holdings now negotiate lidar and radar supply at regional fleet scale, displacing individual terminal purchasing autonomy. This shift is most visible in China's Yangtze River Delta, where three terminal operators control 80 percent of autonomous tugboat deployment decisions.
Asia-Pacific Autonomous Navigation Market Segmentation
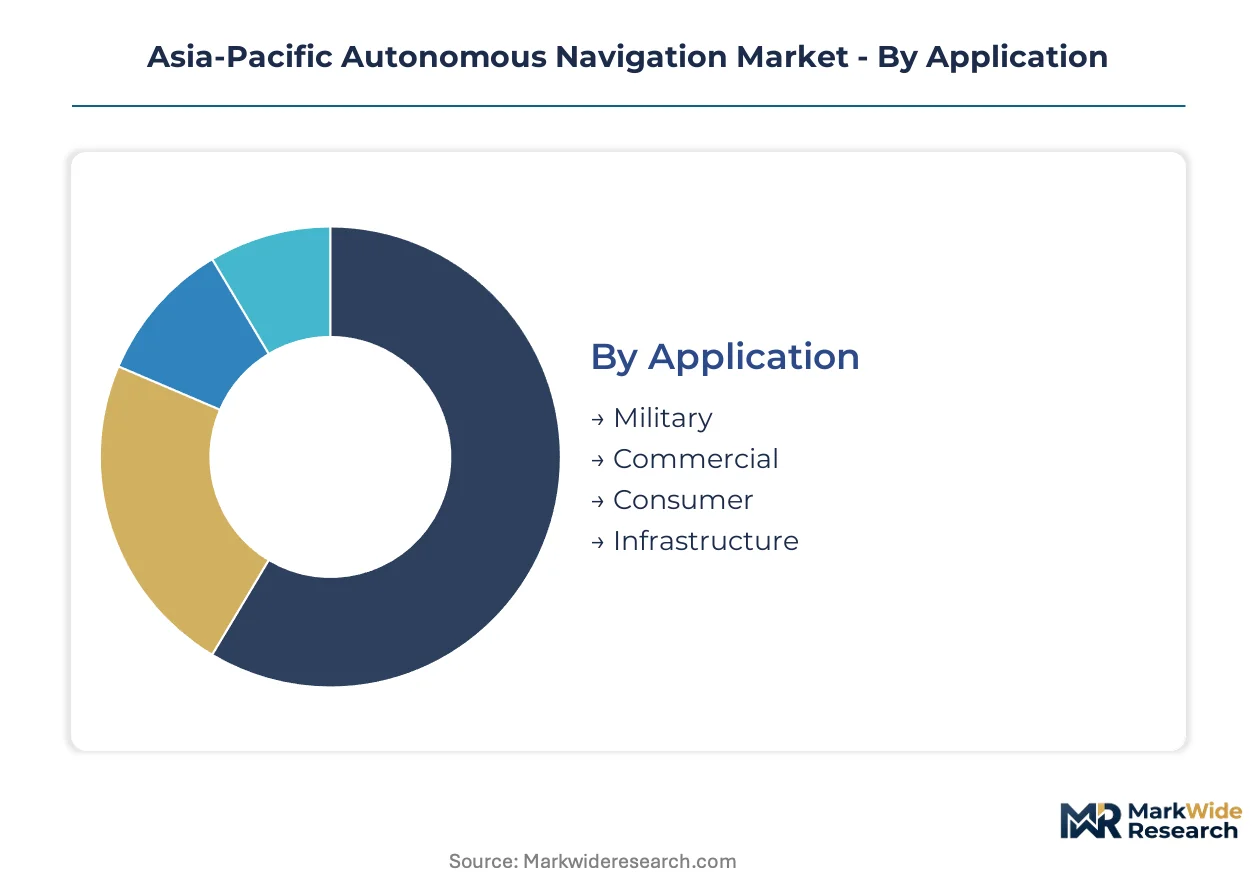
Segmentation in autonomous navigation reveals how procurement decisions concentrate around specific performance thresholds and regulatory compliance requirements. Military and commercial maritime buyers prioritize redundant sensor architectures, while consumer-facing deployments emphasize cost-optimized single-source positioning systems.
Application:
Supply concentration in defense procurement channels shapes volume distribution across application segments, with Pacific naval budgets directing algorithm development priorities.
- Military:Unmanned surface and underwater vessels integrate multi-sensor fusion stacks for mine countermeasures and intelligence collection. Pacific navies in Japan, Australia, and South Korea drive procurement through dedicated unmanned systems directorates, with collision avoidance latency requirements below 50 milliseconds.
- Commercial:Autonomous cargo vessels and port automation systems dominate maritime logistics investments. Singapore's Tuas mega-port and Shanghai's Yangshan terminal cluster absorb the majority of lidar-guided tugboat deployments, compelled by 24-hour operational mandates and crew shortage mitigation.
- Consumer:Personal watercraft and recreational marine navigation systems employ simplified GPS-IMU combinations for route planning.
- Infrastructure:Smart buoy networks and autonomous dredging platforms support channel maintenance in Vietnam's Lach Huyen and Cai Mep expansions.
Military applications absorb the bulk of installed capacity; commercial maritime is expanding most quickly.
Technology:
Cost tier differentiation separates premium multi-sensor fusion deployments from economy single-source positioning systems, with price-performance ratios determining adoption in crew-constrained versus budget-constrained use cases.
- Lidar:Solid-state beam steering enables 360-degree environmental mapping at 200-meter range for port automation. Shanghai and Ningbo-Zhoushan terminal operators specify automotive-grade lidar repurposed for marine salt spray conditions, with procurement volumes concentrated among three framework agreement holders.
- Computer Vision:Convolutional neural networks process camera feeds for vessel classification and wake pattern analysis. Japan's coastal shipping corridors deploy vision-dominant systems in Seto Inland Sea routes where precipitation degradation is less severe than Southeast Asian monsoon zones.
- GPS:Differential correction services provide sub-meter accuracy for open-water navigation with minimal sensor complexity.
- Radar:Frequency-modulated continuous wave systems penetrate precipitation for all-weather operations in tropical waterways.
Lidar captures the dominant share of sensor procurement value; computer vision is climbing the fastest as algorithm efficiency improves on edge hardware.
End User:
Customer type determines integration complexity, with legacy fleet operators facing retrofit constraints that greenfield deployers avoid.
- Logistics Companies:Container terminal operators and coastal shipping lines commission autonomous tugboats and unmanned cargo vessels. COSCO Shipping Ports and Hutchison Ports Holdings negotiate fleet-scale sensor procurement, consolidating purchasing decisions that previously resided at individual terminal level.
- Public Sector:Maritime safety authorities and hydrographic services deploy autonomous survey vessels for seabed mapping. Australia's Commonwealth port equipment standards create certification templates that Indo-Pacific vendors adopt for regional market access.
- Automakers:Urban autonomous mobility programs in Beijing source localization algorithms for robo-taxi deployment.
- Aviation:Airport ground handling automation and drone traffic management systems require centimeter-precision positioning for congested airspace coordination.
Logistics companies direct the majority of current procurement; public sector deployment is gaining share fastest as regulatory frameworks mature.
Deployment:
Volume concentration in latency-sensitive applications favors local processing architectures over cloud-dependent alternatives.
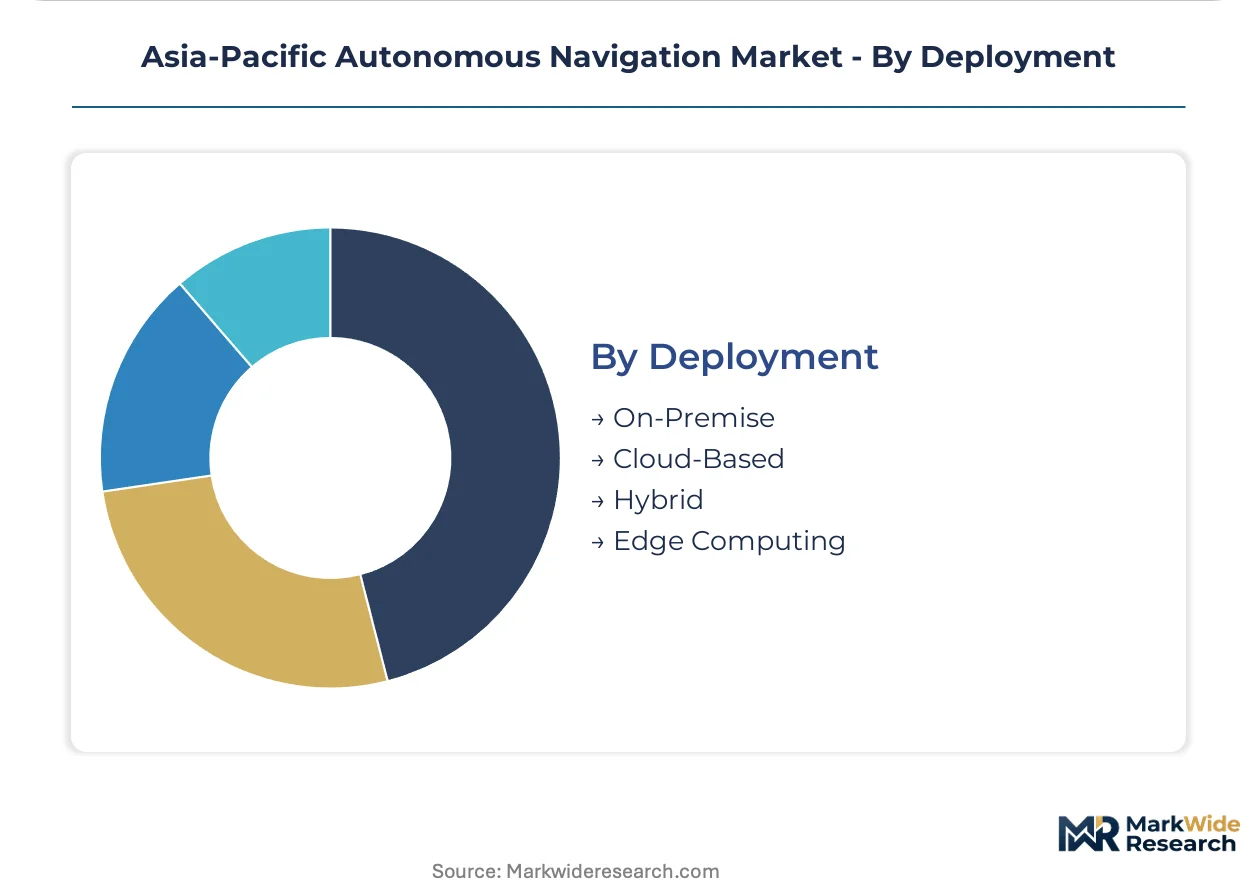
- Edge Computing:On-vessel GPUs and neural processing units execute SLAM and collision avoidance without network dependency. Singapore's Tuas terminal mandates edge deployment for autonomous cranes, where 5G round-trip latency exceeds safe stopping distances for 40-ton container movements.
- Hybrid:Split architectures process time-critical functions locally while offloading fleet optimization and predictive maintenance to shore-based servers. China's MIIT certification pathways accommodate hybrid configurations for vessels operating within coastal 5G coverage zones.
- On-Premise:Fully localized systems serve defense applications with air-gapped security requirements.
- Cloud-Based:Centralized processing supports simulation and training workloads with tolerance for 100+ millisecond latency.
Edge computing dominates installed base; hybrid architectures are expanding most quickly as 5G maritime coverage extends across Pacific shipping lanes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in coastal shipping corridors and automated port clusters across the Asia-Pacific basin, with procurement decisions increasingly centralized among multi-terminal operators.
China
Shanghai's Yangshan terminal and Ningbo-Zhoushan port cluster absorb the majority of lidar-guided tugboat deployments, driven by 24-hour operational mandates. MIIT safety certification requirements compress vendor qualification timelines for autonomous vessel approvals. The Yangtze River Delta terminal operators control 80 percent of regional autonomous tugboat deployment decisions through consolidated framework agreements.
Japan
Aging seafarer demographics compel fleet operators toward unmanned navigation platforms in Tokyo Bay and Seto Inland Sea corridors. METI issues explicit liability frameworks for unmanned coastal vessels, mandating redundant propulsion for Category III autonomous operations. Yokohama engineering heritage anchors maritime navigation system development for gyrocompass and electronic chart applications.
Singapore
Tuas mega-port drives edge computing hardware procurement for latency-sensitive collision avoidance in autonomous crane operations. The Maritime and Port Authority coordinates with terminal operators to mandate local processing where 5G round-trip latency exceeds safe stopping distances. PSA International evaluates algorithm providers on individual pipeline component benchmarks rather than bundled system tenders.
South Korea
Busan-Ulsan coastal shipping lanes face crew shortage pressures similar to Japan, prompting MFDS-aligned transport ministry drafting of autonomous shipping performance benchmarks. The ministry coordinates with Australia's maritime safety authority on reciprocal certification recognition protocols. Daegu-Gyeongbuk manufacturing clusters supply sensor components for regional vessel automation programs.
Australia
Commonwealth port equipment standards create certification templates that Indo-Pacific vendors adopt for regional market access. The TGA-equivalent maritime regulator imposes equipment certification shaping vendor market access across Indo-Pacific ports. Western Australian mining ports deploy autonomous survey vessels for seabed mapping in iron ore export channels.
Asia-Pacific Autonomous Navigation Market Competitive Landscape
Strategic partnerships dominate the current landscape as sensor vendors align with algorithm developers and port operators to secure framework agreement positions. The vendor base clusters around three archetypes: maritime heritage electronics manufacturers, urban autonomous mobility specialists, and industrial automation conglomerates. Consolidation pressure intensifies as buyer concentration among terminal operators eliminates small-scale suppliers. Geographic expansion and technology licensing represent the primary competitive vectors for non-incumbent entrants.
Within the maritime heritage tier, FURUNO ELECTRIC CO., LTD and KONGSBERG occupy positions as anchors of gyrocompass and subsea automation expertise respectively. Among urban mobility specialists, Momenta exemplifies algorithm development concentration drawn from Beijing R&D infrastructure. These three entities represent distinct strategic archetypes: Yokohama-born electronic chart systems, Stavanger-originated maritime automation, and China-based urban autonomous software stacks.
| Leading Market Players |
|---|
| Momenta |
| Advanced Navigation |
| Brain Corporation |
| FURUNO ELECTRIC CO., LTD |
| YUJIN ROBOT Co., Ltd. |
| Kollmorgen |
| KONGSBERG |
| Trimble Inc. |
| Youibot Robotics |
| Others |
Value Network & Pricing Analysis
Framework agreement consolidation among Yangtze River Delta terminal operators forces sensor vendors into multi-year volume commitments, compressing margin structures for lidar and radar suppliers while shifting procurement leverage toward fleet-scale buyers.
Pricing Analysis
Volume procurement through consolidated terminal operators captures margin at the expense of smaller project-specific vendors. Three-tier pricing structure across premium, standard, and economy levels separates military-grade redundant systems from commercial maritime configurations and simplified consumer navigation units. Pricing pressure stems from automotive-grade lidar repurposing for marine salt spray conditions, eroding specialty premiums. Logistics companies exhibit highest price sensitivity due to fleet-scale deployment mandates, while military buyers prioritize latency performance over unit cost.
Supply Chain Analysis
Freight cost volatility from rare earth processing concentration in China amplifies solid-state lidar component exposure. Manufacturing clusters in China, South Korea, and Japan anchor sensor assembly, drawing from gallium nitride substrates, indium phosphide wafers, and precision optical coatings. Single-source vulnerability runs through concentrated upstream rare earth separation facilities. Distribution runs through regional port equipment integrators who bundle sensor modules with bridge system reconfiguration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer concentration among multi-terminal operators eliminates small-scale suppliers, forcing consolidation plays as framework agreements lock out fragmented competitors.
For Market Incumbents: Cement framework agreement positions with COSCO Shipping Ports and Hutchison Ports Holdings through captive supply of edge computing hardware. Deepen algorithm development partnerships with Beijing R&D clusters to defend against urban autonomous mobility specialists encroaching on maritime applications. Vertical integration into solid-state beam steering manufacturing insulates against rare earth supply volatility. For New Entrants and Emerging Players: Port operators in Vietnam's Lach Huyen and Cai Mep expansions lack legacy automation infrastructure, creating greenfield deployment opportunities without retrofit integration burdens. Target coastal shipping corridors in South Korea where MFDS-aligned benchmarks remain in drafting phase, enabling early certification alignment. Pursue algorithm modularization strategies that separate perception software into discrete detection and classification layers for 6-month procurement cycles. For Investors and Strategic Acquirers: The window for entry favors SLAM algorithm specialists with cross-training in robotics and hydrographic surveying. Long-term viability hinges on regulatory interoperability as METI, MIIT, and Australia's TGA-equivalent maritime authority converge on reciprocal certification protocols. Watch for the first jurisdiction achieving standardization export across the Asia-Pacific basin as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Positioning | Multi-year fleet-scale contracts with Yangtze Delta operators lock out fragmented competitors. |
| Algorithm Modularization | Discrete perception layers enable PSA International's 6-month procurement benchmarks. |
| Edge Computing Hardware Supply | Local GPU deployment satisfies Singapore Tuas terminal latency mandates for crane safety. |
| Reciprocal Certification Alignment | METI-MFDS-Australia protocol convergence reduces 18-24 month dual approval timelines. |
| Rare Earth Supply Integration | Upstream control over gallium nitride substrates insulates against solid-state lidar volatility. |
Research Methodology
Document review covered MIIT safety certification pathways, METI autonomous maritime guidelines, and SAMR GB standards documentation, complemented by interviews with port automation procurement directors, maritime electronics engineering leads, and coastal shipping fleet managers. Secondary validation drew from customs trade data, terminal operator framework agreement disclosures, and naval unmanned systems procurement records. Bottom-up sensor deployment estimates triangulated against top-down regional port automation investment flows.
Cross-referencing historical lidar-radar-vision adoption curves with expert panel inputs on SLAM algorithm maturation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include application tier, sensor technology stack, deployment architecture, and end-user integration complexity. CAGRs derived from differential adoption rates between military redundancy requirements and commercial crew shortage mitigation. Forecast inputs incorporated monsoon precipitation degradation factors for Southeast Asian waterways and 5G-V2X convergence timelines for coordinated multi-vessel traffic management.
Several conditions sit outside the modeled scope, including unforeseen regulatory fragmentation between METI and MIIT liability frameworks, breakthrough solid-state lidar cost reductions from alternative substrate materials, and Pacific naval budget reallocation affecting unmanned surface vessel procurement. Forecasts reflect documented assumptions on certification timeline compression and rare earth supply stability. Stakeholders should weight assumptions against their own operating context and regional regulatory engagement capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Drone Transponders Market