
 Asia-Pacific Inertial Systems Market | 2026-2036
Asia-Pacific Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Inertial Systems Market Outlook
Defense procurement concentration is decoupling from traditional Western supply chains as Asia-Pacific militaries diversify vendor relationships. Honeywell Aerospace Inc leverages its Singapore service hub to sustain regional aftermarket support for tactical-grade inertial navigation units. Thales Group anchors its positioning through Australian submarine program partnerships and localized gyroscope calibration facilities. STMicroelectronics NV competes on MEMS cost curves, shipping high-volume motion-tracking chips to Chinese smartphone and drone manufacturers.
Inertial systems integrate gyroscopes and accelerometers to measure angular rate and linear acceleration, typically achieving bias stability below 0.01 degrees per hour in navigation-grade configurations for autonomous vehicle and missile guidance applications. MEMS dominates unit volumes across consumer and automotive tiers, while fiber optic gyroscopes command premium positioning in submarine and satellite attitude control where drift tolerance below 0.001 degrees per hour remains mandatory. Ring laser technology occupies a shrinking but defended niche in strategic ballistic missile platforms where radiation hardness requirements exclude solid-state alternatives. Navigation systems applications pull the strongest growth trajectory as maritime autonomous surface vessels and urban air mobility prototypes multiply across the region.
Japan's METI enforces JIS standards on inertial sensor reliability, while China's SAMR mandates GB certification for military-civil fusion components entering dual-use supply chains. Australia's TGA and South Korea's MFDS impose electromagnetic compatibility testing that extends product qualification timelines by six to twelve months for new entrants. Stakeholders must monitor how India's PLI scheme for electronics manufacturing reshapes component localization requirements before committing to greenfield sensor fabrication investments.
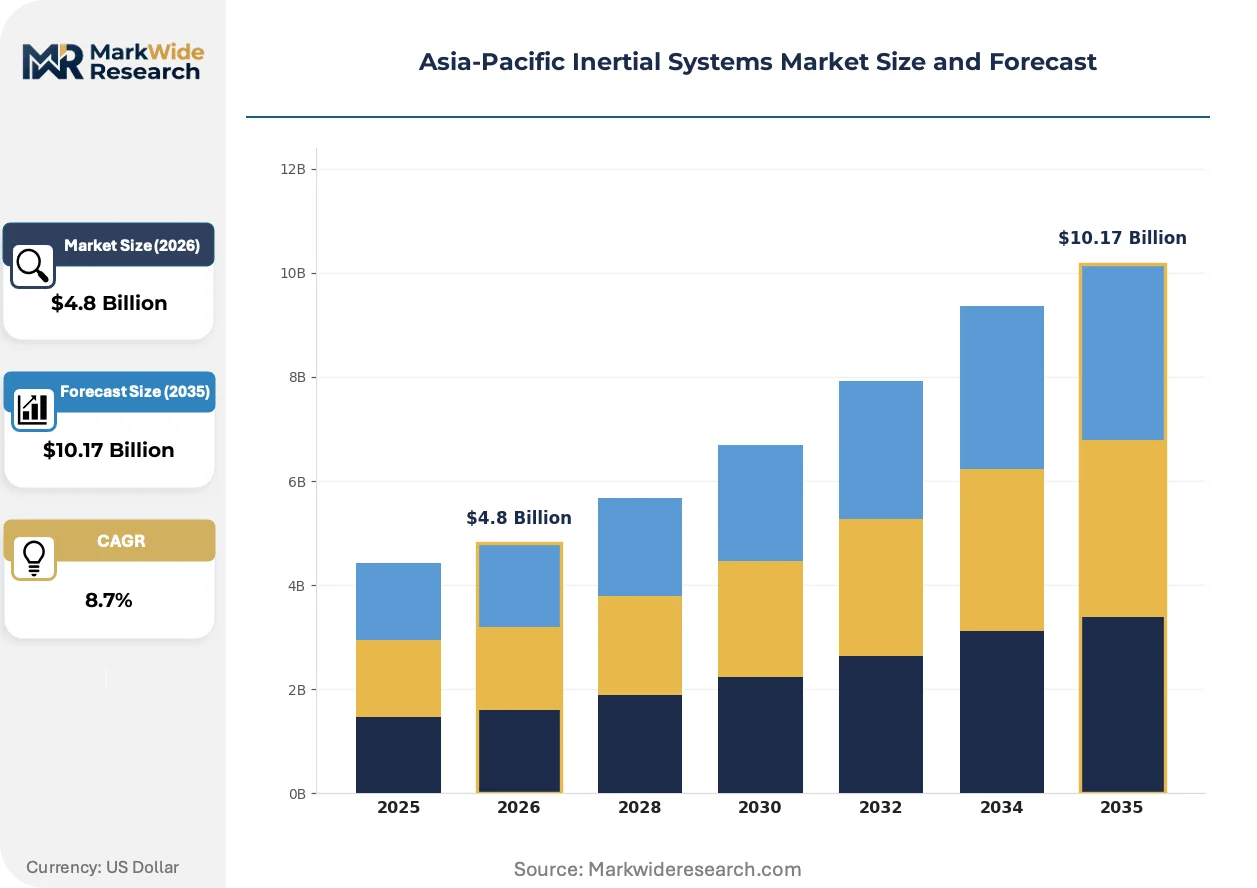
Market Dynamics
Defense procurement diversification across Asia-Pacific is decoupling inertial system sourcing from legacy Western supply chains, forcing component vendors to establish localized calibration facilities and dual-use certification pathways.
Growth Catalysts
- China's SAMR GB certification:Military-civil fusion mandates accelerate domestic MEMS gyroscope production for drone and autonomous vehicle platforms, creating captive demand for navigation-grade components.
- India's defense modernization pipeline:Indigenous missile programs and naval surface vessel upgrades require fiber optic gyroscopes with drift tolerance below 0.001 degrees per hour, pulling specialized imports.
- MEMS cost curve compression:High-volume motion-tracking chip fabrication enables tier-one automotive suppliers to integrate inertial measurement units into mass-market electric vehicle stability systems.
Market Restraints
- Precision quartz and rare earth input volatility:Yttrium and europium price swings destabilize ring laser gyroscope mirror coating costs, squeezing margins on strategic ballistic missile guidance systems.
- Single-source fiber coil concentration:Japanese suppliers dominate polarization-maintaining fiber for tactical-grade FOGs, exposing Australian and South Korean defense contractors to allocation risk during surge procurement.
- Radiation hardness exclusion:Solid-state MEMS platforms fail strategic satellite qualification thresholds above 100 krad total ionizing dose, preserving costly legacy ring laser installations.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for sensor fabrication attract greenfield MEMS foundry investments targeting aerospace and defense qualification.
- Urban air mobility prototyping:South Korean autonomous aerial vehicle testbeds in Gyeonggi Province create demand for compact navigation-grade inertial systems with sub-0.01 degree per hour bias stability.
- Maritime autonomous surface vessels:Singapore and Australian port authorities mandate redundant attitude reference systems for unmanned cargo transit, opening retrofit markets for existing commercial fleets.
Industry Challenges
- Calibration technician scarcity:Specialized gyroscope drift characterization expertise concentrates in Japanese and Chinese national laboratories, constraining regional service hub expansion.
- Dual-use export control alignment:Divergent Wassenaar Arrangement interpretations between Australian, Japanese, and Indian customs authorities extend component transit documentation processing by four to eight weeks.
- Legacy platform integration friction:Analog-to-digital signal conditioning mismatches complicate MEMS retrofit into 1990s-era submarine inertial navigation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Inertial Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MEMS, Fiber Optic, Ring Laser, Quartz End User: Aerospace, Defense, Automotive, Marine Technology: Inertial Navigation, Motion Tracking, Attitude Control, Stabilization Application: Guidance Systems, Navigation Systems, Robotics, Geophysical |
| Companies Covered | Honeywell Aerospace Inc, Northrop Grumman Corporation, Bosch Sensortec GmbH, Analog Devices Inc, Thales Group, Collins Aerospace, Safran Group, STMicroelectronics NV, Moog Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Inertial Systems Market Strategic Shifts
Photonic integration and AI-assisted sensor fusion are compressing form factors while elevating navigation accuracy thresholds across defense and commercial autonomous platforms.
Fiber optic gyroscope miniaturization is expanding into tactical unmanned aerial vehicle payloads previously served by MEMS alternatives. South Korean defense contractors now specify palm-sized FOG units for loitering munition guidance. This shift is compressing the performance gap between navigation-grade and tactical-grade pricing tiers.
Japan's METI JIS reliability standards now mandate 10,000-hour mean time between failures for inertial sensors entering dual-use supply chains. Component vendors must submit accelerated life test data to designated conformity assessment bodies. Chinese manufacturers are responding by establishing captive reliability testing laboratories in Shenzhen and Xi'an.
Defense procurement offices in Australia and India now unbundle long-term calibration service contracts from initial hardware purchases. Tier-one system integrators compete on aftermarket technical support rather than unit cost alone. This behavioral shift concentrates vendor selection around Singapore and Japanese service hub proximity rather than manufacturing origin.
Asia-Pacific Inertial Systems Market Segmentation
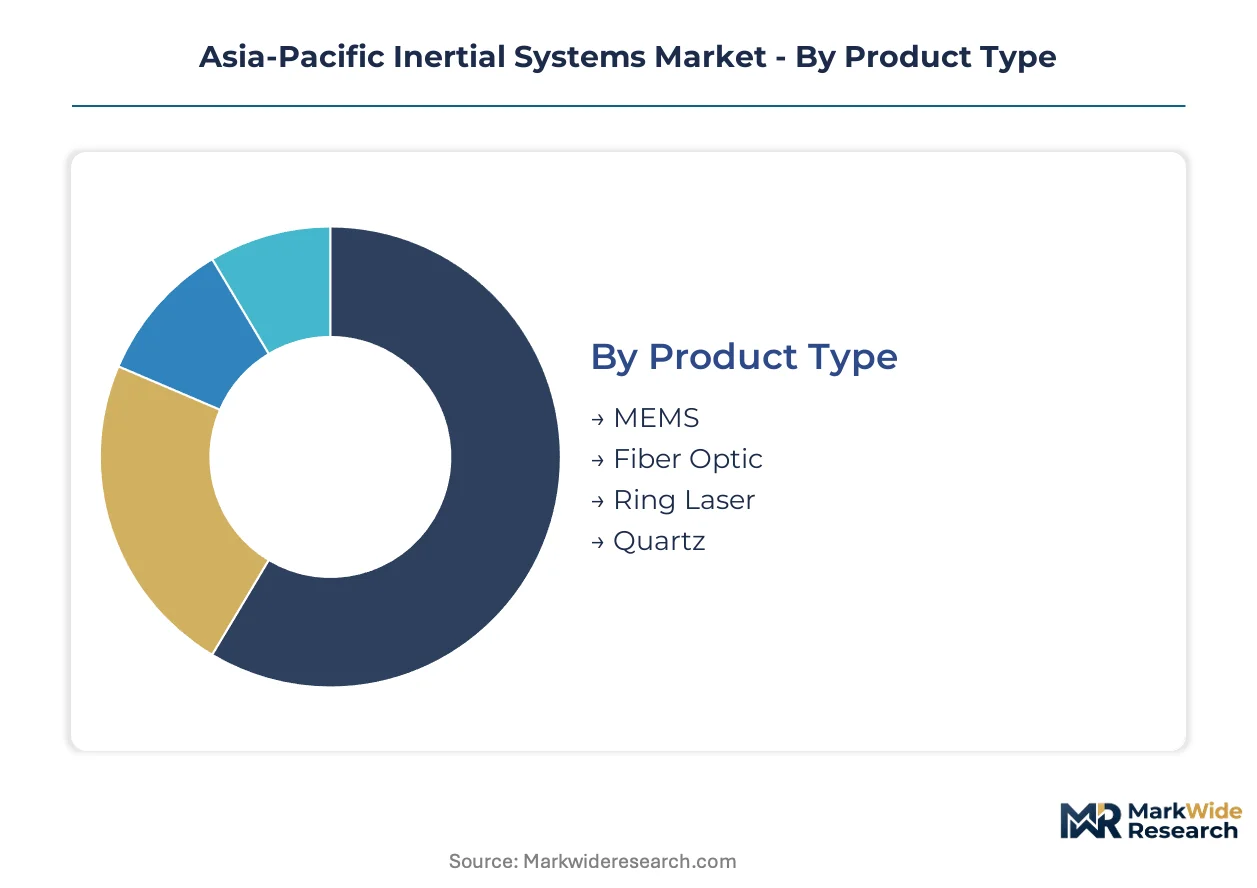
Technology substitution cycles and defense qualification pathways fragment the Asia-Pacific inertial systems landscape into sharply differentiated performance tiers. Vendors must align product roadmaps with specific drift tolerance thresholds and radiation hardness requirements rather than pursuing horizontal scale.
Product Type:
Upgrade cycles from legacy ring laser installations to solid-state alternatives are compressing procurement timelines across defense and commercial fleets.
- Fiber Optic:Polarization-maintaining fiber coils achieve drift tolerance below 0.001 degrees per hour, meeting Indian naval surface vessel and Australian submarine program specifications. Japanese suppliers dominate coil feedstock, exposing regional contractors to allocation risk during surge procurement.
- MEMS:Silicon-based motion-tracking chips leverage semiconductor cost curves for high-volume automotive and consumer drone integration. China's SAMR GB certification mandates now accelerate domestic MEMS gyroscope production for autonomous vehicle platforms.
- Ring Laser:Helium-neon gas discharge tubes with precision quartz mirrors remain mandatory for strategic ballistic missile guidance where radiation hardness above 100 krad total ionizing dose excludes solid-state alternatives.
- Quartz:Piezoelectric resonator configurations serve mid-tier industrial stabilization with moderate bias stability requirements.
MEMS sits at the top of the volume ranking, with Fiber Optic climbing the fastest.
End User:
Customer procurement maturity spans from price-sensitive automotive tier-one suppliers to defense offices unbundling hardware from long-term calibration service contracts.
- Defense:Indigenous missile programs across India and naval modernization pipelines require navigation-grade specifications with dedicated technical support rather than unit cost optimization.
- Aerospace:Urban air mobility prototypes in South Korea's Gyeonggi Province testbeds demand compact attitude reference systems with sub-0.01 degree per hour bias stability for autonomous aerial vehicle navigation.
- Automotive:Electric vehicle stability systems integrate high-volume inertial measurement units as tier-one suppliers exploit MEMS cost compression for mass-market deployment.
- Marine:Singapore and Australian port authorities mandate redundant attitude reference systems for maritime autonomous surface vessels, opening retrofit markets for existing commercial fleets.
Defense commands the premium pricing tier, while Automotive generates the steepest unit volume expansion.
Technology:
Functional integration depth separates navigation-grade platforms requiring sensor fusion algorithms from discrete motion-tracking components.
- Inertial Navigation:Multi-axis gyroscope and accelerometer arrays with Kalman filtering deliver position, velocity, and attitude outputs for autonomous vehicle and missile guidance applications.
- Attitude Control:Satellite and submarine platforms rely on drift-tolerant gyroscope feedback for orientation stabilization where GPS denial or underwater operation precludes external referencing.
- Motion Tracking:Consumer electronics and industrial automation employ simplified accelerometer-gyroscope combinations for gesture recognition and vibration monitoring.
- Stabilization:Camera gimbals and precision manufacturing equipment use lower-grade inertial sensors for mechanical platform damping.
Inertial Navigation anchors revenue concentration, with Attitude Control gaining share fastest in submarine and satellite procurement.
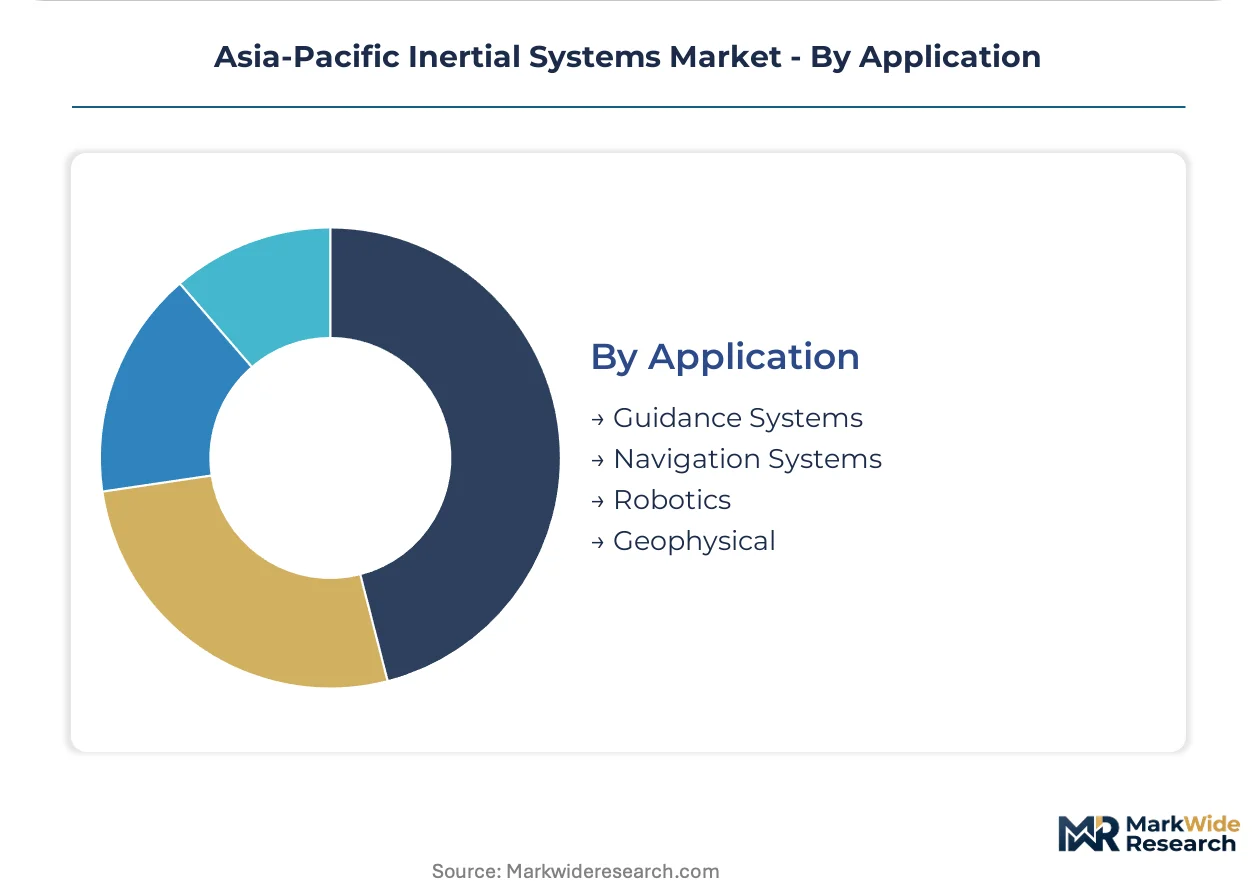
Application:
Deployment environment severity dictates certification grade, from benign commercial robotics to radiation-hardened strategic systems.
- Navigation Systems:Maritime autonomous surface vessels and urban air mobility prototypes multiply across the region, pulling the strongest growth trajectory for redundant attitude reference architectures.
- Guidance Systems:Missile and munition platforms require bias stability below 0.01 degrees per hour for terminal accuracy, with Indian defense procurement offices prioritizing indigenous integration.
- Robotics:Warehouse automation and surgical platforms employ mid-grade inertial measurement units for spatial positioning feedback.
- Geophysical:Seismic survey and drilling operations utilize gyroscopic north-finding for borehole orientation in oil and gas exploration.
Navigation Systems leads deployment velocity, with Geophysical representing the most mature, slowest-expanding segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's aerospace corridor generates volume scale unmatched elsewhere in the region, while India's defense modernization pipeline concentrates procurement around specialized navigation-grade specifications.
China
Drone manufacturers and autonomous vehicle developers in Shenzhen and Xi'an drive MEMS gyroscope consumption at industrial scale. SAMR mandates GB certification for military-civil fusion components, forcing domestic foundries to establish captive reliability testing laboratories. The Yangtze River Delta hosts the densest concentration of motion-tracking chip fabrication facilities serving automotive tier-one suppliers.
India
Indigenous missile programs and naval surface vessel upgrades require fiber optic gyroscopes with drift tolerance below 0.001 degrees per hour. The PLI scheme for electronics manufacturing attracts greenfield MEMS foundry investments targeting aerospace qualification. Bengaluru and Hyderabad anchor defense research clusters where calibration service contracts unbundle from hardware procurement.
Japan
Polarization-maintaining fiber coil production concentrates among specialized suppliers serving tactical-grade FOG demand across the region. METI enforces JIS standards mandating 10,000-hour mean time between failures for dual-use supply chain entry. Nagoya and Tokyo host national laboratories where gyroscope drift characterization expertise constrains regional service hub expansion.
South Korea
Urban air mobility prototypes in Gyeonggi Province testbeds demand compact navigation-grade inertial systems with sub-0.01 degree per hour bias stability. MFDS electromagnetic compatibility testing extends product qualification timelines for new entrants. Busan-Ulsan and the Seoul Capital Area concentrate autonomous aerial vehicle development clusters pulling specialized component imports.
Australia
Submarine program partnerships with Thales Group anchor localized gyroscope calibration facilities for naval modernization. TGA electromagnetic compatibility requirements filter component eligibility for defense procurement. Perth and Adelaide host maritime autonomous surface vessel development where port authorities mandate redundant attitude reference systems for unmanned cargo transit.
Asia-Pacific Inertial Systems Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across sharply tiered performance segments. The vendor base separates into navigation-grade system integrators, MEMS volume manufacturers, and legacy platform maintenance providers. Three archetypes dominate: aerospace-defense conglomerates with captive calibration networks, semiconductor foundries exploiting cost curves for automotive tiers, and precision optics specialists controlling fiber coil feedstock. M&A activity concentrates on calibration service capability acquisition, while greenfield investments cluster around India's PLI-attracted sensor fabrication.
Among aerospace-defense conglomerates, Honeywell Aerospace Inc and Thales Group exemplify the integrated service hub model, with Singapore and Australian facilities anchoring regional aftermarket support. STMicroelectronics NV occupies the semiconductor-foundry archetype, shipping high-volume motion-tracking chips to Chinese smartphone and drone manufacturers. Northrop Grumman Corporation represents the precision-navigation tier where drift tolerance specifications below 0.001 degrees per hour command premium positioning.
| Leading Market Players |
|---|
| Honeywell Aerospace Inc |
| Northrop Grumman Corporation |
| Bosch Sensortec GmbH |
| Analog Devices Inc |
| Thales Group |
| Collins Aerospace |
| Safran Group |
| STMicroelectronics NV |
| Moog Inc |
| Others |
Value Chain & Pricing Dynamics
Navigation-grade versus tactical-grade performance divergence splits the Asia-Pacific inertial systems market into parallel pricing architectures, with certification thresholds and drift tolerance specifications determining both procurement premiums and supplier qualification pathways. China's SAMR GB mandates and Japan's METI JIS reliability standards erect tiered entry barriers that cascade through component sourcing decisions and regional distribution configurations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for MEMS motion-tracking chips as domestic foundries achieve automotive-grade qualification. Three-tier pricing structure across navigation-grade, tactical-grade, and industrial-grade levels reflects drift tolerance thresholds and radiation hardness certification. Cost compression in consumer drone and smartphone tiers intensifies as STMicroelectronics and Bosch Sensortec exploit semiconductor scale curves. Automotive tier-one suppliers exhibit highest price sensitivity, while Australian submarine program offices prioritize technical support over unit cost optimization.
Supply Chain Analysis
Regional distribution centers in Singapore and Tokyo anchor hub-and-spoke patterns for calibration equipment and polarization-maintaining fiber coil feedstock. Manufacturing concentrates in China, Japan, and South Korea, with Japanese suppliers dominating specialized fiber coil production for tactical-grade FOGs. Rare earth inputs including yttrium and europium for ring laser gyroscope mirror coatings draw from concentrated extraction networks. Single-source fiber coil concentration creates allocation vulnerability during surge defense procurement. Distribution runs through authorized service hubs rather than direct OEM relationships for navigation-grade systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's military-civil fusion mandates and Japan's reliability standards continuously elevate qualification barriers, driving replacement demand across installed defense and commercial fleets.
For Market Incumbents: Lock in calibration service contracts by expanding Singapore and Australian technical support facilities before India's PLI-attracted foundries achieve defense qualification. Defensive consolidation around polarization-maintaining fiber coil suppliers mitigates allocation risk from Japanese feedstock concentration. Capacity additions in Chinese MEMS fabrication threaten margin compression in automotive tiers. For New Entrants and Emerging Players: The tactical-to-navigation-grade price-point gap opens white-space targeting for South Korean urban air mobility developers seeking compact FOG units below established defense contractor premiums. India's indigenous missile programs present penetrable entry through unbundled hardware-calibration procurement structures. Go-to-market positioning should emphasize aftermarket technical proximity over manufacturing origin claims. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration technician scarcity concentrates vendor selection around Japanese and Chinese national laboratory proximity. Long-term viability favors precision optics specialists controlling fiber coil feedstock and MEMS foundries achieving dual-use certification. Watch India's PLI scheme disbursement velocity as inflection indicator for regional manufacturing gravity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Hub Expansion | Proximity to Singapore and Tokyo facilities anchors Australian and Indian defense procurement decisions. |
| Captive Reliability Testing Investment | China's SAMR GB certification mandates accelerate Shenzhen and Xi'an laboratory buildouts for MEMS qualification. |
| Polarization-Maintaining Fiber Backward Integration | Upstream control over Japanese coil suppliers mitigates allocation risk for tactical-grade FOG production. |
| Urban Air Mobility Component Partnership | South Korean Gyeonggi Province testbeds create demand for compact navigation-grade inertial systems. |
| Dual-Use Certification Pathway Development | India's PLI scheme attracts greenfield sensor fabrication targeting aerospace and defense qualification tiers. |
Study Parameters
Bottom-up defense and automotive demand modeling reconciled against top-down MEMS foundry capacity and fiber optic gyroscope shipment tracking forms the analytical core of this study. Primary interviews with defense procurement officers, MEMS fabrication executives, calibration service technicians, and autonomous vehicle platform engineers combined with secondary validation against SAMR certification databases, METI conformity assessment records, and customs trade flows for polarization-maintaining fiber and rare earth coating materials. Triangulation across stakeholder inputs and documented regulatory filings ensures segmentation integrity.
Historical trendline analysis of ring laser gyroscope replacement cycles, MEMS cost curve compression trajectories, and defense procurement authorization patterns informed projection frameworks across the analysis window. Segmentation dimensions span technology type, drift tolerance grade, radiation hardness certification, end-use sector, and regional regulatory cluster. CAGRs derive from installed base turnover rates and emerging application penetration curves, with specific weighting applied to maritime autonomous surface vessel mandates and urban air mobility prototyping timelines.
Caveats apply where rare earth price volatility, Wassenaar Arrangement interpretation divergence, or radiation hardness qualification threshold revisions could materially shift the outlook. Forecasts reflect documented assumptions regarding certification timeline standardization and defense budget authorization continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Drone Transponders Market