
 Global Military Communications Market | 2026-2036
Global Military Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Communications Market Foresight
Radio-frequency engineering talent scarcity is unwinding deployment timelines for next-generation tactical networks. L3Harris Technologies leverages decades of signal-processing expertise to sustain its position in software-defined radio platforms. ASELSAN A.S. anchors regional supply for secure voice networks across Eastern European and Middle Eastern defense customers. General Dynamics Corporation dominates naval satellite communications through integrated shipboard systems.
Military communications encompass encrypted transmission systems, hardened network infrastructure, and electromagnetic spectrum management tools engineered to operate in contested environments with latency below 250 milliseconds and jam-resistant waveforms. These systems enable real-time command authority across dispersed land, sea, air, and space domains. Satellite communications commands the largest value share due to orbital infrastructure costs and sovereign payload requirements, while software-defined radios represent the fastest-expanding technology segment as programmable waveforms replace hardware-specific legacy sets. Command and control applications absorb the majority of procurement budgets because joint all-domain operations demand interoperable decision networks.
The U.S. Department of Defense mandates NSA-certified encryption through the Commercial Solutions for Classified program, while NATO standardization agreements enforce waveform interoperability across allied forces. The EU's Radio Equipment Directive and national spectrum regulators in Germany, France, and the United Kingdom constrain frequency allocation for military use. Stakeholders must monitor quantum-resistant cryptography migration timelines and sovereign satellite constellation buildouts to anticipate procurement priority shifts.
Market Dynamics
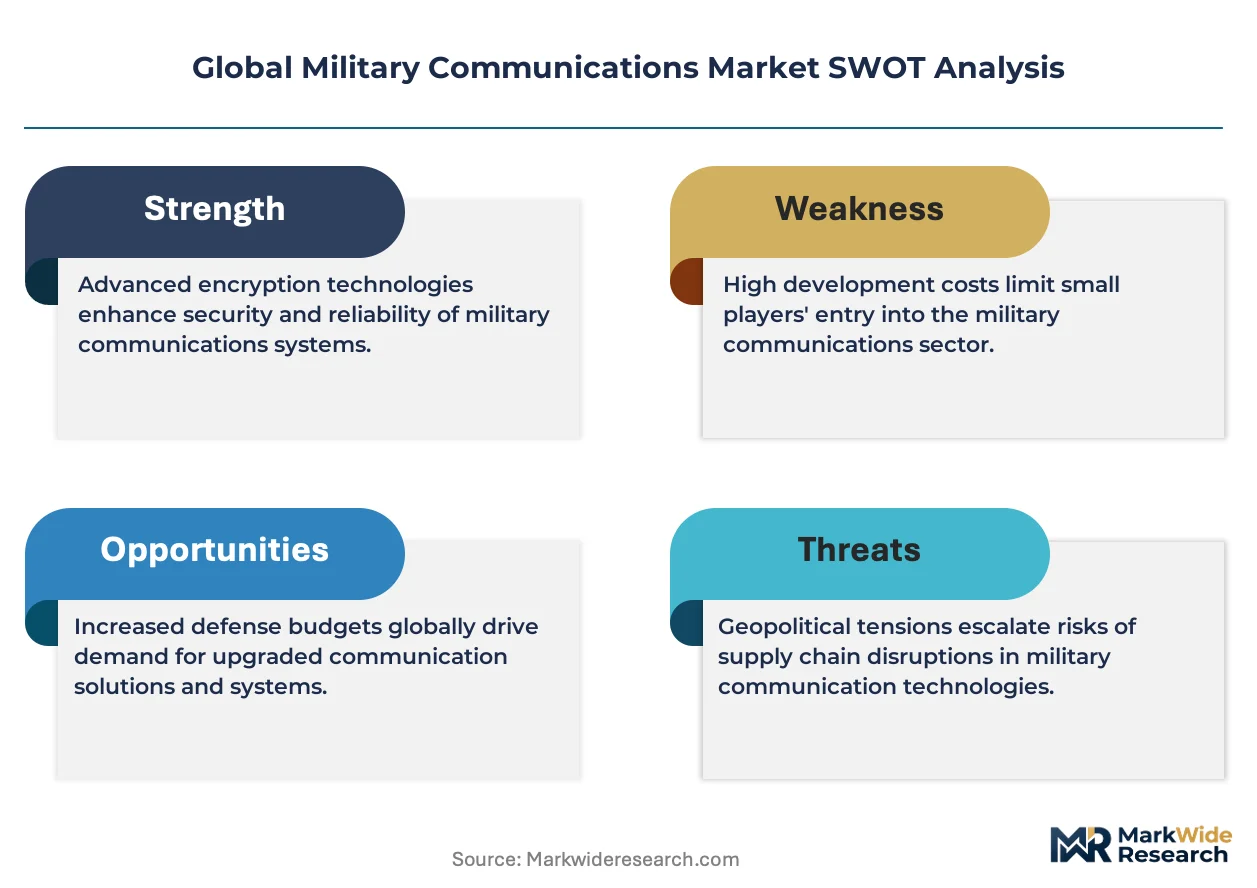
Quantum-resistant cryptography migration is compressing procurement timelines for legacy encryption systems across NATO defense ministries, forcing accelerated R&D budgets and supplier recertification cycles.
Growth Catalysts
- NSA Commercial Solutions for Classified Program:The U.S. Department of Defense mandates certified encryption standards, creating guaranteed demand pipelines for compliant subsystem vendors.
- Joint All-Domain Operations Doctrine:Military commands require interoperable decision networks linking land, sea, air, and space assets, expanding procurement of unified command infrastructure.
- Israeli Defense Modernization:The Israel Defense Forces prioritize battlefield network resilience, driving sustained investment in tactical radio and satellite uplink systems.
Market Restraints
- Gallium Nitride Substrate Costs:Advanced RF components depend on specialized semiconductor materials with concentrated supply from East Asian foundries, creating input price volatility.
- EU Radio Equipment Directive:Frequency allocation constraints in Germany, France, and the United Kingdom limit spectrum availability for military testing and deployment.
- Legacy Waveform Hardware Lock-in:Existing tactical radio fleets use hardware-specific architectures that resist software-defined upgrades without full platform replacement.
Strategic Opportunities
- Polish Defense Procurement Expansion:NATO's eastern flank buildup creates demand for secure voice networks and tactical data links in previously underpenetrated European markets.
- LEO Constellation Integration:Convergence of commercial low-Earth-orbit satellite networks with military terminals offers resilient beyond-line-of-sight connectivity without proprietary orbital infrastructure.
- UK National Shipbuilding Strategy:Royal Navy vessel construction programs mandate integrated communications suites, opening procurement windows for naval satellite system specialists.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized signal-processing expertise required for software-defined radio development remains concentrated among aging workforce cohorts with limited pipeline replenishment.
- NSA Certification Timelines:Encryption module approval cycles extend 18-36 months, delaying revenue recognition for subsystem suppliers and compressing product refresh windows.
- Multi-Domain Integration Complexity:Legacy C4ISR systems built for single-service operations resist interoperability modifications needed for joint command architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Communications Market |
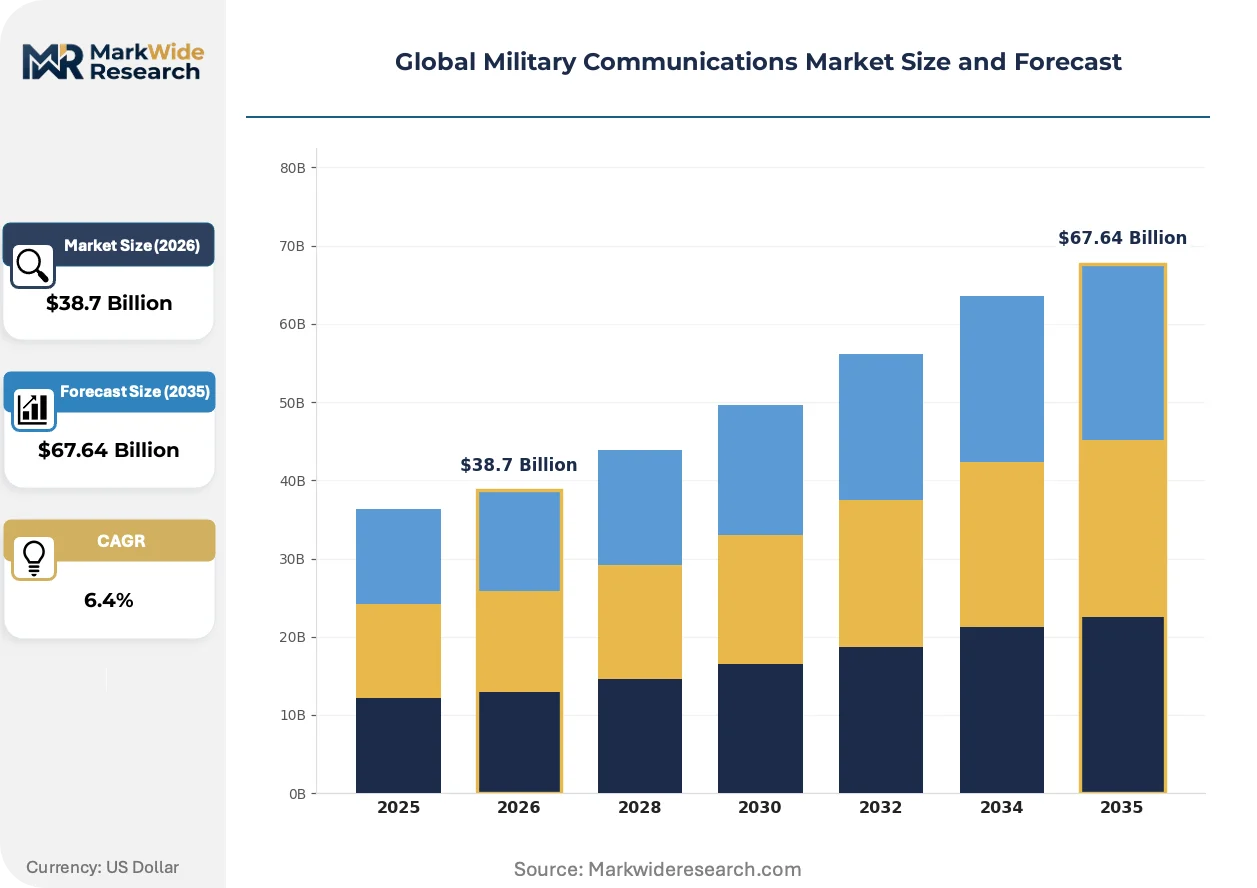
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Communication Type: Satellite Communications, Radio Frequency Systems, Secure Voice Networks, Data Links, Tactical Networks Technology: Software-Defined Radios, Cybersecurity Solutions, Encryption Protocols, Network Management, Signal Processing Application: Command & Control, Surveillance & Reconnaissance, Battlefield Communications, Intelligence Gathering, Logistics Coordination End User: Defense Forces, Paramilitary Units, Peacekeeping Organizations, Homeland Security, Intelligence Agencies |
| Companies Covered | BAE Systems, Lockheed Martin Corporation, L3Harris Technologies, ASELSAN A.S., Thales Group, RTX Corporation, General Dynamics Corporation, Elbit Systems, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Communications Market Shifts & Advancements
Battlefield connectivity architectures are fragmenting into competing technical philosophies, with sovereign payload programs diverging from commercial satellite integration paths and programmable waveforms displacing fixed-function hardware.
Software-defined radio platforms are bifurcating the tactical communications landscape. These systems enable waveform reprogramming without hardware replacement, allowing military operators to adapt to emerging threats in hours rather than years. U.S. Army and Marine Corps procurement offices are accelerating fielding schedules for open-architecture radios. The technology is bifurcating supplier tiers between full-stack platform vendors and specialized waveform software houses.
EU AI Act risk classification frameworks are reshaping autonomous communications system development. Military command networks incorporating machine-learning-based spectrum management must now document algorithmic decision pathways for audit compliance. European defense procurement agencies are inserting AI governance clauses into satellite ground station contracts, requiring vendors to demonstrate human-in-the-loop override capabilities.
Defense ministries are consolidating vendor relationships around integrated system-of-systems providers rather than discrete component suppliers. The U.K. Strategic Command and Australian Defence Force have shifted from siloed radio, satellite, and network procurements toward single-contractor responsibility for end-to-end connectivity. This concentration is most visible in Five Eyes intelligence-sharing arrangements, where interoperability certification now favors vendors with proven multi-domain integration track records.
Global Military Communications Market Segmentation
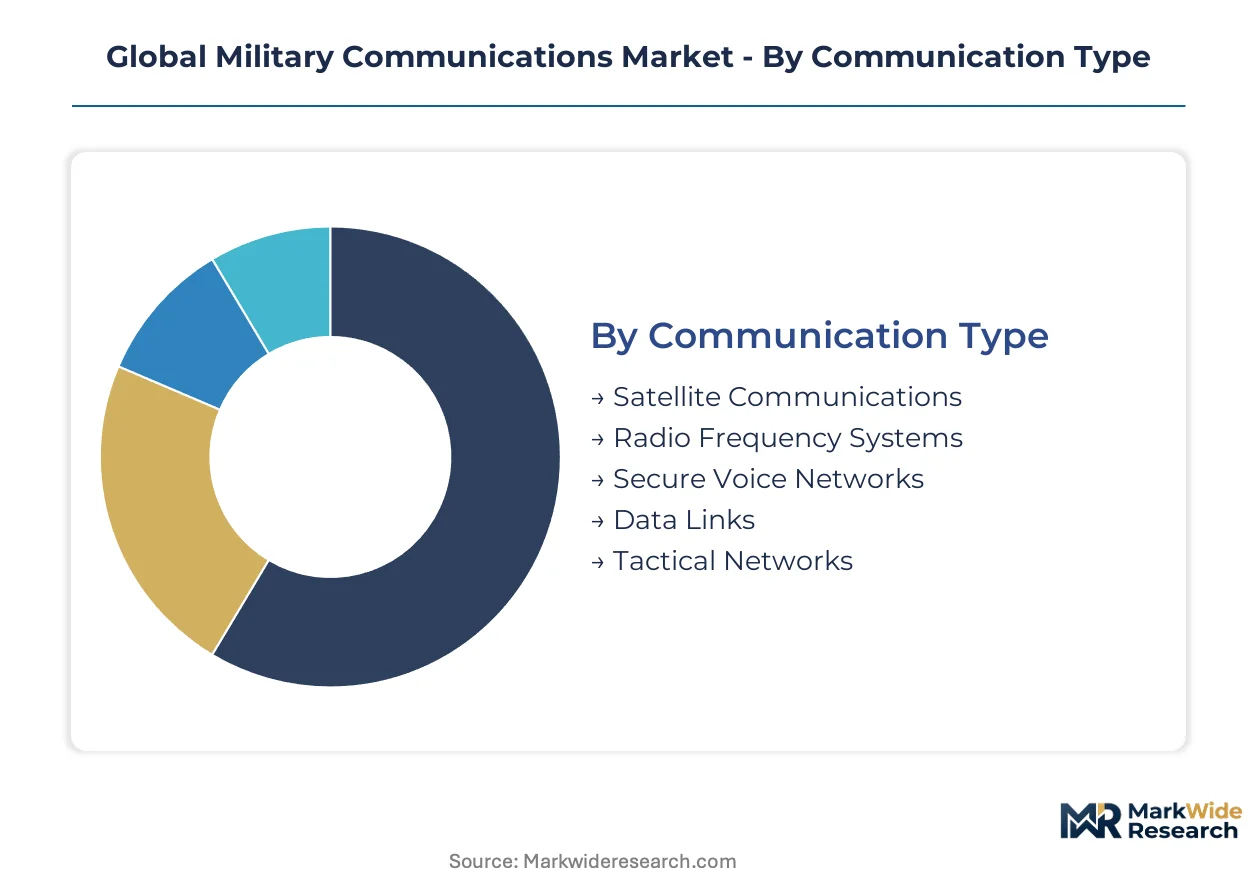
Military communications procurement splits across technical architectures, operational applications, and security classifications. Each segmentation dimension carries distinct vendor qualification requirements and sovereign content rules that reshape competitive access.
Communication Type:
Radio Frequency Systems face the most acute substitution pressure as software-defined architectures displace hardware-specific legacy platforms across NATO modernization programs.
- Satellite Communications:Orbital infrastructure enabling beyond-line-of-sight connectivity through military and commercial payloads. Demand concentrates in the United States and the United Kingdom where sovereign constellation investments and Royal Navy vessel programs drive integrated shipboard terminal procurement.
- Radio Frequency Systems:Ground-based transmission equipment operating across HF, VHF, and UHF bands with hardened electromagnetic protection. Israeli Defense Forces and Polish defense procurement offices prioritize battlefield network resilience, accelerating open-architecture radio fielding schedules.
- Secure Voice Networks:Encrypted audio transmission systems with NSA Commercial Solutions for Classified certification. NATO standardization agreements enforce waveform interoperability across allied forces.
- Data Links:High-bandwidth digital channels connecting sensors to shooters in contested spectrum environments. Joint All-Domain Operations doctrine expands unified command infrastructure requirements.
- Tactical Networks:Mobile ad-hoc mesh systems enabling peer-to-peer connectivity without fixed infrastructure. Eastern European NATO members expand procurement following regional security realignment.
Satellite Communications anchors the volume base while Software-Defined Radios embedded within Radio Frequency Systems gain share at the steepest rate.
Technology:
Cost tiering separates sovereign development programs from commercial subsystem integration paths, with full-stack platform vendors capturing premium positions.
- Software-Defined Radios:Programmable waveform platforms enabling threat adaptation without hardware replacement. U.S. Army and Marine Corps procurement offices accelerate fielding schedules as programmable architectures displace fixed-function hardware.
- Cybersecurity Solutions:Defensive countermeasures protecting network integrity against electronic warfare and intrusion attempts. Quantum-resistant cryptography migration compresses procurement timelines across NATO defense ministries.
- Encryption Protocols:NSA-certified modules ensuring classified information protection through Commercial Solutions for Classified compliance. Approval cycles extend 18-36 months, delaying supplier revenue recognition.
- Network Management:Centralized orchestration tools for spectrum allocation and traffic prioritization. EU AI Act risk classification frameworks reshape autonomous system development requirements.
- Signal Processing:Specialized RF engineering capabilities concentrated among aging workforce cohorts with limited pipeline replenishment. L3Harris Technologies leverages decades of expertise in this domain.
Encryption Protocols anchors the volume base while Software-Defined Radios climb the fastest as programmable waveforms replace legacy sets.
Application:
Volume concentration follows joint force command infrastructure investments, with multi-domain integration complexity favoring system-of-systems providers over component specialists.
- Command & Control:Decision networks linking dispersed land, sea, air, and space assets through interoperable architectures. U.K. Strategic Command and Australian Defence Force consolidate vendor relationships around end-to-end connectivity responsibility.
- Surveillance & Reconnaissance:Sensor-to-shooter data pipelines requiring low-latency transmission below 250 milliseconds. Five Eyes intelligence-sharing arrangements favor vendors with proven multi-domain integration track records.
- Battlefield Communications:Tactical connectivity for maneuver units operating in contested electromagnetic environments. Israeli Defense Forces prioritize network resilience investments.
- Intelligence Gathering:Secure collection and dissemination systems for classified operational data. Intelligence Agencies represent a specialized end-user segment with distinct procurement protocols.
- Logistics Coordination:Supply chain visibility networks connecting rear-area support to forward-deployed forces. Homeland Security applications extend into critical infrastructure protection.
Command & Control anchors the volume base while Surveillance & Reconnaissance expands most quickly under Joint All-Domain Operations doctrine.
End User:
Customer type segmentation reveals procurement authority fragmentation, with defense ministries consolidating spend while paramilitary and security agencies operate through separate budget lines.
- Defense Forces:National military services operating heavy platforms and strategic systems. United States, United Kingdom, and Israel concentrate modernization investment in joint force command infrastructure.
- Paramilitary Units:Gendarmerie, coast guard, and border security forces requiring tactical communications without full military specifications. Polish defense procurement expansion creates demand in previously underpenetrated European markets.
- Peacekeeping Organizations:Multinational mission forces dependent on interoperable equipment across contributing nations. NATO standardization agreements enable equipment sharing.
- Homeland Security:Domestic agencies protecting critical infrastructure and responding to emergent threats. EU Radio Equipment Directive constrains spectrum availability for testing and deployment.
- Intelligence Agencies:Clandestine services with specialized requirements for low-probability-of-intercept systems. NSA certification mandates govern subsystem selection.
Defense Forces anchors the volume base while Homeland Security shows the steepest expansion trajectory as critical infrastructure protection budgets grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The NSA anchors procurement governance for the dominant geography through Commercial Solutions for Classified certification mandates. Defense ministries across five nations concentrate modernization budgets on quantum-resistant encryption migration and software-defined radio fielding.
United States
The U.S. Army and Marine Corps accelerate open-architecture radio procurement under Joint All-Domain Operations doctrine. FCC spectrum allocation proceedings constrain military testing windows in shared bands. Huntsville, Alabama clusters missile defense and satellite ground station development alongside Redstone Arsenal facilities.
United Kingdom
Royal Navy vessel construction programs mandate integrated communications suites for fleet modernization. Strategic Command consolidates vendor relationships around end-to-end connectivity responsibility. Glasgow shipyards anchor naval satellite terminal integration with Type 26 frigate production lines.
Germany
Bundeswehr procurement offices prioritize NATO waveform interoperability for allied force integration. EU Radio Equipment Directive frequency constraints limit military spectrum access for tactical network testing. Bavaria concentrates RF engineering talent around Munich aerospace and defense electronics clusters.
Israel
Israel Defense Forces prioritize battlefield network resilience investments for contested electromagnetic environments. National encryption standards exceed NATO baseline requirements for sovereign communications security. Tel Aviv metropolitan area hosts specialized waveform software houses serving domestic and export markets.
Poland
NATO eastern flank buildup accelerates secure voice network procurement for territorial defense modernization. National spectrum regulators coordinate military frequency allocation with allied interoperability requirements. Warsaw defense procurement offices expand tactical data link acquisition budgets for regional security realignment.
Global Military Communications Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in military communications supply. Full-stack platform vendors capture premium positions through multi-domain integration capabilities while component suppliers compete on certification speed and waveform software specialization. Two strategic archetypes dominate: sovereign system-of-systems providers serving national defense ministries, and open-architecture radio specialists enabling threat adaptation through programmable platforms. Competitive moves concentrate on strategic partnerships for LEO constellation integration and portfolio diversification into quantum-resistant encryption subsystems.
Within the integrated systems tier, L3Harris Technologies and General Dynamics Corporation exemplify full-stack platform positioning. ASELSAN A.S. occupies a distinctive geography-anchored role serving Eastern European and Middle Eastern defense customers. These three entities represent the spectrum from U.S.-based multi-domain specialists to regional secure voice network providers, illustrating how vendor consolidation around end-to-end responsibility reshapes competitive access in Five Eyes and NATO procurement channels.
| Leading Market Players |
|---|
| BAE Systems |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| ASELSAN A.S. |
| Thales Group |
| RTX Corporation |
| General Dynamics Corporation |
| Elbit Systems |
| Northrop Grumman Corporation |
| Others |
Supply & Pricing Matrix
Orbital infrastructure scale economies concentrate pricing power among sovereign payload operators and integrated shipboard system vendors, compressing margins for component suppliers while elevating floor prices for NSA-certified encryption modules. Gallium Nitride substrate utilization rates at East Asian foundries directly propagate into RF component cost structures, linking procurement timelines to semiconductor capacity cycles.
Pricing Analysis
Transatlantic price spreads of 15-25 percent separate U.S. NSA-certified subsystem vendors from Eastern European secure voice network suppliers. Project-based contracting dominates, with price differentiation driven by Commercial Solutions for Classified certification tier and volume scale of tactical radio fleet orders. Cost compression in software-defined radio tiers is intensifying because programmable waveform development amortizes across multiple hardware platforms. Paramilitary units and border security forces exhibit highest price sensitivity, while intelligence agencies accept premium positioning for low-probability-of-intercept capabilities.
Supply Chain Analysis
Taiwan Strait transit risk underwrites Gallium Nitride wafer supply security for advanced RF component manufacturing. Production concentrates in the United States, Israel, and Turkey, drawing from specialized semiconductor substrates, quantum-resistant cryptographic IP, and hardened electromagnetic shielding materials. Single-source vulnerability in East Asian foundry capacity creates procurement contingency planning requirements. Distribution runs through defense ministry prime contractor relationships with tiered subsystem vendor qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cyclicality is recovering through NATO eastern flank modernization budgets and quantum-resistant cryptography migration mandates. Joint All-Domain Operations doctrine sustains multi-year program visibility.
For Market Incumbents: Secure NSA recertification pipeline priority for encryption modules before legacy system obsolescence accelerates. Deepen backward integration into Gallium Nitride substrate supply through long-term offtake agreements with East Asian foundries. Channel control over software-defined radio waveform libraries defends against open-architecture commoditization. For New Entrants and Emerging Players: Waveform software specialization gaps in existing vendor portfolios offer entry points without full-stack platform investment requirements. Polish territorial defense modernization represents the most penetrable geography, with tactical data link procurement expanding fastest. Pursue NATO standardization agreement pre-certification as the primary go-to-market angle. For Investors and Strategic Acquirers: Quantum-resistant cryptography subsystem specialists with existing NSA approval cycles represent the priority acquisition archetype. Long-term viability rests on sovereign satellite constellation buildout participation and software-defined radio platform consolidation. Watch Joint All-Domain Operations procurement timeline acceleration as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| NSA Certification Acceleration | Compresses 18-36 month approval cycles for encryption module suppliers competing for tactical network contracts. |
| LEO Constellation Integration Partnership | Links military terminals to commercial low-Earth-orbit networks without proprietary orbital infrastructure investment. |
| Software-Defined Radio Platform Launch | Enables waveform reprogramming without hardware replacement, displacing fixed-function legacy sets in U.S. Army procurement. |
| Quantum-Resistant Cryptography R&D Expansion | Addresses NATO defense ministry migration timelines forcing accelerated supplier recertification cycles. |
| Polish Defense Market Entry | Captures NATO eastern flank buildup demand for secure voice networks and tactical data links. |
Research Methodology
Operator-level perspectives from program managers at defense ministries, procurement officers at prime contractors, RF engineering directors, and satellite ground station operators anchored the qualitative base. Primary interview insights combined with secondary validation from NATO standardization agreement documentation, NSA Commercial Solutions for Classified certification records, FCC spectrum allocation proceedings, and EU Radio Equipment Directive regulatory filings. Bottom-up segment sizing and top-down macro constraint triangulation cross-checked volume estimates.
Sensitivity analysis tested forecast responsiveness to Gallium Nitride substrate price volatility, NSA certification timeline compression, and Joint All-Domain Operations procurement acceleration. Segmentation dimensions modeled across communication type, technology tier, application domain, and end-user category, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from installed base replacement cycles and modernization program visibility across the projection horizon. Industry-specific inputs included sovereign satellite constellation deployment schedules and software-defined radio fielding timelines.
Underlying assumptions cover sustained NATO defense spending commitments, stable East Asian semiconductor foundry capacity, and incremental quantum-resistant cryptography standard adoption, with deviation risk concentrated in geopolitical supply chain disruptions and regulatory timeline extensions. Practitioners should keep alternative scenarios live as NATO procurement priority shifts and commercial LEO constellation reliability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Inertial Navigation System Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market