
 Radar Transmitter Market | 2026-2036
Radar Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Radar Transmitter Market Outlook
Military-grade transmitter reliability is collapsing the gap between commercial and defense specifications, forcing suppliers to recalibrate quality systems across both segments. Lockheed Martin leverages its vertically integrated GaN foundry investments to control critical semiconductor supply chains for active electronically scanned arrays. Raytheon Technologies sustains dominance in high-power vacuum tube legacy systems while simultaneously building solid-state replacement portfolios. Thales Group competes through European defense consortium access, anchoring its transmitter business to Franco-German combat air system programs.
A radar transmitter is a radio frequency subsystem that generates and amplifies electromagnetic pulses or continuous wave signals at specified power levels, frequencies, and pulse repetition rates for subsequent radiation through antenna arrays. These systems typically operate across L-band through W-band frequencies with output power ranging from milliwatts for automotive sensors to megawatts for long-range surveillance platforms, serving target detection, tracking, and imaging functions across military, civil aviation, and weather monitoring applications. Pulse transmitter architectures retain the largest installed base in long-range defense applications where peak power requirements exceed solid-state capabilities, while GaN-based solid-state technology captures the fastest expansion in compact aerospace and maritime platforms where thermal efficiency and reliability outweigh peak power metrics. Vacuum tube technology occupies a shrinking but defended niche in ground-based early warning systems where infrastructure replacement cycles extend across decades.
The United States Department of Defense mandates MIL-STD-810 environmental testing and ITAR export controls that constrain supplier eligibility and shape procurement pools for radar transmitter contracts. European defense agencies enforce CE marking under the EU Radio Equipment Directive alongside national security clearances that fragment market access across member states. The Federal Communications Commission regulates civilian radar spectrum allocation in the United States, directly constraining transmitter frequency bands for automotive and weather applications. Stakeholders must monitor gallium nitride substrate supply concentration and defense budget authorization trajectories as decisive variables for capacity planning and technology roadmapping.
Market Dynamics
Gallium nitride semiconductor technology is compressing transmitter form factors while simultaneously elevating thermal performance thresholds, forcing incumbent suppliers to rebuild manufacturing competencies around compound semiconductor fabrication.
Growth Catalysts
- ITAR Procurement Pools:United States Department of Defense export controls restrict eligible suppliers, concentrating contract awards among pre-qualified domestic manufacturers with cleared facilities.
- Electronic Warfare Modernization:NATO member states are accelerating radar refresh cycles across fighter aircraft and naval platforms, prioritizing active electronically scanned array retrofits.
- GaN Substrate Scaling:Defense-funded foundry investments in wide-bandgap semiconductor capacity are resolving historical bottlenecks in high-electron-mobility transistor supply.
Market Restraints
- Substrate Supply Concentration:Gallium nitride wafer production clusters among Japanese and United States specialty material suppliers, exposing procurement to single-source vulnerability.
- Vacuum Tube Skill Attrition:Traveling wave tube and crossed-field amplifier engineering expertise is retiring without replacement pipeline, constraining legacy system sustainment.
- CE Marking Fragmentation:European Union Radio Equipment Directive implementation varies across member state notified bodies, delaying transmitter certification timelines for cross-border defense contracts.
Strategic Opportunities
- Maritime Compact Arrays:Naval frigate and destroyer modernization programs in Germany and the United Kingdom are specifying solid-state transmitters for rotating and fixed-face radar configurations.
- Weather Radar Replacement:National meteorological agencies across the United States and Europe are retiring magnetron-based systems with GaN-powered dual-polarization upgrades.
- Automotive 4D Imaging:Frequency-modulated continuous-wave transmitter architectures are penetrating commercial vehicle advanced driver-assistance systems at 77 GHz and 79 GHz bands.
Industry Challenges
- Compound Semiconductor Talent Gap:RF device physics and epitaxial growth specialists command premium compensation, constraining foundry expansion timelines.
- Legacy Interface Integration:Solid-state transmitter retrofits must emulate vacuum tube impedance characteristics to avoid wholesale radar receiver redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radar Transmitter Market |
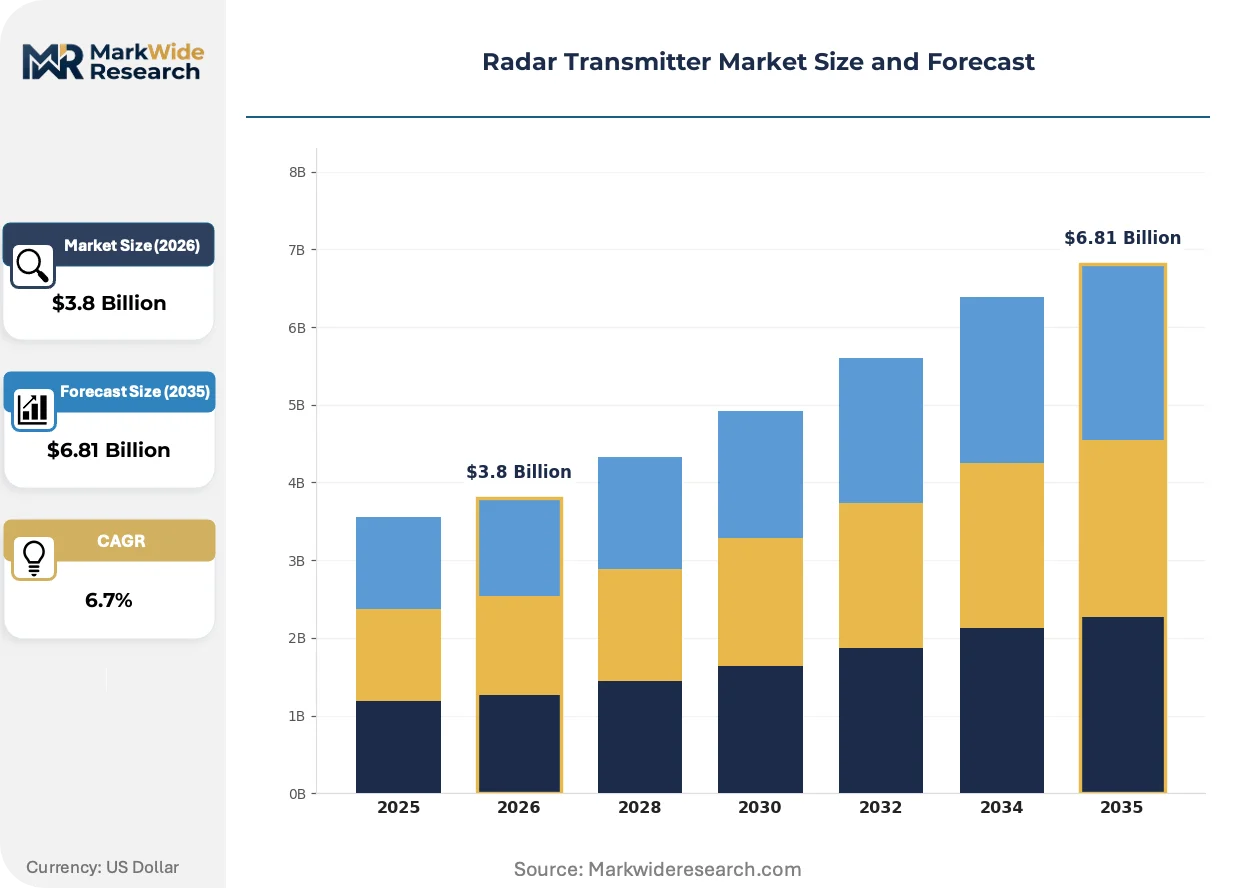
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Continuous Wave, Pulse, Frequency Modulated, Doppler Application: Aerospace, Maritime, Automotive, Defense Technology: Solid-State, Vacuum Tube, GaN, GaAs End User: Government, Commercial, Industrial, Academic |
| Companies Covered | Emerson Electric Co., Lockheed Martin Corporation, BAE Systems, Rheinmetall AG, General Dynamics Corporation, Saab AB, Raytheon Technologies, Thales Group, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radar Transmitter Market Strategic Shifts
Transmitter architecture is bifurcating between legacy high-power vacuum systems and solid-state alternatives, with thermal management and spectral efficiency becoming decisive design variables across both paths.
GaN-on-SiC monolithic microwave integrated circuits are replacing discrete transistor assemblies in airborne fire control radars. Fighter aircraft prime contractors in the United States and Europe are specifying these devices for active electronically scanned array tile integration. The technology is miniaturizing transmit-receive module footprints while sustaining peak power density previously achievable only through tube-based amplification.
The European Union Radio Equipment Directive mandates CE marking for all radar equipment operating in civilian spectrum allocations. This framework imposes electromagnetic compatibility and spectrum efficiency testing that legacy magnetron transmitters cannot satisfy without redesign. Weather radar operators in Germany, France, and the United Kingdom are responding by accelerating magnetron-to-solid-state replacement schedules.
Defense procurement agencies are consolidating transmitter specifications into platform-level performance contracts rather than discrete subsystem purchases. Prime contractors now assume integration risk for active electronically scanned array performance, compressing supplier tiers and eliminating historical component-level competition. This concentration is most visible in United States Department of Defense programs, where Lockheed Martin and Northrop Grumman have internalized GaN foundry relationships to secure transmitter supply.
Radar Transmitter Market Segmentation
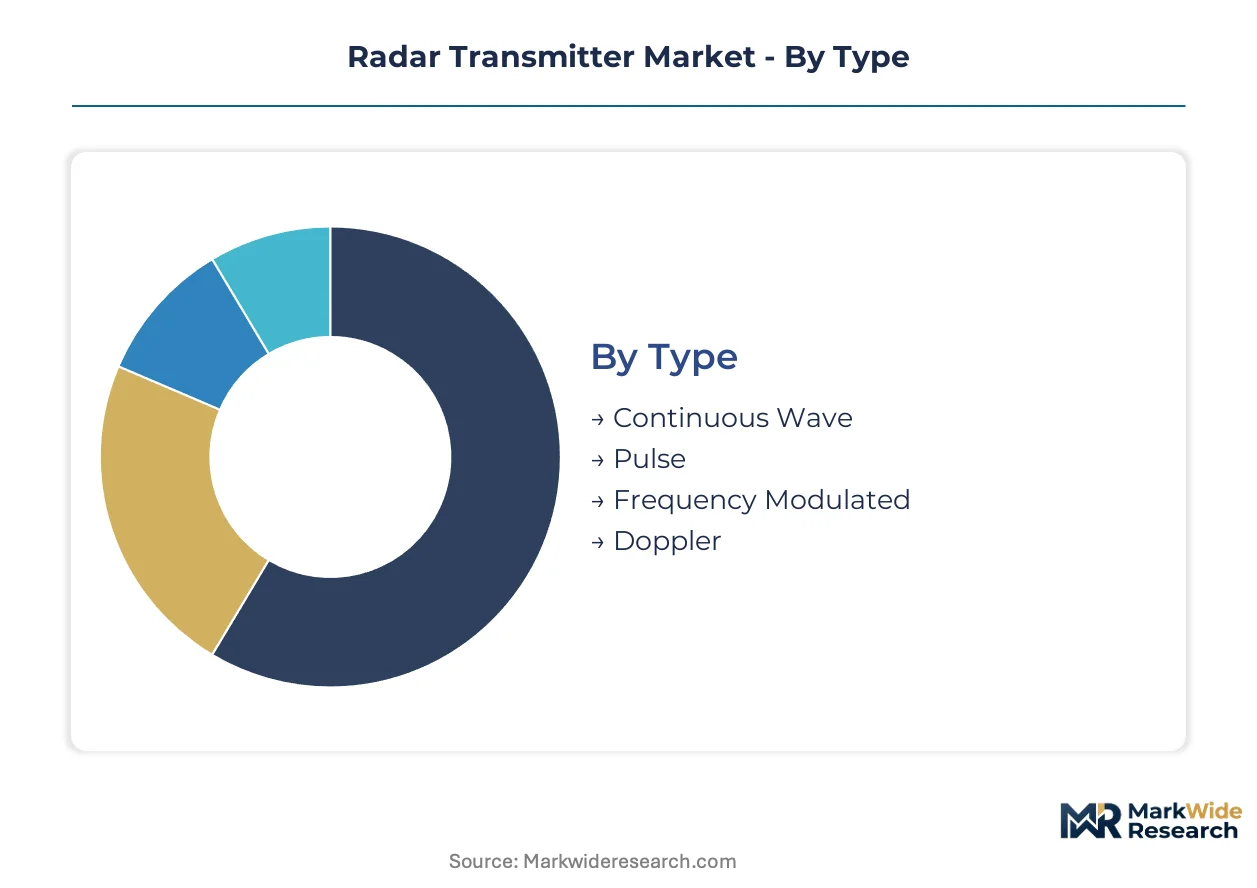
Radar transmitter architectures diverge sharply across frequency bands, power classes, and thermal envelopes. Procurement specifications from defense agencies and civilian regulators fragment demand into distinct technical tiers with incompatible qualification pathways.
Type:
FCC Part 90 rules in the United States and CE marking under the EU Radio Equipment Directive impose divergent waveform certification requirements that shape transmitter architecture selection.
- Pulse:Generates high-peak-power bursts with precise timing control for long-range target detection. NATO early warning systems and naval fire control platforms in the United Kingdom and Germany specify these transmitters where peak power exceeds solid-state limits. Vacuum tube sustainment challenges and GaN replacement timelines dominate procurement planning.
- Continuous Wave:Emits unmodulated carrier signals for Doppler velocity measurement and frequency-modulated continuous-wave ranging. Automotive advanced driver-assistance systems at 77 GHz and maritime navigation radars drive volume demand, with FCC spectrum allocation directly constraining frequency band availability.
- Frequency Modulated:Sweeps carrier frequency across pulse duration to encode range information through beat frequency detection. Weather radar modernization programs across Germany and France deploy these architectures for dual-polarization precipitation measurement.
- Doppler:Processes frequency shift from moving targets to isolate velocity data from stationary clutter. Police speed enforcement and airborne weather avoidance systems represent primary end-uses.
Pulse transmitters handle the majority of defense procurement value; continuous wave architectures are gaining share fastest in automotive volume applications.
Application:
Customer procurement authority concentrates in platform prime contractors for defense and fleet operators for commercial aviation, fragmenting sales channel structures.
- Defense:Active electronically scanned array retrofits for fighter aircraft and ground-based air defense command the highest unit values. United States Department of Defense ITAR controls restrict supplier pools to cleared domestic manufacturers, compressing competitive dynamics.
- Automotive:77 GHz and 79 GHz frequency-modulated continuous-wave modules for adaptive cruise control and collision avoidance. German automotive Tier 1 suppliers specify GaN-on-SiC devices for thermal performance at compact form factors.
- Aerospace:Civil aviation weather radar and terrain mapping systems operate under FAA technical standard orders for equipment authorization. Dual-polarization upgrades for airline fleets drive replacement cycles.
- Maritime:Solid-state X-band and S-band transmitters for naval frigate rotating arrays and commercial vessel collision avoidance. United Kingdom Royal Navy Type 26 programs specify GaN-based fixed-face configurations.
Defense applications concentrate revenue; automotive deployments are expanding most quickly on unit volume.
Technology:
Compound semiconductor foundry capacity and vacuum tube engineering expertise distribute across incompatible supply bases with diverging investment profiles.
- GaN:Wide-bandgap high-electron-mobility transistors on silicon carbide substrates deliver power density and thermal efficiency for active electronically scanned array tiles. United States defense-funded foundry investments in North Carolina and Arizona resolve historical substrate bottlenecks.
- Solid-State:Silicon LDMOS and GaAs pHEMT devices for medium-power applications where cost sensitivity outweighs extreme performance. Weather radar magnetron replacements and commercial marine systems dominate demand.
- Vacuum Tube:Traveling wave tubes and crossed-field amplifiers sustain peak power levels beyond solid-state reach in ground-based early warning systems. Engineering workforce attrition constrains legacy system sustainment across United States and European maintenance depots.
- GaAs:Legacy monolithic microwave integrated circuits for phased array beamforming networks. Yielding share to GaN in new designs but retaining installed base support requirements.
GaN technology commands the steepest expansion trajectory; vacuum tube architectures retain entrenched positions in highest-power defense installations.
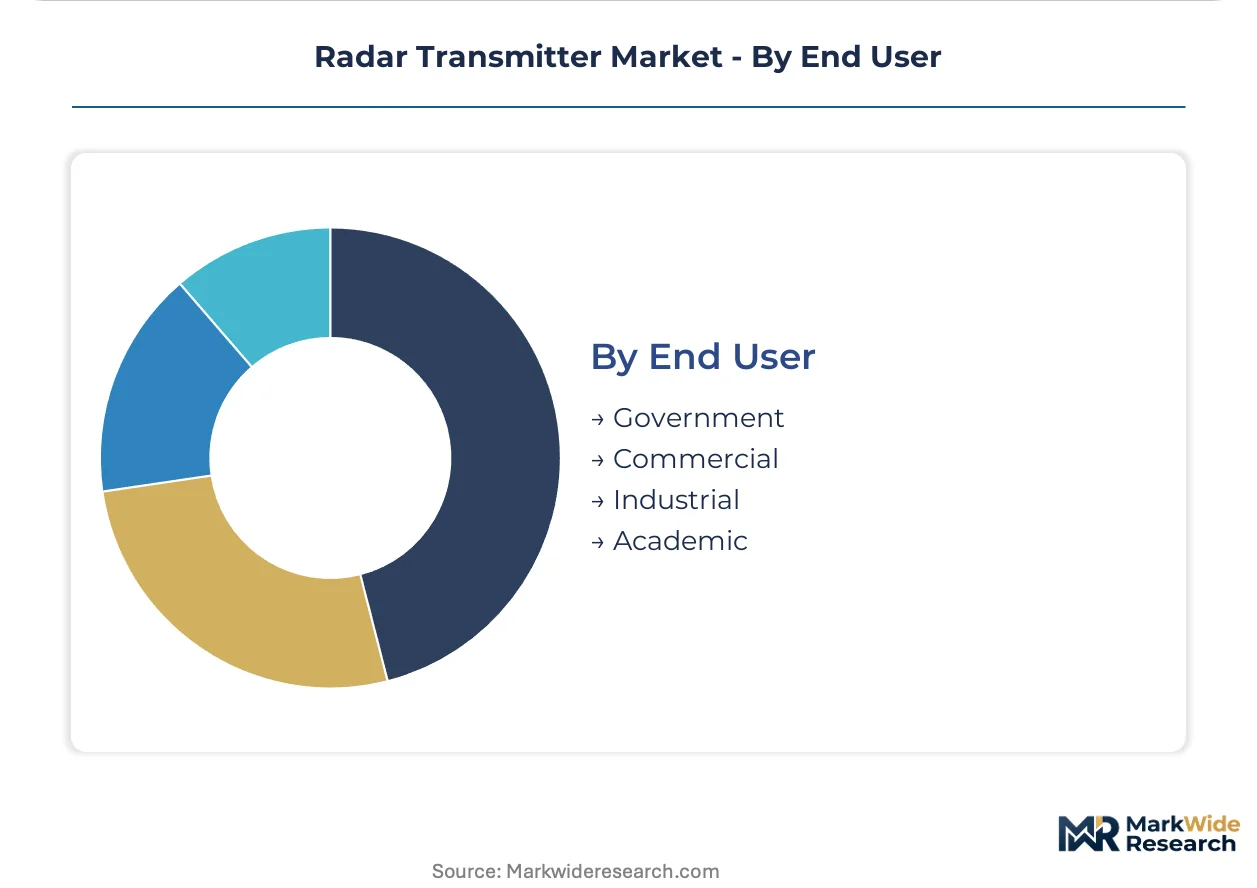
End User:
Budget authorization cycles and security clearance requirements segment addressable markets into procurement pools with distinct contracting protocols.
- Government:National defense agencies and meteorological services with multi-year capital appropriations. United States Department of Defense platform-level performance contracts internalize transmitter procurement within prime contractor scope.
- Commercial:Airlines, shipping operators, and automotive manufacturers with total cost of ownership procurement criteria. FAA and EASA airworthiness certification frames equipment selection.
- Industrial:Mining, agriculture, and infrastructure operators deploying ground-penetrating radar and proximity sensing. Price sensitivity drives LDMOS and magnetron architectures.
- Academic:Research institutions and atmospheric science programs with specialized waveform requirements. National Science Foundation and European Research Council grants fund experimental array development.
Government end users direct the largest contract values; commercial procurement is climbing fastest as automotive volumes scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains substantial net export capacity in defense-grade radar transmitters, while Germany and the United Kingdom balance import reliance for GaN substrates against domestic system integration strengths. Japan and South Korea anchor the Asia-Pacific supply chain for wide-bandgap semiconductor materials.
United States
Department of Defense platform-level performance contracts concentrate procurement authority within prime contractor ecosystems. ITAR export controls restrict eligible suppliers to cleared domestic manufacturers with secured facilities. Defense-funded foundry investments in North Carolina and Arizona resolve historical GaN substrate bottlenecks for active electronically scanned array production.
Germany
Franco-German combat air system programs anchor Thales Group and Rheinmetall transmitter specifications to European consortium requirements. CE marking under the EU Radio Equipment Directive imposes electromagnetic compatibility testing that accelerates magnetron-to-solid-state replacement in weather radar installations. Bavaria-based defense electronics clusters coordinate GaN-on-SiC device qualification for naval frigate radar modernization.
United Kingdom
Royal Navy Type 26 frigate programs specify GaN-based fixed-face radar configurations, driving solid-state transmitter demand. National security clearances fragment market access across notified bodies, delaying cross-border defense contract certification timelines. Scottish and southern England defense electronics corridors sustain traveling wave tube engineering expertise for legacy system sustainment.
Japan
Domestic specialty material suppliers concentrate gallium nitride wafer production, exposing procurement to single-source vulnerability despite METI industrial policy support. National meteorological agency radar replacement schedules align with GaN-powered dual-polarization upgrades. Tokyo-Osaka industrial corridors maintain compound semiconductor fabrication competencies for phased array beamforming networks.
South Korea
Defense acquisition program administration budgets prioritize active electronically scanned array retrofits for indigenous fighter aircraft development. MFDS regulatory frameworks for electromagnetic equipment shape civilian radar spectrum allocation constraints. Seoul Capital Area foundry investments target high-electron-mobility transistor capacity expansion for maritime and aerospace applications.
Radar Transmitter Market Competitive Environment
Listed defense primes compete with private specialists across technology licensing and foundry access dimensions. The vendor base organizes around three tiers: vertically integrated platform primes controlling captive semiconductor supply, component specialists supplying transmit-receive modules under subcontract, and legacy vacuum tube sustainment depots. Two strategic archetypes dominate competitive positioning—GaN foundry owners securing backward integration advantages, and consortium-anchored European suppliers leveraging cross-border program access. M&A activity concentrates on compound semiconductor foundry acquisitions, while capacity expansion focuses on wide-bandgap epitaxial growth facilities.
Within the platform prime tier, Lockheed Martin Corporation and Raytheon Technologies exemplify divergent technology strategies—one leveraging in-house GaN foundry investments, the other sustaining vacuum tube legacy dominance while building solid-state replacement portfolios. Thales Group occupies a position representing European consortium-anchored competition, securing transmitter business through Franco-German combat air system program access. Northrop Grumman sits within the vertically integrated archetype alongside Lockheed Martin, internalizing semiconductor supply chains for active electronically scanned array performance contracts.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Lockheed Martin Corporation |
| BAE Systems |
| Rheinmetall AG |
| General Dynamics Corporation |
| Saab AB |
| Raytheon Technologies |
| Thales Group |
| Northrop Grumman |
| Others |
Value Chain & Pricing Dynamics
ITAR export controls and CE marking under the EU Radio Equipment Directive simultaneously gate supplier qualification and stratify price tiers, forcing defense contractors to absorb certification costs while civilian operators face electromagnetic compliance premiums that separate GaN-equipped transmitters from legacy magnetron alternatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across ITAR-cleared premium tiers, CE-marked standard tiers, and uncertified economy tiers for industrial applications. Price differentiation rests on certification level—FCC Part 90 authorization and MIL-STD-810 compliance—and volume scale for active electronically scanned array tile orders. Cost compression in solid-state architectures is intensifying because GaN foundry capacity expansion resolves substrate bottlenecks. Automotive Tier 1 suppliers exhibit highest price sensitivity; defense prime contractors with captive semiconductor supply show lowest.
Supply Chain Analysis
Japan and the United States anchor gallium nitride wafer production, while Taiwan and South Korea feed silicon carbide substrate fabrication for high-electron-mobility transistor foundries. Raw material dependencies center on high-purity gallium metal, silicon carbide boules, and specialized ceramic packaging substrates. Single-source vulnerability in Japanese specialty material suppliers exposes procurement to geopolitical disruption. Distribution runs through defense prime contractor ecosystems for military applications and automotive Tier 1 integrators for commercial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radar transmitter market rewards mastery of compound semiconductor fabrication and vacuum tube sustainment engineering—capabilities that are simultaneously scarce and geographically concentrated. Organizations must secure these assets before competitive windows narrow.
For Market Incumbents: Consolidate GaN foundry relationships through backward integration into epitaxial growth facilities or exclusive capacity agreements with Arizona and North Carolina defense-funded plants. Acquire traveling wave tube engineering talent from retiring workforces in Scottish and southern England defense corridors to sustain legacy system service contracts. Lockheed Martin's vertically integrated model demonstrates how captive semiconductor supply secures platform-level performance contract awards.
For New Entrants and Emerging Players: Differentiate on maritime compact array specifications for United Kingdom Royal Navy Type 26 and German frigate modernization programs, where solid-state transmitter demand outruns incumbent capacity. Target weather radar replacement schedules across German and French national meteorological agencies, where CE marking mandates accelerate magnetron-to-GaN conversion. Pursue technology licensing from Japanese specialty material suppliers to bypass substrate supply bottlenecks.
For Investors and Strategic Acquirers: EU Radio Equipment Directive enforcement reshapes the acquisition landscape by devaluing legacy magnetron transmitter portfolios while elevating GaN-on-SiC device specialists with certified production lines. Long-term viability favors compound semiconductor foundries with defense security clearances and automotive thermal qualification. Monitor gallium nitride substrate spot pricing and United States Department of Defense budget authorization trajectories as inflection indicators for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Acquisition | Captive supply of high-electron-mobility transistors secures active electronically scanned array contract eligibility under ITAR. |
| Traveling Wave Tube Sustainment Partnership | Engineering workforce retention agreements preserve legacy ground-based early warning system service revenue streams. |
| CE Marking Fast-Track Certification | Accelerated electromagnetic compliance testing unlocks German and French weather radar replacement procurement pools. |
| Automotive Tier 1 Integration Agreement | Direct supply relationships with German vehicle manufacturers bypass component distributor margins at 77 GHz and 79 GHz bands. |
| Defense Prime Contractor Subcontract | Transmit-receive module supply agreements with Lockheed Martin or Northrop Grumman provide volume stability through platform-level performance contracts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers at NATO member state agencies, GaN foundry engineering directors in North Carolina and Arizona, automotive Tier 1 radar module procurement leads in Germany, and traveling wave tube sustainment depot managers in the United Kingdom. Secondary validation drew from United States Department of Defense budget justification documents, FCC spectrum allocation dockets, EU Radio Equipment Directive notified body certification records, and SEC 10-K filings from listed defense primes. Bottom-up transmitter unit demand estimates triangulated against top-down defense electronics market sizing.
Across the analysis window, the forecast framework modeled volume and value outputs through segmented projections across pulse, continuous wave, frequency modulated, and Doppler transmitter architectures; defense, automotive, aerospace, and maritime applications; GaN, solid-state, vacuum tube, and GaAs technology tiers; and government, commercial, industrial, and academic end users. CAGRs were derived from defense budget authorization trajectories, automotive advanced driver-assistance system penetration curves, and meteorological agency capital replacement schedules.
The analysis sits within stated boundaries; outcomes outside sustained gallium nitride substrate supply expansion or shifted NATO electronic warfare modernization priorities would require recalibration. Forecasts reflect assumptions regarding ITAR control continuity, CE marking enforcement consistency, and compound semiconductor talent pipeline development. Recalibration cycles align with material shifts in defense appropriations, wide-bandgap foundry capacity announcements, and regulatory directive implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market