
 Space Situational Awareness (SSA) Systems Market | 2026-2036
Space Situational Awareness (SSA) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Space Situational Awareness (SSA) Systems Market Analytics
Subscription-based data fusion services is repositioning vendor economics toward recurring revenue models rather than one-time hardware sales. Lockheed Martin Corporation leverages its classified sensor networks to anchor high-margin government contracts. L3Harris Technologies, Inc. competes through dual-use optical-radar portfolios that span civil and defense buyers. LeoLabs specializes in radar-derived orbital analytics for commercial constellation operators.
Space Situational Awareness (SSA) Systems encompass ground-based radars, space-based optical payloads, and algorithmic platforms that detect, track, and characterize orbital objects with sub-meter positional accuracy for collision prediction and space traffic coordination. Machine Learning Solutions within the technology dimension are capturing disproportionate R&D investment as operators automate conjunction assessment workflows. Government Agencies within the end-user dimension sustain the largest procurement budgets, though Commercial Operators represent the fastest-expanding contract category as mega-constellation deployments multiply.
The U.S. Space Force, the Federal Communications Commission, and the European Space Agency's Space Safety Programme collectively shape SSA demand through orbital debris mitigation mandates, spectrum licensing conditions, and cross-border data-sharing protocols. These frameworks compel vendors to certify tracking accuracy, standardize conjunction data messages, and integrate multi-source sensor feeds. Stakeholders must weigh sovereign data residency requirements against the technical benefits of federated global sensor architectures.
Market Dynamics
Machine learning convergence with legacy sensor architectures is compressing conjunction assessment timelines from hours to minutes, forcing vendors to reengineer software stacks around real-time orbital analytics rather than batch-processed catalog updates.
Growth Catalysts
- Debris Mitigation Mandates:The U.S. Space Force's 18th Space Defense Squadron data-sharing protocols compel commercial operators to procure certified tracking services. Federal contracts now require standardized conjunction data messages.
- Launch Cadence Intensification:Mega-constellation deployments by commercial satellite operators multiply the addressable object population requiring surveillance. Each new launch injects hundreds of trackable elements into near-Earth orbits.
- Optical-Radar Sensor Fusion:Hybrid ground architectures combining electro-optical telescopes with phased-array radars improve all-weather coverage. This technology convergence reduces single-sensor dependency gaps.
Market Restraints
- Capital Intensity of Radar Infrastructure:High-power S-band and X-band phased arrays require specialized real estate and electromagnetic spectrum licenses. Site acquisition costs constrain new market entrants.
- Data Sovereignty Fragmentation:National security classifications restrict cross-border sensor data flows. The European Space Agency's Space Safety Programme maintains separate orbital catalogs from U.S. military sources.
- Sensor Network Concentration:Southern Hemisphere radar coverage remains sparse. Tracking gaps over the Pacific and Indian Oceans degrade conjunction prediction accuracy for high-inclination orbits.
Strategic Opportunities
- Commercial SSA-as-a-Service:Subscription-based orbital analytics platforms unlock recurring revenue from small satellite operators. These buyers lack capital for dedicated ground infrastructure.
- Cislunar Domain Extension:Artemis program traffic and lunar gateway architectures create demand for beyond-GEO tracking capabilities. Current catalogs terminate at geostationary altitude.
- EU Space Traffic Management Framework:The European Commission's proposed regulatory package mandates collision avoidance services for EU-flagged satellites. This creates compliance-driven procurement pools.
Industry Challenges
- Astrodynamics Talent Scarcity:Orbital mechanics expertise concentrates within government laboratories and legacy aerospace primes. Commercial vendors compete for limited personnel capable of maneuver optimization algorithms.
- Legacy System Integration Friction:New machine learning platforms must ingest decades of heterogeneous catalog formats. Data normalization consumes engineering resources before predictive models deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Situational Awareness (SSA) Systems Market |
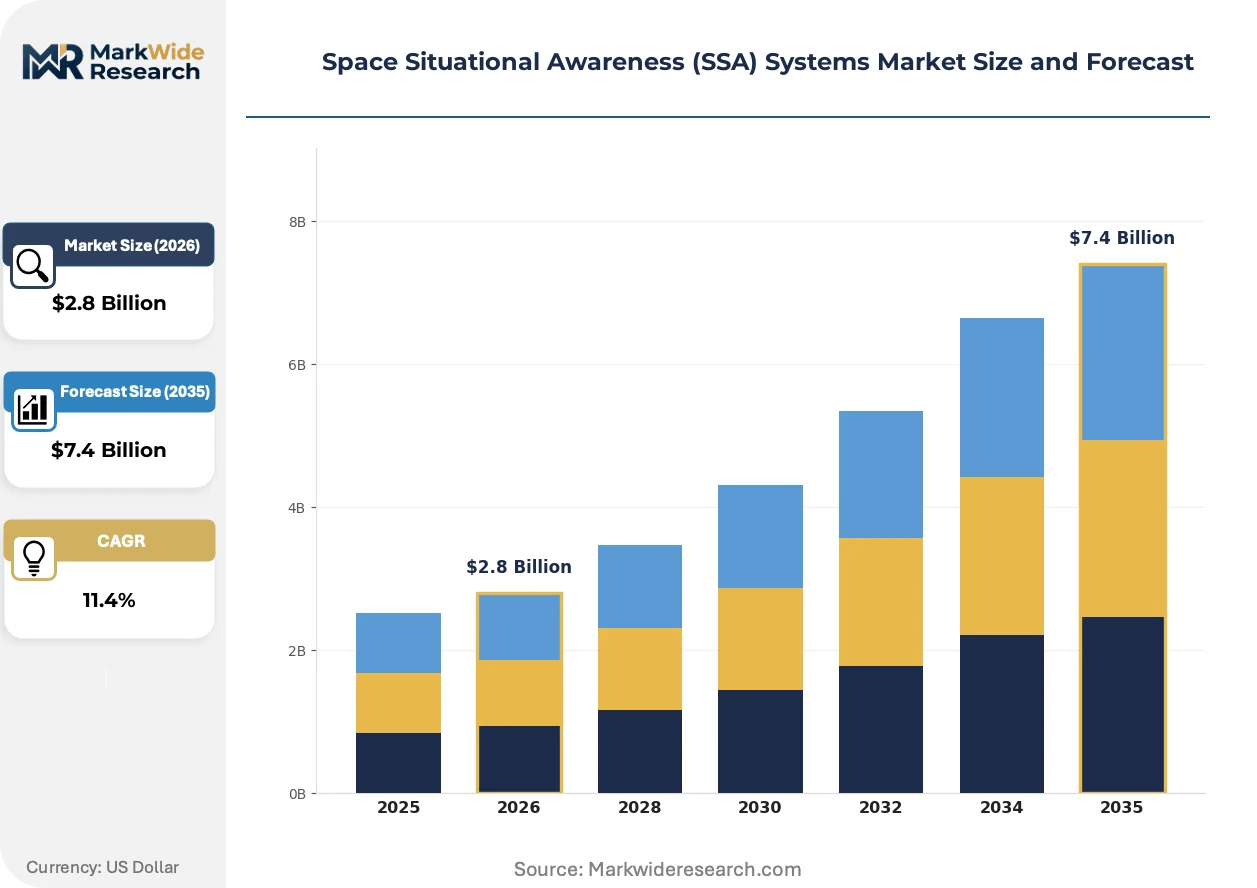
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-based Systems, Space-based Sensors, Data Processing Solutions, Integrated Platforms Technology: Radar Systems, Optical Sensors, Data Fusion Technologies, Machine Learning Solutions End User: Government Agencies, Military Organizations, Commercial Operators, Research Institutions Application: Collision Avoidance, Space Traffic Management, Satellite Monitoring, Debris Tracking |
| Companies Covered | Lockheed Martin Corporation, L3Harris Technologies, Inc., Kratos Defense & Security Solutions, Inc., Parsons Corporation, Peraton Corp., ExoAnalytic Solutions, LeoLabs, Analytical Graphics, Inc., NorthStar Earth & Space Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Situational Awareness (SSA) Systems Market Evolving Landscape
Artificial intelligence is penetrating every layer of SSA architecture, from sensor tasking automation to predictive collision modeling, while regulatory jurisdictions compete to establish authoritative space traffic management standards.
Neural network architectures trained on historical conjunction events are automating false-positive filtering in optical telescope data streams. Commercial constellation operators at SpaceX and Amazon's Kuiper Project now ingest machine-validated collision alerts directly into autonomous maneuver planning systems. This compression of human-in-the-loop review cycles is reducing operational staffing ratios per satellite by half.
The Federal Communications Commission's updated spectrum licensing conditions now require debris mitigation plans as a condition of market access. Satellite operators must demonstrate post-mission disposal reliability and tracking cooperation with the 18th Space Defense Squadron. This regulatory stringency disproportionately affects venture-backed launch ventures seeking rapid constellation deployment.
Consolidated procurement by mega-constellation anchor tenants is displacing fragmented buying from individual satellite owners. Amazon, SpaceX, and Telesat now negotiate enterprise SSA subscriptions covering thousands of spacecraft under unified service agreements. This buyer concentration is visible most acutely in the United States, where federal contracting vehicles and commercial mega-constellation headquarters cluster procurement decision-making.
Space Situational Awareness (SSA) Systems Market Segmentation
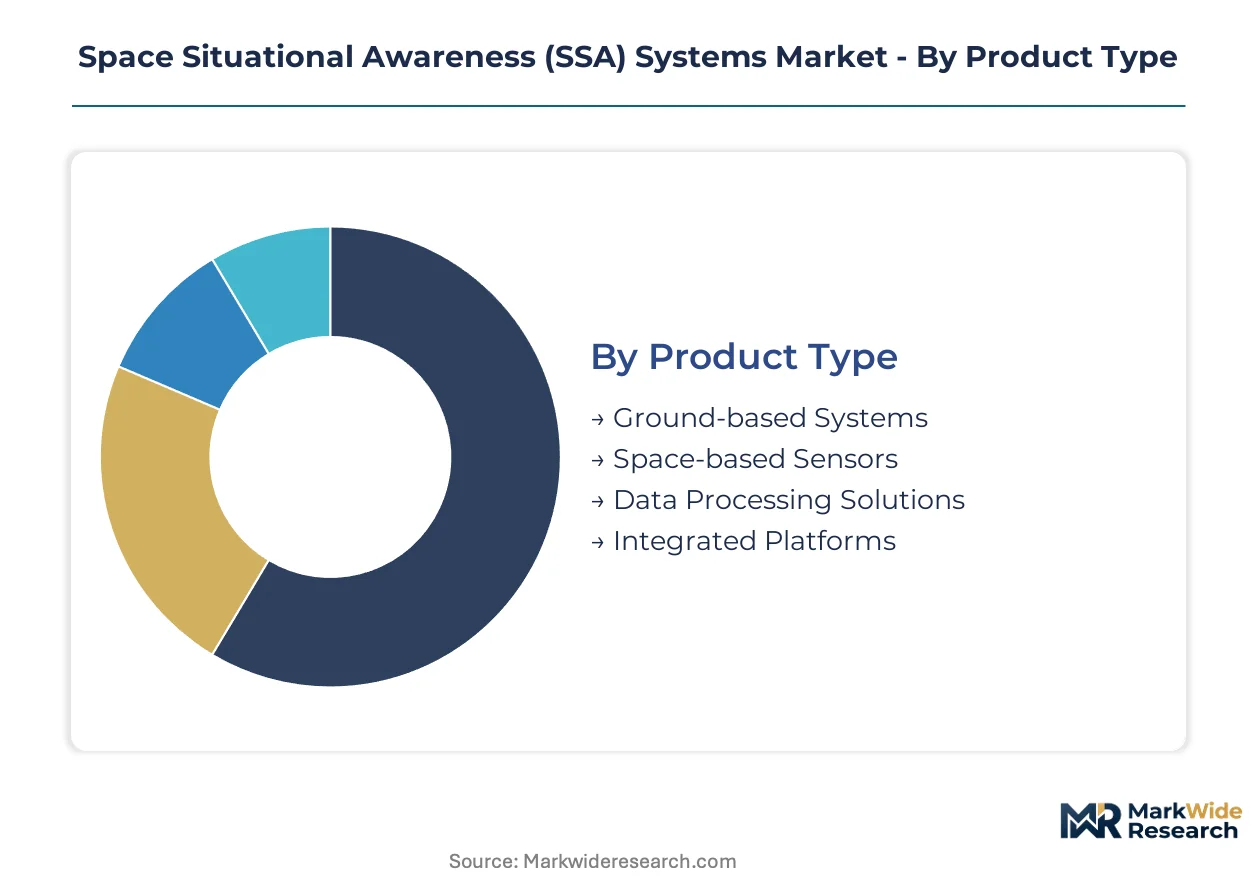
SSA procurement patterns diverge sharply across product architectures and buyer categories. Technology choices determine capital intensity and refresh cycles. End-user mandates shape interoperability requirements and data classification protocols.
Product Type:
Ground infrastructure suppliers dominate near-term contract awards through established radar networks and phased-array installations. Space-based alternatives command premium valuations but face longer development timelines.
- Ground-based Systems:Phased-array radars and electro-optical telescopes deliver all-weather tracking with sub-meter positional accuracy. The U.S. Space Force's 18th Space Defense Squadron anchors procurement through data-sharing mandates that require certified ground sensor feeds. Southern Hemisphere coverage gaps constrain conjunction prediction reliability for high-inclination orbits.
- Space-based Sensors:Orbital payloads eliminate atmospheric distortion and extend detection range to cislunar distances. Mega-constellation operators at Amazon and SpaceX drive demand for hosted SSA payloads that reduce ground segment dependency. Launch costs and thermal management complexity limit deployment scale.
- Data Processing Solutions:Cloud-native orbital analytics platforms normalize heterogeneous sensor feeds into standardized conjunction data messages.
- Integrated Platforms:End-to-end architectures combining sensors, processing, and distribution reduce buyer integration burden.
Today's leader: Ground-based Systems. Tomorrow's challenger: Space-based Sensors.
Technology:
Sensor modality selection determines weather resilience, detection range, and spectrum licensing requirements. Algorithmic layers are capturing disproportionate R&D investment as operators automate collision assessment workflows.
- Radar Systems:S-band and X-band phased arrays penetrate cloud cover and detect debris as small as two centimeters in low Earth orbit. Capital intensity and electromagnetic spectrum scarcity constrain new market entrants. Site acquisition costs in remote equatorial locations present particular barriers.
- Optical Sensors:Ground-based telescopes and space-based imagers achieve superior angular resolution for geostationary belt monitoring. The European Space Agency's Space Safety Programme procures optical networks for independent catalog maintenance separate from U.S. military sources. Daylight and weather limitations require hybrid architectures.
- Data Fusion Technologies:Multi-sensor correlation engines integrate radar tracks with optical observations to reduce single-source dependency.
- Machine Learning Solutions:Neural architectures trained on historical conjunction events automate false-positive filtering and compress assessment timelines from hours to minutes.
Radar Systems anchor current procurement volumes. Machine Learning Solutions are climbing the fastest as vendors reengineer software stacks around real-time analytics.
End User:
Budget scale and data classification requirements fragment procurement patterns across buyer categories. Government contracts sustain revenue visibility while commercial segments expand addressable market scope.
- Government Agencies:Civil space regulators and national space offices mandate tracking cooperation as a condition of spectrum licensing and launch authorization. The Federal Communications Commission's updated debris mitigation rules compel operator compliance with standardized conjunction data protocols. Procurement concentrates in the United States through federal contracting vehicles.
- Commercial Operators:Satellite constellation owners procure subscription-based SSA services rather than capitalizing dedicated infrastructure. SpaceX, Amazon, and Telesat negotiate enterprise agreements covering thousands of spacecraft under unified terms. This buyer concentration displaces fragmented procurement from individual satellite owners.
- Military Organizations:Classified mission requirements drive demand for sovereign sensor networks with restricted data residency.
- Research Institutions:Academic consortia access archival catalog data for orbital dynamics modeling and debris evolution studies.
Government Agencies dominate contract value. Commercial Operators are gaining share fastest as mega-constellation deployments multiply.
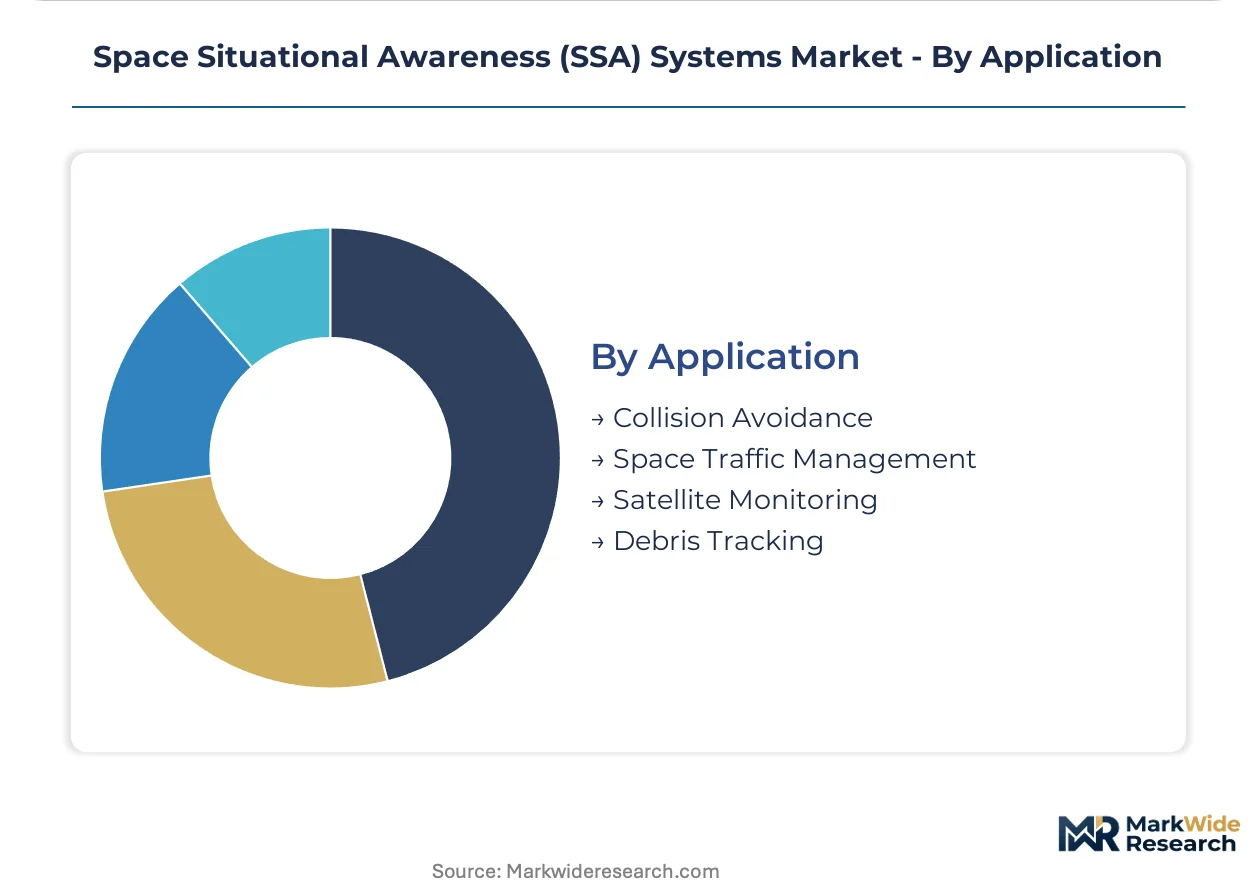
Application:
Functional use cases determine sensor tasking priorities and alert urgency classifications. Collision avoidance commands premium pricing through liability exposure and maneuver fuel costs.
- Collision Avoidance:Automated conjunction assessment and maneuver recommendation systems protect high-value assets from catastrophic impact. Commercial operators integrate machine-validated alerts directly into autonomous satellite control systems, reducing operational staffing ratios. False-positive filtering remains a critical performance differentiator.
- Space Traffic Management:Coordination protocols for launch sequencing, orbital slot allocation, and post-mission disposal require authoritative catalog maintenance. The European Commission's proposed regulatory framework mandates collision avoidance services for EU-flagged satellites, creating compliance-driven procurement pools.
- Satellite Monitoring:Health assessment and anomaly detection extend SSA utility beyond collision prediction to operational support.
- Debris Tracking:Fragmentation event characterization and catalog maintenance support long-term orbital environment sustainability.
Collision Avoidance captures premium pricing. Space Traffic Management shows steepest expansion trajectory as regulatory jurisdictions compete to establish authoritative standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping SSA procurement geography as vendors seek jurisdictions with streamlined spectrum licensing and classified-data handling protocols. Sovereign data-residency mandates fragment vendor footprints while federal contracting concentration anchors near-term revenue visibility. Production gravity follows defense procurement clusters and commercial launch infrastructure.
United States
The U.S. Space Force's 18th Space Defense Squadron compels commercial operators to procure certified tracking services through data-sharing mandates. FCC debris-mitigation rules now require post-mission disposal reliability demonstrations as a condition of spectrum licensing. Colorado Springs and Los Angeles aerospace corridors concentrate ground-segment engineering talent and classified sensor network operations.
Germany
German satellite operators face EU Space Traffic Management framework compliance requirements for collision-avoidance service procurement. The country's national space regulator enforces conjunction-data message standardization under ESA Space Safety Programme protocols. Munich and Bremen industrial clusters host optical sensor integrators serving both civil and dual-use mission profiles.
United Kingdom
UK Space Agency licensing conditions mandate tracking cooperation for orbital slot allocation and launch authorization. The national regulator requires debris-mitigation plan submission alongside spectrum applications. Harwell Space Cluster and Glasgow satellite manufacturing corridors drive demand for subscription-based orbital analytics from small-satellite constellation ventures.
France
French civil and military space programs sustain procurement of sovereign sensor networks with restricted data-residency requirements. CNES and Ministry of Armed Forces joint programs standardize conjunction assessment workflows for dual-use missions. Toulouse aerospace engineering concentration supports optical-radar hybrid architecture development for all-weather coverage.
Japan
JAXA and METI coordinate SSA capability development through public-private partnerships addressing mega-constellation traffic management. The country's space regulatory framework mandates debris-tracking cooperation for commercial launch licensing. Tsukuba and Tokyo metropolitan engineering bases concentrate machine-learning talent for automated conjunction filtering systems.
Space Situational Awareness (SSA) Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing premium pricing against component suppliers. The vendor base concentrates around defense primes with classified sensor access and emerging commercial analytics pure-plays. Three archetypes dominate: legacy aerospace conglomerates with sovereign network assets, dual-use technology specialists spanning civil-defense boundaries, and cloud-native orbital analytics startups. Competitive moves center on strategic partnerships for sensor-data federation and vertical integration into processing-layer software stacks.
Within the legacy prime tier, Lockheed Martin Corporation and L3Harris Technologies, Inc. exemplify divergent positioning strategies—one anchored in classified government network exclusivity, the other in dual-use optical-radar portfolio breadth. LeoLabs occupies a position representing the commercial-native archetype, leveraging radar-derived analytics for constellation-operator subscription contracts. These three entities collectively illustrate how vendor economics are repositioning from hardware sales toward recurring data-service revenue models.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| L3Harris Technologies, Inc. |
| Kratos Defense & Security Solutions, Inc. |
| Parsons Corporation |
| Peraton Corp. |
| ExoAnalytic Solutions |
| LeoLabs |
| Analytical Graphics, Inc. |
| NorthStar Earth & Space Inc. |
| Others |
Value Network & Pricing Analysis
Machine learning convergence with legacy sensor architectures is compressing development timelines and redistributing cost economics toward software-layer investments, concentrating procurement leverage among mega-constellation operators with enterprise-scale subscription negotiating power.
Pricing Analysis
Direct-to-OEM discount structures dominate high-volume government contracting, while tiered SaaS subscriptions serve commercial constellation operators lacking capital for dedicated infrastructure. Price differentiation rests on sensor certification tier against 18th Space Defense Squadron data-sharing protocols and real-time analytics latency guarantees. Pricing pressure stems from buyer consolidation as SpaceX, Amazon, and Telesat negotiate unified enterprise agreements covering thousands of spacecraft. Small satellite ventures exhibit highest price sensitivity, while classified military programs demonstrate lowest elasticity due to sovereign data-residency mandates.
Supply Chain Analysis
Freight costs for specialized radar components remain secondary to electromagnetic spectrum licensing and site acquisition expenditures that dominate landed cost structures. Manufacturing concentrates in the United States, Germany, and Japan, drawing from gallium nitride semiconductors, precision optical substrates, and specialized antenna arrays. Single-source vulnerability persists for high-power transmitter modules sourced from defense-qualified foundries. Distribution runs through prime contractor integration channels for government end-users and cloud-native platforms for commercial subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward premium-tier sensor fusion architectures as collision-avoidance liability exposure intensifies.
For Market Incumbents: Hedge against margin compression in hardware sales by deepening proprietary data-service revenue through machine-learning analytics layers. Lockheed Martin Corporation and L3Harris Technologies, Inc. should accelerate backward integration into cloud-native processing stacks before commercial pure-plays capture subscription economics. Sovereign network exclusivity remains defensible only with continuous certification investment against evolving 18th Space Defense Squadron protocols. For New Entrants and Emerging Players: Systems integrators represent the most accessible channel pathway for radar-derived analytics specialists seeking footprint in commercial mega-constellation procurement. White-space concentrates in Southern Hemisphere coverage gaps where sparse radar infrastructure degrades conjunction prediction accuracy for high-inclination orbits. Target subscription-based SSA-as-a-Service for venture-backed small satellite operators lacking capital for ground segment ownership. For Investors and Strategic Acquirers: Valuations sit cheapest among dual-use technology specialists with civil-defense portfolio breadth and established ESA Space Safety Programme relationships. Long-term viability favors vendors with demonstrated machine-learning deployment at operational scale rather than sensor hardware pure-plays. Watch FCC debris-mitigation rule enforcement intensity as inflection signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Data Federation Partnership | Multi-source correlation reduces single-sensor dependency gaps for all-weather coverage. |
| Machine Learning Platform Integration | Neural architectures automate false-positive filtering for autonomous maneuver systems. |
| Cislunar Tracking Capability Extension | Artemis program traffic creates demand beyond geostationary altitude catalog limits. |
| EU Regulatory Compliance Certification | European Commission mandates collision-avoidance services for EU-flagged satellites. |
| Commercial SSA-as-a-Service Launch | Subscription models unlock recurring revenue from small satellite operators. |
Research Methodology
Bottom-up government and commercial operator modeling reconciled against top-down sensor network capacity tracking forms the analytical core of this study. Primary interviews with satellite constellation operations directors, Space Force procurement officers, FCC regulatory affairs leads, and ESA program managers combined with secondary validation against federal contracting databases, spectrum licensing filings, and launch manifest records. Triangulation across these sources anchors market sizing with cross-referenced procurement visibility.
Input-output matrices map installed sensor capacity against addressable orbital object population growth across the projection horizon. Segmentation dimensions modeled include product architecture, sensor modality, end-user classification, and application function. CAGRs derive from trajectory analysis of federal budget appropriations, commercial launch cadence projections, and regulatory mandate implementation schedules. Forecast inputs incorporate mega-constellation deployment timelines and debris-mitigation compliance cost assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sovereign data-residency fragmentation and Southern Hemisphere infrastructure investment decisions. Forecasts reflect documented assumptions about regulatory enforcement intensity and machine-learning adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Flight Tracking System Market