
 Navigational Inertial Systems Market | 2026-2036
Navigational Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Navigational Inertial Systems Market Foresight
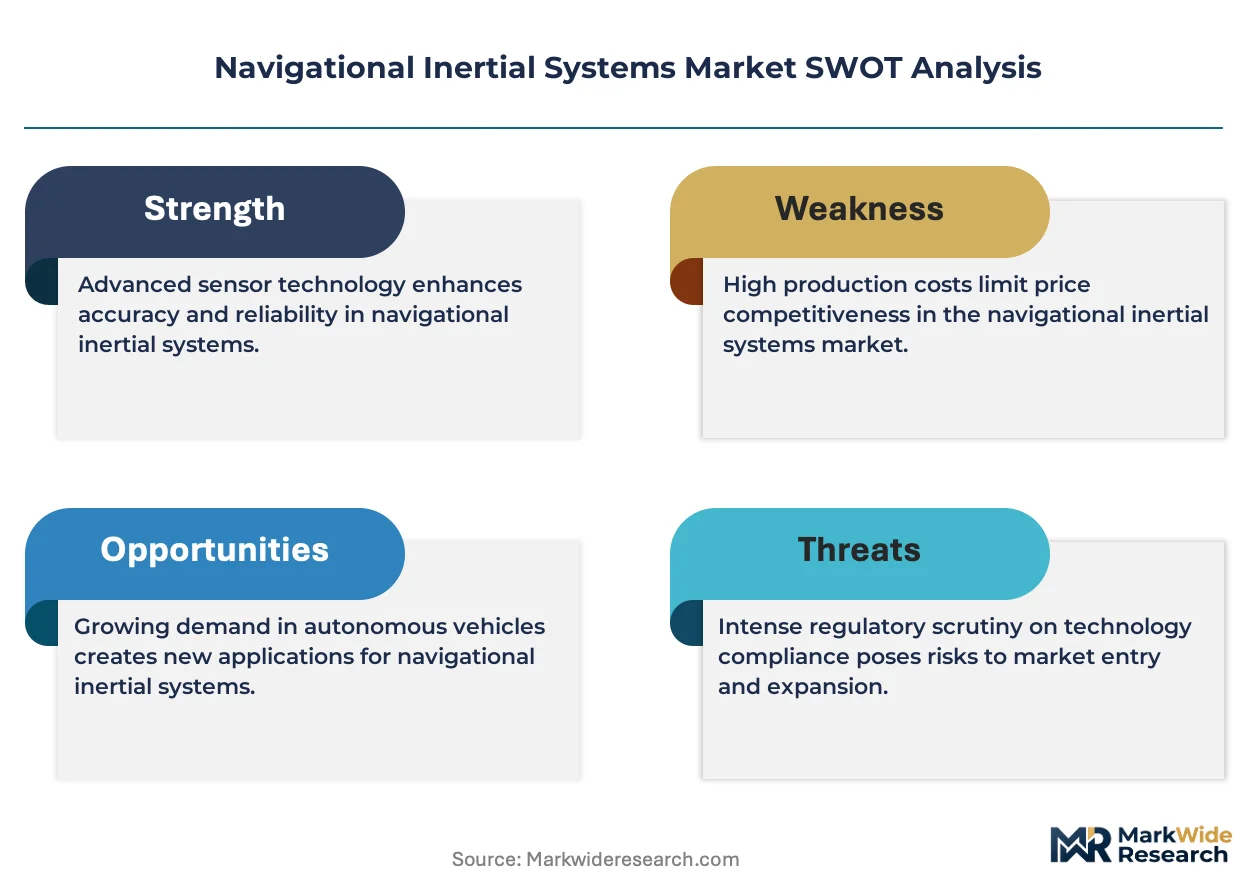
Specialized gyroscope engineering talent is reorganizing supply capacity across the Navigational Inertial Systems industry as defense primes and tier-one integrators compete for limited pools of physicists and MEMS fabrication specialists. Honeywell International Inc. leverages decades of ring laser gyroscope heritage to anchor high-end aerospace contracts. Safran Electronics & Defense sustains European sovereignty in naval inertial navigation through captive manufacturing in France. Northrop Grumman Corporation dominates U.S. strategic platforms with radiation-hardened systems for submarine and space applications.
Navigational inertial systems comprise self-contained dead-reckoning instruments that measure linear acceleration and rotational rate to compute position, velocity, and attitude without external references, typically achieving drift specifications below 0.01 degrees per hour in strategic-grade configurations for ballistic missile guidance. Fiber optic gyroscope technology leads commercial and tactical segments due to solid-state reliability and absence of moving parts, while MEMS accelerometers represent the fastest-expanding form factor as automotive autonomy and consumer drone applications drive unit volume. Stand-alone units retain premium pricing in defense and space, whereas integrated systems capture margin pools in commercial aviation through reduced size, weight, and power requirements.
FAA airworthiness standards for civil inertial reference units and EASA certification timelines for next-generation flight management systems shape product development cycles and market access thresholds for non-domestic suppliers. U.S. ITAR export controls and EU dual-use regulations further constrain technology transfer, compelling regional production footprints. Stakeholders must monitor evolving GPS-denied warfare doctrines and corresponding military specification shifts to align R&D allocation with procurement trajectories.
Market Dynamics
Fiber optic gyroscope maturation is compressing procurement cycles across defense and commercial aviation as solid-state reliability eliminates mechanical maintenance intervals. Talent scarcity in MEMS fabrication and precision optics is constraining supply elasticity faster than demand expansion.
Growth Catalysts
- EASA Flight Management Certification:Accelerated timelines for autonomous vehicle programs in Germany are pulling forward fiber optic gyroscope procurement. German automotive OEMs are pre-qualifying inertial units for SAE Level 4 architectures.
- GPS-Denied Warfare Doctrine:U.S. military specification shifts toward assured positioning, navigation, and timing are mandating redundant inertial cores on tactical platforms. Pentagon procurement is prioritizing radiation-hardened systems for contested electromagnetic environments.
- Automotive Lidar Integration:Solid-state MEMS accelerometers are achieving tactical-grade performance thresholds. Tier-one automotive suppliers are embedding compact inertial measurement units directly into sensor fusion stacks.
Market Restraints
- Precision Optics Input Volatility:Specialty fiber coil winding equipment and polarization-maintaining fiber supply concentrate among Japanese and German component houses. Price instability in rare-earth doping materials affects fiber optic gyroscope cost structures.
- ITAR Export Control Friction:U.S. State Department classification of ring laser gyroscope technology constrains cross-border technology transfer. Non-U.S. primes face extended licensing timelines for strategic-grade inertial navigation systems.
- MEMS Noise Floor Limitations:Consumer-grade MEMS accelerometers lack the bias stability for aviation-grade dead-reckoning. Tactical applications remain tethered to higher-cost fiber optic architectures despite unit volume pressures.
Strategic Opportunities
- Indian Defense Indigenization:India's Defense Research and Development Organisation is funding domestic inertial navigation capability under the Make in India framework. Local production mandates create openings for joint ventures with foreign technology holders.
- Quantum Inertial Sensing Convergence:Cold atom interferometry is approaching portable form factors. Convergence with conventional fiber optic gyroscopes promises order-of-magnitude drift improvements for submarine and space applications.
- Commercial Space Launch Expansion:Reusable launch vehicle programs in the United States and Europe are consuming strapdown inertial units at volumes exceeding traditional satellite procurement. New space operators are accepting commercial-grade specifications with faster refresh cycles.
Industry Challenges
- Specialized Physicist Recruitment:Ring laser gyroscope engineering requires expertise in quantum optics and precision machining that universities produce in limited cohorts. Defense primes compete for the same doctoral-level talent pools.
- EASA-FAA Certification Divergence:Civil aviation inertial reference units face non-harmonized airworthiness standards. Dual certification for global platform deployment extends development timelines and engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Navigational Inertial Systems Market |
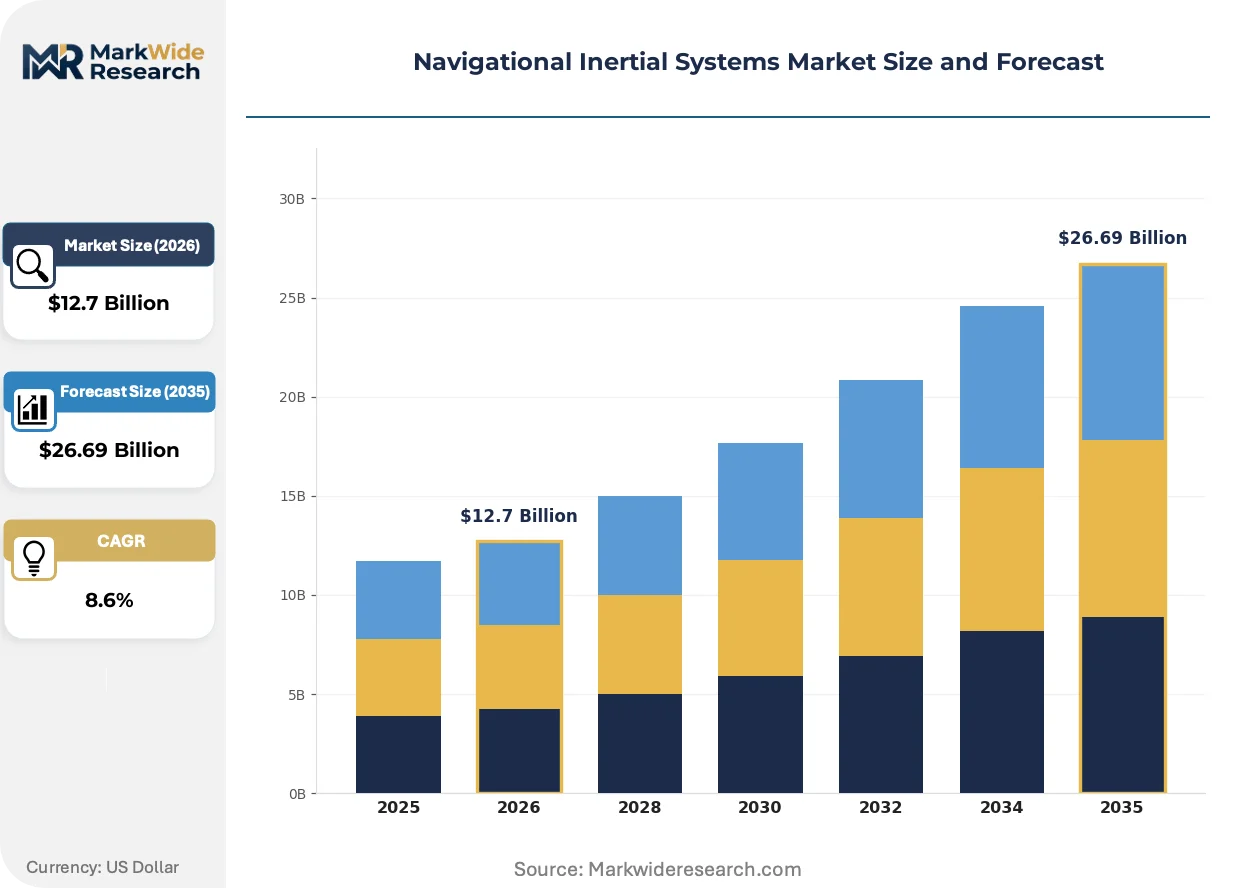
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ring Laser Gyroscopes, Fiber Optic Gyroscopes, Micro-Electro-Mechanical Systems, MEMS Accelerometers End User: Aerospace, Defense, Automotive, Maritime Application: Guidance Systems, Navigation Systems, Weapon Systems, Robotics Form Factor: Stand-Alone Units, Integrated Systems, Miniaturized Sensors, Modular Systems |
| Companies Covered | Honeywell International Inc., Northrop Grumman Corporation, Safran Electronics & Defense, Thales Group, Collins Aerospace, Raytheon Technologies, L3Harris Technologies Inc., BAE Systems, Inertial Labs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Navigational Inertial Systems Market Shifts & Advancements
Photonic integration and chip-scale atomic technologies are restructuring the performance-cost frontier across navigation tiers. Established mechanical architectures face substitution pressure from solid-state alternatives with fundamentally different reliability profiles.
Photonic integrated circuit gyroscopes are displacing discrete fiber optic coil assemblies in tactical and commercial aviation segments. Defense primes in the United States are qualifying indium phosphide-based optical chips for guided munitions where volume and shock tolerance outweigh strategic-grade precision. The displacement is compressing supplier margins on traditional coil-winding equipment while opening foundry partnerships with compound semiconductor houses.
EU F-Gas Regulation phase-down schedules are affecting cooling system design for cold atom inertial sensors. Research programs in France and Germany are pivoting toward closed-cycle cryocoolers with lower global warming potential refrigerants. Laboratory-grade atomic gyroscope developers face extended qualification timelines as they revalidate thermal management architectures under REACH-compliant material constraints.
Defense procurement offices are consolidating vendor lists around dual-use qualified suppliers with captive manufacturing. Prime contractors in the United States are awarding multi-year inertial navigation system contracts with embedded technical data rights clauses. The behavioral shift is most visible in submarine and strategic bomber programs where sole-source risk mitigation now outweighs unit cost minimization.
Navigational Inertial Systems Market Segmentation
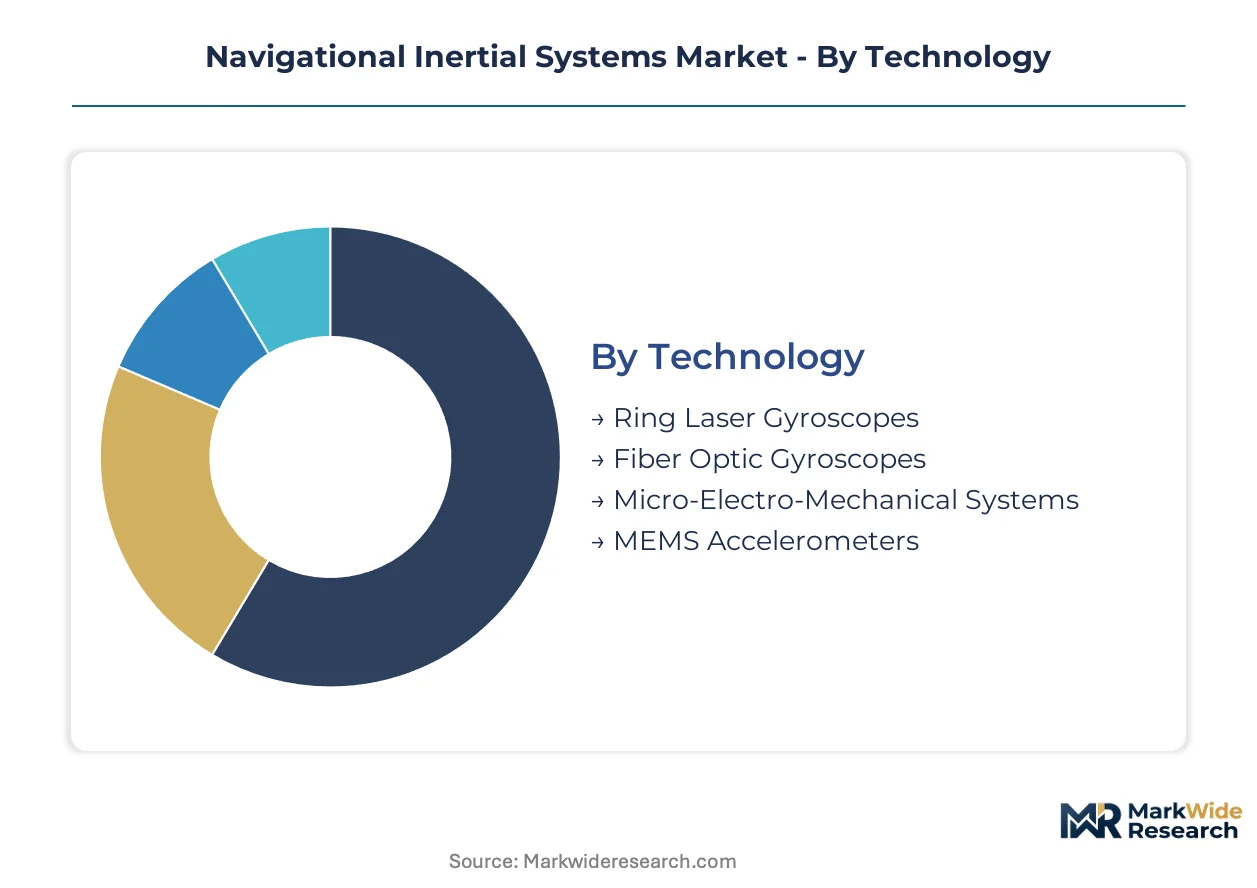
Technology choice dictates certification pathways and export control exposure across the Navigational Inertial Systems market. End-use concentration in defense procurement creates divergent margin structures between strategic-grade and commercial-grade tiers.
Technology:
Ring laser gyroscope production concentrates in U.S. and European defense primes under ITAR and EU dual-use regulations, while fiber optic and MEMS architectures serve export-oriented commercial segments with fewer licensing constraints.
- Ring Laser Gyroscopes:These instruments exploit the Sagnac effect in helium-neon gas cavities to detect rotation with drift specifications below 0.001 degrees per hour. Pentagon submarine and strategic bomber programs anchor domestic demand; ITAR classification blocks technology transfer to non-U.S. allies.
- Fiber Optic Gyroscopes:Solid-state designs using polarization-maintaining fiber coils eliminate mechanical wear and reduce maintenance intervals. German automotive OEMs are pre-qualifying these units for SAE Level 4 autonomous architectures under accelerated EASA timelines.
- Micro-Electro-Mechanical Systems:Silicon-fabricated inertial sensors achieve tactical-grade performance at consumer electronics cost structures.
- MEMS Accelerometers:Surface-micromachined devices measure linear acceleration for automotive stability control and consumer drone stabilization.
Ring laser gyroscopes hold the largest share; momentum sits with fiber optic architectures.
End User:
Defense procurement operates on multi-year sole-source contracts with embedded technical data rights, while automotive and maritime segments demand commercial off-the-shelf qualification cycles.
- Aerospace:Civil aviation inertial reference units must achieve FAA airworthiness certification and EASA CS-25 compliance. Boeing and Airbus platform specifications favor integrated systems with reduced size, weight, and power footprints.
- Defense:Radiation-hardened inertial navigation systems support GPS-denied warfare doctrines across U.S. submarine, bomber, and tactical missile programs. Sole-source risk mitigation now outweighs unit cost minimization in Pentagon procurement.
- Automotive:Tier-one suppliers embed compact inertial measurement units into sensor fusion stacks for advanced driver assistance systems.
- Maritime:Naval surface vessels and submarines require strapdown inertial navigation with ring laser or fiber optic cores.
Defense holds the largest share; automotive is climbing the fastest.
Application:
Guidance and navigation applications demand strategic-grade precision with extended calibration intervals, while weapon systems and robotics accept tactical-grade specifications with faster refresh cycles.
- Guidance Systems:Ballistic missile and precision munition applications require drift specifications below 0.01 degrees per hour. U.S. strategic platforms mandate radiation-hardened inertial cores from sole-source qualified suppliers.
- Navigation Systems:Marine and aviation dead-reckoning applications combine inertial measurement units with external reference updates. Commercial shipping operators are adopting integrated fiber optic systems to reduce gyrocompass maintenance.
- Weapon Systems:Guided munitions and fire control systems prioritize shock tolerance and volume production over strategic-grade precision.
- Robotics:Autonomous ground vehicles and industrial automation platforms consume MEMS-based inertial units.
Navigation systems hold the largest share; robotics is gaining share fastest.
Form Factor:
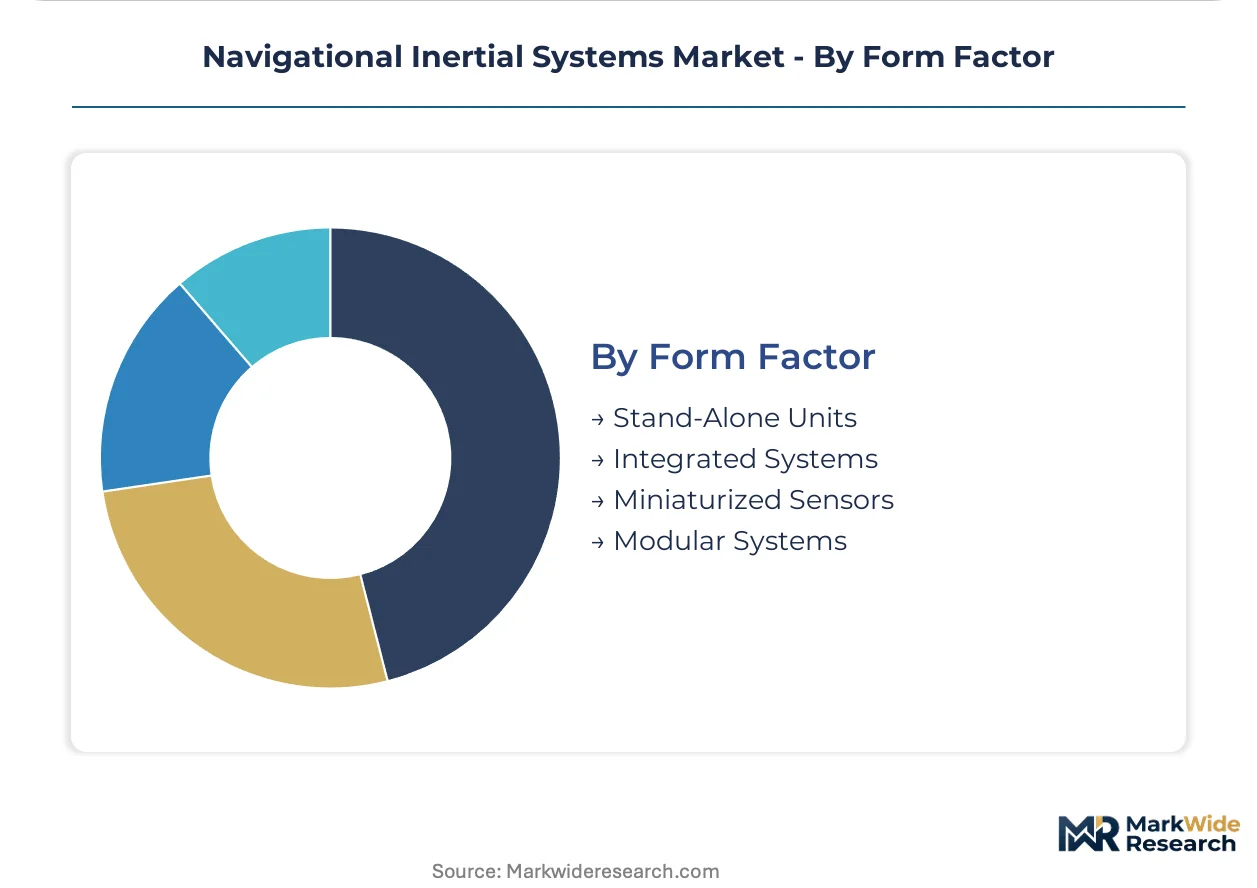
Stand-alone units retain premium pricing in defense applications where performance isolation matters, while integrated and modular architectures capture commercial aviation and new space volume.
- Stand-Alone Units:Discrete inertial navigation systems with dedicated enclosures and power supplies achieve the highest performance tiers. U.S. Navy submarine programs specify stand-alone ring laser gyroscope units for nuclear deterrent patrols.
- Integrated Systems:Multi-sensor fusion architectures combine inertial cores with GPS receivers and air data computers on common circuit cards. Airbus and Boeing flight management system upgrades favor this form factor for retrofit compatibility.
- Miniaturized Sensors:Chip-scale and wafer-level packaged inertial units target consumer drone and wearable applications.
- Modular Systems:Open-architecture inertial units with standardized interfaces enable platform reconfiguration without redesign.
Stand-alone units hold the largest share; integrated systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes navigational inertial systems predominantly through defense procurement for strategic platforms, while Germany and Japan deploy equivalent technologies toward automotive autonomy and commercial aerospace certification pathways.
United States
Pentagon procurement for submarine and bomber programs drives demand for radiation-hardened inertial cores. FAA airworthiness standards for civil inertial reference units shape product development cycles for dual-use suppliers. Defense primes cluster around Washington D.C. and California corridors where sole-source contracts embed technical data rights clauses.
Germany
Automotive OEMs pre-qualify fiber optic gyroscopes for SAE Level 4 autonomous architectures. EASA certification timelines for next-generation flight management systems accelerate procurement cycles. Engineering talent concentrates in Munich and Stuttgart where tier-one suppliers compete for MEMS fabrication specialists.
France
Naval inertial navigation programs sustain demand for sovereign manufacturing capability. EU F-Gas Regulation phase-down schedules affect cooling system design for cold atom research. Safran Electronics & Defense anchors production in Paris-Saclay cluster with captive manufacturing for European defense markets.
Japan
Specialty fiber coil winding equipment and polarization-maintaining fiber supply concentrate among component houses in Tokyo-Osaka industrial corridor. METI funding supports photonic integrated circuit development for tactical-grade applications. Precision optics input volatility affects cost structures for fiber optic gyroscope manufacturers.
India
Defense Research and Development Organisation funds domestic inertial navigation capability under Make in India framework. BIS standards and local production mandates create openings for joint ventures with foreign technology holders. Hyderabad and Bengaluru clusters host emerging MEMS fabrication facilities for tactical-grade sensors.
Navigational Inertial Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in navigational inertial systems. Defense primes with decades of ring laser gyroscope heritage anchor high-end aerospace contracts through sole-source relationships. MEMS fabrication specialists and photonic component houses occupy mid-tier positions serving commercial aviation and automotive autonomy programs. Competitive moves center on multi-year contract consolidation with embedded technical data rights and foundry partnerships with compound semiconductor houses.
Among U.S.-based defense primes, Honeywell International Inc. and Northrop Grumman Corporation exemplify integrated leadership through captive manufacturing and radiation-hardened system qualification. Safran Electronics & Defense occupies a position within the European sovereign tier, anchoring naval inertial navigation production in France. These three entities represent distinct archetypes: U.S. strategic platform integration, European defense sovereignty, and dual-use commercial certification capability.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Northrop Grumman Corporation |
| Safran Electronics & Defense |
| Thales Group |
| Collins Aerospace |
| Raytheon Technologies |
| L3Harris Technologies Inc. |
| BAE Systems |
| Inertial Labs Inc. |
| Others |
Supply & Pricing Matrix
FAA airworthiness standards and EASA CS-25 certification gates both supply qualification and price differentiation simultaneously, with dual-certified inertial reference units commanding substantial premiums over single-jurisdiction alternatives. Defense procurement through sole-source contracts anchors the high-value tier, while commercial aviation and automotive segments face compression from volume-scale demands.
Pricing Analysis
Long-term offtake agreements with embedded technical data rights clauses dominate defense procurement, insulating prime contractors from spot-market volatility. Three-tier pricing structure across strategic-grade, tactical-grade, and commercial-grade tiers reflects certification burden and drift specification differentials. Cost compression in MEMS accelerometer segments is intensifying because automotive OEMs are consolidating supplier lists around dual-use qualified vendors. Tier-one automotive suppliers exhibit the highest price sensitivity, whereas Pentagon submarine programs demonstrate minimal elasticity due to sole-source risk mitigation priorities.
Supply Chain Analysis
Container availability constraints on transpacific lanes elevate inbound logistics costs for Japanese polarization-maintaining fiber and German specialty coil-winding equipment. Manufacturing concentrates in the United States, France, and Japan, with the Paris-Saclay cluster hosting captive naval production and Tokyo-Osaka corridors feeding precision optics inputs. Rare-earth doping materials and indium phosphide substrates draw from concentrated geological and refining sources. Single-source vulnerability pervades helium-neon gas cavity supply for ring laser gyroscopes. Distribution runs through defense prime direct channels for strategic platforms and tier-one integrator networks for commercial aviation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photonic integrated circuit gyroscopes threaten established fiber optic coil architectures with fundamentally different cost structures, compelling incumbents to defend substitution exposure through capability deepening and certification moats.
For Market Incumbents: Fortify radiation-hardened system qualification pipelines against cold atom interferometry convergence by accelerating foundry partnerships with compound semiconductor houses. Deepen backward integration into polarization-maintaining fiber supply to offset Japanese component house concentration. Lock in multi-year sole-source contracts with embedded technical data rights before EASA-FAA harmonization opens procurement to cross-border challengers. For New Entrants and Emerging Players: EASA fast-track certification for SAE Level 4 automotive architectures offers the most penetrable entry vector, with German OEM pre-qualification cycles shorter than defense procurement timelines. Target Indian joint ventures under Make in India local production mandates to bypass ITAR export control friction for tactical-grade segments. Lead with MEMS-based inertial measurement units for sensor fusion stacks where consumer-grade cost structures meet tactical-grade performance thresholds. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape by extending cold atom sensor qualification timelines and stranding legacy cooling system investments. Five-to-ten-year viability favors photonic integrated circuit developers with indium phosphide foundry access over discrete fiber optic coil assemblers. Watch for Pentagon vendor list consolidation announcements as the primary inflection signal for sole-source contract availability.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Foundry Partnership | Indium phosphide optical chip qualification compresses traditional coil-winding equipment margins. |
| Dual Certification Investment | Simultaneous FAA-EASA compliance unlocks Airbus and Boeing platform retrofit opportunities. |
| Radiation-Hardening Capability Buildout | Pentagon GPS-denied warfare mandates prioritize contested electromagnetic environment resilience. |
| Indian Joint Venture Formation | DRDO funding under Make in India framework bypasses ITAR licensing for tactical-grade exports. |
| Cold Atom Interferometry R&D Pipeline | Portable form factor convergence promises order-of-magnitude drift improvements for submarine guidance. |
Research Methodology
Operator-level perspectives from defense procurement officers, MEMS fabrication specialists, tier-one automotive supplier engineers, and flight management system certification leads anchored the qualitative base. Primary interview insights combined with secondary validation from FAA airworthiness directives, EASA certification databases, Pentagon budget justification materials, and customs trade data for polarization-maintaining fiber imports. Bottom-up segment sizing and top-down macroeconomic cross-checks established triangulation discipline across the analysis window.
Sensitivity analysis framed volume and value outputs across technology, end-user, application, and form factor dimensions, with additional modeling for certification jurisdiction and radiation-hardening grade. CAGRs derived from segment-level unit economics and procurement pipeline visibility, incorporating defense modernization cycle phasing and automotive autonomy roadmap milestones as industry-specific forecast inputs.
Underlying assumptions cover EASA-FAA harmonization progress, helium-neon gas supply stability, and rare-earth doping material price trajectories, with deviation risk concentrated in export control policy shifts and cold atom sensor commercialization timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market