

Surface Radars Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Radars Market Insights
Software-defined radar processing is decoupling hardware refresh cycles from capability upgrades across military and commercial fleets. RTX leverages its GaN semiconductor foundry investments to sustain technology leadership in active electronically scanned arrays. Lockheed Martin anchors long-range air defense programs with integrated radar networks spanning multiple NATO member states. Thales competes through dual-use maritime surveillance platforms serving both naval forces and port authorities.
Surface radars are electromagnetic detection systems operating across L-band through X-band frequencies, transmitting pulsed or continuous wave energy to determine target range, velocity, and azimuth with resolutions down to sub-meter scales for synthetic aperture modes. Their primary function spans air traffic management, ballistic missile tracking, vessel traffic services, and meteorological observation. Phased array architectures now lead defense procurement budgets due to simultaneous multi-target tracking and electronic beam steering without mechanical rotation. Solid-state transmitters represent the fastest-growing technology segment as magnetron-dependent systems face obsolescence from reliability and maintenance cost disadvantages. Maritime navigation applications constitute a mature revenue pool, while border security deployments in contested littoral zones concentrate margin expansion.
The U.S. Federal Communications Commission and Department of Defense jointly regulate spectrum allocation for radar operations, with recent reassignments compressing available bandwidth for civilian meteorological systems. EU F-Gas Regulation compliance requirements are forcing transmitter thermal management redesigns, particularly affecting traveling wave tube cooling architectures. India's Bureau of Indian Standards and Defence Research and Development Organisation enforce indigenous content thresholds that reshape supply chain qualification for foreign OEMs. Stakeholders must monitor spectrum policy divergence between allied defense blocs, as incompatible frequency band plans threaten interoperability for multinational radar networks and joint operations.
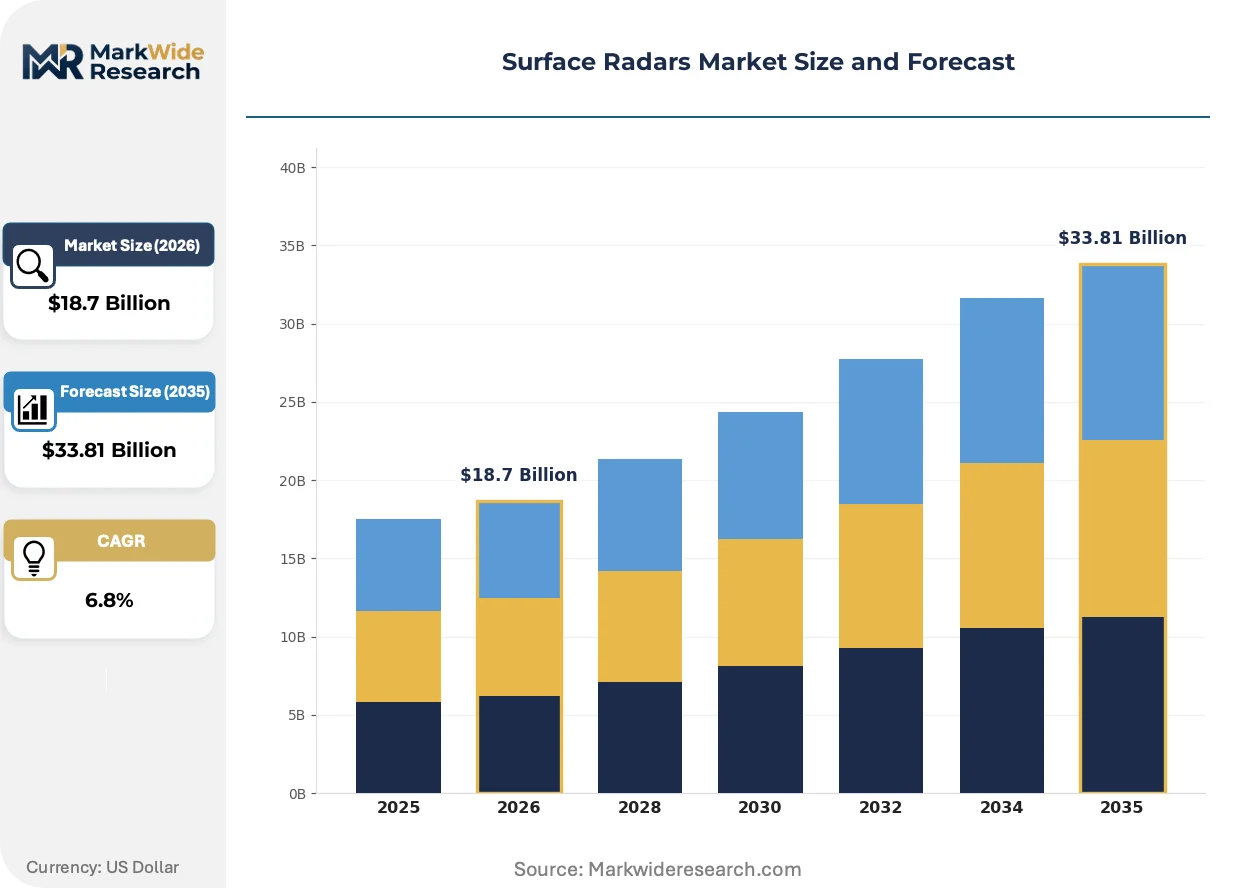
Market Dynamics
Defense procurement agencies are consolidating requirements around software-defined architectures that decouple hardware refresh cycles from capability upgrades, compressing supplier qualification timelines and reshaping contract structures for active electronically scanned array systems.
Growth Catalysts
- Solid-state transmitter mandates:Magnetron-dependent systems face obsolescence as defense ministries prioritize gallium nitride semiconductor reliability and reduced maintenance burdens in integrated air defense networks.
- EU F-Gas Regulation:The revised framework accelerates thermal management redesigns in radar transmitter assemblies, creating replacement demand for traveling wave tube cooling architectures.
- Coastal surveillance expansion:Contested littoral zones in the Indo-Pacific drive border security deployments with higher margin profiles than mature maritime navigation applications.
Market Restraints
- Gallium nitride substrate concentration:Foundry capacity for wide-bandgap semiconductors concentrates among limited suppliers, creating input bottlenecks for active electronically scanned array production.
- Spectrum reallocation friction:The U.S. Federal Communications Commission's bandwidth compressions for civilian meteorological systems force costly frequency migration programs.
- Indigenous content thresholds:India's Bureau of Indian Standards and Defence Research and Development Organisation mandates reshape supply chain qualification, extending foreign OEM entry timelines.
Strategic Opportunities
- Dual-use maritime platforms:Naval forces and port authorities converge on shared surveillance infrastructure, opening civilian revenue streams for defense-optimized radar manufacturers.
- Synthetic aperture resolution tiers:Sub-meter imaging capabilities expand addressable markets beyond traditional air traffic management into environmental monitoring and disaster response.
- Make in India localization:The Ministry of Defence's indigenization mandates create partnership structures for foreign technology transfer into domestic manufacturing ecosystems.
Industry Challenges
- Phased array integration complexity:Legacy mechanical rotation systems resist retrofit with electronic beam steering architectures, forcing complete platform replacement versus upgrade paths.
- Interoperability standardization gaps:Divergent frequency band plans between allied defense blocs threaten multinational radar network compatibility and joint operational effectiveness.
- GaN foundry talent scarcity:Compound semiconductor fabrication expertise concentrates in aerospace-defense clusters, constraining workforce scaling for commercial radar entrants.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Radars Market Trends and Innovations
Software-defined processing architectures are collapsing traditional hardware refresh timelines while regulatory pressure on thermal management and spectrum efficiency forces fundamental transmitter redesigns across defense and civilian fleets.
Digital beamforming is expanding into long-range air defense applications by enabling simultaneous multi-target tracking without mechanical antenna movement. NATO integrated radar networks are adopting these architectures to reduce platform downtime and extend operational availability. The technology is expanding into legacy platform upgrade programs that previously required complete system replacement.
The EU F-Gas Regulation is forcing transmitter thermal management redesigns with specific compliance deadlines for refrigerant phase-out in cooling systems. Traveling wave tube manufacturers face forced migration to solid-state alternatives or closed-loop cooling architectures. Maritime surveillance platforms serving dual naval and port authority use cases are most affected due to extended deployment cycles in salt-air environments.
Defense procurement agencies are consolidating vendor relationships around integrated radar networks rather than discrete sensor purchases. Long-term service and upgrade contracts are displacing transactional hardware sales in NATO member state programs. This concentration is most visible in United States Department of Defense programs spanning multiple allied territories with unified command requirements.
Surface Radars Market Segmentation
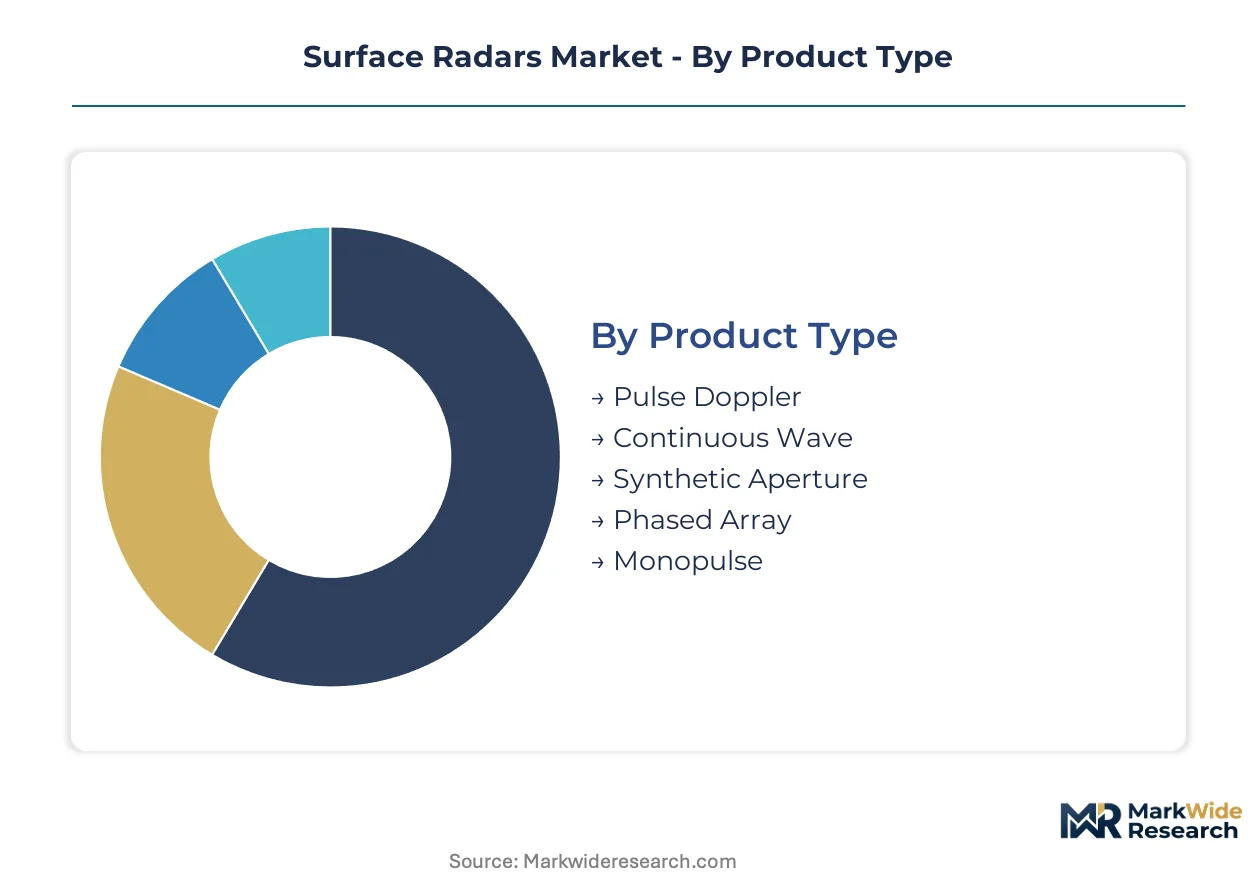
Segmentation in surface radars reveals how procurement agencies balance legacy system sustainment against capability modernization. Upgrade cycles vary dramatically across product architectures, with solid-state replacements accelerating while magnetron-dependent fleets face compressed retirement timelines.
Product Type:
Replacement cycles diverge sharply between mechanically scanned legacy platforms and electronically steered architectures, with procurement agencies favoring upgrade paths that preserve existing infrastructure investments.
- Phased Array:Active electronically scanned arrays eliminate mechanical rotation through solid-state transmit/receive modules. Defense agencies in the United States prioritize these systems for integrated air and missile defense networks, driven by simultaneous multi-target tracking requirements and reduced platform downtime.
- Synthetic Aperture:Sub-meter resolution imaging modes process radar returns across multiple pulses to generate high-fidelity terrain maps. Demand concentrates in environmental monitoring and disaster response applications, where resolution tiers below one meter expand addressable markets beyond traditional air traffic management.
- Pulse Doppler:Velocity measurement through frequency shift analysis remains standard for air traffic control and weather surveillance applications.
- Continuous Wave:Uninterrupted transmission architectures serve low-power applications including proximity fuses and short-range navigation aids.
- Monopulse:Simultaneous lobing techniques provide instantaneous angle measurement for precision tracking radars in fire control systems.
Phased Array sits at the top of the volume ranking, with Synthetic Aperture climbing the fastest.
Technology:
Cost tiers separate transmitter architectures by reliability premiums and lifecycle maintenance burdens, with gallium nitride semiconductors commanding price multiples over vacuum tube alternatives.
- Solid State:Gallium nitride semiconductor transmitters deliver higher power density and thermal efficiency than vacuum tube predecessors. Foundry capacity constraints concentrate among limited suppliers, creating input bottlenecks for active electronically scanned array production as defense ministries mandate reliability improvements.
- Digital Signal Processing:Software-defined architectures decouple hardware refresh cycles from capability upgrades through firmware-based waveform generation. NATO integrated radar networks adopt these systems to extend operational availability without complete platform replacement.
- Magnetron:Crossed-field oscillator transmitters face obsolescence from maintenance cost disadvantages and limited frequency agility in modern threat environments.
- Traveling Wave Tube:Linear beam amplifiers require thermal management redesigns under EU F-Gas Regulation compliance deadlines for refrigerant phase-out in cooling systems.
- Pulse Compression:Matched filter techniques improve range resolution without peak power increases, serving long-range surveillance applications with spectrum efficiency constraints.
Solid State dominates procurement budgets by value, while Digital Signal Processing expands most quickly across retrofit programs.
Application:
Margin profiles vary by deployment environment maturity, with contested littoral zones commanding premium pricing over established maritime corridors.
- Border Security:Coastal surveillance in contested Indo-Pacific regions requires all-weather detection against low-observable threats. India's Ministry of Defence indigenization mandates under the Make in India initiative reshape local manufacturing ecosystems for these deployments.
- Port Surveillance:Dual-use infrastructure serving naval forces and civilian port authorities converges on shared sensor networks. Thales competes through platforms optimized for both military and maritime authority requirements, opening civilian revenue streams for defense-optimized manufacturers.
- Maritime Navigation:Vessel traffic services in established shipping lanes constitute mature revenue pools with compressed margin structures.
- Weather Monitoring:Meteorological observation networks face spectrum reallocation pressure from the U.S. Federal Communications Commission bandwidth compressions, forcing costly frequency migration programs.
- Coastal Defense:Integrated air and missile defense networks require long-range detection against ballistic and cruise missile threats.
Maritime Navigation retains the largest installed base, though Border Security gains share fastest as Indo-Pacific procurement accelerates.
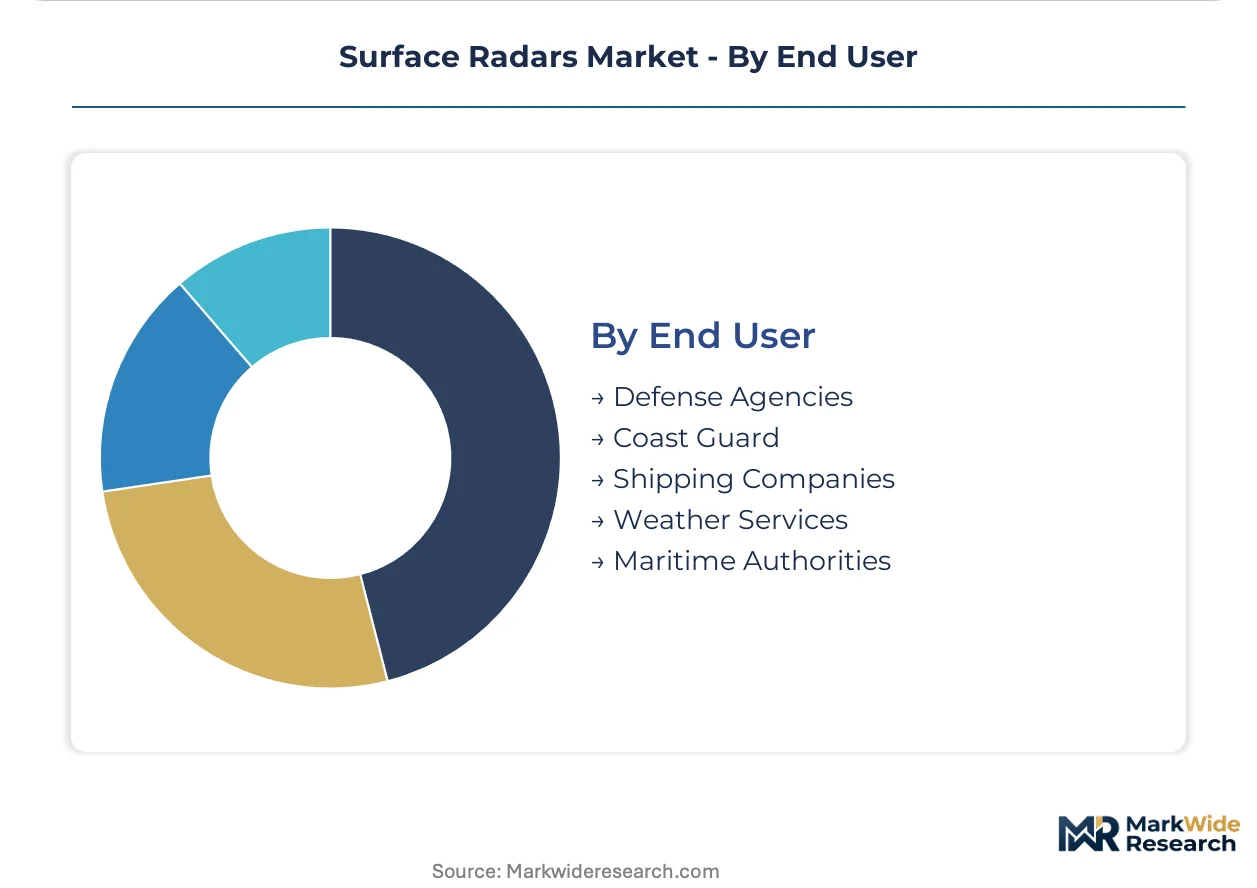
End User:
Customer type determines contract structure complexity, with defense agencies consolidating vendor relationships around long-term service agreements while commercial operators prioritize transactional hardware procurement.
- Defense Agencies:Integrated radar network requirements span multiple NATO member states with unified command structures. The United States Department of Defense anchors long-range air defense programs with consolidated procurement spanning allied territories, displacing transactional hardware sales with multi-year upgrade contracts.
- Coast Guard:Dual-mission maritime security and search-and-rescue operations demand versatile platforms with rapid reconfiguration capability.
- Shipping Companies:Commercial fleet operators prioritize collision avoidance and navigation safety within established corridor traffic separation schemes.
- Weather Services:National meteorological agencies operate under spectrum allocation constraints from joint U.S. Federal Communications Commission and Department of Defense regulatory frameworks.
- Maritime Authorities:Port state control and vessel traffic management systems integrate with naval surveillance networks in dual-use architectures.
Defense Agencies command the largest procurement volumes, with Coast Guard modernization programs expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates phased array procurement for integrated air defense networks, while India accelerates coastal surveillance indigenization under Make in India mandates. Defense procurement patterns diverge sharply between established NATO integrated systems and emerging Indo-Pacific border security deployments.
United States
The Department of Defense anchors long-range air defense programs spanning multiple allied territories with unified command requirements. FCC and DoD joint spectrum reassignments compress available bandwidth for civilian meteorological systems, forcing costly frequency migration programs. RTX leverages GaN semiconductor foundry investments in Arizona and Massachusetts to sustain technology leadership in active electronically scanned arrays.
Germany
HENSOLDT anchors European radar manufacturing with traveling wave tube architectures requiring thermal management redesigns under EU F-Gas Regulation compliance deadlines. The revised framework accelerates refrigerant phase-out in cooling systems, creating replacement demand across transmitter assemblies. Bavaria-based defense electronics clusters concentrate compound semiconductor fabrication expertise for NATO integrated radar networks.
India
The Ministry of Defence's indigenization mandates reshape local manufacturing ecosystems for coastal surveillance radars in contested littoral zones. BIS and DRDO enforce indigenous content thresholds that extend foreign OEM entry timelines while creating partnership structures for technology transfer. Gujarat and Tamil Nadu defense corridors concentrate Make in India localization programs for border security deployments.
United Kingdom
BAE Systems anchors long-range air defense programs with integrated radar networks spanning multiple NATO member states. The UK Ministry of Defence consolidates vendor relationships around multi-year upgrade contracts displacing transactional hardware sales. Scotland-based electronics manufacturing clusters focus on maritime surveillance platforms serving dual naval and port authority use cases.
France
Thales competes through dual-use maritime surveillance platforms optimized for both naval forces and civilian port authorities, opening civilian revenue streams for defense-optimized manufacturers. ANSM and CNIL regulatory frameworks intersect with EU F-Gas thermal management requirements for transmitter cooling architectures. Provence-Alpes-Côte d'Azur defense electronics clusters concentrate on Mediterranean coastal surveillance integration with NATO command structures.
Surface Radars Market Competitive Landscape
Top-tier vendors anchor integrated radar network procurement, while mid-tier specialists occupy retrofit and upgrade niches. The vendor base stratifies across three tiers: prime contractors delivering NATO-spanning command systems, national champions serving domestic defense requirements, and component specialists feeding GaN foundry and digital signal processing supply chains. Strategic archetypes include software-defined architecture consolidators, dual-use maritime platform developers, and solid-state transmitter technology licensors. M&A activity concentrates on GaN semiconductor foundry acquisitions and long-term service contract consolidation.
Among US-based defense primes, RTX, Lockheed Martin, and Northrop Grumman occupy positions exemplifying the integrated network consolidator archetype. RTX represents the GaN foundry-integrated technology path, Lockheed Martin anchors the NATO-spanning command system tier, and Northrop Grumman sits within the long-range surveillance specialization segment. European counterparts Thales, Leonardo, and HENSOLDT exemplify dual-use maritime and thermal management redesign specialists under EU regulatory pressure. Saab and BAE Systems occupy national champion positions with NATO interoperability mandates, while L3Harris Technologies represents the mid-tier upgrade and retrofit service consolidation path.
| Leading Market Players |
|---|
| RTX |
| Lockheed Martin |
| Thales |
| Northrop Grumman |
| L3Harris Technologies |
| Leonardo |
| BAE Systems |
| Saab |
| HENSOLDT |
| Others |
Pricing and Supply Chain Analysis
Compound semiconductor fabrication expertise concentrated in Arizona and Massachusetts drives labor-cost differentials that widen pricing-tier spreads between GaN-integrated active electronically scanned arrays and legacy magnetron-dependent systems.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for gallium nitride substrates used in solid-state transmitters. Three-tier pricing structure across premium, standard, and economy levels separates NATO-integrated command systems from national-defense specifications and commercial maritime navigation units. Cost compression in the economy tier is intensifying because India's indigenization mandates force foreign OEMs to absorb technology-transfer overhead. Defense agencies show least price sensitivity due to mission-critical requirements, while commercial shipping operators resist premium positioning.
Supply Chain Analysis
MIL-STD-810G environmental qualification and BIS certification gating restrict supplier pools for transmitter assemblies deployed in contested littoral zones. Manufacturing concentrates in the United States, Germany, and India for defense-grade systems, with Taiwan and Japan anchoring commercial GaN foundry supply. The supply chain draws from high-purity silicon carbide substrates, specialized thermal interface materials, and precision antenna fabrication. Single-source vulnerability in wide-bandgap semiconductor foundries creates structural risk. Distribution runs through defense procurement agencies with multi-year service contracts displacing transactional hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
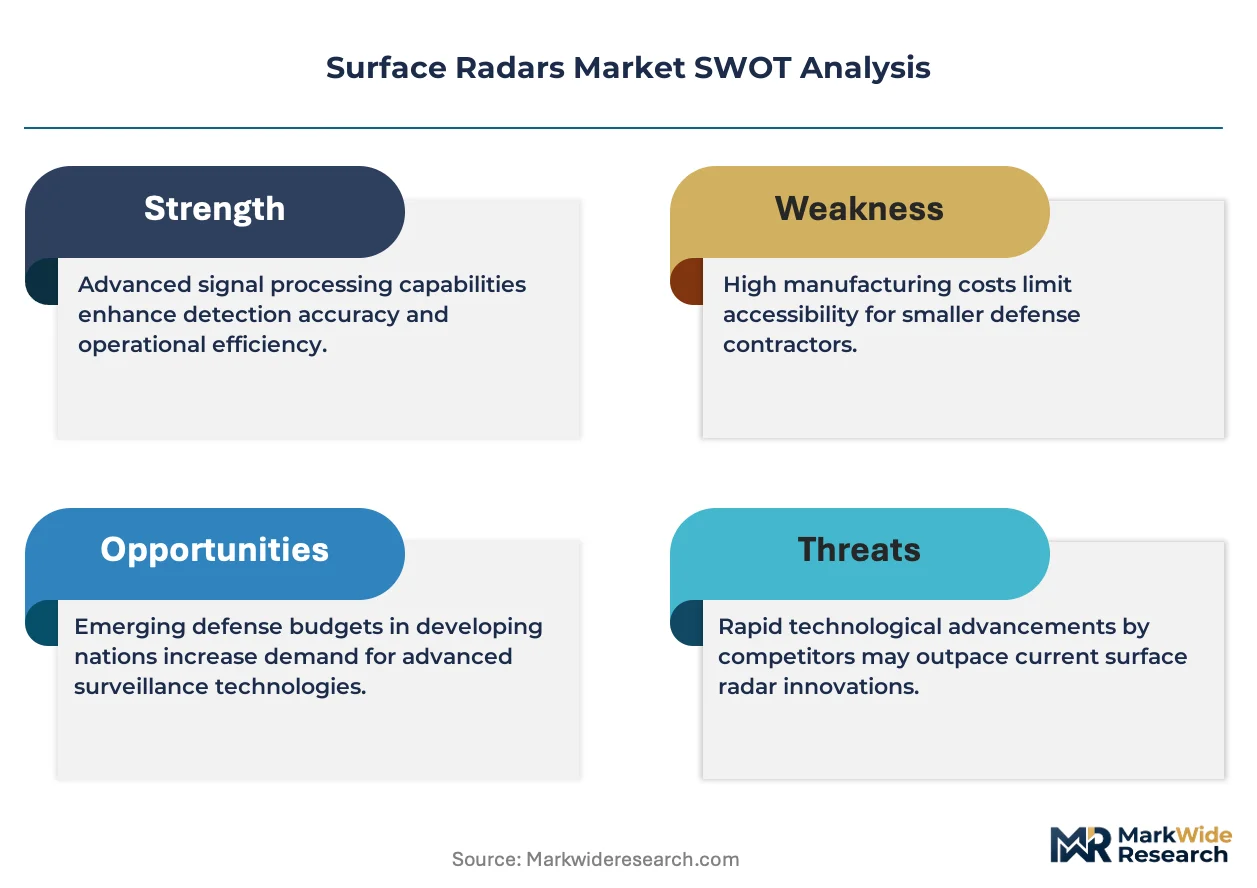
The surface radars market functions as a stable compounder anchored by defense procurement cycles that refresh integrated air and missile defense networks across NATO territories regardless of commercial cyclicality.
For Market Incumbents: Lock in long-term service contracts spanning multiple NATO member states to capture recurring upgrade revenue from software-defined architectures. Deepen backward integration into gallium nitride foundry capacity to defend against substrate concentration bottlenecks. Prioritize thermal management redesign capabilities as EU F-Gas Regulation compliance deadlines force transmitter cooling system replacements.
For New Entrants and Emerging Players: India's Make in India initiative opens a window for partnership structures that transfer solid-state transmitter technology into Gujarat and Tamil Nadu defense corridors. Target coastal surveillance deployments in contested Indo-Pacific regions where margin profiles exceed mature maritime navigation applications. Pursue dual-use maritime platforms serving both naval forces and port authorities to access civilian revenue streams.
For Investors and Strategic Acquirers: Defense primes with integrated radar network consolidation mandates are the most active acquirer in this space. The market supports long-term viability through sustained defense budget allocation to electronic beam steering architectures. Monitor GaN semiconductor foundry acquisition activity as the primary inflection indicator for technology leadership shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Acquisition | RTX's Arizona and Massachusetts investments secure captive supply for active electronically scanned array production. |
| Dual-Use Platform Development | Thales' maritime surveillance systems serve both French naval forces and Mediterranean port authorities. |
| Make in India Localization | Foreign OEM technology transfer partnerships satisfy BIS and DRDO indigenous content thresholds. |
| Software-Defined Architecture Deployment | NATO integrated radar networks adopt firmware-based waveform generation to extend operational availability. |
| Thermal Management Redesign | HENSOLDT's traveling wave tube cooling architectures migrate to solid-state alternatives under EU F-Gas deadlines. |
Research Methodology
Multiple input streams — defense procurement officer interviews, GaN foundry technical assessments, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged radar systems engineers, Ministry of Defence acquisition leads, port authority maritime surveillance directors, and thermal management component suppliers. Secondary validation drew from U.S. Department of Defense budget justification documents, EU F-Gas Regulation compliance filings, BIS technical standards publications, and NATO integrated radar network capability roadmaps.
Historical deployment trajectories were cross-referenced against panel input from defense electronics executives to establish analytical framework parameters across the projection horizon. Segmentation dimensions modeled include product architecture, transmitter technology tier, application environment maturity, and end-user contract structure complexity. CAGRs were derived from capacity expansion announcements, procurement timeline disclosures, and substitution elasticity estimates for solid-state versus vacuum tube systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under spectrum reallocation acceleration or GaN substrate supply disruption scenarios. Model outputs reflect documented assumptions regarding defense budget continuity, regulatory phase-out schedules, and foundry yield improvement trajectories. A model refresh is warranted upon material change in NATO integrated radar network procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.