
 Drone Transponders Market | 2026-2036
Drone Transponders Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Transponders Market Analysis
China is reconfiguring its domestic supply chain for miniature avionics components, creating ripple effects for transponder module availability worldwide. UAvionix leverages its FAA-certified engineering organization to sustain design authority over remote ID and ADS-B solutions for commercial unmanned platforms. Garmin anchors the high-performance segment with integrated avionics ecosystems that extend from manned aviation into unmanned applications. Sagetech competes through military-grade Mode S and IFF transponders purpose-built for small tactical unmanned systems.
A drone transponder is an electronic device that transmits identification, position, and altitude data via radio frequency to air traffic control systems and other aircraft, typically operating on 1090 MHz or 978 MHz with power outputs ranging from 20 to 250 watts depending on platform class. Its primary purpose is to prevent mid-air collisions and enable safe integration of unmanned aircraft into controlled airspace alongside manned aviation. ADS-B technology dominates the commercial retrofit segment as regulatory deadlines force compliance investments, while Mode S transponders command premium pricing in military applications where encryption and identification-friend-or-foe compatibility are mandatory. GPS-enabled hybrid architectures represent the fastest-growing technology category, combining satellite positioning with RF backup for contested electromagnetic environments.
The FAA's remote ID rule and EASA's equivalent drone regulation framework are mandating broadcast capabilities that directly specify transponder performance standards, creating product-level compliance barriers for uncertified manufacturers. Military procurement specifications from NATO standardization offices and national defense ministries further segment the market between commercial off-the-shelf and hardened tactical variants. Stakeholders must monitor the divergence between civilian remote ID mandates and military encryption requirements, as dual-use product strategies face escalating certification complexity on both fronts.
Market Dynamics
The FAA Remote ID rule and EASA drone regulation frameworks are compressing product development cycles, forcing manufacturers to prioritize certified ADS-B and Mode S architectures over uncertified alternatives before enforcement deadlines take effect.
Growth Catalysts
- Beyond-visual-line-of-sight mandates:NATO procurement specifications for active transponder systems in tactical unmanned platforms are expanding military adoption across member defense ministries.
- Remote ID compliance deadlines:Commercial operators in the United States face retrofit requirements for legacy drone fleets, creating immediate certified equipment demand.
- Hybrid GPS-RF architectures:GPS-enabled backup systems for contested electromagnetic environments are gaining traction in defense applications requiring operational redundancy.
Market Restraints
- Certification cost barriers:FAA TSO-C154c and EASA CS-ETSO approval processes impose six-figure testing expenditures that exclude smaller module suppliers.
- Component supply concentration:Miniature avionics manufacturing capacity in China creates vulnerability for transponder module availability during trade disruptions.
- Power-weight tradeoffs:Mode S transponders with IFF compatibility require 20-250 watt outputs that exceed payload budgets for sub-25kg commercial drones.
Strategic Opportunities
- Unpenetrated logistics corridors:Last-mile delivery networks in Germany and France lack certified transponder infrastructure for urban air mobility integration.
- Dual-use certification convergence:Products meeting both civilian Remote ID and military encryption specifications can capture procurement budgets from defense and commercial buyers simultaneously.
- Retrofit service channels:Authorized installation networks for legacy fleet compliance represent recurring revenue streams distinct from equipment sales.
Industry Challenges
- RF engineering talent scarcity:Design authority for 1090 MHz and 978 MHz systems requires specialized expertise concentrated among FAA-certified engineering organizations.
- Multi-jurisdiction certification timelines:Parallel FAA and EASA approval processes extend product launch cycles by 18-24 months for international market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Transponders Market |
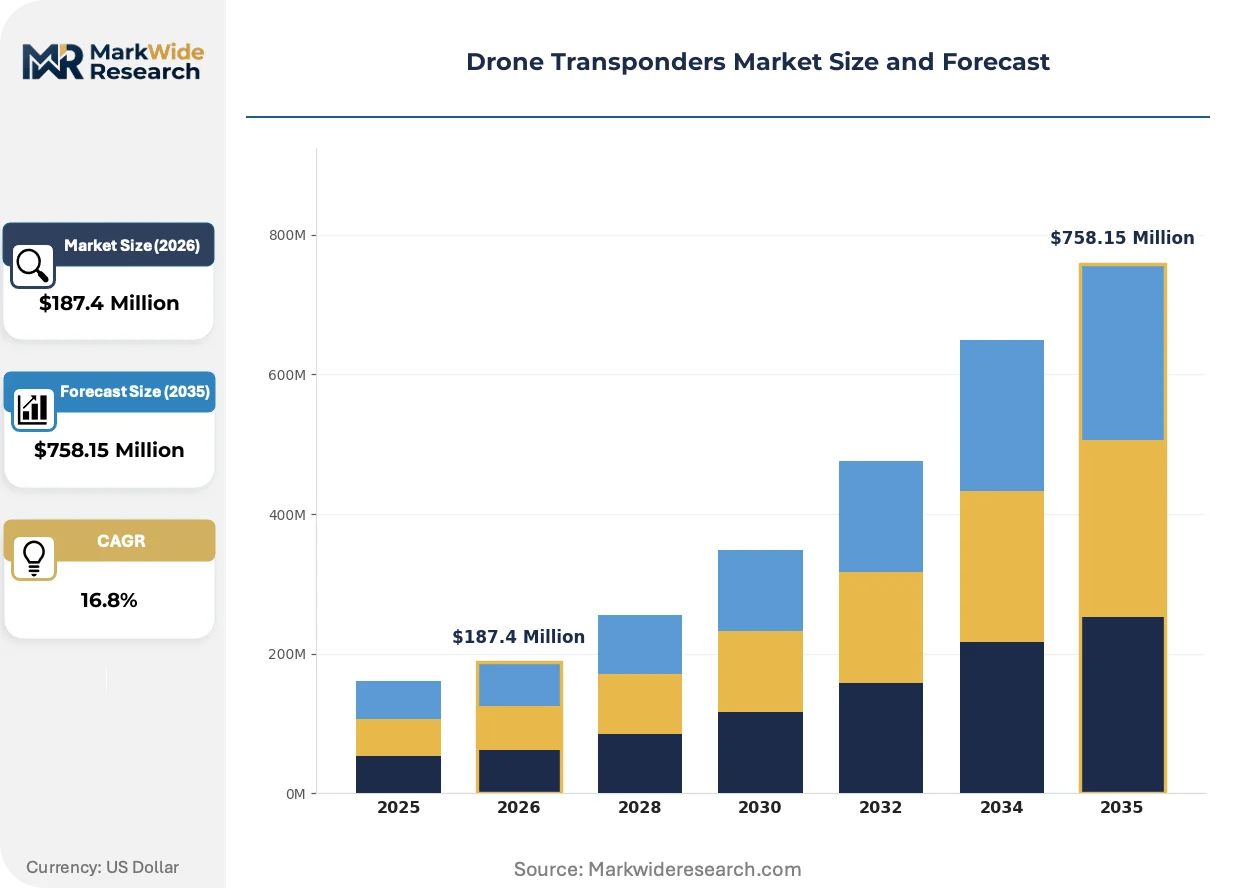
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Passive, Active, Semi-Active, Hybrid Application: Aerial Photography, Cargo Delivery, Surveillance, Agriculture End User: Government, Commercial, Military, Emergency Services Technology: ADS-B, Mode S, GPS, RF |
| Companies Covered | Sandia Aerospace, Microair Avionics, UAvionix, Micro Systems, Teletronics Technology, Sagetech, Trig Avionics, Garmin, Aerobits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Transponders Market Emerging Trajectories
Transponder architectures are bifurcating between standardized commercial Remote ID modules and hardened military variants, with certification requirements becoming the primary axis of competitive differentiation rather than raw performance specifications.
Multi-frequency transponder designs integrating 1090 MHz ADS-B Out with 978 MHz UAT are migrating from experimental platforms into mainstream commercial unmanned systems. Agricultural spraying operators and infrastructure inspection providers in the United States are adopting these dual-band configurations to maximize airspace access flexibility. This migration from single-frequency legacy equipment is compressing the addressable market for standalone 978 MHz solutions.
The European Union's harmonized drone regulation framework, implemented through EASA delegated acts, mandates broadcast remote ID capabilities that specify exact transponder performance thresholds. Equipment manufacturers must demonstrate compliance with CS-ETSO standards to access EU member state markets. Small tactical drone suppliers in France and Italy are accelerating product redesigns to meet these certification requirements before 2026 enforcement phases begin.
Defense procurement offices are unbundling transponder specifications from complete airframe contracts, creating direct vendor relationships with component specialists. This pattern displaces traditional prime contractor intermediation for avionics subsystems. The United Kingdom Ministry of Defence and Norwegian Defence Materiel Agency have issued standalone Mode S and IFF transponder tenders, establishing this channel structure as standard practice for NATO procurement.
Drone Transponders Market Segmentation
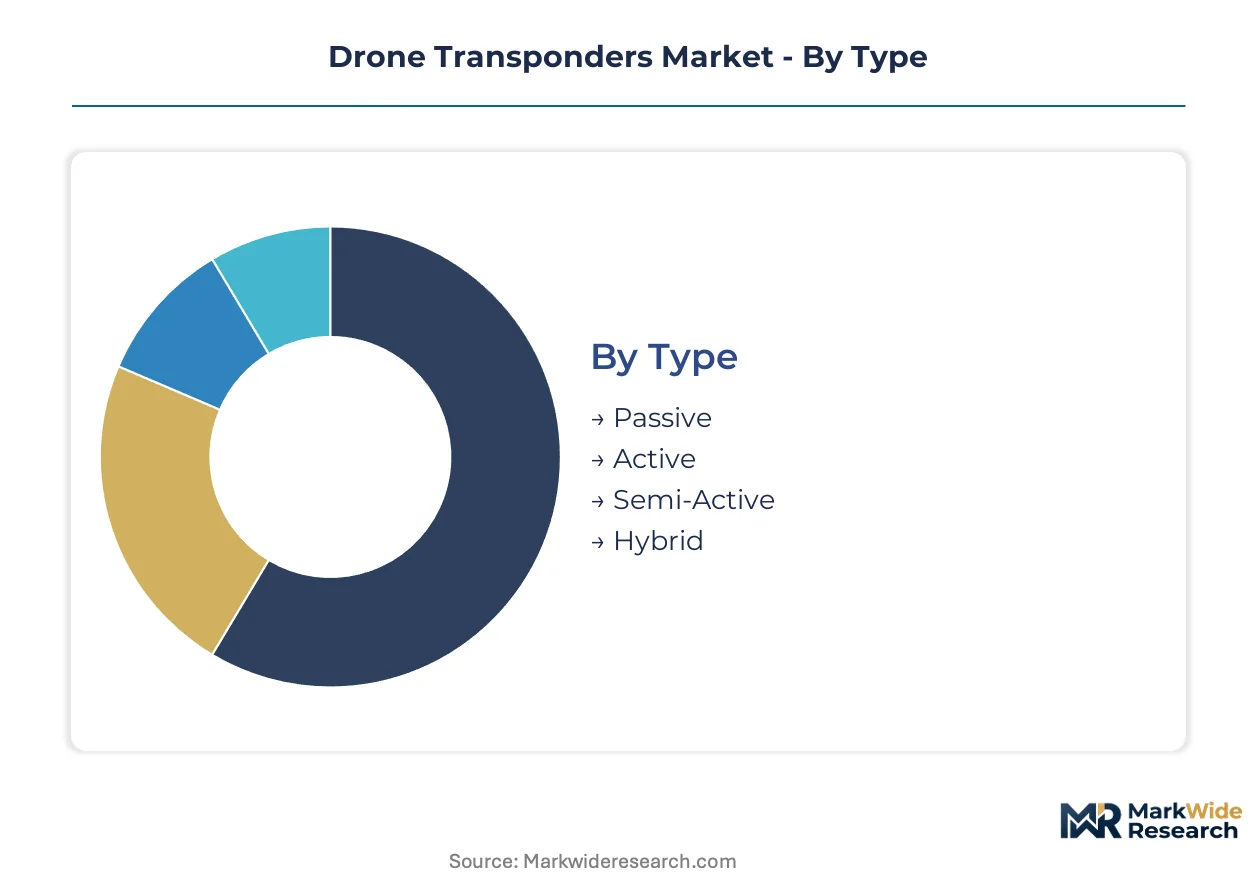
Drone transponder segmentation reveals distinct procurement rhythms across defense, commercial, and regulatory compliance channels. Equipment replacement cycles vary from months for commercial retrofit programs to years for military platform integration, creating tiered revenue predictability for suppliers.
Type:
Active transponders turn over fastest in commercial retrofit waves, while passive and hybrid architectures endure longer in defense platform lifecycles.
- Active:Self-powered units transmit identification and position data independently, drawing 20-250 watts for 1090 MHz broadcast. Demand concentrates in United States cargo delivery fleets facing FAA Remote ID enforcement, where retrofit deadlines compress procurement into concentrated windows.
- Hybrid:Dual-mode architectures combine active transmission with passive reception capabilities, enabling contested-environment redundancy. Military procurement across NATO member states prioritizes these configurations for tactical unmanned systems operating in GPS-denied airspace.
- Passive:Transponder units relying on external interrogation signals, common in legacy surveillance platforms requiring minimal power draw.
- Semi-Active:Intermediate architectures using external power for signal amplification while maintaining passive reception characteristics.
Active transponders anchor the volume base while hybrid configurations gain share at the steepest rate.
Application:
Application segmentation maps directly onto regulatory jurisdiction intensity, with surveillance and cargo delivery facing the most stringent equipment mandates.
- Surveillance:Border patrol and infrastructure monitoring operations require continuous position broadcasting for airspace deconfliction. Government contracts in the United States and United Kingdom specify encrypted Mode S or ADS-B Out compliance, with procurement cycles tied to federal fiscal appropriations.
- Cargo Delivery:Urban air mobility networks in Germany and France demand certified transponder infrastructure for beyond-visual-line-of-sight authorization. Last-mile logistics providers face EASA CS-ETSO compliance thresholds before operational permits issue.
- Aerial Photography:Commercial imaging operations in controlled airspace require basic Remote ID broadcast capability for FAA compliance.
- Agriculture:Crop spraying and field monitoring applications in the United States adopt dual-band 1090/978 MHz configurations for maximum airspace access flexibility.
Surveillance applications command the highest unit margins while cargo delivery expands most quickly.
End User:
End user segmentation separates specification authority between centralized defense procurement and fragmented commercial operator decisions.
- Military:Defense ministries issue standalone transponder tenders unbundled from complete airframe contracts, creating direct vendor relationships. Mode S and IFF compatibility requirements from NATO standardization offices mandate encryption capabilities unavailable in commercial variants.
- Commercial:Logistics providers and service operators face retrofit mandates with compressed compliance deadlines, prioritizing certified equipment availability over performance optimization.
- Government:Civilian agencies including border control and environmental monitoring operate under procurement specifications distinct from military encryption requirements.
- Emergency Services:Search and rescue operations require portable transponder solutions for rapid deployment across varied airspace classifications.
Military procurement anchors the value base while commercial end users drive volume expansion.
Technology:
Technology segmentation tracks the divergence between civilian broadcast standards and military identification protocols.
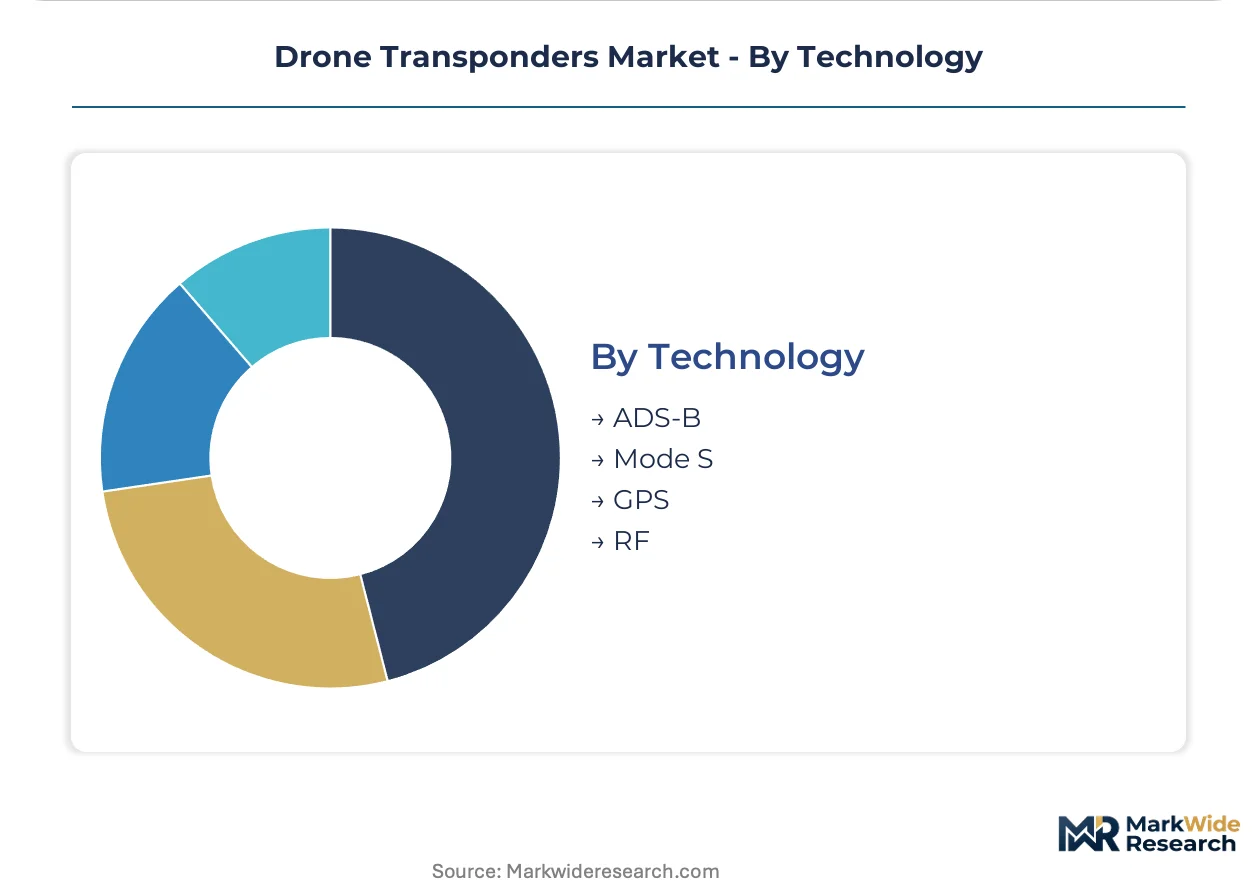
- ADS-B:Automatic Dependent Surveillance-Broadcast dominates commercial retrofit demand as FAA and EASA mandates specify exact performance thresholds. Equipment manufacturers demonstrate TSO-C154c or CS-ETSO compliance to access regulated markets.
- Mode S:Selective interrogation transponders with IFF compatibility command premium positioning in defense applications. United Kingdom Ministry of Defence and Norwegian Defence Materiel Agency tenders specify these architectures for tactical unmanned systems.
- GPS:Satellite positioning modules serve as enabling components within hybrid architectures rather than standalone transponder solutions.
- RF:Radio frequency backup systems provide electromagnetic contingency for contested operational environments.
ADS-B technology anchors the installed base while Mode S climbs the fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA's Remote ID mandate anchors United States transponder demand through 2026 enforcement deadlines, while NATO procurement specifications and EASA delegated acts create parallel compliance channels across Europe. Defense logistics corridors and urban air mobility networks concentrate equipment procurement in specific national markets with distinct regulatory timelines.
United States
Defense contractors and commercial logistics providers scale transponder-integrated platforms simultaneously, with FAA Remote ID rule deadlines compelling retrofit investments across legacy drone fleets. The FAA's TSO-C154c certification process filters equipment suppliers through six-figure testing expenditures. California and Texas host concentrated aerospace engineering clusters where UAvionix and Garmin maintain design authority operations.
Germany
Urban air mobility networks in last-mile delivery corridors lack certified transponder infrastructure for beyond-visual-line-of-sight authorization. EASA CS-ETSO compliance thresholds block operational permits for logistics providers until equipment certification completes. Bavaria and North Rhine-Westphalia concentrate unmanned systems engineering talent alongside automotive supplier networks pivoting into avionics.
United Kingdom
The Ministry of Defence issues standalone Mode S and IFF transponder tenders unbundled from complete airframe contracts, establishing direct vendor relationships with component specialists. NATO standardization office specifications mandate encryption capabilities unavailable in commercial variants. Greater London and the Midlands host defense procurement offices driving tactical unmanned systems requirements.
France
Small tactical drone suppliers accelerate product redesigns to meet EASA delegated act requirements before 2026 enforcement phases begin. The country's national aviation regulator enforces harmonized drone regulation frameworks specifying exact transponder performance thresholds. Île-de-France and Provence-Alpes-Côte d'Azur concentrate aerospace manufacturing clusters adapting to dual-use certification demands.
Norway
The Defence Materiel Agency tenders specify Mode S and IFF transponder architectures for tactical unmanned systems operating in Arctic electromagnetic environments. NATO procurement specifications prioritize hybrid GPS-RF architectures providing contested-environment redundancy. Oslo and surrounding regions host defense procurement offices coordinating Nordic unmanned systems integration.
Drone Transponders Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in a market structure bifurcated between certified engineering organizations and module suppliers. FAA-certified design authority concentrates among a limited set of engineering organizations, creating tiered access to regulated commercial markets. Three archetypes dominate: avionics ecosystem extenders from manned aviation, military-grade specialists with encryption capabilities, and retrofit service providers building authorized installation networks. Competitive moves center on dual-use certification convergence and geographic expansion of approved installation channels.
Among avionics ecosystem extenders, Garmin anchors the high-performance segment with integrated architectures spanning manned and unmanned applications. UAvionix occupies a position within the certified engineering organization tier, sustaining design authority over remote ID and ADS-B solutions. Sagetech exemplifies the military-grade specialist archetype, competing through hardened tactical variants purpose-built for small unmanned systems requiring Mode S and IFF compatibility.
| Leading Market Players |
|---|
| Sandia Aerospace |
| Microair Avionics |
| UAvionix |
| Micro Systems |
| Teletronics Technology |
| Sagetech |
| Trig Avionics |
| Garmin |
| Aerobits |
| Others |
Supply Flow & Price Mechanics
China's miniature avionics manufacturing clusters concentrate RF component output for transponder modules, anchoring margin capture downstream with FAA-certified engineering organizations that command design authority premiums. Pricing power fragments between upstream module suppliers facing capacity constraints and downstream integrators capturing certification-linked value.
Pricing Analysis
FAA TSO-C154c and EASA CS-ETSO dictate the pricing tier structure across the Drone Transponders Market, separating certified from uncertified equipment. Three-tier pricing structure across certified-premium, compliance-standard, and uncertified-economy levels reflects testing expenditure recovery and design authority scarcity. Pricing pressure stems from military procurement offices unbundling transponder specifications from airframe contracts, forcing component specialists to absorb certification costs without prime contractor buffers. Commercial logistics operators exhibit highest price sensitivity due to retrofit mandate volume requirements, while defense ministries prioritize encryption capability over unit cost.
Supply Chain Analysis
Miniature RF amplifiers and ceramic substrate materials feed from specialized foundries in China, Taiwan, and Japan, creating geographic concentration for core transponder components. Module assembly draws from Shenzhen and Dongguan electronics corridors, with final integration tethered to FAA-certified engineering facilities in the United States and Germany. Single-source vulnerability runs through Chinese gallium nitride substrate suppliers subject to export control reviews. Distribution runs through authorized installation networks for commercial retrofit compliance, alongside direct military procurement channels for NATO defense ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Drone Transponders Market operates as a regulatory-moat arena where FAA-certified design authority creates switching costs that entrench incumbent positions. Certification backlog and specialized RF engineering talent scarcity compound defensive advantages for established players.
For Market Incumbents: Harden certification portfolio breadth by securing parallel EASA CS-ETSO approvals before 2026 enforcement phases, reducing single-jurisdiction vulnerability. Deepen backward integration into GaN substrate sourcing to mitigate Chinese supply concentration risks. Anchor channel control through authorized installation network expansion in Germany and France, where urban air mobility permit delays create captive retrofit demand. For New Entrants and Emerging Players: Pursue dual-use certification convergence as the most penetrable wedge, targeting products that satisfy both civilian Remote ID and military Mode S encryption specifications. Target Norway and United Kingdom defense procurement offices issuing standalone transponder tenders unbundled from prime contractor relationships. Lead with retrofit service capabilities rather than equipment-only positioning, capturing recurring revenue from legacy fleet compliance mandates. For Investors and Strategic Acquirers: Capital is best deployed toward FAA-certified engineering organizations with sustained design authority over 1090 MHz and 978 MHz architectures, as these capabilities cannot be replicated through capital expenditure alone. Long-term viability favors component specialists with military-grade encryption portfolios that insulate against commercial pricing compression. Watch NATO standardization office procurement specification releases as the signal for defense budget inflection and dual-use product strategy validation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Certification Convergence | Captures procurement budgets from FAA Remote ID mandates and NATO Mode S specifications simultaneously. |
| Authorized Installation Network Expansion | Creates recurring retrofit revenue streams distinct from equipment sales in Germany and France. |
| Backward Integration into RF Substrates | Reduces vulnerability to Chinese gallium nitride supply concentration and export control exposure. |
| Parallel EASA Approval Investment | Accelerates EU market entry before 2026 enforcement deadlines compress procurement windows. |
| Military Encryption Capability Acquisition | Secures premium positioning in United Kingdom and Norwegian defense tenders specifying IFF compatibility. |
Methodological Framework
The analysis maps active, hybrid, and passive transponder architectures alongside ADS-B, Mode S, and GPS-enabled technologies, each validated through procurement officers at NATO defense ministries, commercial drone fleet operators, FAA certification engineers, and avionics distribution channel managers. Primary interview findings triangulate against FAA TSO-C154c filing databases, EASA CS-ETSO approval registries, NATO standardization office procurement specifications, and customs records for miniature avionics component trade flows. Bottom-up equipment shipment estimates reconcile with top-down defense and commercial aviation budget appropriations.
Assumptions hold regulatory enforcement timelines and NATO procurement specifications fixed while varying commercial fleet retrofit penetration rates and military platform integration cycles across the projection horizon. Segmentation models incorporate technology type, application intensity, end-user procurement authority, and geographic regulatory cluster. CAGRs derive from equipment replacement cycle analysis and compliance deadline clustering. Forecast inputs include FAA Remote ID retrofit mandate compliance curves and EASA delegated act implementation phasing.
Sensitivities concentrate around Chinese export control enforcement on RF substrate materials and potential harmonization between FAA Remote ID and military encryption standards. Forecasts reflect assumptions about certification timeline continuity and defense budget stability. Cross-checking against NATO procurement office tender release patterns and EASA approval queue lengths is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Integrated 3D Radar Market